
 Viral Molecular Diagnostics Market | 2026-2036
Viral Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Viral Molecular Diagnostics Market Analytics
The performance gap between laboratory-grade PCR systems and point-of-care isothermal devices is broadening, splitting procurement budgets into two distinct tracks. F. Hoffmann-La Roche Ltd anchors the high-throughput segment with integrated cobas platforms that sustain workflow automation for centralized labs. Abbott competes in near-patient settings with compact molecular instruments that extend diagnostic access beyond traditional laboratory infrastructure. Thermo Fisher Scientific dominates the reagent supply chain with broad menu coverage that positions the company across both tiers.
Viral molecular diagnostics encompass nucleic acid amplification and detection methods used to identify viral pathogens through genetic material analysis, typically operating with sensitivity thresholds below 100 copies per milliliter and turnaround times ranging from 15 minutes to several hours depending on platform complexity. The technology serves primarily to guide clinical treatment decisions, manage infectious disease outbreaks, and ensure blood supply safety through pathogen screening. Reagents capture the recurring revenue stream in this market, while instruments function as margin-locked installed bases that shape long-term customer retention. PCR retains the largest volume share among technologies, though sequencing gains traction in outbreak surveillance applications where variant identification determines public health response.
FDA clearance pathways and CLIA complexity requirements govern market access in the United States, while the EMA's IVDR transition in Europe is elevating clinical evidence standards for molecular assay approvals. The EU AI Act introduces additional scrutiny for software-integrated diagnostic platforms that automate result interpretation. Stakeholders must monitor how regulatory divergence between FDA and EMA evidence requirements reshapes product development priorities and geographic launch sequencing.
Market Dynamics
The viral molecular diagnostics sector is bifurcating around workflow automation intensity, with centralized laboratories demanding integrated sample-to-result systems while decentralized settings prioritize rapid turnaround over throughput. This divergence is fragmenting R&D budgets and reshaping how manufacturers configure platform architectures.
Growth Catalysts
- ECDC Surveillance Mandates:European infectious disease monitoring protocols are expanding PCR testing volumes in Germany, France, and Italy, driving instrument replacement cycles in hospital-affiliated laboratories.
- Isothermal Amplification:Loop-mediated isothermal amplification (LAMP) platforms are penetrating urgent care and pharmacy settings where laboratory infrastructure remains limited, extending diagnostic access beyond traditional sites.
- Medicare Reimbursement Restructuring:United States payment policy shifts favor syndromic respiratory panels over single-target assays, accelerating menu consolidation among hospital purchasers.
Market Restraints
- Reagent Supply Concentration:Polymerase and reverse transcriptase production clusters in specific biomanufacturing hubs, creating vulnerability to batch contamination or export restriction events.
- IVDR Clinical Evidence Burden:Europe's In Vitro Diagnostic Regulation demands expanded performance studies for molecular assay approvals, extending time-to-market and elevating compliance costs for mid-tier manufacturers.
- Sequencing Substitution:Next-generation sequencing platforms are capturing outbreak surveillance applications where variant identification requirements exceed conventional PCR capabilities.
Strategic Opportunities
- Home-Based Collection Infrastructure:Self-sampling protocols for respiratory and sexually transmitted infections are creating demand for stabilized transport media and companion compatibility testing.
- AI-Integrated Result Interpretation:The EU AI Act's risk classification framework for diagnostic software is establishing compliance benchmarks that first-movers can leverage for competitive differentiation.
- Veterinary Diagnostics Extension:Livestock pathogen surveillance programs in Brazil and Australia are adopting human molecular diagnostic architectures, opening cross-species platform utilization.
Industry Challenges
- Bioinformatics Specialist Scarcity:Assay design and validation workflows require computational biology expertise that outpaces academic pipeline output, inflating compensation and extending development timelines.
- CLIA Complexity Navigation:United States laboratory certification tiers create fragmented compliance requirements for platforms deployed across hospital, physician office, and retail clinic settings.
- Legacy LIS Integration:Hospital information system interoperability gaps force custom middleware development for automated result reporting, elevating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viral Molecular Diagnostics Market |
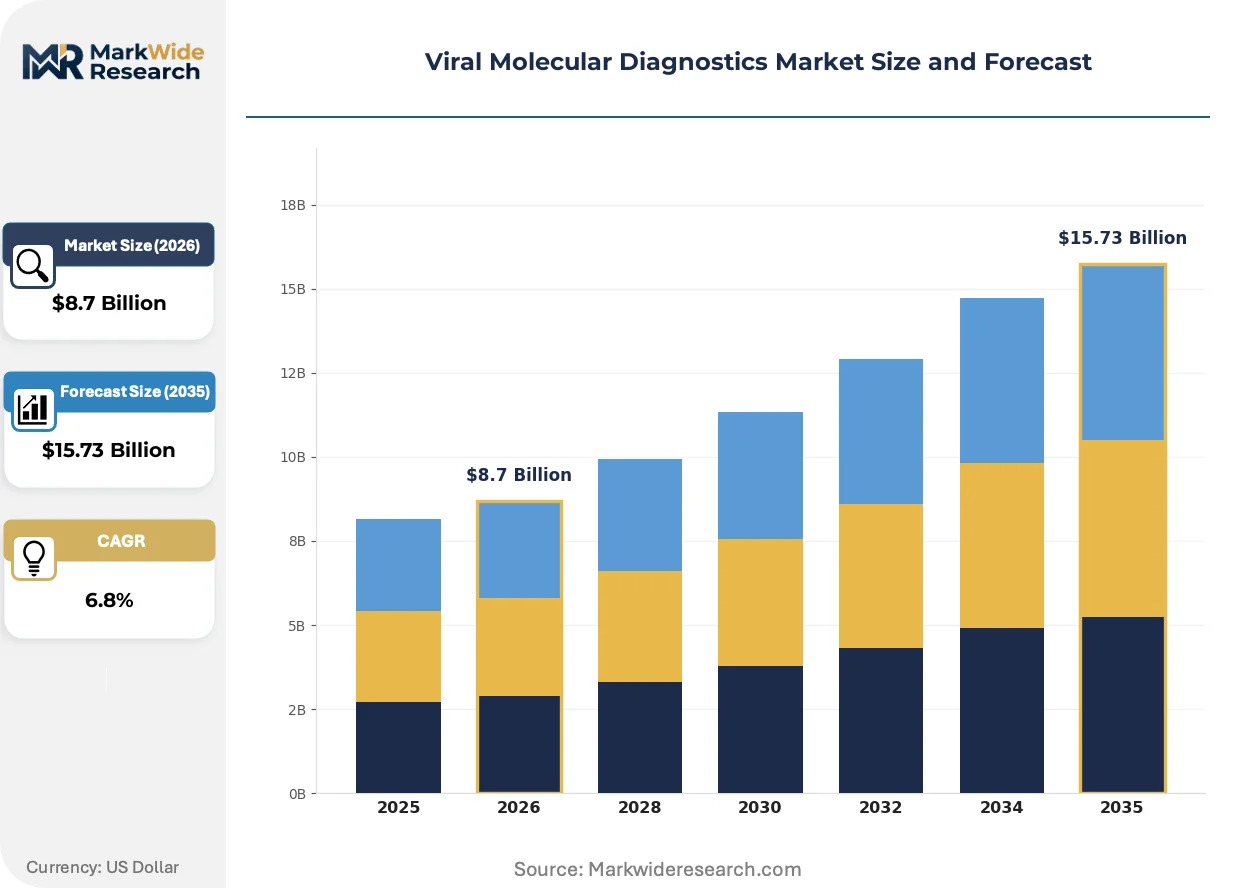
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Accessories Application: Infectious Diseases, Blood Screening, Cancer Diagnostics, Pathogen Detection End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Technology: PCR, Sequencing, Microarrays, Isothermal Amplification |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific, QIAGEN, bioMérieux, Danaher, Siemens Healthineers, Bio-Rad Laboratories, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viral Molecular Diagnostics Market Evolving Landscape
Digital connectivity and assay miniaturization are converging to reshape how molecular diagnostics are deployed, consumed, and reimbursed across care settings. These developments are compressing the traditional boundary between laboratory and near-patient testing.
Multiplexed cartridge-based systems are unifying sample preparation, nucleic acid extraction, amplification, and detection within sealed disposable units. Community health centers and retail clinic chains in the United States are adopting these platforms at accelerating pace. This integration is unifying previously fragmented workflow steps, reducing operator training requirements and error rates while enabling test menu expansion without infrastructure overhaul.
The EU AI Act's risk-based classification framework for software-integrated medical devices is elevating documentation requirements for automated result interpretation algorithms. Manufacturers must now maintain technical files demonstrating validation across diverse patient populations and pathogen variants. High-complexity laboratories in France and Germany are responding by centralizing algorithm governance committees and tightening vendor qualification protocols.
Hospital procurement committees are consolidating molecular diagnostic contracts under single-source agreements that bundle instruments, reagents, and service. This behavior is displacing the historical pattern of best-of-breed instrument selection followed by open reagent sourcing. The shift is most visible in United States integrated delivery networks, where standardization across affiliated laboratories now outweighs point solution optimization in vendor evaluation criteria.
Viral Molecular Diagnostics Market Segmentation
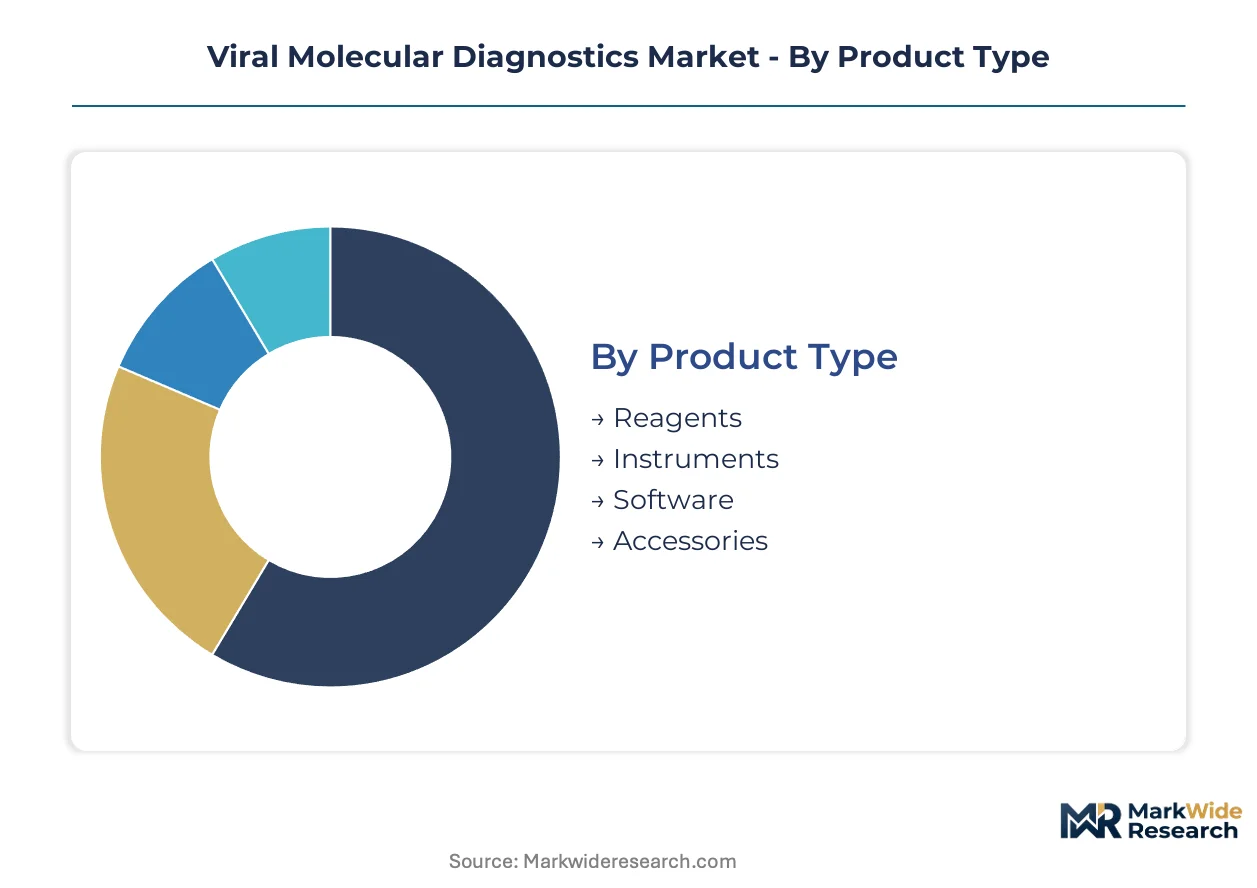
Procurement patterns in viral molecular diagnostics diverge sharply between centralized laboratories seeking automation economies and decentralized sites prioritizing speed over throughput. Understanding these segment boundaries reveals where manufacturers must configure distinct platform architectures and pricing strategies.
Product Type:
Buyers in this category separate into those optimizing recurring revenue streams versus those minimizing capital deployment.
- Reagents:Enzyme master mixes, nucleic acid extraction kits, and probe cocktails constitute the consumable backbone with sensitivity thresholds below 100 copies per milliliter. Demand concentrates in hospital-affiliated diagnostic centers across the United States where Medicare reimbursement shifts favor syndromic panel adoption and drive recurring purchase volumes.
- Instruments:Thermal cyclers, extraction platforms, and integrated sample-to-result systems function as margin-locked installed bases that shape long-term customer retention. Clinical laboratories in Germany are scaling automated PCR workflows to meet rising respiratory virus surveillance mandates under ECDC protocols, accelerating replacement cycles for high-throughput equipment.
- Software:Laboratory information system middleware and automated result interpretation algorithms enable workflow integration.
- Accessories:Cartridges, pipette tips, and transport media complete operational requirements for testing workflows.
Volume sits with Reagents; growth tilts toward Software.
Application:
Clinical utility and regulatory evidence requirements determine where manufacturers concentrate development resources.
- Infectious Diseases:Respiratory, sexually transmitted, and gastrointestinal pathogen detection dominates current test menu utilization. China's NMPA streamlined molecular assay approvals are redirecting procurement toward domestic reagent manufacturers for infectious disease panels.
- Blood Screening:Nucleic acid testing for HIV, HBV, and HCV ensures transfusion safety through pathogen reduction protocols.
- Cancer Diagnostics:Viral oncogene detection and minimal residual disease monitoring extend molecular methods into oncology workflows.
- Pathogen Detection:Environmental and food safety surveillance applications leverage PCR sensitivity for outbreak source tracing.
Infectious Diseases commands installed base volume; Pathogen Detection expands most quickly.
End User:
Certification complexity and reimbursement access create tiered purchasing authority across care settings.
- Hospitals:Integrated delivery networks consolidate contracts under single-source agreements bundling instruments, reagents, and service. Procurement committees now prioritize standardization across affiliated laboratories over point solution optimization.
- Laboratories:Independent and hospital-affiliated sites face divergent CLIA complexity requirements that fragment compliance needs.
- Diagnostic Centers:Community health centers and retail clinic chains adopt cartridge-based platforms at accelerating pace.
- Research Institutions:Academic medical centers drive early adoption of sequencing and multiplexed assay formats.
Hospitals anchor procurement volume; Diagnostic Centers gain share fastest.
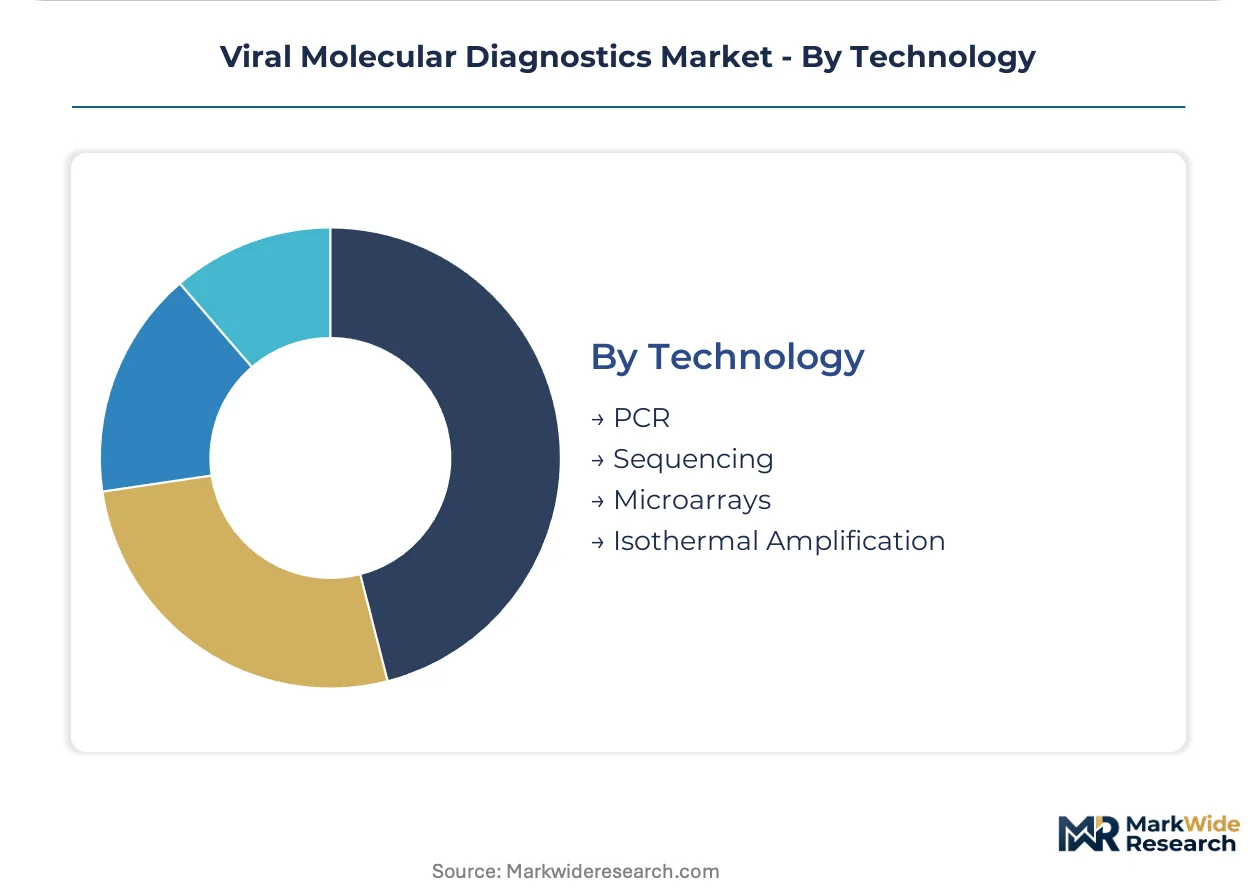
Technology:
Performance specifications and infrastructure requirements split development budgets between established and emerging methods.
- PCR:Real-time and digital PCR retains the largest volume share among amplification technologies with established regulatory pathways. The performance gap between laboratory-grade PCR systems and point-of-care alternatives is broadening, splitting procurement budgets into two distinct tracks.
- Sequencing:Next-generation platforms capture outbreak surveillance applications where variant identification requirements exceed conventional PCR capabilities.
- Microarrays:Multiplexed hybridization formats enable parallel pathogen detection for respiratory and gastrointestinal panels.
- Isothermal Amplification:LAMP platforms penetrate urgent care and pharmacy settings where laboratory infrastructure remains limited.
PCR holds current volume dominance; Sequencing climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's concentration of academic medical centers and biotech incubators anchors North American molecular diagnostics innovation, while Basel and Shanghai house the headquarters of dominant platform manufacturers serving distinct regulatory jurisdictions.
United States
Hospital-affiliated diagnostic centers in the United States concentrate procurement volume for syndromic respiratory panels as Medicare reimbursement restructuring favors multi-target assays over single-pathogen tests. FDA clearance pathways and CLIA complexity requirements govern market access, fragmenting compliance needs across hospital, physician office, and retail clinic deployment settings. The Greater Boston corridor drives early adoption of sequencing and multiplexed assay formats through proximity to academic medical centers.
Germany
Clinical laboratories across Germany are scaling automated PCR workflows to meet rising respiratory virus surveillance mandates under ECDC protocols, accelerating instrument replacement cycles in hospital-affiliated sites. The EMA's IVDR transition elevates clinical evidence standards for molecular assay approvals, extending time-to-market for mid-tier manufacturers. The Rhine-Main biotech cluster around Frankfurt hosts centralized reference laboratories standardizing algorithm governance for AI-integrated diagnostic platforms.
China
China's NMPA streamlined molecular assay approvals are redirecting procurement toward domestic reagent manufacturers for infectious disease panels, particularly in tier-one city hospital systems. National regulators emphasize domestic supply chain security for polymerase and reverse transcriptase production. The Yangtze River Delta biopharmaceutical corridor around Shanghai concentrates manufacturing capacity for both instrument platforms and consumable reagents.
France
High-complexity laboratories in France are centralizing algorithm governance committees and tightening vendor qualification protocols in response to the EU AI Act's risk classification framework for software-integrated diagnostic devices. ANSM oversight of clinical evidence requirements shapes molecular assay validation workflows. The Paris-Saclay research cluster coordinates public health surveillance sequencing networks capturing variant identification requirements that exceed conventional PCR capabilities.
Japan
Japanese diagnostic centers prioritize compact near-patient molecular instruments that extend testing access beyond traditional laboratory infrastructure, particularly in aging rural communities with limited specialized staffing. PMDA regulatory pathways emphasize analytical validation standards comparable to FDA requirements. The Kansai biomedical manufacturing corridor around Osaka houses precision instrument fabricators supplying both domestic hospitals and export markets across Southeast Asia.
Viral Molecular Diagnostics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across reagent supply chain control and installed base lock-in intensity. The market structure consolidates around three tiers: integrated platform manufacturers capturing workflow automation contracts, specialized reagent suppliers dominating consumable recurring revenue, and point-of-care instrument specialists penetrating decentralized settings. Dominant competitive moves include strategic partnerships bundling instruments with long-term reagent supply agreements, and backward integration into enzyme manufacturing to secure supply chain resilience.
Among Swiss-headquartered integrated platform manufacturers, F. Hoffmann-La Roche Ltd exemplifies the high-throughput automation archetype with installed bases that shape long-term customer retention across centralized laboratory networks. Abbott occupies a position within the near-patient testing tier, representing compact molecular instrument specialists that extend diagnostic access beyond traditional infrastructure. Thermo Fisher Scientific anchors the reagent supply chain tier, exemplifying broad menu coverage strategies that position across both centralized and decentralized market segments. These three entities collectively represent the strategic archetypes—integrated platform, point-of-care specialist, and consumable backbone—that define competitive positioning in viral molecular diagnostics.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Thermo Fisher Scientific |
| QIAGEN |
| bioMérieux |
| Danaher |
| Siemens Healthineers |
| Bio-Rad Laboratories |
| Illumina |
| Others |
Value Network & Pricing Analysis
Captive enzyme manufacturing in Germany and the United States anchors supply security for high-throughput PCR manufacturers while simultaneously hardening their pricing power against reagent-only competitors. This backward integration into polymerase and reverse transcriptase production insulates integrated platform vendors from batch contamination events that disrupt mid-tier suppliers, allowing sustained premium positioning in hospital procurement cycles.
Pricing Analysis
Outcome-based pricing anchors instrument-reagent bundles, with United States integrated delivery networks negotiating per-test costs tied to syndromic panel throughput guarantees rather than capital expenditure schedules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared high-complexity systems from CLIA-waived near-patient devices and unregulated research-grade instruments. Cost compression in the economy tier intensifies because Chinese domestic manufacturers exploit NMPA streamlining to undercut import pricing. Diagnostic centers and retail clinic chains exhibit highest price sensitivity, while centralized hospital laboratories prioritize workflow automation over unit economics.
Supply Chain Analysis
Dual-sourcing requirements for thermostable polymerases now mandate qualification of both German and Chinese enzyme suppliers among Tier 1 manufacturers, forcing redundant validation investments. Biomanufacturing capacity clusters in Germany, China, and Switzerland, with the Yangtze River Delta and Rhine-Main corridor hosting captive production for reverse transcriptase and probe chemistries. Raw material dependencies center on recombinant enzyme fermentation, fluorophore conjugation substrates, and medical-grade plastic resin for cartridge molding. Single-source vulnerability concentrates in rare earth-dependent optical detection components sourced through Southeast Asian distributors. Distribution runs through authorized distributor networks serving hospital GPOs and direct procurement contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as IVDR clinical evidence burdens and AI Act compliance costs force mid-tier manufacturers toward strategic exit or acquisition, compressing the vendor base around integrated platform specialists and reagent supply chain anchors.
For Market Incumbents: Deepen backward integration into enzyme manufacturing to neutralize supply chain risk exposure from Chinese export restriction scenarios. Lock hospital-affiliated laboratories into decade-long reagent supply agreements bundled with instrument service contracts, defending against Abbott's near-patient expansion and sequencing substitution threats in outbreak surveillance applications.
For New Entrants and Emerging Players: Enter via veterinary diagnostics extension in Brazil and Australia, where livestock pathogen surveillance programs adopt human molecular architectures with lower regulatory barriers than FDA or EMA pathways. Target urgent care and pharmacy settings with LAMP-based compact instruments, leveraging isothermal amplification's minimal infrastructure requirements to bypass centralized laboratory procurement committees entirely.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated platform manufacturers seeking reagent menu expansion, with strategic value peaking for firms holding AI-integrated result interpretation algorithms pre-validated under EU AI Act technical documentation requirements. Acquisition target archetype: mid-tier reagent suppliers with established IVDR technical files and hospital GPO contract access. Watch NMPA approval velocity for domestic Chinese manufacturers as inflection indicator for pricing pressure intensity in infectious disease panels.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enzyme Manufacturing | Captive polymerase production insulates against Chinese export restrictions and secures reagent margin control. |
| AI-Integrated Result Interpretation Development | EU AI Act compliance establishes competitive moat through elevated technical documentation barriers. |
| Hospital System Partnership Consolidation | Single-source bundling agreements displace best-of-breed procurement patterns in United States IDNs. |
| Veterinary Diagnostics Platform Extension | Cross-species utilization opens revenue streams in Brazilian and Australian livestock surveillance programs. |
| Home-Based Collection Infrastructure Buildout | Stabilized transport media demand aligns with self-sampling protocol expansion for respiratory and STI testing. |
Research Methodology
Independent corroboration across hospital procurement managers, GPO contracts specialists, biomedical engineers, and regulatory affairs leads underwrites the qualitative findings on CLIA complexity navigation and IVDR transition impacts. Secondary validation draws from FDA 510(k) clearances, EMA IVDR technical documentation summaries, CMS Medicare reimbursement schedules, and hospital supply chain databases. Bottom-up instrument installation counts and top-down reagent revenue estimates were triangulated to anchor market sizing.
Comparable-period anchoring to pre-pandemic baseline volumes established the forecast window's lower bound, with syndromic panel adoption curves and sequencing substitution rates defining upper trajectory limits. Segmentation modeling spanned product type, application, end user, technology, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from instrument replacement cycle analysis, reagent consumption per installed base unit, and Medicare reimbursement elasticity estimates for multi-target versus single-pathogen assays.
Forecast precision tightens around the base case; tail outcomes carry wider variance under IVDR implementation delays or novel respiratory pathogen emergence scenarios. Deviation in Chinese NMPA domestic preference enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Middle East and Africa Lung Cancer Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Epigenetics Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Canada Latent Tuberculosis Infection Detection Market
Diagnostics
RT-PCR Kits Market
Diagnostics
Rapid Oral Fluid Screening Device Market
Diagnostics
Cancer Tissue Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Global Alzheimers Disease Diagnostic Market
Diagnostics
Immunoassay Interference Blocker Market
Diagnostics
In Vitro Diagnostics Test Kit Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Blood Culture Media Market