
 North America and Europe Companion Animal Diagnostics Imaging Market | 2026-2036
North America and Europe Companion Animal Diagnostics Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Companion Animal Diagnostics Imaging Market Intelligence
EU MDR is broadening the cost-of-entry calculus for imaging device manufacturers serving European veterinary channels. IDEXX Laboratories, Inc. leverages its installed base of digital radiography platforms to sustain recurring revenue from software subscriptions and consumables. Siemens Healthineers anchors its position through R&D intensity in advanced MRI sequences tailored for small-animal neurology. Canon Medical Systems Corporation differentiates via manufacturing scale that supports rapid fulfillment across North American distributor networks.
Companion animal diagnostics imaging encompasses the use of ionizing radiation, magnetic resonance, computed tomography, and acoustic energy to generate anatomical and functional visual data for veterinary clinical decision-making, with spatial resolution requirements typically ranging from sub-millimeter for feline cardiac studies to several millimeters for large-breed canine skeletal surveys. Ultrasound dominates procedure volume in veterinary clinics due to lower capital barriers and minimal facility shielding requirements, while MRI captures disproportionate margin pools in tertiary referral centers handling complex neurology and oncology cases. Digital imaging displaces conventional film-based radiography across both regions as cloud-based PACS integration becomes standard in multi-site veterinary practice groups.
FDA Center for Veterinary Medicine oversight shapes device quality expectations in the United States, while EU MDR and CE marking requirements govern market access across European member states. The EU F-Gas Regulation constrains availability of certain MRI cooling agents, redirecting procurement toward helium-recovery systems or dry-magnet alternatives. Stakeholders must monitor how evolving veterinary telemedicine licensure rules affect reimbursement for remotely interpreted imaging studies.
Market Dynamics
Cloud-based PACS integration across multi-site veterinary practice groups is compressing hardware refresh cycles and elevating software-as-a-service revenue models in diagnostic imaging workflows.
Growth Catalysts
- EU MDR compliance timelines:Veterinary device manufacturers are accelerating quality management system upgrades to meet notified body certification requirements, expanding addressable market for compliant suppliers.
- Cardiology service line expansion:United States veterinary clinics are adding echocardiography suites to capture referral revenue from age-related valvular disease in canine patients.
- Helium recovery systems:MRI magnet cooling infrastructure investments are accelerating across Germany's specialty hospital networks as EU F-Gas Regulation constrains conventional refrigerant supply.
Market Restraints
- Capital intensity of MRI installation:Shielding requirements and siting constraints limit deployment to tertiary referral centers, capping addressable volume in community practice settings.
- Input cost volatility:Gadolinium-based contrast agent pricing fluctuations squeeze margin pools in neurology imaging protocols.
- Substitution pressure from ultrasound:Point-of-care acoustic imaging advances reduce reliance on radiography for thoracic and abdominal screening in feline patients.
Strategic Opportunities
- Telemedicine licensure evolution:Remote imaging interpretation reimbursement frameworks are expanding across United States state veterinary boards, enabling teleradiology platform scaling.
- Oncology application depth:Staging protocols for hemangiosarcoma and lymphoma are driving CT and PET-CT adoption in academic veterinary medical centers.
- Artificial intelligence convergence:Machine learning algorithms trained on breed-specific anatomical variants are integrating into radiography and MRI workstations to accelerate diagnostic throughput.
Industry Challenges
- Veterinary radiologist workforce scarcity:Board-certified specialist supply constraints create interpretation bottlenecks, extending report turnaround times in emergency settings.
- Legacy equipment interoperability:DICOM conformance variations between vendor platforms complicate image archive consolidation in acquired practice networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Companion Animal Diagnostics Imaging Market |
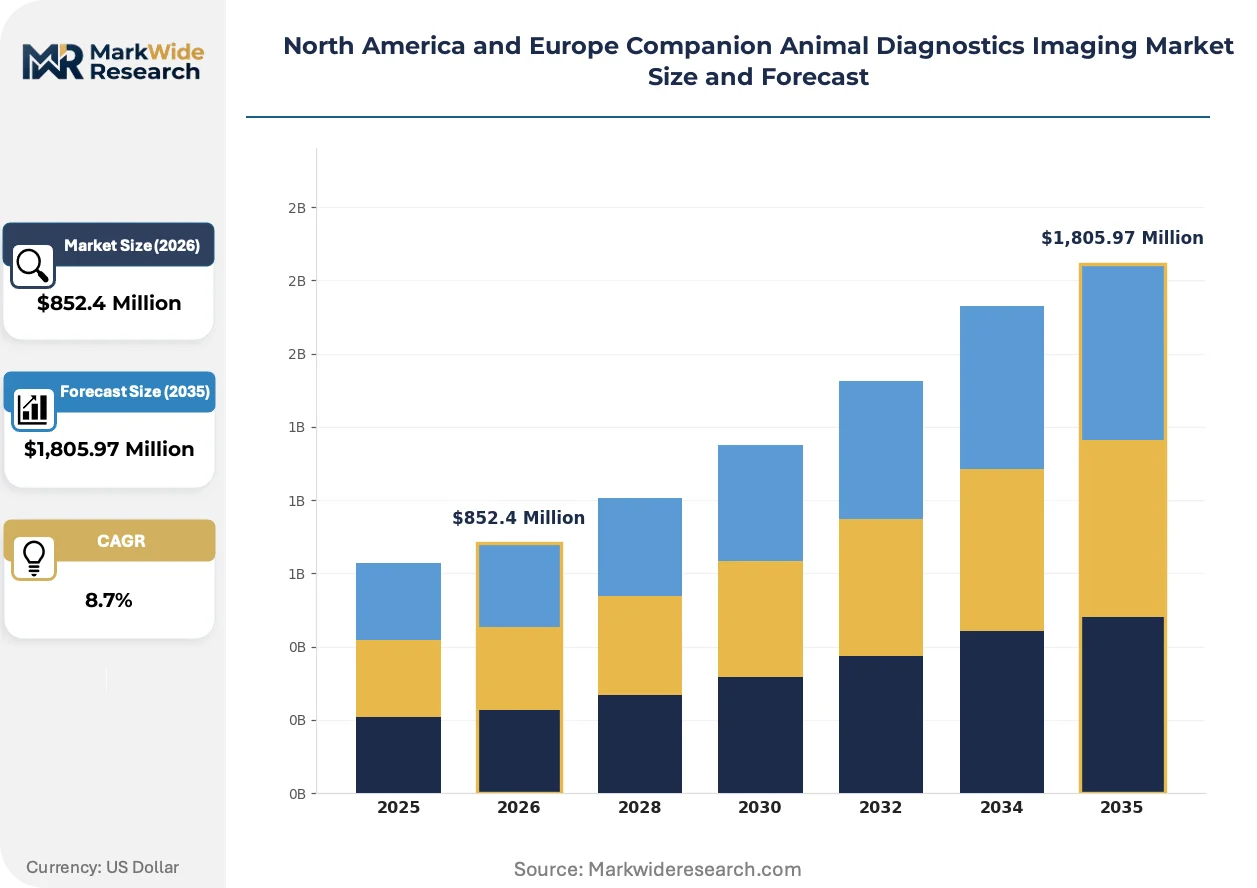
| Market Size in 2026 | $852.4 Million |
| Market Size in 2035 | $1,805.97 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-Ray, Ultrasound, MRI, CT Scan End User: Veterinary Clinics, Animal Hospitals, Research Laboratories, Pet Specialty Clinics Technology: Digital Imaging, Conventional Imaging, Telemedicine Solutions, Portable Imaging Devices Application: Internal Medicine, Oncology, Cardiology, Neurology |
| Companies Covered | IDEXX Laboratories, Inc., ESAOTE SPA, Hallmarq Veterinary Imaging, Canon Medical Systems Corporation, Siemens Healthineers, FUJIFILM Holdings America Corporation, Carestream Health, Agfa-Gevaert Group, Heska Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Companion Animal Diagnostics Imaging Market Strategic Shifts & Innovations
Artificial intelligence is penetrating image acquisition and interpretation workflows, while regulatory frameworks on device quality and environmental compliance reshape capital procurement priorities across veterinary channels.
Portable ultrasound systems with linear and micro-convex probes are integrating into ambulatory veterinary services, enabling on-farm equine and large-animal imaging without transport stress. Mobile practitioners across France and the United Kingdom are adopting battery-powered units for reproductive and musculoskeletal assessments. This mobility is compressing the addressable market for fixed-installation radiography in rural practice settings.
EU MDR Article 10 technical documentation requirements are elevating conformity assessment burdens for imaging device manufacturers seeking CE marking renewal. Notified body backlogs are extending time-to-market for software-upgradable radiography platforms. German and Dutch veterinary distributors are prioritizing inventory positions with MDR-certified suppliers to mitigate supply continuity risk.
Subscription-based software licensing is displacing perpetual purchase models for image viewing and archival systems. Multi-site practice groups in the United States and United Kingdom are unbundling hardware procurement from PACS and AI tool access, converting capital expenditure to operational expenditure. This financing flexibility is accelerating digital platform adoption among mid-size veterinary hospital chains.
North America and Europe Companion Animal Diagnostics Imaging Market Segmentation
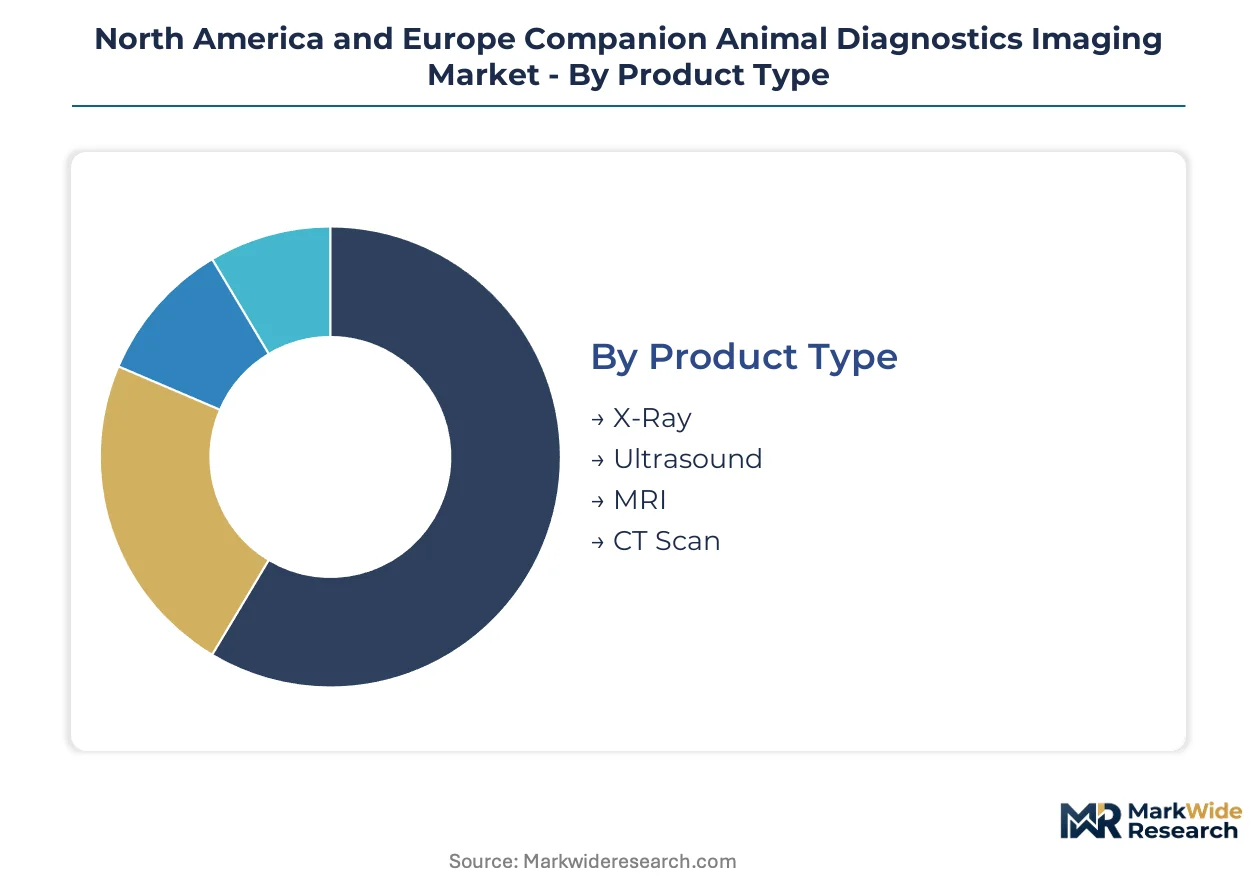
Equipment refresh cycles in veterinary diagnostics imaging vary sharply by modality capital intensity and software obsolescence curves. Segment-level procurement patterns reveal where multi-site practice groups concentrate upgrade spending versus where legacy systems persist.
Product Type:
Replacement timelines diverge dramatically across imaging modalities, with software-integrated platforms commanding accelerated refresh schedules compared to hardware-dominant systems.
- Ultrasound:Battery-powered units with micro-convex and linear probes now deliver cardiac and abdominal imaging without facility shielding. Demand clusters in ambulatory services across France and the United Kingdom where mobile practitioners avoid patient transport stress.
- X-Ray:Digital radiography platforms displace conventional film systems as cloud-based PACS integration becomes standard in United States and German multi-site practice groups. Detector panel upgrades and software subscription renewals sustain recurring revenue streams for installed base vendors.
- MRI:Helium-dependent magnet cooling faces supply constraints under EU F-Gas Regulation, redirecting German specialty hospital procurement toward recovery systems or dry-magnet alternatives.
- CT Scan:Oncology staging protocols for hemangiosarcoma drive adoption in academic veterinary medical centers with capital budgets for tertiary referral infrastructure.
Ultrasound sits at the top of the volume ranking, with MRI climbing the fastest as neurology case referrals concentrate in specialty networks.
End User:
Procurement authority and financing flexibility separate institutional buyers from independent operators across the North America and Europe footprint.
- Veterinary Clinics:Independent and small-group practices prioritize ultrasound and digital radiography with minimal facility modifications. United States state veterinary board telemedicine licensure evolution is expanding remote interpretation reimbursement, enabling teleradiology partnerships without on-site specialist staffing.
- Animal Hospitals:Tertiary referral centers in Germany and the United Kingdom anchor MRI and CT installation bases, absorbing complex neurology and oncology cases from community practices. Capital intensity and shielding requirements limit this segment to urban academic and specialty networks.
- Research Laboratories:Preclinical imaging for pharmaceutical and device trials demands high-field MRI and micro-CT specifications distinct from clinical veterinary applications.
- Pet Specialty Clinics:Cardiology-focused operators in the United States are adding echocardiography suites to capture age-related canine valvular disease revenue, driving probe and platform procurement.
Veterinary clinics dominate procedure volume, with animal hospitals expanding most quickly as referral consolidation accelerates.
Technology:
Software-as-a-service conversion is restructuring vendor revenue models and customer capital allocation across imaging technology categories.
- Digital Imaging:DICOM-compliant radiography and PACS platforms enable multi-site archive consolidation, though legacy equipment interoperability variations complicate unified workflows in acquired practice networks.
- Telemedicine Solutions:Remote image interpretation platforms scale where state-level licensure frameworks permit cross-border radiologist consultation, addressing board-certified specialist scarcity in emergency settings.
- Portable Imaging Devices:Battery-powered ultrasound units penetrate ambulatory large-animal services in rural France and the United Kingdom, compressing demand for fixed-installation radiography in exurban practice settings.
- Conventional Imaging:Film-based radiography persists only in cost-constrained single-site operations without digital upgrade capital, primarily in peripheral European markets.
Digital imaging commands the largest installed base, with telemedicine solutions gaining share fastest as reimbursement frameworks mature.
Application:
Clinical indication complexity determines modality mix and price realization within each application segment.
- Oncology:Staging for lymphoma and hemangiosarcoma requires CT and PET-CT protocols at academic veterinary medical centers, with gadolinium-based contrast agent pricing volatility squeezing margin pools in neurology imaging workflows.
- Cardiology:Echocardiography suite expansion in United States veterinary clinics targets age-related valvular disease in canine patients, with breed-specific anatomical reference databases integrating into measurement software.
- Neurology:Advanced MRI sequences for small-animal brain and spinal imaging concentrate in German specialty hospital networks with helium-recovery infrastructure.
- Internal Medicine:Thoracic and abdominal screening in feline patients faces substitution pressure from point-of-care ultrasound advances, reducing radiography dependence for routine assessments.
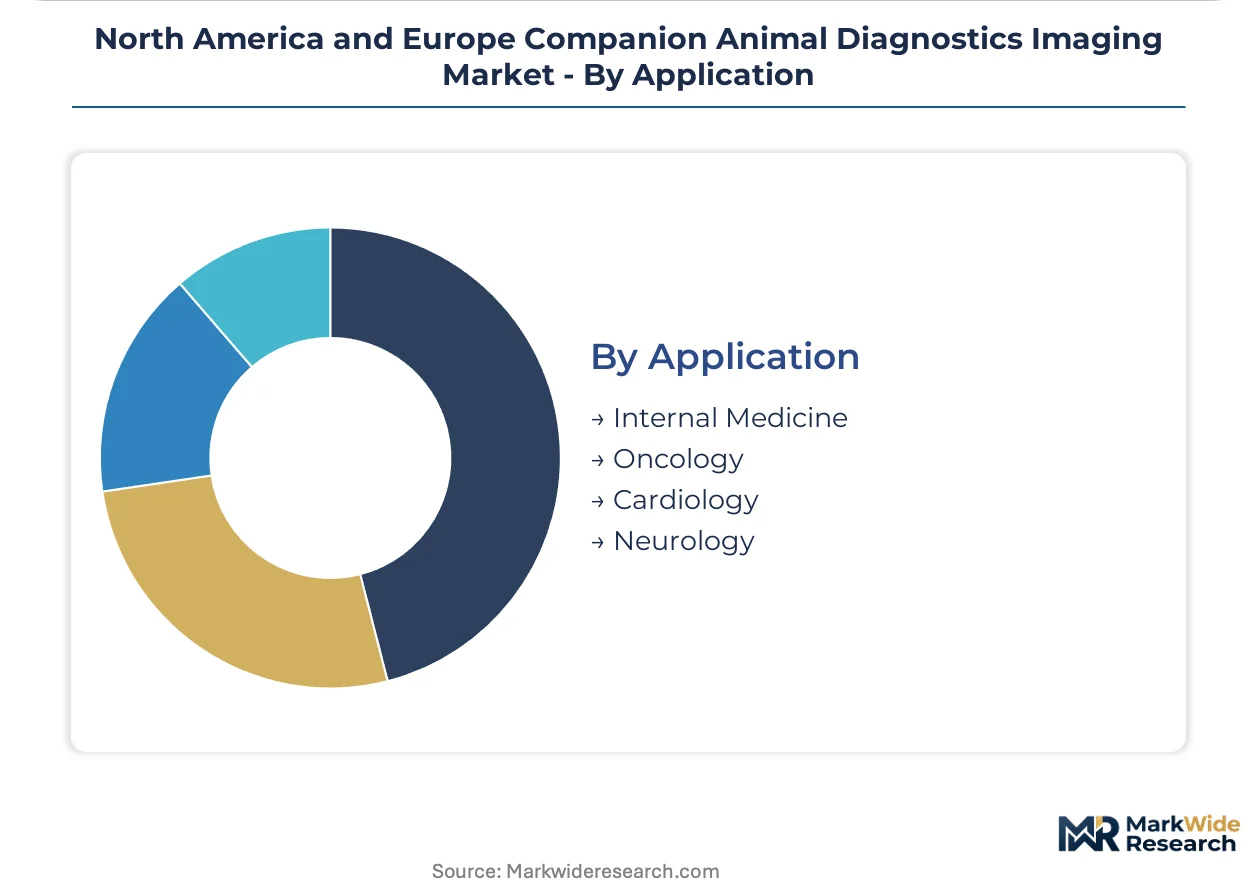
Internal medicine generates the highest procedure volume, with oncology expanding most steeply as pet owner willingness-to-pay for cancer staging rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Veterinary radiologist concentrations in Boston, London, and Munich anchor regional imaging interpretation capacity. Specialist scarcity in emergency settings drives teleradiology platform deployment across state and national borders.
United States
Cardiology service line expansion in veterinary clinics drives echocardiography suite installations for canine valvular disease. FDA Center for Veterinary Medicine guidance elevates diagnostic device quality compliance investments. Greater Boston and Pacific Northwest clusters concentrate board-certified specialist training programs.
Germany
Specialty veterinary hospital networks absorb complex neurology referrals requiring advanced MRI sequences. EU F-Gas Regulation constrains conventional MRI cooling agent supply, redirecting procurement toward helium-recovery infrastructure. Bavaria's academic veterinary medical centers anchor oncology staging protocol development.
United Kingdom
Mobile practitioners adopt battery-powered ultrasound for ambulatory large-animal services. EU MDR notified body backlogs extend CE marking timelines for software-upgradable radiography platforms. London and Southeast England concentrate multi-site practice group PACS consolidation activity.
France
Rural veterinary networks compress fixed-installation radiography demand through portable imaging adoption. ANSM oversight shapes device quality expectations for veterinary channel suppliers. Auvergne-Rhône-Alpes region hosts reproductive imaging specialists serving equine breeding operations.
Canada
Telemedicine licensure evolution enables cross-province radiologist consultation for emergency imaging interpretation. Health Canada and PMRA govern veterinary diagnostic device market access requirements. Ontario and Quebec veterinary teaching hospitals anchor CT and PET-CT oncology staging capacity.
North America and Europe Companion Animal Diagnostics Imaging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across imaging modality segments. The vendor base stratifies into three tiers: diversified medical technology conglomerates with veterinary divisions, dedicated veterinary imaging specialists, and regional distributor-assemblers. Consolidation pressure concentrates in digital radiography and PACS software segments where recurring revenue models reward installed base scale. Strategic moves center on M&A for specialist talent acquisition and cloud-based platform partnerships for multi-site practice group penetration.
Within the diversified conglomerate tier, Siemens Healthineers and Canon Medical Systems Corporation represent scale-driven positions anchored through manufacturing breadth and distributor network coverage. IDEXX Laboratories, Inc. exemplifies the installed-base monetization archetype, leveraging digital radiography platform penetration to sustain recurring software and consumable revenue streams. ESAOTE SPA and Hallmarq Veterinary Imaging occupy specialist-focused positions emphasizing veterinary-specific hardware configurations and application-tailored imaging protocols.
| Leading Market Players |
|---|
| IDEXX Laboratories, Inc. |
| ESAOTE SPA |
| Hallmarq Veterinary Imaging |
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| FUJIFILM Holdings America Corporation |
| Carestream Health |
| Agfa-Gevaert Group |
| Heska Corporation |
| Others |
Cost & Logistics Intelligence
Multi-site veterinary practice groups in the United States and Germany dominate procurement volume, anchoring a pricing model that unbundles hardware from software subscriptions and consumable replenishment cycles.
Pricing Analysis
Bundled service contracts for MRI and CT installations compete against unbundled per-procedure pricing for ultrasound and digital radiography platforms. Three-tier pricing structure across premium, standard, and economy levels separates helium-recovery MRI systems from conventional magnet cooling configurations from refurbished legacy units. Pricing pressure stems from EU MDR compliance cost pass-through and gadolinium-based contrast agent input volatility. Independent veterinary clinics exhibit acute price sensitivity for capital equipment, while tertiary referral centers absorb premium-tier pricing for advanced neurology sequencing capabilities.
Supply Chain Analysis
Single-source vulnerability sits with helium supply chains concentrated in Qatar, the United States, and Algeria, constraining MRI magnet cooling infrastructure availability under EU F-Gas Regulation enforcement. Detector panel manufacturing draws from semiconductor fabrication in Taiwan and South Korea, while rare earth magnet production rests on Chinese processing capacity. Tariff exposure on Chinese-sourced permanent magnets elevates landed costs for portable ultrasound motor assemblies. Distribution runs through authorized veterinary distributor networks in Germany, the United Kingdom, and the United States, with direct-to-practice fulfillment accelerating for software subscription renewals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in companion animal diagnostics imaging rest on SaaS conversion of PACS and AI tool access, converting capital expenditure to recurring operational outflows while reducing customer churn.
For Market Incumbents: Cement installed base retention through detector panel upgrade programs and cloud archive migration services that deepen switching costs for multi-site practice groups. Counter substitution pressure from point-of-care ultrasound by embedding AI measurement tools into radiography workstations. Prioritize MDR certification maintenance to preserve CE marking access across German and Dutch distribution channels.
For New Entrants and Emerging Players: The mid-market price-point gap between premium-tier MRI configurations and economy-tier refurbished radiography platforms offers white-space penetration for teleradiology platform providers and portable ultrasound specialists. Target ambulatory large-animal services in rural France and the United Kingdom with battery-powered micro-convex probe units. Pursue partnership routes with veterinary telemedicine licensure evolution to bypass capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates with veterinary divisions are the most active acquirer in this space, seeking AI algorithm developers and breed-specific anatomical database specialists. Long-term viability favors platforms with recurring revenue density above hardware transactional dependence. Monitor EU notified body backlog resolution as inflection signal for software-upgradable radiography platform time-to-market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Helium Recovery Infrastructure Deployment | EU F-Gas Regulation compliance secures MRI magnet cooling continuity for German specialty hospitals. |
| AI Algorithm Integration into PACS Workstations | Breed-specific anatomical variant training accelerates diagnostic throughput for board-certified specialist scarcity. |
| Cloud-Based Archive Consolidation | Multi-site practice groups in the United States and United Kingdom convert capital expenditure to operational expenditure. |
| Telemedicine Licensure Platform Scaling | Cross-border radiologist consultation addresses interpretation bottlenecks in emergency veterinary settings. |
| MDR Certification Pathway Acceleration | Notified body alignment preserves CE marking access for software-upgradable radiography platforms. |
Research Approach
Coverage spans North America and Europe, with primary inputs from each region's veterinary practice groups, imaging device manufacturers, and regulatory affairs specialists. The analytical approach combines interviews with veterinary radiologists, biomedical engineers at academic medical centers, GPO contracts managers, and distributor procurement leads with secondary validation from FDA Center for Veterinary Medicine guidance documents, EU MDR technical documentation requirements, hospital procurement databases, and veterinary telemedicine licensure rule filings. Bottom-up equipment installation tracking and top-down addressable market sizing triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include imaging modality, end-user facility type, technology deployment model, and clinical application complexity. CAGRs derive from logistic diffusion curves fitted to historical modality adoption patterns, adjusted for EU F-Gas Regulation supply constraints and SaaS conversion acceleration in multi-site practice groups. Forecast inputs incorporate veterinary radiologist workforce pipeline data and cloud PACS penetration benchmarks.
The model assumes a particular technology adoption path; alternative pathways for dry-magnet MRI or AI-native image acquisition would alter the outlook. Forecasts reflect assumptions regarding telemedicine licensure evolution pace and helium supply chain stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
Population Screening Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Semen Analysis Market
Diagnostics
Septicemia Diagnostic Testing Market
Diagnostics
Pancreatic Cyst Diagnostics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Blood Urea Nitrogen Diagnostics Market
Diagnostics
FISH Probe Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Professional Diagnostics Market
Diagnostics
US Tissue Diagnostics Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
Global Blood Transfusion Diagnostics Market
Diagnostics
Cervical Cancer Diagnostic Tests Market