
 Singleplex Immunoassay Market | 2026-2036
Singleplex Immunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Singleplex Immunoassay Market Outlook
High-sensitivity specification tiers is bifurcating the competitive landscape into premium instrument-reagent systems and cost-efficient open-platform consumables. Siemens Healthineers leverages integrated analyzer-chemiluminescent workflows to dominate tertiary hospital networks in Western Europe. Abbott Laboratories sustains R&D intensity across fluorescent detection architectures, while Roche Diagnostics anchors its position through captive reagent supply agreements with centralized laboratories.
Singleplex immunoassay denotes a quantitative analytical method detecting one analyte per reaction vessel, typically employing antibody-antigen binding with signal amplification via enzymatic or fluorescent reporters, achieving detection thresholds in the picogram-per-milliliter range for clinical biomarkers. The technique serves diagnostic laboratories requiring definitive positive-negative determination for individual pathogens, hormones, or tumor markers without multiplex interference. ELISA platforms occupy mature volume pools in routine serology, whereas chemiluminescent technology leads growth trajectories due to superior dynamic range and automation compatibility. Clinical diagnostics generates the largest revenue base among application segments, though drug development workflows in contract research organizations are expanding fastest as biologics pipelines proliferate.
FDA premarket notification pathways and the EU In Vitro Diagnostic Regulation impose escalating clinical validation burdens on novel assay introductions, compressing timelines for smaller manufacturers while advantaging established submitters with dedicated regulatory affairs infrastructure. ISO 13485 quality management certification has become a non-negotiable market access credential for reagent suppliers seeking OEM partnerships with instrument manufacturers. Stakeholders must monitor evolving IVD performance standards and calibrate portfolio investments toward automated platforms that satisfy both stringent regulatory dossier requirements and laboratory consolidation-driven procurement criteria.
Market Dynamics
Hospital consolidation across the United States, Germany, and Japan is compressing procurement cycles and favoring centralized high-throughput chemiluminescent platforms over distributed ELISA workstations.
Growth Catalysts
- EU In Vitro Diagnostic Regulation:Mandatory performance validation dossiers are accelerating replacement of legacy assays with certified automated systems in European clinical laboratories.
- Infectious disease testing volumes:Residual pandemic-era infrastructure investments continue converting serology workflows to chemiluminescent architectures in tertiary hospital networks.
- Biologics pipeline expansion:Contract research organizations in North America and Europe are scaling singleplex immunoassay capacity for pharmacokinetic studies.
Market Restraints
- Reagent supply concentration:Captive reagent-instrument bundling by dominant platform vendors locks laboratories into proprietary consumable ecosystems with limited price negotiation leverage.
- FDA premarket notification burden:Novel assay developers face compressed submission timelines and escalating clinical validation costs that disadvantage smaller manufacturers without dedicated regulatory affairs infrastructure.
- Multiplex assay substitution:Panel-based testing platforms are capturing volume in oncology and autoimmune screening where simultaneous multi-analyte detection reduces per-test cost.
Strategic Opportunities
- Japanese point-of-care expansion:Community clinic networks in Japan are adopting compact chemiluminescent analyzers for decentralized infectious disease screening outside metropolitan hospital systems.
- ISO 13485 certification arbitrage:Reagent suppliers achieving quality management certification are capturing OEM partnerships with open-platform instrument manufacturers seeking validated consumable sources.
- Drug development workflow integration:Biopharma sponsors are embedding singleplex immunoassay modules into adaptive trial designs for real-time biomarker monitoring.
Industry Challenges
- Regulatory dossier complexity:Smaller assay developers struggle to resource parallel FDA and EU MDR submission pathways simultaneously.
- Legacy system integration friction:Hospital information system interoperability gaps complicate data exchange between new chemiluminescent platforms and existing laboratory middleware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singleplex Immunoassay Market |
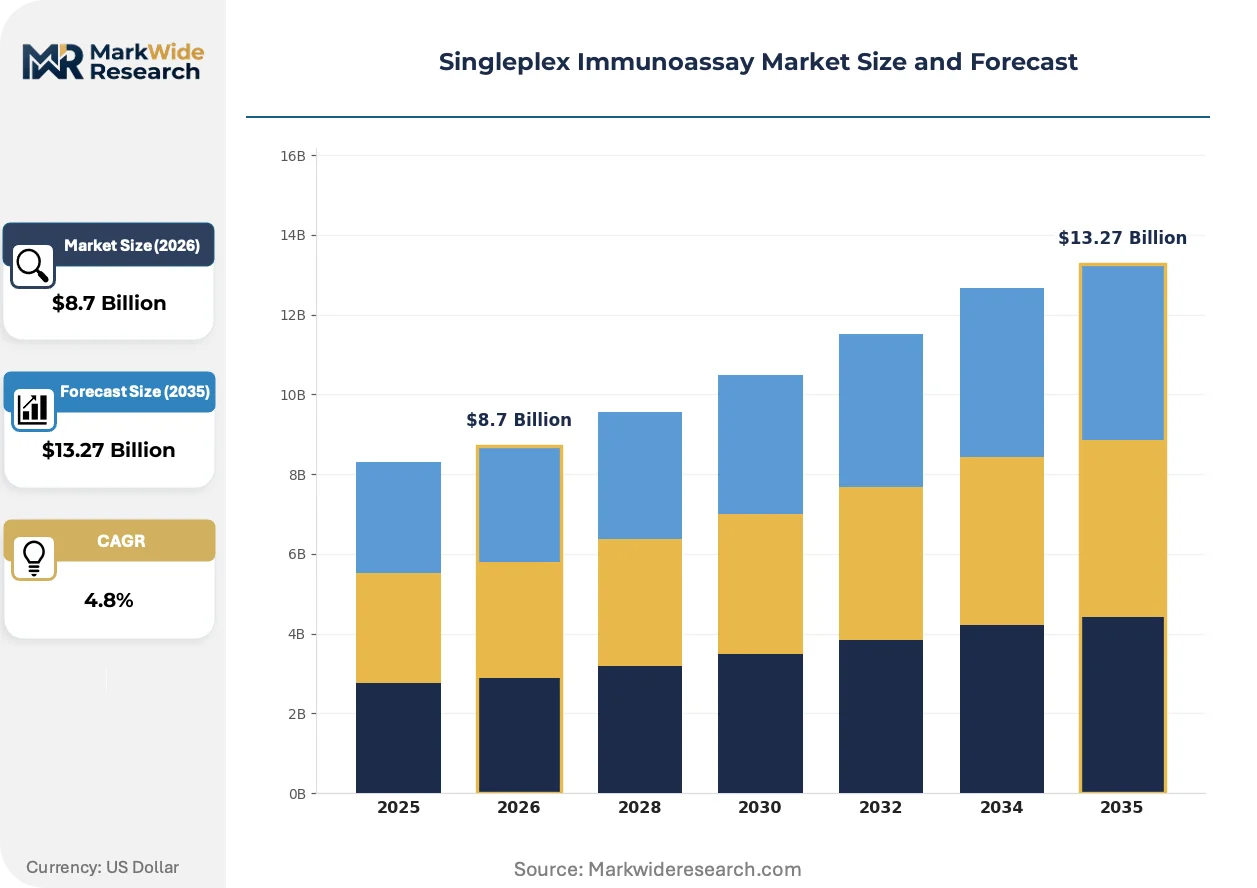
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Western Blot, Lateral Flow Assay, Radioimmunoassay End User: Clinical Laboratories, Research Institutions, Hospitals, Diagnostic Centers Application: Clinical Diagnostics, Drug Development, Environmental Testing, Food Safety Technology: Fluorescent, Chemiluminescent, Colorimetric, Electrochemical |
| Companies Covered | Siemens Healthineers, Ortho Clinical Diagnostics, Abbott Laboratories, Quidel Corporation, PerkinElmer, Roche Diagnostics, Bio-Rad Laboratories, Danaher Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singleplex Immunoassay Market Strategic Shifts
Automation architectures are restructuring competitive advantage around throughput density and walk-away processing capability, displacing manual ELISA batch workflows in high-volume laboratories.
Digital microfluidic sample handling is decomposing traditional liquid-handling robotics into cartridge-based disposable fluidic circuits. Mid-sized clinical laboratories in Germany and Japan are adopting these systems to reduce capital footprint and maintenance overhead. The technology is decomposing the historical instrument-revenue model into recurring consumable streams with lower upfront procurement barriers.
The EU In Vitro Diagnostic Regulation's Class C device classification for infectious disease assays is forcing manufacturers to generate expanded clinical performance data. This regulatory burden is compressing the viable manufacturer base toward established submitters with dedicated clinical affairs teams. Western European reference laboratories are responding by consolidating procurement around vendors with proven MDR technical documentation.
Consolidated buying committees in United States health systems are unbundling service contracts from instrument procurement, separating warranty terms from reagent supply agreements. Independent service organizations are capturing maintenance revenue previously held by original equipment manufacturers. This pattern is most visible in multi-hospital networks across Texas and California where centralized laboratory administration controls capital allocation.
Singleplex Immunoassay Market Segmentation
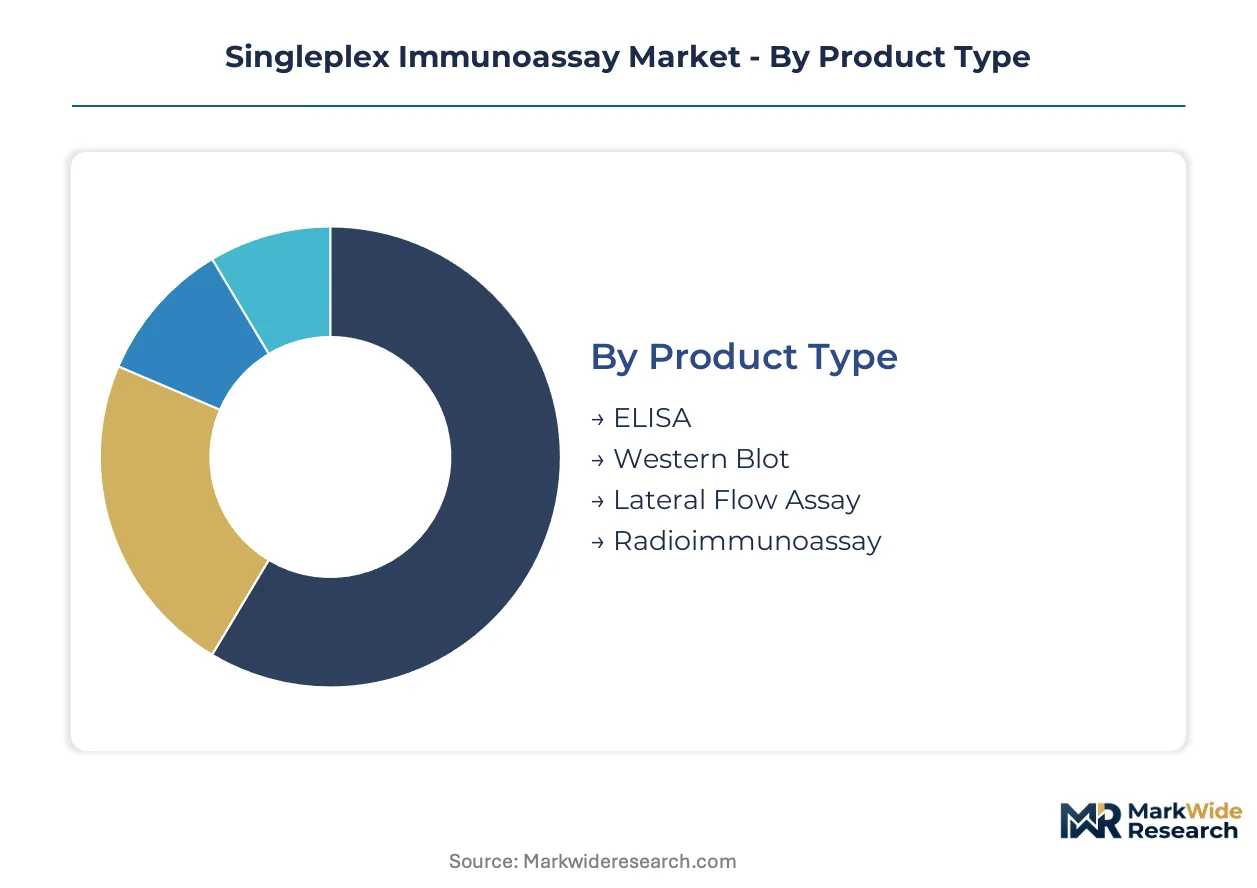
Technology-platform choices in singleplex immunoassay determine regulatory pathway complexity and capital deployment requirements. Laboratories segment procurement across detection modalities based on throughput needs and biomarker sensitivity specifications.
Product Type:
FDA premarket notification requirements and EU MDR technical documentation burdens vary sharply across detection platforms, with enzymatic systems facing lighter validation loads than radioisotope-based methods.
- ELISA:Enzyme-linked immunosorbent assay platforms employ horseradish peroxidase or alkaline phosphatase signal amplification with optical density readout. Clinical laboratories in the United States and Germany concentrate procurement here for routine serology panels where picogram-per-milliliter sensitivity suffices and batch processing economics dominate.
- Chemiluminescent Immunoassay:Acridinium ester and alkaline phosphatase-dioxetane architectures achieve superior dynamic range with automated walk-away processing. Tertiary hospital networks in Japan and Western Europe are converting volume to these platforms as laboratory consolidation compresses staffing headcount.
- Western Blot:Semi-quantitative protein separation with antibody detection serves confirmatory testing workflows in research institutions.
- Lateral Flow Assay:Capillary-driven immunochromatographic strips enable rapid point-of-care screening outside centralized laboratory infrastructure.
- Radioimmunoassay:Isotope-labeled competitive binding methods persist in specialized endocrinology reference laboratories despite regulatory handling constraints.
ELISA handles the majority of throughput; chemiluminescent platforms are expanding most quickly on share.
End User:
Procurement authority concentrates differently across customer types, with consolidated health systems extracting volume discounts unavailable to fragmented diagnostic networks.
- Clinical Laboratories:High-throughput centralized facilities process thousands of samples daily with automated chemiluminescent analyzers. United States hospital networks in Texas and California drive demand for integrated instrument-reagent contracts with dedicated field service support.
- Research Institutions:Academic medical centers and contract research organizations require flexible open-platform configurations for biomarker discovery. North American and European biopharma sponsors are embedding singleplex modules into adaptive trial designs.
- Hospitals:Inpatient and emergency departments prioritize rapid turnaround over sensitivity for critical care decision-making.
- Diagnostic Centers:Independent reference laboratories compete on specialized test menus and courier logistics rather than capital equipment scale.
Clinical laboratories command the largest equipment budgets; research institutions are climbing the fastest on consumable pull-through.
Application:
Reimbursement coding and payer coverage determinations segment demand across clinical versus non-clinical use cases, with diagnostic testing enjoying more predictable revenue streams.
- Clinical Diagnostics:Definitive positive-negative determination for infectious pathogens, cardiac markers, and tumor antigens generates the foundational revenue base. German reference laboratories and Japanese university hospitals anchor procurement volume under statutory health insurance frameworks.
- Drug Development:Pharmacokinetic and immunogenicity studies for biologics pipelines demand ultra-sensitive detection thresholds. Contract research organizations in North America are scaling capacity fastest as monoclonal antibody submissions proliferate.
- Environmental Testing:Water quality and contaminant monitoring applications employ competitive ELISA formats for field-deployable screening.
- Food Safety:Pathogen detection and allergen quantification in supply chain auditing uses lateral flow and ELISA methods for rapid lot release.
Clinical diagnostics absorbs the majority of platform placements; drug development workflows are gaining share fastest.
Technology:
Detection modality selection determines reagent stability, instrument capital requirements, and regulatory classification complexity across jurisdictions.
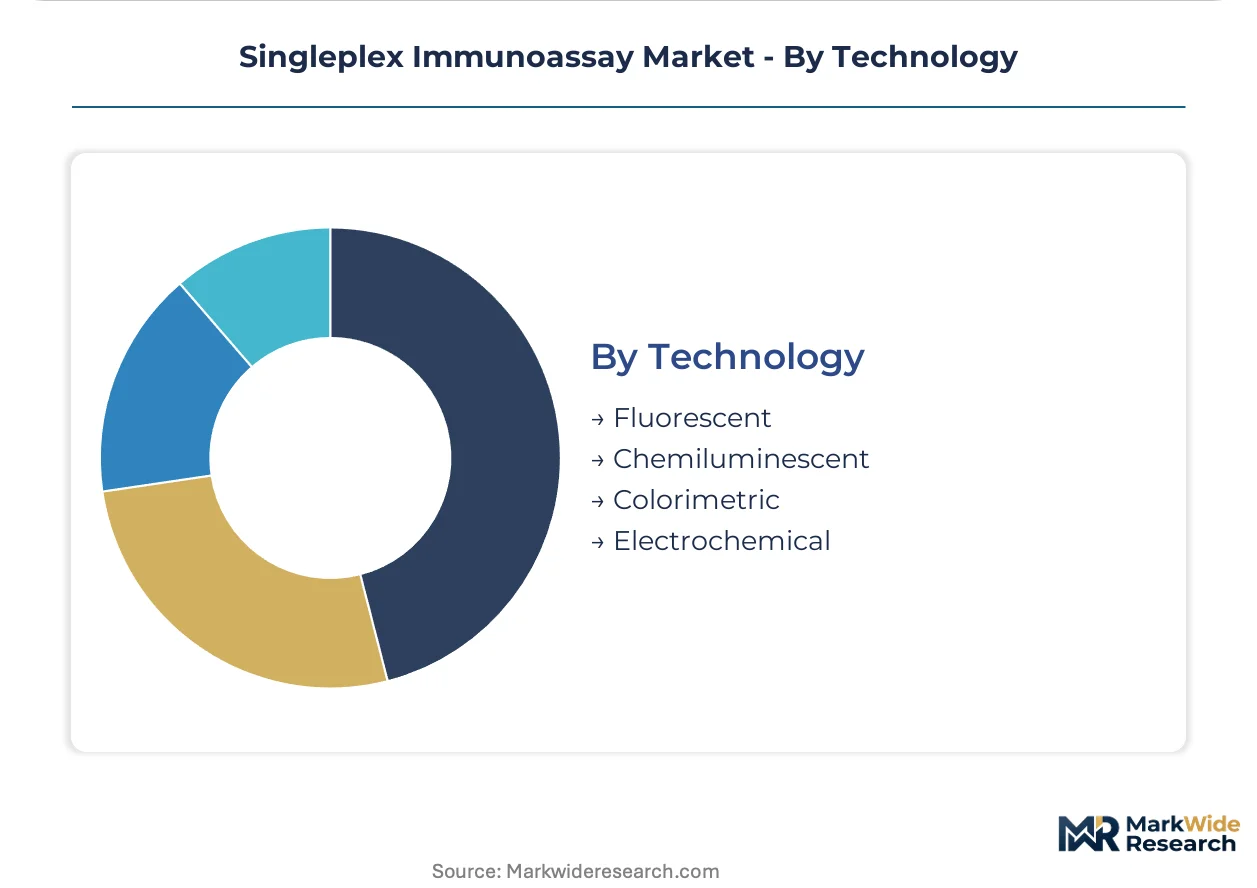
- Chemiluminescent:Signal amplification via acridinium ester flash kinetics or alkaline phosphatase sustained glow delivers the widest dynamic range. Siemens Healthineers and Abbott Laboratories dominate installed base in Western European tertiary networks through integrated analyzer workflows.
- Fluorescent:Time-resolved fluorometry and fluorescence polarization architectures offer multiplex-compatibility and reduced background interference. Research institutions in the United States favor these platforms for biomarker panel development.
- Colorimetric:Absorbance-based readout systems maintain lowest reagent cost and simplest optical train for resource-limited settings.
- Electrochemical:Amperometric and impedimetric detection enables miniaturization for point-of-care and wearable biosensor applications.
Chemiluminescent technology commands the dominant installed base; electrochemical methods are expanding most quickly in point-of-care configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform vendors concentrate manufacturing and technical support infrastructure in Germany, the United States, and Japan where hospital consolidation drives centralized laboratory procurement. Regulatory validation requirements in these markets create entry barriers that reinforce incumbent positions.
United States
Consolidated health systems in Texas and California extract volume discounts through centralized laboratory administration controlling capital allocation. FDA premarket notification pathways impose escalating clinical validation burdens on novel assay introductions. Tertiary hospital networks across the Midwest and Northeast are converting serology workflows to chemiluminescent architectures.
Germany
Reference laboratories under statutory health insurance frameworks anchor procurement volume for high-throughput analyzers. EU In Vitro Diagnostic Regulation Class C device classification forces manufacturers to generate expanded clinical performance data. The Rhine-Ruhr metropolitan region hosts dense clusters of diagnostic instrument engineering and reagent manufacturing operations.
Japan
Community clinic networks outside metropolitan hospital systems are adopting compact chemiluminescent analyzers for decentralized infectious disease screening. METI industrial standards and PMDA device approvals structure market access requirements. The Kanto region around Tokyo concentrates tertiary hospital networks driving premium platform adoption.
United Kingdom
NHS procurement frameworks favor vendors with established MDR technical documentation and dedicated field service support. MHRA post-Brexit regulatory alignment creates parallel submission requirements for IVD manufacturers. The Greater Southeast region including London anchors specialized reference laboratory capacity for oncology biomarker testing.
Switzerland
Swissmedic certification requirements and proximity to German manufacturing clusters position the country as a regulatory testbed for novel detection platforms. Basel and Zurich host concentrated pharmaceutical research operations driving demand for pharmacokinetic assay services. Private diagnostic networks compete on specialized test menus and rapid courier logistics.
Singleplex Immunoassay Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the singleplex immunoassay market. The vendor base organizes around three strategic tiers: integrated analyzer-reagent systems commanding premium pricing, open-platform consumable suppliers competing on per-test economics, and point-of-care specialists optimizing for footprint and turnaround time. Dominant competitive moves include captive reagent-instrument bundling to lock laboratory procurement and ISO 13485 certification arbitrage to capture OEM partnerships with instrument manufacturers.
Among diversified healthcare conglomerates, Siemens Healthineers and Abbott Laboratories exemplify integrated platform strategies, while Roche Diagnostics occupies a position within the captive supply agreement archetype. These entities anchor competitive dynamics through control over automated workflow architectures and reagent supply continuity.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Ortho Clinical Diagnostics |
| Abbott Laboratories |
| Quidel Corporation |
| PerkinElmer |
| Roche Diagnostics |
| Bio-Rad Laboratories |
| Danaher Corporation |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
High-throughput analyzer scale economies in Germany and Japan concentrate manufacturing capacity among integrated platform vendors, compressing per-test reagent costs for centralized laboratories while erecting price floors that exclude smaller consumable suppliers from tertiary hospital procurement cycles.
Pricing Analysis
EU In Vitro Diagnostic Regulation dictates the pricing tier structure across European clinical laboratories, separating premium automated chemiluminescent systems with full MDR technical documentation from mid-tier ELISA platforms and economy-grade open-consumable configurations. Price differentiation rests on ISO 13485 certification grade and after-sales service bundling. Pricing pressure stems from consolidated buying committees unbundling service contracts from instrument procurement. Research institutions exhibit highest price sensitivity; tertiary hospital networks anchored by statutory insurance frameworks show lowest.
Supply Chain Analysis
Acrylamide and nitrocellulose membrane supply from German chemical manufacturers constitutes a chokepoint for Western European reagent production. Manufacturing concentrates in Germany, the United States, and Japan. Raw material dependencies include acridinium ester chemiluminescent substrates, monoclonal antibody cell lines, and precision injection-molded cartridges. Single-source vulnerability runs through captive reagent-instrument bundling by dominant platform vendors. Distribution feeds from direct field service organizations and independent diagnostic distributors into consolidated health system laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
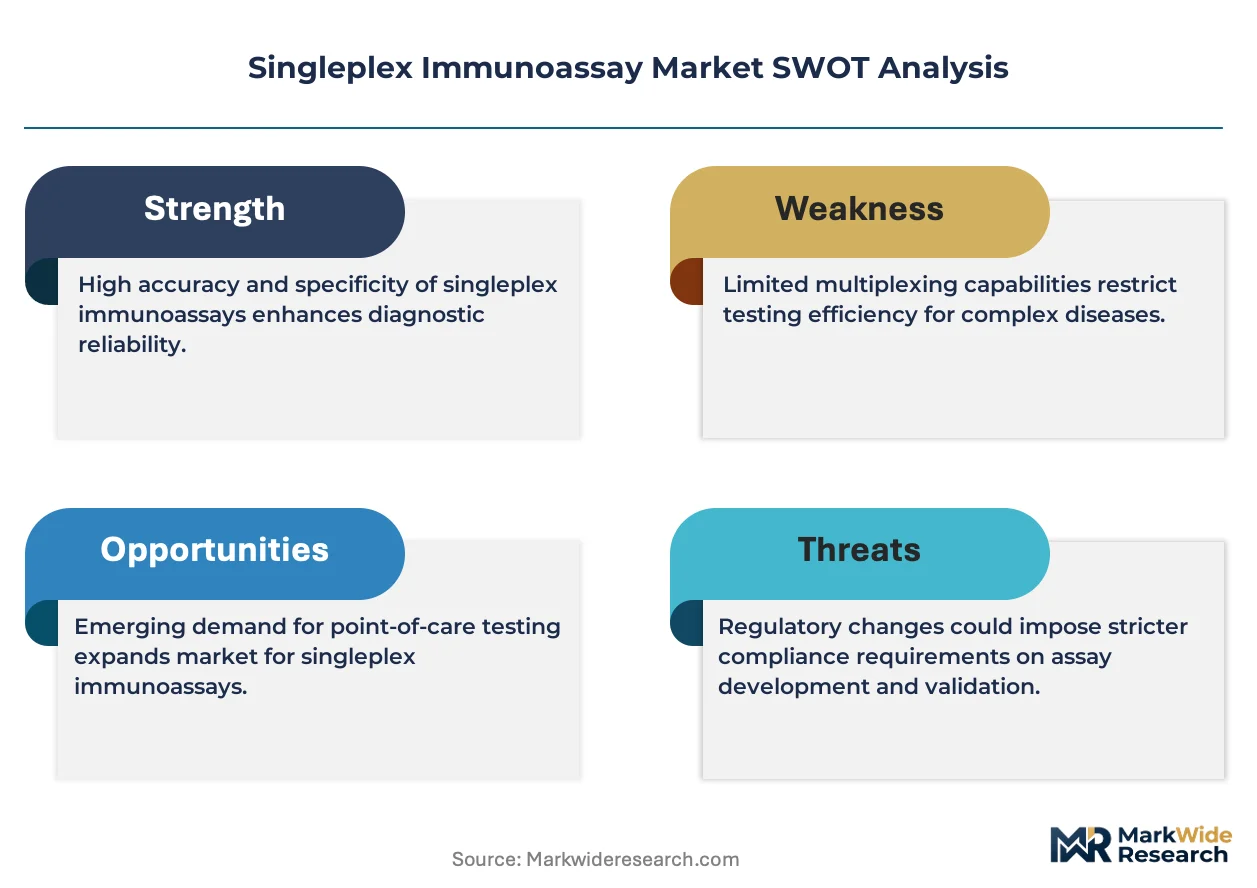
The singleplex immunoassay market presents a regulatory entrenchment moat where EU MDR and FDA premarket notification pathways create switching costs that lock laboratories into validated vendor ecosystems.
For Market Incumbents: Compound captive reagent supply agreements with centralized laboratories in Texas and California health systems to deepen switching cost architecture. Expand ISO 13485-certified manufacturing capacity in the Rhine-Ruhr corridor to capture OEM partnerships with open-platform instrument manufacturers. Multiplex assay substitution in oncology screening represents the primary substitution threat requiring defensive R&D investment.
For New Entrants and Emerging Players: Independent service organization capacity for chemiluminescent analyzer maintenance presents a service-layer gap where incumbents under-serve unbundled procurement contracts. Target community clinic networks in Japan's non-metropolitan prefectures for compact analyzer placement. Pursue ISO 13485 certification arbitrage to supply validated consumables into open-platform ecosystems without competing directly on instrument capital.
For Investors and Strategic Acquirers: Regional reagent specialists with captive antibody production capabilities and established MDR dossiers represent the most defensible acquisition target archetype. Long-term viability depends on regulatory submission infrastructure becoming scarcer as EU MDR and FDA pathways compress the viable manufacturer base. Monitor biologics pipeline submission rates at North American contract research organizations as the inflection indicator for pharmacokinetic assay demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates market access for Class C infectious disease assays in German reference laboratories. |
| ISO 13485 Certification Achievement | Unlocks OEM consumable partnerships with open-platform instrument manufacturers seeking validated reagent sources. |
| Hospital System Partnership Expansion | Captures volume discounts through consolidated procurement committees in Texas and California health networks. |
| Digital Microfluidic Cartridge Development | Reduces capital footprint for mid-sized German and Japanese laboratories adopting disposable fluidic circuits. |
| Biopharma CRO Service Integration | Embeds singleplex modules into adaptive trial designs for real-time biomarker monitoring in North American sponsors. |
Study Parameters
The analysis maps chemiluminescent, fluorescent, colorimetric, and electrochemical detection sub-sectors, each validated through laboratory directors, regulatory affairs managers at reagent manufacturers, hospital procurement committee members, and biomedical engineers at contract research organizations. Primary interview findings triangulate against FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract records, and GPO pricing agreements. Bottom-up instrument placement and consumable pull-through estimates reconcile with top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including statutory health insurance reimbursement schedules in Germany and Japan, CMS clinical laboratory fee schedules, and biopharma R&D expenditure disclosures. The analytical framework models technology platform, end-user type, application segment, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs derive from instrument replacement cycles, laboratory consolidation trajectories, and biologics pipeline submission velocity inputs.
Forecasts assume regulatory continuity in FDA premarket notification and EU MDR regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated multiplex assay substitution in oncology, PMDA device approval pathway changes in Japan, and hospital information system interoperability failures disrupting chemiluminescent platform adoption. Practitioners should keep alternative scenarios live as laboratory consolidation patterns and biologics pipeline composition evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Rapid Plasma Reagin Test Market
Diagnostics
Global Companion Diagnostic Technologies Market
Diagnostics
Melanoma Cancer Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
In-Vitro Diagnostics (IVD) Packaging Market
Diagnostics
In Vitro Diagnostics (IVD) Quality Control Market
Diagnostics
Latent Tuberculosis Infection Detection Market
Diagnostics
Global HIV/AIDS Diagnostics Market
Diagnostics
Europe Ovarian Cancer Diagnostics Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Food Allergy Diagnostics and Therapeutics Market
Diagnostics
H. Pylori Breath Test Kit Market
Diagnostics
Fructosamine Test Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Immunoassay Interference Blocker Market