
 China in Vitro Diagnostics Market | 2026-2036
China in Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
China in Vitro Diagnostics Market Analysis
NMPA's revised Class III IVD registration pathway is hardening cost-of-entry calculus for multinational manufacturers seeking China market access. Mindray Medical International Limited leverages its domestic manufacturing footprint to navigate regulatory timelines more efficiently than imported competitors. Roche Diagnostics sustains premium positioning through specialized oncology and immunoassay portfolios that command hospital laboratory loyalty. Shanghai Kehua Bio-Engineering anchors its competitive stance in biochemical analyzers through extensive provincial distribution networks.
In vitro diagnostics encompasses medical tests performed on blood, urine, tissue, or other biological specimens outside the living organism, typically requiring reagent kits, automated analyzers, and consumables processed through controlled laboratory conditions with sensitivity thresholds measured in ng/mL or lower. These systems enable disease screening, therapeutic monitoring, and clinical decision support across hospital, laboratory, and point-of-care settings. Reagent segments capture recurring revenue streams through pull-through models tied to installed analyzer bases, while molecular diagnostics technology commands premium positioning as oncology companion testing expands in tertiary hospitals. Point-of-care delivery mode segments are gaining traction in emergency departments and rural clinic networks where turnaround time constraints override centralized laboratory economics.
NMPA, GB standards administered by SAMR, and dual carbon goals from MEE collectively shape product registration timelines, energy efficiency mandates for instrumentation, and domestic substitution priorities in public procurement. CDSCO-aligned quality system inspections and post-market surveillance requirements are intensifying compliance investments for both domestic firms and joint-venture operations. Stakeholders must monitor evolving provincial centralized procurement rules and diagnostic service pricing reforms that directly alter margin structures across the value chain.
Market Dynamics
NMPA's tightened Class III IVD registration pathway is compressing market entry timelines while provincial centralized procurement in Jiangsu and Zhejiang is forcing price renegotiation cycles that reshape margin structures across automated immunoassay and molecular diagnostics segments.
Growth Catalysts
- Oncology companion testing protocols:Tier-three hospitals in Jiangsu province are expanding molecular diagnostics capacity for precision therapy selection, creating pull-through demand for automated nucleic acid extraction platforms.
- Dual carbon mandates from MEE:Energy efficiency standards for laboratory instrumentation are accelerating replacement cycles of legacy analyzers in public hospital networks.
- Rural clinic network expansion:Point-of-care diagnostic deployment in county-level health centers is bypassing centralized laboratory infrastructure constraints.
Market Restraints
- Import dependency for high-sensitivity optical components:Photomultiplier tubes and precision lenses concentrate in Japanese and German supplier bases, exposing domestic manufacturers to lead time volatility.
- GB standard harmonization gaps:Divergence between NMPA clinical validation requirements and ISO 15189 laboratory accreditation creates duplicate documentation burdens for multinational registrants.
- Reagent-kit substitution economics:Open-system biochemical analyzers enable third-party reagent sourcing that erodes proprietary consumable pull-through revenue for original equipment manufacturers.
Strategic Opportunities
- Western province laboratory buildout:Sichuan and Shaanxi provincial health commissions are funding tier-three hospital expansions with dedicated molecular diagnostics floors.
- AI-assisted pathology integration:Digital image analysis algorithms are converging with immunohistochemistry workflows to reduce specialist pathologist review time.
- Centralized procurement participation rules:SAMR's domestic preference weighting in public tenders creates channel access advantages for manufacturers with in-country manufacturing footprints.
Industry Challenges
- Clinical validation specialist scarcity:NMPA's expanded biostatistics requirements for Class III submissions outpace trained regulatory affairs capacity in domestic CRO networks.
- Legacy analyzer integration complexity:Hospital laboratory information systems from disparate vendors require custom middleware development for new instrument connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China in Vitro Diagnostics Market |
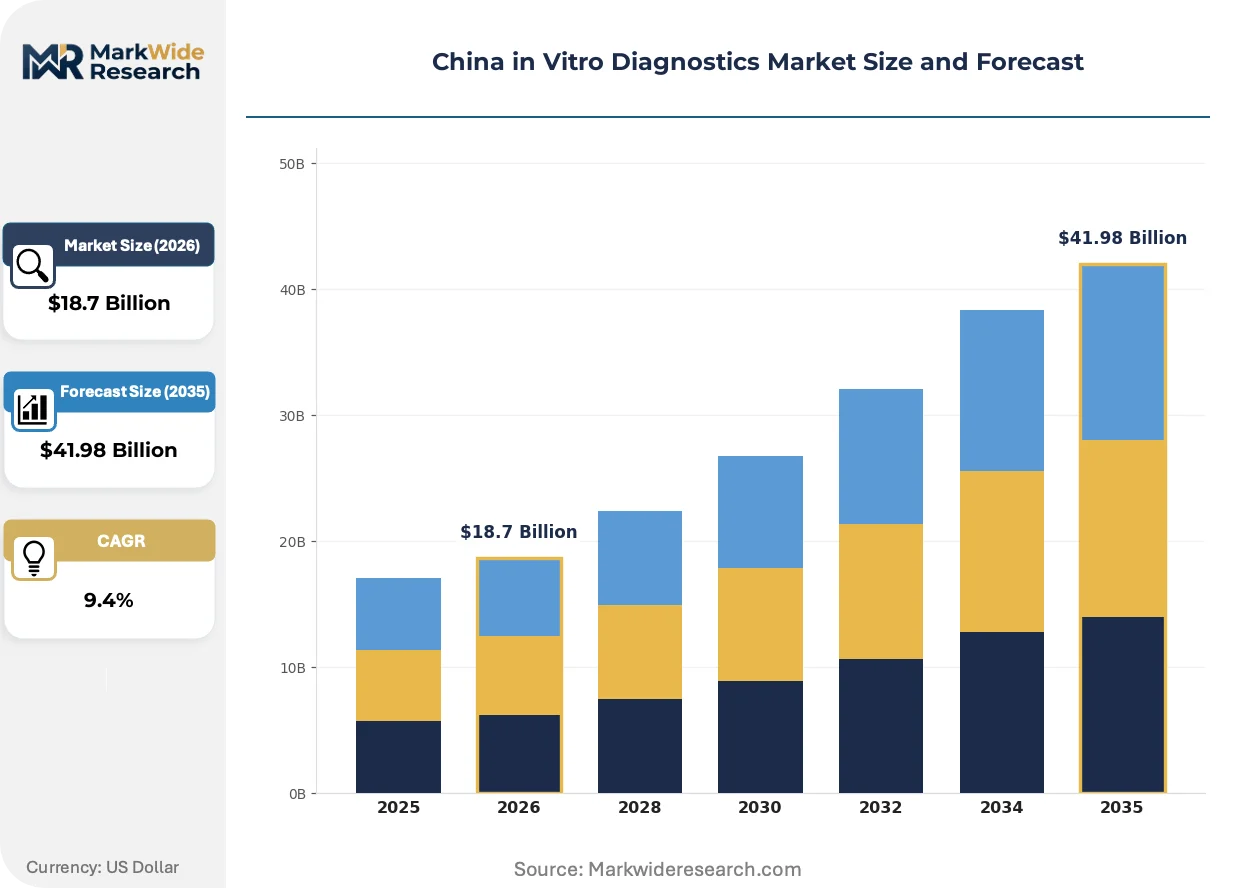
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Analyzers, Consumables, Software Technology: Molecular Diagnostics, Immunoassays, Microbiology, Hematology End User: Hospitals, Clinics, Laboratories, Home Care Delivery Mode: Point-of-Care, Laboratory-Based, Telehealth, Connected Devices |
| Companies Covered | Roche Diagnostics, Sysmex Corporation, Mindray Medical International Limited, Abbott, Shanghai Kehua Bio-Engineering, Siemens Healthcare GmbH, Danaher Corporation, Bio-Rad Laboratories, Inc., Maccura Biotechnology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China in Vitro Diagnostics Market Emerging Trajectories
Automated sample-to-answer platforms are compressing molecular diagnostics workflows while regulatory data requirements harden and hospital procurement centralization redistributes purchasing authority from individual laboratories to provincial consortia.
Multiplexed chemiluminescence immunoassay analyzers are unifying previously separate infectious disease and tumor marker testing workflows onto single platforms. Tier-three hospitals in Zhejiang province are adopting these systems at replacement-cycle velocity. This consolidation is unifying reagent procurement decisions under centralized laboratory management rather than individual department heads.
NMPA's 2023 revision to Class III IVD registration technical review guidelines mandates extended clinical trial cohorts for novel biomarker claims. Domestic manufacturers with established hospital research collaborations are navigating these timelines more efficiently than imported competitors. Oncology companion diagnostics and infectious disease panels face the steepest documentation requirements.
Provincial centralized procurement consortia in Jiangsu and Anhui are consolidating reagent purchasing decisions across multiple hospital networks. Distributors with exclusive territorial rights are losing negotiation leverage to direct manufacturer-contracting models. This concentration is most visible in biochemical analyzer consumables where volume commitments determine pricing tiers.
China in Vitro Diagnostics Market Segmentation
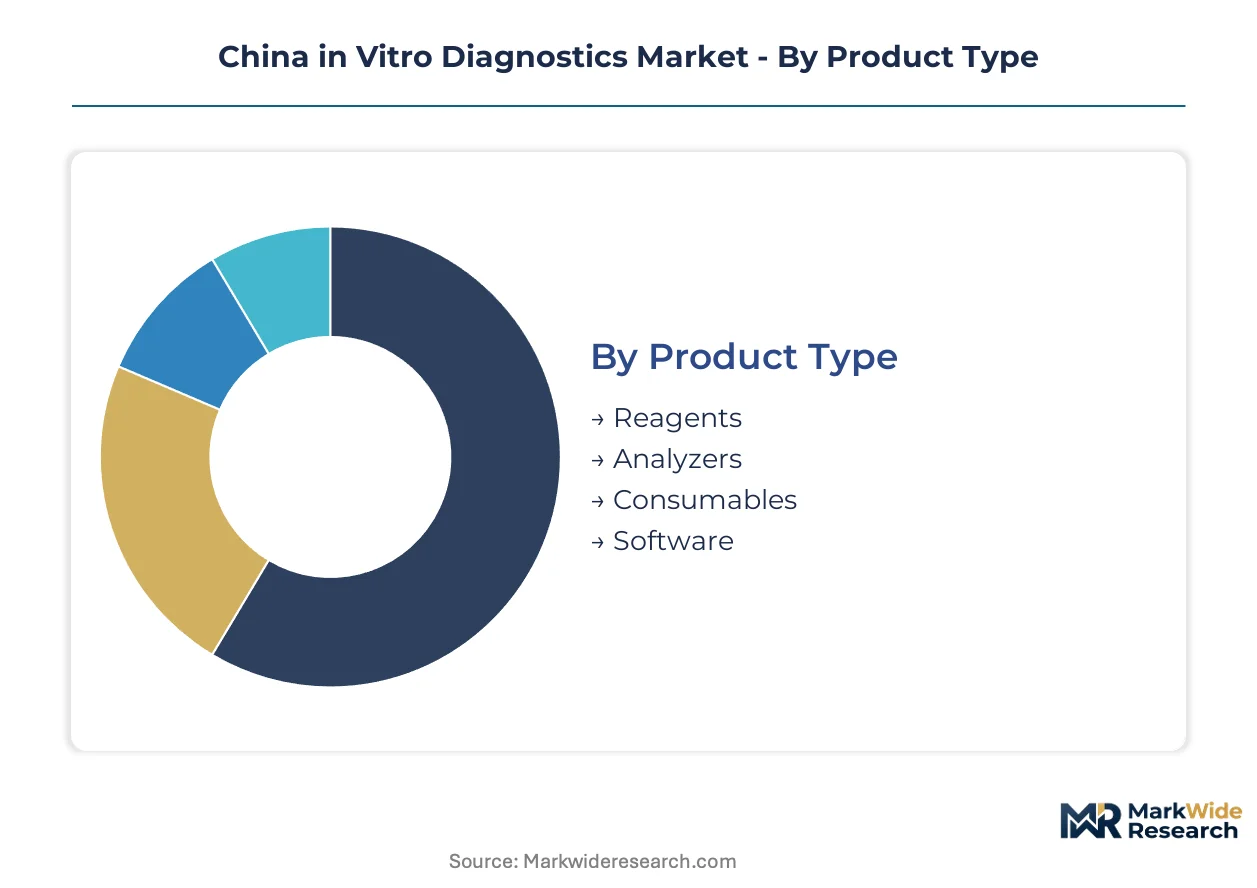
IVD market segmentation reveals distinct upgrade cycles across hardware, reagent, and software layers. Hospital procurement centralization in Jiangsu and Zhejiang provinces is compressing decision timelines and favoring integrated platform vendors over point-solution suppliers.
Product Type:
Replacement cycles for automated analyzers are accelerating as NMPA's Class III registration pathway hardens compliance requirements for new system introductions.
- Reagents:Biochemical and immunoassay reagent kits generate recurring revenue through analyzer-installed base pull-through. Jiangsu provincial centralized procurement is consolidating purchasing authority and forcing volume-commitment pricing tiers across hospital networks.
- Analyzers:Automated immunoassay and molecular diagnostic platforms require capital investment cycles tied to NMPA registration timelines. Tier-three hospitals in Zhejiang are replacing legacy systems with sample-to-answer platforms that unify multiple test menus.
- Consumables:Pipette tips, reaction vessels, and sample collection devices face cost-down pressure from provincial procurement consortia.
- Software:Laboratory information system middleware and AI-assisted pathology algorithms require custom integration with hospital IT infrastructure.
Reagents sit at the top of the volume ranking, with analyzers climbing the fastest as dual carbon mandates from MEE accelerate energy-efficient equipment replacement.
Technology:
Cost tier differentiation separates premium molecular platforms from standardized immunoassay systems in hospital laboratory budgeting.
- Molecular Diagnostics:Nucleic acid amplification and sequencing platforms enable oncology companion testing with sensitivity thresholds measured in copies per milliliter. Tier-three hospitals in Sichuan are expanding dedicated molecular diagnostics floors with government funding.
- Immunoassays:Chemiluminescence analyzers dominate infectious disease and tumor marker testing workflows. Multiplexed systems from domestic manufacturers are gaining share in Jiangsu centralized procurement tenders through price-performance positioning.
- Microbiology:Automated culture and identification systems face longer validation timelines under NMPA's tightened clinical evidence requirements.
- Hematology:Cell counter and coagulation analyzer segments are maturing with replacement demand concentrated in county-level hospital upgrades.
Immunoassays command the largest installed base, while molecular diagnostics is expanding most quickly as precision therapy protocols proliferate in tertiary oncology centers.
End User:
Customer type determines pricing elasticity and purchasing process complexity across public and private healthcare channels.
- Hospitals:Tier-three public hospitals concentrate demand for high-throughput automated platforms. Centralized procurement in Anhui and Jiangsu provinces is shifting negotiation leverage from distributors to direct manufacturer contracting.
- Clinics:County-level health centers and rural clinics are deploying point-of-care devices that bypass centralized laboratory infrastructure constraints.
- Laboratories:Independent clinical laboratories face margin compression from diagnostic service pricing reforms.
- Home Care:Self-monitoring glucose and infectious disease testing kits remain limited by reimbursement policy uncertainty.
Hospitals dominate procurement volume, with clinics gaining share fastest as rural network expansion targets county-level diagnostic capacity.
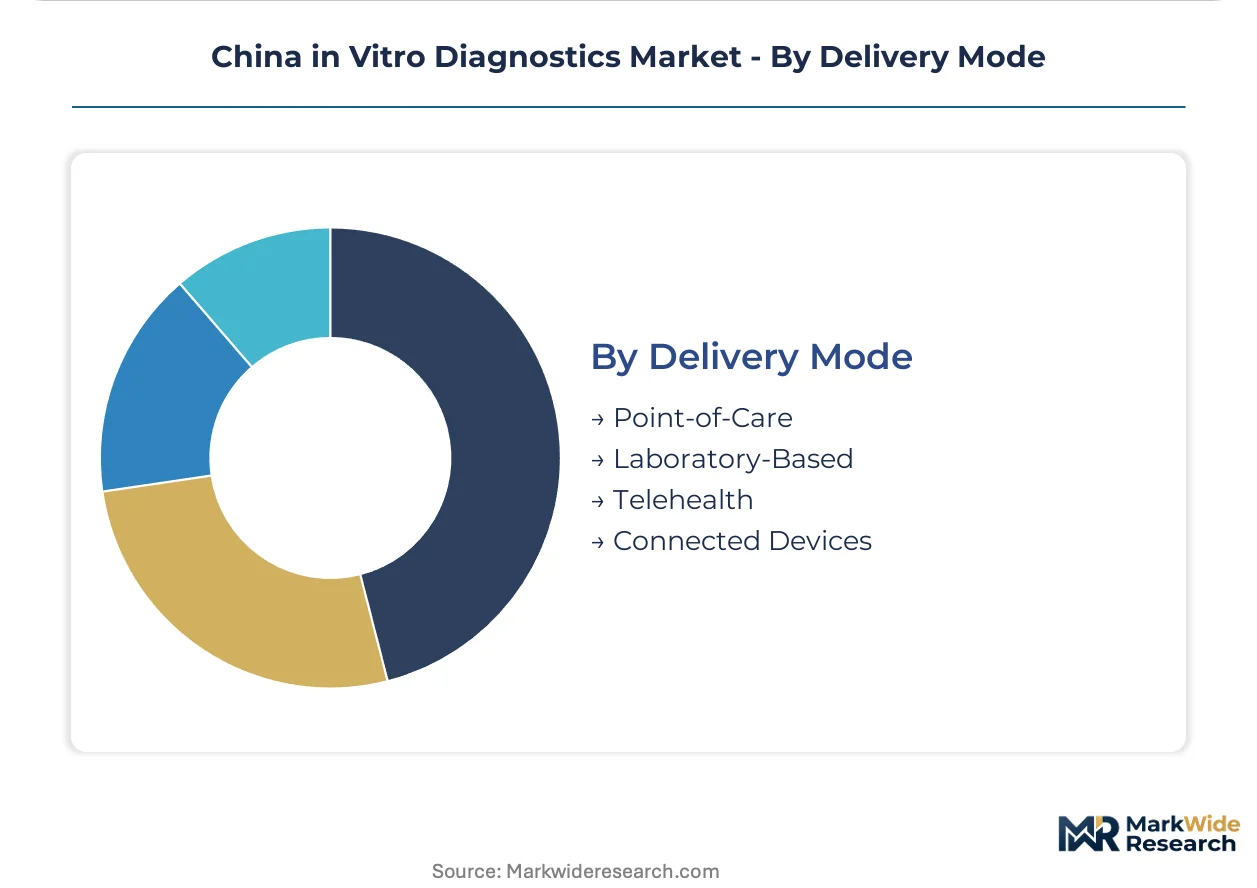
Delivery Mode:
Application urgency determines whether centralized laboratory economics or decentralized turnaround time priorities govern equipment selection.
- Point-of-Care:Emergency departments and rural clinics prioritize rapid turnaround over test menu breadth. Connected glucose meters and infectious disease rapid tests are penetrating county health centers in western provinces.
- Laboratory-Based:Centralized testing maintains cost efficiency for high-volume routine panels. Automated sample-to-answer platforms are compressing molecular diagnostics workflows in Zhejiang tier-three hospitals.
- Telehealth:Remote diagnostic consultation requires digital pathology and image transmission infrastructure.
- Connected Devices:IoT-enabled analyzers with cloud-based quality control are emerging in laboratory networks seeking centralized monitoring capabilities.
Laboratory-based delivery retains the highest throughput volume, with point-of-care expanding most quickly as emergency department efficiency metrics harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory affairs specialists and clinical validation scientists cluster in Jiangsu and Zhejiang provinces, anchoring the talent base for NMPA compliance and hospital laboratory expansion across eastern China.
Jiangsu Province
Tier-three hospitals in Nanjing and Suzhou are expanding automated immunoassay capacity for oncology companion testing protocols. Provincial centralized procurement consortia are consolidating reagent purchasing decisions across hospital networks, compressing distributor margins. The Yangtze River Delta manufacturing corridor hosts domestic analyzer assembly operations serving eastern China demand.
Zhejiang Province
Hangzhou's hospital laboratories are replacing legacy systems with multiplexed chemiluminescence platforms that unify infectious disease and tumor marker workflows. NMPA's tightened Class III registration pathway is extending validation timelines for novel biomarker claims. The province's health commission is funding molecular diagnostics floor expansions in tertiary oncology centers.
Sichuan Province
Chengdu-based tier-three hospitals are building dedicated molecular diagnostics capacity with provincial government funding for precision therapy selection. Western province laboratory buildout targets diagnostic equity gaps relative to eastern coastal infrastructure. The Sichuan-Chongqing economic zone is emerging as a secondary hub for clinical trial site networks.
Beijing-Tianjin-Hebei
Capital region hospitals concentrate demand for high-sensitivity molecular diagnostics platforms serving national referral networks. SAMR's domestic preference weighting in public tenders favors manufacturers with in-country manufacturing footprints. The Beijing cluster hosts NMPA headquarters and specialized regulatory consulting capacity for Class III device submissions.
Shandong Province
Qingdao and Jinan hospital networks are upgrading hematology and coagulation analyzer fleets under county-level health center expansion programs. Dual carbon mandates from MEE are accelerating replacement cycles of energy-intensive legacy instrumentation. The province's biochemical reagent manufacturing base supplies domestic open-system analyzer networks.
China in Vitro Diagnostics Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across analyzer, reagent, and consumable segments. Market structure tilts toward consolidation in molecular diagnostics platforms while remaining fragmented in biochemical reagent supply. Three archetypes dominate: multinational instrument manufacturers with premium positioning, domestic integrated platform vendors with regulatory timeline advantages, and specialized reagent producers with provincial distribution depth. Competitive moves center on direct manufacturer contracting with centralized procurement consortia and backward integration into high-sensitivity optical component sourcing.
Within the multinational tier, Roche Diagnostics and Abbott exemplify premium portfolio positioning through specialized oncology and immunoassay offerings. Among domestic integrated manufacturers, Mindray Medical International Limited occupies a position leveraging in-country production for streamlined NMPA navigation. Shanghai Kehua Bio-Engineering represents the specialized reagent archetype with extensive provincial distribution networks in biochemical analyzer consumables.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Sysmex Corporation |
| Mindray Medical International Limited |
| Abbott |
| Shanghai Kehua Bio-Engineering |
| Siemens Healthcare GmbH |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Maccura Biotechnology |
| Others |
Supply Flow & Price Mechanics
Photomultiplier tube and precision lens costs from Japanese and German supplier bases cascade through analyzer manufacturing tiers, with NMPA Class III registration timelines amplifying working capital requirements for importers relative to domestic assemblers in Jiangsu and Zhejiang.
Pricing Analysis
Reagent kit bundling versus unbundled analyzer-only procurement separates pricing models across hospital laboratory contracts. Three-tier pricing structure across premium, standard, and economy levels aligns with NMPA registration tier, installed base scale, and after-sales service intensity. Cost compression in biochemical reagent segments runs through provincial centralized procurement volume commitments. County-level health centers exhibit highest price sensitivity; national referral network hospitals in Beijing-Tianjin-Hebei show lowest.
Supply Chain Analysis
Specialized optical engineering talent concentrates in Japanese precision component clusters and German lens manufacturing regions, constraining domestic analyzer assembly capacity expansion. High-sensitivity photodetector arrays and precision optical assemblies draw from supplier bases in Japan, Germany, and select South Korean component specialists. Single-source vulnerability in photomultiplier tube supply exposes lead time volatility. Distribution runs through provincial distributor networks transitioning toward direct manufacturer contracting with centralized procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's IVD market functions as a geographic-arbitrage play where domestic manufacturing footprints compress NMPA registration timelines relative to import-dependent competitors facing extended clinical validation requirements.
For Market Incumbents: Acquire clinical validation specialist capacity to offset NMPA biostatistics requirements expansion. Backward integration into high-sensitivity optical component sourcing reduces Japanese and German supplier dependency. Channel control through direct contracting with Jiangsu and Zhejiang provincial procurement consortia defends against distributor margin erosion. Certification investment in dual carbon-compliant analyzer platforms accelerates replacement cycle capture. For New Entrants and Emerging Players: AI-assisted pathology algorithms offer technology-first wedge into immunohistochemistry workflow digitization. Western province molecular diagnostics floor buildouts in Sichuan and Shaanxi represent the most penetrable geography. Point-of-care device deployment in county-level health centers bypasses entrenched centralized laboratory relationships. Go-to-market through emergency department efficiency metrics rather than laboratory capital budget cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where open-system biochemical analyzer economics erode proprietary reagent pull-through revenue. Long-term viability favors integrated platform vendors with captive reagent manufacturing and provincial distribution depth. Acquisition target archetype: domestic manufacturers with NMPA Class III registration track records and established hospital research collaborations. Signal to watch: provincial centralized procurement consortia expansion beyond Jiangsu and Zhejiang into Anhui and Shandong.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Pathway Investment | Accelerates market access timelines relative to import-dependent competitors facing extended clinical validation. |
| Provincial Centralized Procurement Consortium Participation | Secures volume-commitment pricing tiers in Jiangsu and Zhejiang hospital network consolidations. |
| Dual Carbon-Compliant Analyzer Platform Development | Captures MEE-mandated replacement cycles in public hospital energy efficiency upgrades. |
| AI-Assisted Pathology Software Companion Development | Reduces specialist pathologist review time in tier-three hospital immunohistochemistry workflows. |
| Backward Integration into Optical Component Sourcing | Mitigates photomultiplier tube supply vulnerability from Japanese and German supplier concentration. |
Methodological Framework
Coverage spans eastern coastal provinces, western buildout regions, and capital region clusters, with primary inputs from each. Laboratory directors, hospital procurement committee members, NMPA regulatory affairs specialists, and provincial health commission planning officers provided structured interview data. Secondary validation drew from NMPA device registration databases, SAMR procurement policy circulars, provincial health commission capital expenditure disclosures, and hospital laboratory information system vendor documentation. Bottom-up analyzer and reagent volume estimates triangulated against top-down healthcare infrastructure spending allocations.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product type tier, technology platform, end-user facility class, and delivery mode configuration. CAGRs derive from installed base expansion rates, replacement cycle velocity, and reagent pull-through coefficients. NMPA registration timeline assumptions and provincial centralized procurement participation rates constitute industry-specific forecast inputs.
The model holds under continued NMPA Class III pathway stability and provincial procurement centralization; deviation in reimbursement policy reform timing or import component tariff exposure would shift trajectory. Forecasts reflect these base conditions and embedded assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Canada in-Vitro Diagnostics Market
Diagnostics
Asia-Pacific Antinuclear Antibody Test Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
Hepatitis Test Solution and Diagnosis Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
Preeclampsia Diagnostics Market
Diagnostics
Professional Diagnostics Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Diagnostic Reagents Market
Diagnostics
Global Hemostasis Diagnostics Market
Diagnostics
Adenovirus Diagnostic Testing Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Middle East and Africa Syndromic Multiplex Diagnostic Market
Diagnostics
Veterinary Chemistry Analyzers Market