
 Global Alcoholic Hepatitis Therapeutics Market | 2026-2036
Global Alcoholic Hepatitis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alcoholic Hepatitis Therapeutics Market Intelligence
Hepatology specialist availability is collapsing across rural health systems, forcing tertiary hospitals to consolidate complex alcoholic hepatitis cases into centralized referral networks. Gilead Sciences anchors its position through deep R&D investment in liver disease modalities. Intercept Pharmaceuticals differentiates via bile acid receptor targeting platforms. Madrigal Pharmaceuticals competes on NASH-to-ASH pipeline adjacencies.
Alcoholic hepatitis therapeutics encompass pharmacological agents designed to suppress hepatic inflammation, modulate cytokine cascades, and prevent progression to cirrhosis in patients with acute-on-chronic alcohol-related liver injury; corticosteroids such as prednisolone function through NF-κB pathway inhibition to reduce neutrophil infiltration and hepatocyte apoptosis. The product type landscape shows corticosteroids sustaining dominant share in severe presentations while antioxidant combinations capture emerging interest for mild-to-moderate cases. By therapy area, severe alcoholic hepatitis concentrates the highest acuity spend and shortest treatment windows, whereas cirrhosis prevention represents a longer-duration margin pool as healthcare systems emphasize downstream cost avoidance.
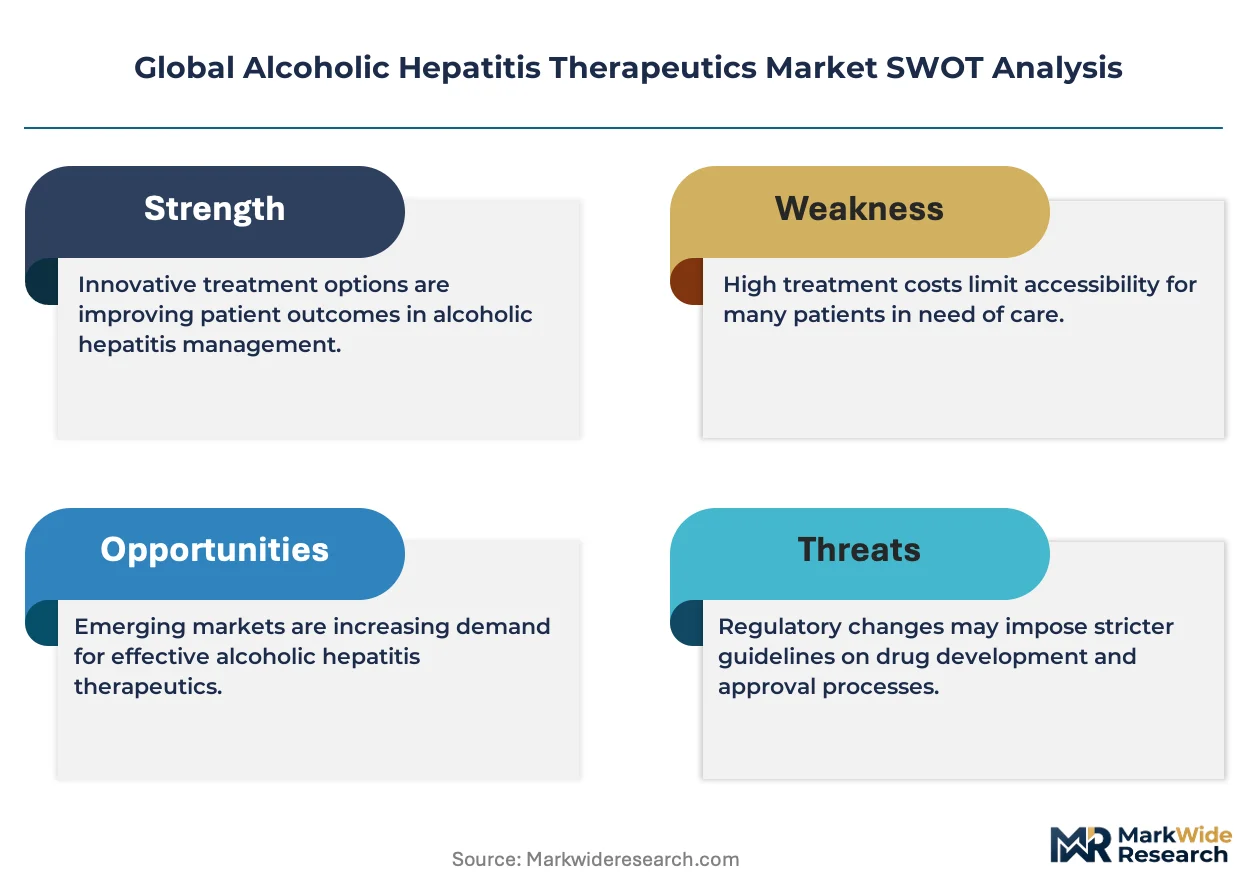
The U.S. FDA, European Medicines Agency, and Japan's Pharmaceuticals and Medical Devices Agency each enforce distinct evidentiary thresholds for liver disease drug approval, with FDA's breakthrough therapy designation and EMA's PRIME scheme accelerating access for severe alcoholic hepatitis candidates. These frameworks shape trial endpoints, biomarker qualification, and post-market surveillance obligations across jurisdictions. Stakeholders must monitor evolving payer evidence requirements for combination regimens versus monotherapy standards.
Market Dynamics
The FDA's accelerated approval pathways for liver disease indications are compressing development timelines while simultaneously raising evidentiary bars for post-market validation, forcing developers to front-load biomarker qualification and adaptive trial design.
Growth Catalysts
- FDA Breakthrough Therapy Designation:This framework expedites review timelines for severe alcoholic hepatitis candidates, reducing regulatory friction for novel corticosteroid alternatives and cytokine modulators entering Phase III.
- Tertiary Hospital Consolidation:Centralized hepatology referral networks in the United States, Germany, and Japan are concentrating eligible patient pools, improving trial recruitment efficiency and post-launch adoption velocity.
- Biomarker-Qualified Surrogate Endpoints:Validated liver function surrogates are enabling smaller, faster trials for mild-to-moderate disease segments, expanding addressable populations beyond historically restrictive severe-case definitions.
Market Restraints
- Plasma-Derived Biologics Input Volatility:Albumin and clotting factor supply constraints create formulation bottlenecks for combination therapies targeting coagulopathy in acute presentations.
- EMA Conditional Approval Stringency:European post-authorization study requirements impose heavier confirmatory trial burdens than FDA pathways, delaying revenue recognition in Western European markets.
- Diagnostic Substitution Risk:Transient elastography and MRI-PDFF are displacing liver biopsy for disease staging, reducing histologically-confirmed case identification and narrowing precision-treatment eligibility.
Strategic Opportunities
- PMDA Sakigake Pathway:Japan's regenerative medicine and pioneering drug designation offers first-mover premium pricing for hepatoprotective agents addressing unmet need in East Asian populations.
- Telehepatology Channel Expansion:Remote specialist consultation platforms are penetrating rural health systems, extending prescriber reach for maintenance therapies beyond traditional tertiary center catchments.
- NASH-to-ASH Pipeline Adjacency:Fibroblast activation protein inhibitors and CCR2/CCR5 antagonists validated in non-alcoholic steatohepatitis trials are repositioning toward alcoholic hepatitis with abbreviated development paths.
Industry Challenges
- Hepatology Specialist Workforce Compression:Fellowship program output is failing to match retirement rates, creating prescriber scarcity that limits launch scale for novel agents requiring specialist administration.
- Adaptive Trial Infrastructure Capex:Real-time biomarker monitoring and interim analysis capabilities demand substantial upfront investment in data management platforms and biostatistical staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alcoholic Hepatitis Therapeutics Market |
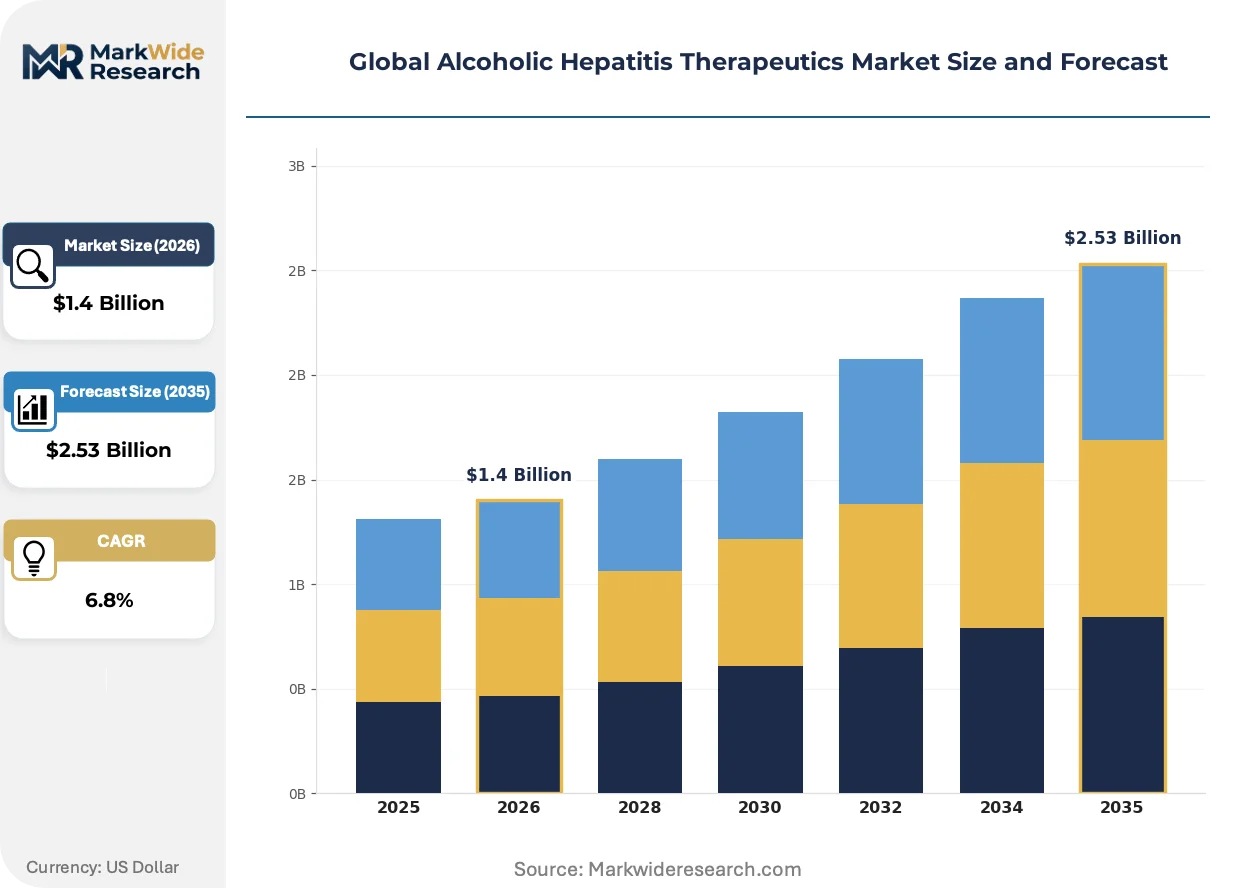
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Pentoxifylline, Antioxidants, Nutritional Supplements Therapy Area: Severe Alcoholic Hepatitis, Mild Alcoholic Hepatitis, Chronic Liver Disease, Cirrhosis Prevention End User: Hospitals, Specialty Clinics, Diagnostic Centers, Research Institutes Delivery Mode: Oral, Intravenous, Injectable, Transdermal |
| Companies Covered | Gilead Sciences Inc, Sanofi S.A, Intercept Pharmaceuticals Inc, Immuron Limited, Generon Pharmaceutical Technology Company Limited, DURECT Corporation, Conatus Pharmaceuticals Inc, Madrigal Pharmaceuticals Inc, CymaBay Therapeutics Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alcoholic Hepatitis Therapeutics Market Strategic Shifts & Innovations
Clinical development models are pivoting from fixed-protocol designs toward adaptive frameworks that respond to interim biomarker signals, compressing decision timelines while multiplying regulatory complexity.
Artificial intelligence-driven patient stratification is fragmenting traditional severity-based trial enrollment. Machine learning models integrating multi-omics data identify treatment-responsive subpopulations invisible to conventional MELD scoring. Academic medical centers in the United States and Netherlands are deploying these platforms for prospective cohort selection, enabling smaller effect sizes to achieve statistical significance.
The European Medicines Agency's PRIME scheme is accelerating access for severe alcoholic hepatitis therapies through enhanced scientific dialogue and accelerated assessment procedures. Developers gain earlier clarity on acceptable surrogate endpoints and post-authorization evidence requirements. This regulatory tailwind is concentrating investment in cytokine-targeting biologics and gut-liver axis modulators, with applicants prioritizing EMA rapporteur engagement ahead of FDA pre-IND meetings.
Hospital procurement committees are unbundling pharmaceutical purchasing from bundled liver service contracts, creating direct manufacturer-tertiary center negotiations for high-cost biologics. This shift bypasses traditional group purchasing organization intermediaries in United States health systems. German university hospitals pioneered this model through AMNOG early benefit assessment negotiations, with Japanese designated medical institutions now adopting similar direct contracting for hepatology biologics.
Global Alcoholic Hepatitis Therapeutics Market Segmentation
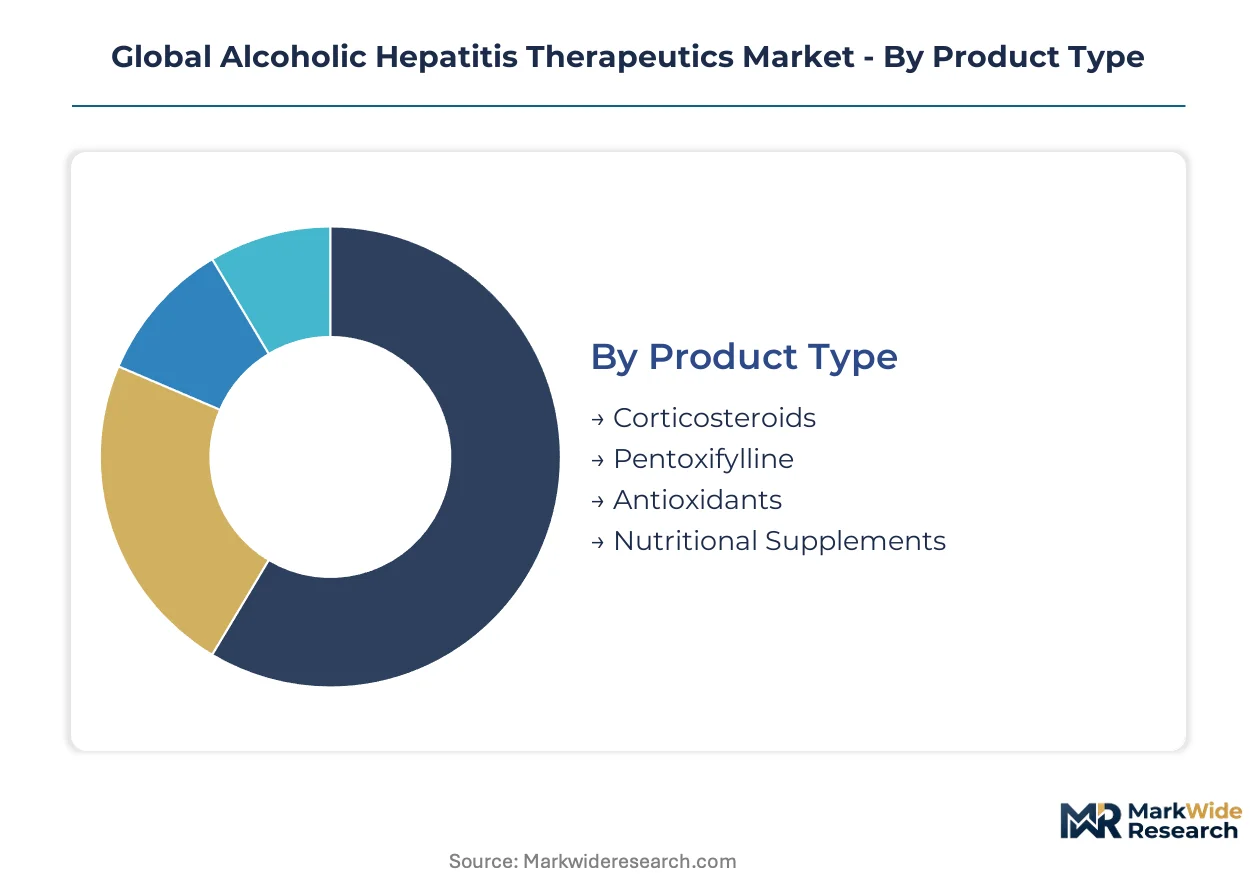
Alcoholic hepatitis therapeutics fragment across pharmacological classes, disease severity tiers, and care delivery settings. Each dimension carries distinct regulatory pathways, prescriber access patterns, and reimbursement frameworks that shape commercial strategy.
Product Type:
Corticosteroids command domestic production volumes in the United States and Germany, while antioxidant combinations and pentoxifylline formulations rely more heavily on cross-border API sourcing from India and China.
- Corticosteroids:Prednisolone and methylprednisolone function through NF-κB pathway inhibition to blunt neutrophil infiltration and hepatocyte apoptosis in severe presentations. Demand concentrates in tertiary hepatology units across the United States, Germany, and Japan where MELD scoring protocols guide rapid initiation.
- Antioxidants:N-acetylcysteine and silymarin combinations target oxidative stress in mild-to-moderate disease segments. Sourcing gravitates toward Italian and Spanish manufacturers with botanical extraction capabilities, though finished formulation often occurs in Central European CMOs.
- Pentoxifylline:Phosphodiesterase inhibitor with modest anti-TNF properties, positioned as corticosteroid-sparing therapy in infection-risk patients.
- Nutritional Supplements:Branched-chain amino acids and thiamine-folate protocols address malnutrition-driven decompensation in chronic cases.
Corticosteroids hold the largest share; momentum sits with antioxidant combinations as biopsy-confirmed case definitions narrow.
Therapy Area:
Cost tier stratification separates acute rescue interventions from chronic maintenance protocols, with severe cases absorbing disproportionate inpatient spend per episode.
- Severe Alcoholic Hepatitis:Maddrey discriminant function above 32 defines this high-acuity cohort requiring immediate pharmacological rescue. Treatment windows compress to 7-14 days, concentrating volume in academic medical centers with transplant evaluation capabilities.
- Mild Alcoholic Hepatitis:Outpatient-managed presentations with abstinence counseling and nutritional optimization as primary interventions. Volume spreads across community hepatology practices in the United States and German ambulatory networks.
- Chronic Liver Disease:Long-duration management of persistent inflammation without acute decompensation.
- Cirrhosis Prevention:Fibrosis regression targets in compensated patients with histological evidence of reversible injury.
Severe alcoholic hepatitis absorbs the highest per-patient expenditure; cirrhosis prevention is climbing fastest as healthcare systems prioritize downstream cost avoidance.
End User:
Customer type fragmentation maps directly to prescriber credentialing requirements and reimbursement authorization tiers.
- Hospitals:Inpatient hepatology services and emergency department admissions drive corticosteroid and IV albumin utilization. Concentrated in designated transplant centers across the United States, Germany, and Japan with 24-hour gastroenterology coverage.
- Specialty Clinics:Outpatient hepatology practices manage mild-to-moderate cases with oral pentoxifylline and antioxidant protocols. German liver centers and Japanese polyclinics anchor regional referral networks.
- Diagnostic Centers:Transient elastography and biomarker staging services influence treatment eligibility determination.
- Research Institutes:Academic medical centers conduct adaptive trials with biomarker-qualified surrogate endpoints.
Hospitals retain the dominant share; specialty clinics are gaining fastest as telehepatology extends prescriber reach.
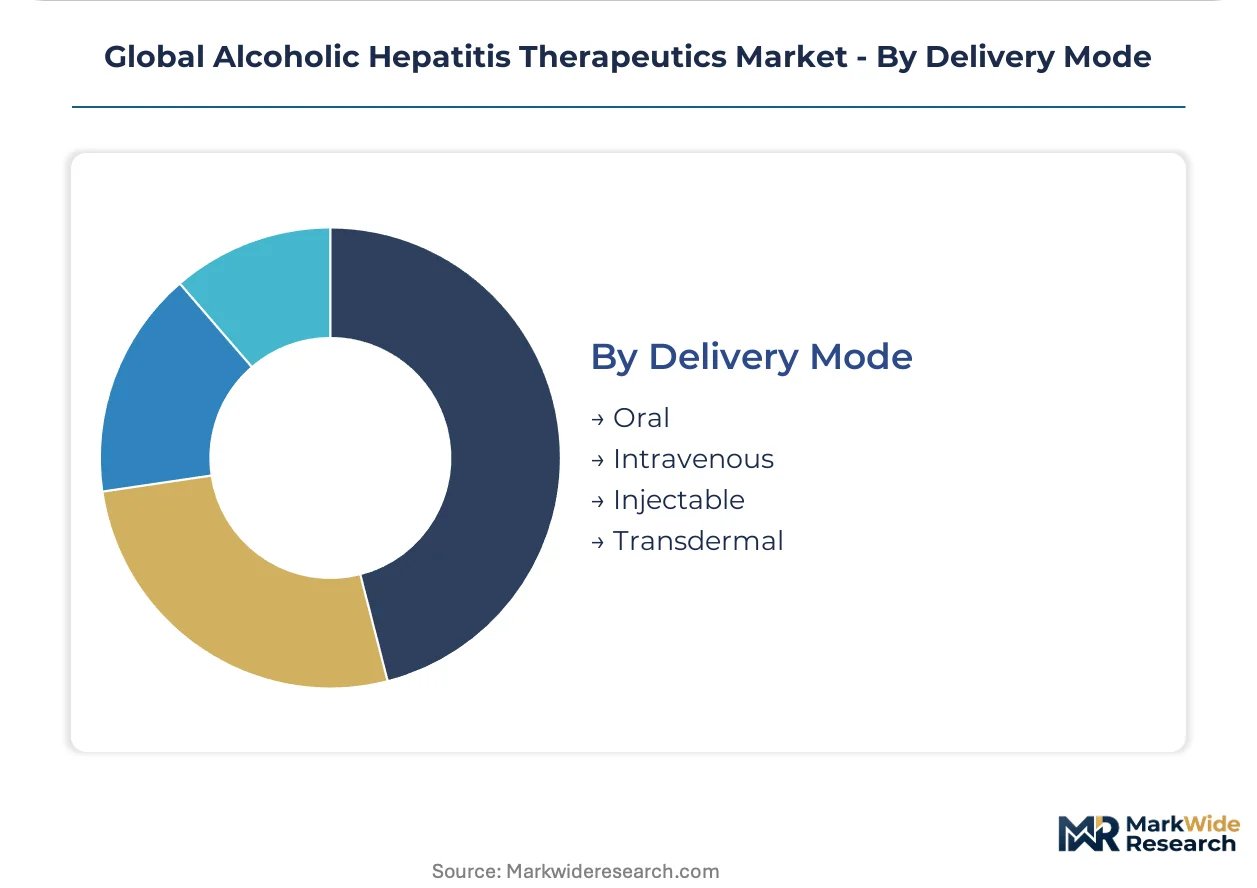
Delivery Mode:
Supply concentration favors parenteral manufacturing in established injectables hubs, while oral solid dose capacity remains geographically dispersed.
- Intravenous:Corticosteroid bolus therapy and albumin infusion for acute decompensation. Production clusters in North Carolina, Bavaria, and Osaka prefecture for aseptic fill-finish capabilities.
- Oral:Maintenance pentoxifylline and antioxidant tablets for outpatient adherence. Formulation spreads across Indian and Chinese oral solid dose facilities with cost-competitive API integration.
- Injectable:Subcutaneous cytokine modulators in development for severe cases.
- Transdermal:Experimental delivery platforms for hepatoprotective agents with poor oral bioavailability.
Intravenous administration commands premium pricing; oral formats are expanding most quickly as mild-case definitions broaden addressable populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor commercial strategy in the United States, while EMA and PMDA frameworks reshape trial design across Western Europe and East Asia. Hospital-based hepatology networks concentrate eligible patient pools in tertiary centers across three continents.
United States
Academic medical centers in Boston and Houston drive adaptive trial recruitment for severe alcoholic hepatitis candidates. FDA breakthrough therapy designation compresses Phase III timelines for cytokine modulators. The Research Triangle Park cluster in North Carolina anchors parenteral manufacturing capacity for corticosteroid formulations.
Germany
University hospitals in Munich and Heidelberg pioneered direct manufacturer contracting through AMNOG early benefit assessment negotiations. EMA conditional approval stringency imposes heavier post-authorization burdens than FDA pathways. The Bavarian injectables hub supplies aseptic fill-finish capacity for albumin combination therapies.
Japan
Designated medical institutions in Tokyo and Osaka consolidate severe case management within national liver disease networks. PMDA Sakigake designation offers premium pricing for hepatoprotective agents addressing unmet East Asian need. The Kansai region hosts specialized CMOs for biologic formulation development.
United Kingdom
Liver units in London and Birmingham manage centralized referral networks as rural hepatology specialist availability contracts. NICE technology appraisals shape reimbursement for corticosteroid alternatives in severe presentations. The Cambridge-Oxford corridor supports biomarker qualification studies for surrogate endpoints.
India
CDSCO accelerated approval pathways attract Phase IIb investment for antioxidant combinations targeting mild-to-moderate segments. Mumbai and Hyderabad anchor API sourcing for N-acetylcysteine and silymarin extraction. Contract research organizations in Bangalore support adaptive trial infrastructure for multinational sponsors.
Global Alcoholic Hepatitis Therapeutics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with R&D-intensive biopharmaceuticals commanding premium positioning against generic corticosteroid incumbents. The competitive terrain splits between liver disease modality developers and inflammation-targeting biologics platforms. Strategic archetypes include NF-κB pathway specialists, bile acid receptor modulators, and fibrosis regression platforms. Dominant competitive moves center on biomarker-qualified trial design and centralized hospital contracting bypassing traditional group purchasing intermediaries.
Within the integrated biopharmaceutical tier, Gilead Sciences Inc and Intercept Pharmaceuticals Inc exemplify contrasting modality bets—hepatitis antiviral heritage versus bile acid receptor innovation. Madrigal Pharmaceuticals Inc occupies a position bridging non-alcoholic steatohepatitis validation toward alcoholic hepatitis repositioning. Sanofi S.A represents the diversified pharmaceutical conglomerate archetype with liver disease assets folded into broader inflammation portfolios. These three entities anchor distinct strategic vectors without overlapping therapeutic claims.
| Leading Market Players |
|---|
| Gilead Sciences Inc |
| Sanofi S.A |
| Intercept Pharmaceuticals Inc |
| Immuron Limited |
| Generon Pharmaceutical Technology Company Limited |
| DURECT Corporation |
| Conatus Pharmaceuticals Inc |
| Madrigal Pharmaceuticals Inc |
| CymaBay Therapeutics Inc |
| Others |
Cost & Logistics Intelligence
FDA Breakthrough Therapy Designation gates both supply qualification and price differentiation simultaneously, requiring manufacturers to front-load biomarker validation and adaptive trial infrastructure before commanding premium positioning for severe alcoholic hepatitis candidates.
Pricing Analysis
Long-term offtake agreements with designated transplant centers anchor pricing for corticosteroid alternatives, while spot purchasing dominates antioxidant combinations for mild-to-moderate segments. Price differentiation rests on certification tier—FDA breakthrough versus standard approval—and volume scale through centralized hospital procurement committees. Cost compression in oral maintenance tiers is intensifying because Indian and Chinese API sourcing expands generic competition. Community hepatology practices exhibit highest price sensitivity; academic medical centers with transplant capabilities demonstrate lowest.
Supply Chain Analysis
Inventory lead times for parenteral corticosteroid formulations stretch across North Carolina, Bavaria, and Osaka prefecture where aseptic fill-finish capacity concentrates. Raw material dependencies include plasma-derived albumin, phosphodiesterase inhibitors, and botanical extracts from Italian and Spanish silymarin suppliers. Single-source vulnerability in plasma fractionation creates formulation bottlenecks for combination therapies. Distribution runs through direct manufacturer-tertiary center negotiations bypassing traditional group purchasing organization intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as diagnostic substitution with transient elastography fragments traditional severity-based case definitions, creating niche positioning for biomarker-qualified therapies outside histologically-confirmed eligibility.
For Market Incumbents: Fortify centralized hospital contracting relationships against emerging telehepatology channel expansion by embedding clinical decision support tools within electronic health record systems. Deepen backward integration into plasma-derived biologics supply to insulate against albumin formulation bottlenecks threatening combination therapy launches. For New Entrants and Emerging Players: Differentiate on AI-driven patient stratification platforms that identify treatment-responsive subpopulations invisible to conventional MELD scoring. Target mild-to-moderate alcoholic hepatitis segments where antioxidant combinations face less entrenched corticosteroid competition and outpatient management protocols expand addressable volume. Deploy telehepatology partnerships to extend prescriber reach beyond traditional tertiary center catchments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across adaptive trial infrastructure and real-time biomarker monitoring platforms. Long-term viability favors developers with qualified surrogate endpoints enabling smaller, faster trials. Acquisition target archetype: mid-cap biopharmaceuticals with NASH-to-ASH pipeline adjacencies and existing cytokine modulator validation. Watch FDA biomarker qualification decisions as inflection signal for trial cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Qualification Pathway | FDA acceptance of liver function surrogates reduces Phase III enrollment requirements for severe alcoholic hepatitis candidates. |
| Centralized Hospital Contracting | Direct negotiations with designated transplant centers in Houston and Heidelberg bypass group purchasing organization intermediaries. |
| Telehepatology Platform Integration | Remote specialist consultation extends prescriber reach for maintenance therapies into rural health system catchments. |
| NASH-to-ASH Pipeline Repositioning | Fibroblast activation protein inhibitors validated in non-alcoholic steatohepatitis trials compress development paths toward alcoholic hepatitis. |
| Plasma-Derived Supply Security | Backward integration into albumin fractionation insulates against input volatility threatening combination therapy formulations. |
Research Approach
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and secondary sources including FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchors the qualitative findings. Bottom-up patient flow modeling and top-down healthcare expenditure triangulation reconcile volume estimates across the analysis window.
Sensitivity analysis around biomarker adoption rates and diagnostic substitution timelines shapes the analytical framework. Segmentation dimensions include pharmacological class, disease severity tier, administration route, and regional regulatory cluster. CAGRs derive from patient population projections, treatment penetration curves, and pricing trajectory assumptions. Forecast inputs incorporate hepatology specialist workforce constraints and evolving payer evidence requirements for combination regimens.
The analysis sits within stated boundaries; outcomes outside sustained FDA breakthrough therapy designation momentum or accelerated EMA conditional approval pathways would require recalibration. Forecasts reflect documented assumptions regarding biomarker qualification timelines and plasma supply stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Frontotemporal Dementia Management Market
Specialty Medicine
Dementia Management Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Rhabdomyosarcoma Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Global Constipation Treatment Market