
 Complement 3 Glomerulopathy (C3G) Market | 2026-2036
Complement 3 Glomerulopathy (C3G) Market Size, Share, and Industry Trends Forecast 2026-2036
Complement 3 Glomerulopathy (C3G) Market Outlook
The specialty pharmacy channel is narrowing around a handful of complement-focused distributors with cold-chain capabilities for biologic infusion. Omeros Corporation leverages its proprietary antibody platform to sustain development of C5-targeted interventions. Alexion Pharmaceuticals anchors its position through deep expertise in complement-mediated diseases. Amyndas Pharmaceuticals SA differentiates via peptide-based C3 inhibitors designed for improved renal targeting.
Complement 3 Glomerulopathy represents a rare, progressive renal disorder driven by dysregulated alternative complement pathway activation, characterized by C3-dominant immune complex deposition on glomerular basement membranes. The condition destroys filtration function and frequently advances to end-stage renal disease without targeted intervention. Monoclonal antibodies command the therapeutic frontier, with biologics capturing concentrated investment as developers pursue durable complement blockade. Small molecules occupy an emerging niche, offering oral bioavailability that could reshape patient compliance outside infusion centers.
The FDA orphan drug program shapes clinical trial economics through tax credits and market exclusivity provisions for C3G indications. EMA's rare disease framework and Japan's PMDA sakigake designation collectively establish multi-regional regulatory momentum for complement therapeutics. Stakeholders must monitor biomarker qualification progress, as validated surrogate endpoints will determine whether regulators accept accelerated approval pathways for novel C3G interventions.
Market Dynamics
The orphan drug designation pathway is compressing clinical development timelines for complement-targeted therapies, while specialized nephrology centers concentrate demand around academic medical hubs with biopsy-proven diagnostic capabilities.
Growth Catalysts
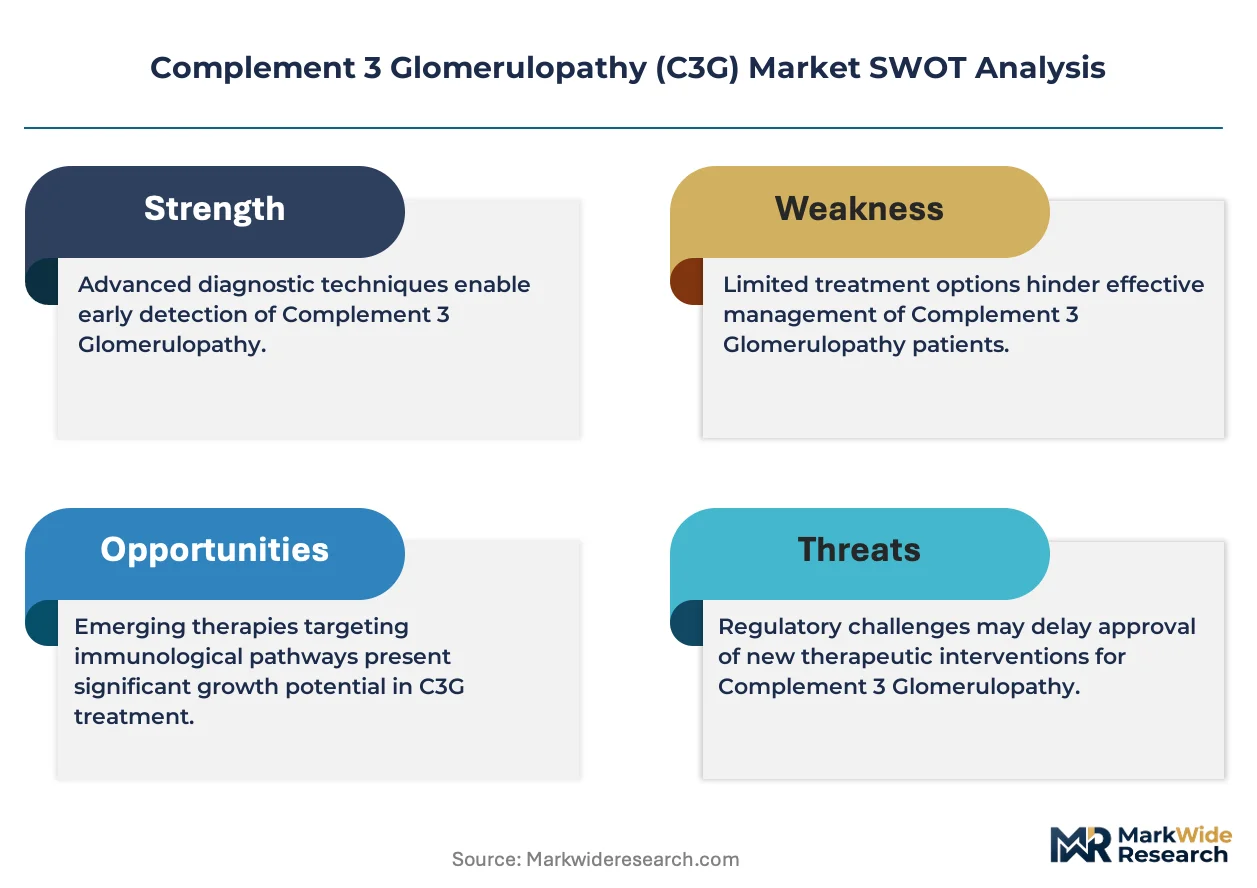
- FDA orphan drug tax credits:The incentive structure reduces clinical trial costs for developers pursuing rare renal indications, accelerating pipeline progression.
- Biomarker qualification progress:Validated surrogate endpoints for C3G are enabling accelerated approval pathways that compress regulatory review timelines.
- Academic medical hub clustering:Specialized glomerular disease centers in Boston, London, and Tokyo concentrate patient recruitment and specialist expertise.
Market Restraints
- Cold-chain biologic distribution:Complement-targeted antibodies require temperature-controlled logistics that limit pharmacy network expansion.
- Diagnostic complexity:Electron microscopy and C3 staining protocols create bottlenecks at pathology laboratories, delaying treatment initiation.
- Reimbursement uncertainty:Payers in Germany and France apply distinct rare disease funding mechanisms that fragment market access.
Strategic Opportunities
- Oral small molecule development:Bioavailable C3 inhibitors could shift treatment delivery from infusion centers to community nephrology practices.
- Japan's PMDA sakigake designation:The priority review framework offers expedited access for first-in-class complement therapeutics.
- Home infusion services:Specialty pharmacy networks are building nurse-administered delivery capabilities that bypass hospital-based administration.
Industry Challenges
- Nephrology fellowship pipeline:The shortage of glomerular disease specialists limits clinical trial site activation and patient identification.
- Companion diagnostic co-development:Aligning biomarker assays with therapeutic submissions creates regulatory coordination complexity across FDA and EMA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Complement 3 Glomerulopathy (C3G) Market |
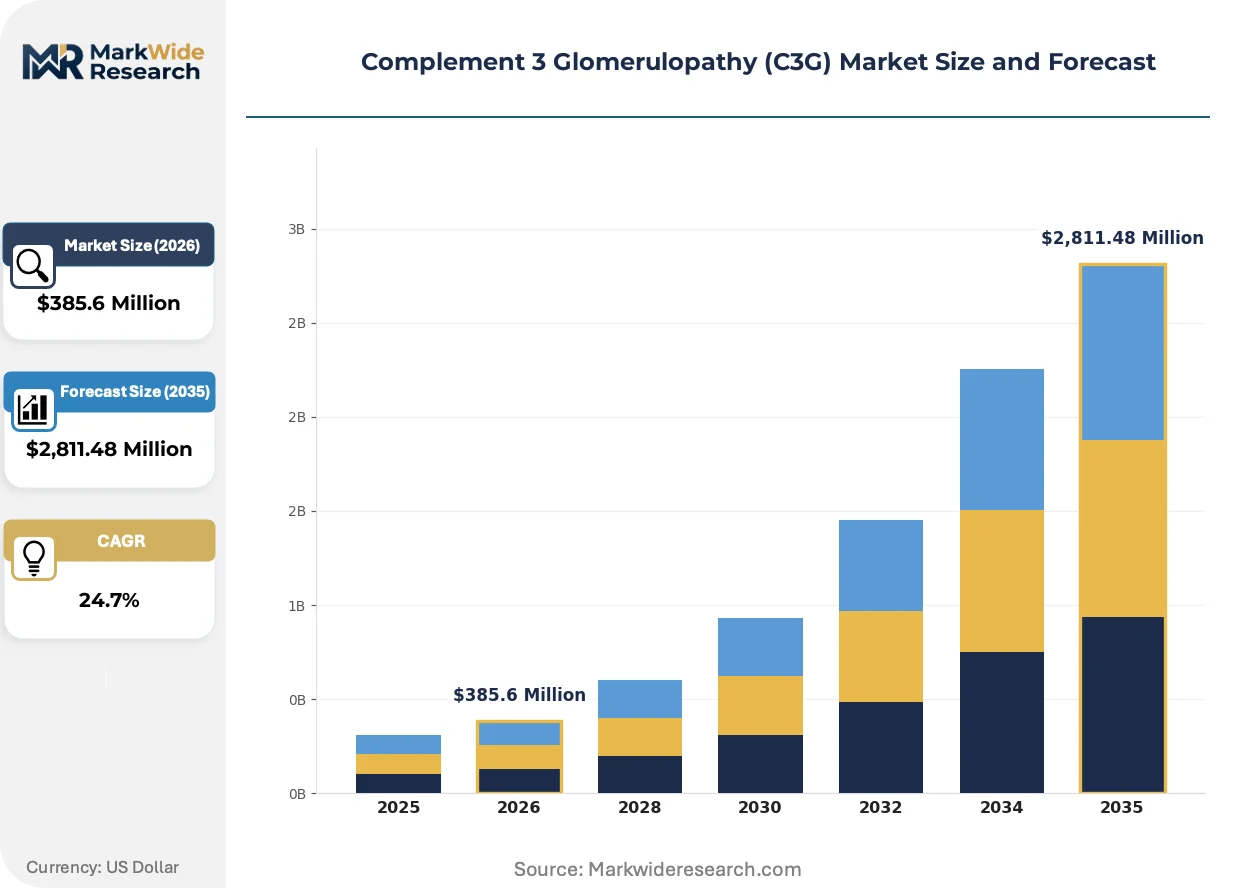
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $2,811.48 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Immunology, Nephrology, Hematology, Urology Delivery Mode: Injectable, Oral, Intravenous, Subcutaneous End User: Hospitals, Clinics, Laboratories, Homecare Product Type: Monoclonal Antibodies, Small Molecules, Biologics, Biosimilars |
| Companies Covered | Omeros Corporation, Boehringer Ingelheim International GmbH, Alexion Pharmaceuticals, Sobi, Amyndas Pharmaceuticals SA, Apellis Pharmaceuticals, Amgen, Kira Pharmaceuticals, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Complement 3 Glomerulopathy (C3G) Market Strategic Shifts
Complement therapeutics are diverging toward modular platform technologies that enable rapid target switching, while regulatory frameworks coalesce around biomarker-driven approval pathways that reward diagnostic-therapeutic pairing.
Peptide-based C3 inhibitors are achieving improved renal targeting through molecular weight optimization and charge modification. Hospital-based nephrology departments in the United States and Germany are piloting these agents in biopsy-confirmed cases. This modality is virtualizing the traditional monoclonal antibody development timeline by enabling oral delivery and reduced immunogenicity risk.
EMA's rare disease framework now mandates pediatric investigation plans for novel complement therapeutics, forcing developers to establish juvenile dosing protocols earlier in development. The requirement compresses timeline flexibility but expands addressable patient populations. European reference networks for rare renal diseases are coordinating multi-site trials to meet these standards.
Patient advocacy organizations are consolidating procurement influence through managed access programs that negotiate pre-approval supply agreements. These arrangements displace traditional physician-led prescribing in France and Italy. The shift concentrates volume through single-payer negotiations that demand outcomes-based continuation criteria.
Complement 3 Glomerulopathy (C3G) Market Segmentation
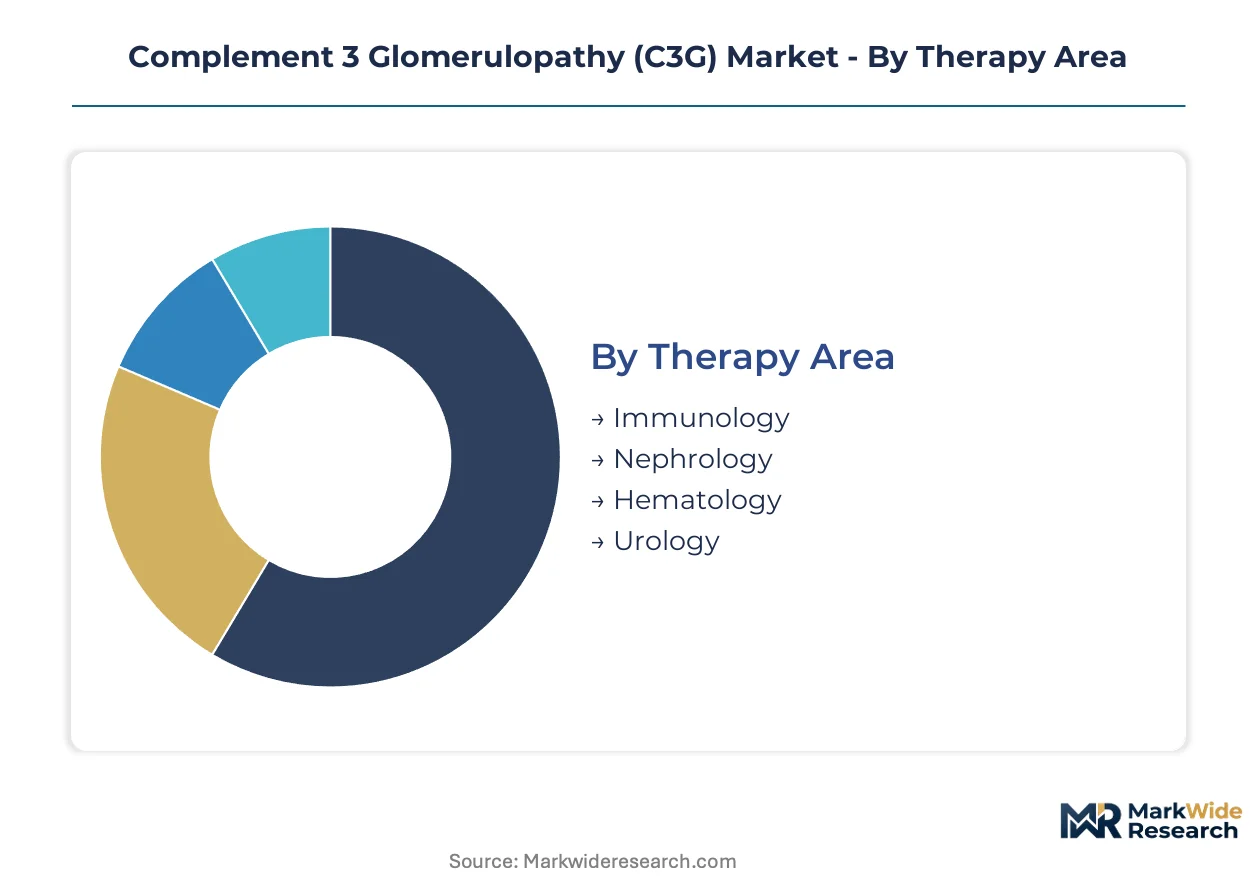
C3G therapeutic development spans multiple clinical disciplines and delivery technologies, with segmentation revealing where complement-targeted investments concentrate. Understanding these divisions exposes which patient access pathways and regulatory frameworks shape commercial viability.
Therapy Area:
The use-case spectrum stretches from primary renal intervention to systemic complement modulation across immune-mediated conditions.
- Immunology:Systemic complement dysregulation drives investment in broad-spectrum C3 inhibitors for multi-organ autoimmune contexts. Demand clusters in academic medical centers with integrated rheumatology-nephrology services.
- Nephrology:Glomerular disease specialists anchor the core indication, with biopsy-confirmed C3G cases requiring targeted alternative pathway blockade. FDA orphan drug designations concentrate here.
- Hematology:Paroxysmal nocturnal hemoglobinuria and atypical hemolytic uremic syndrome represent adjacent indications with shared complement biology. Cross-specialty prescribing expands addressable populations.
- Urology:Lower urinary tract manifestations of complement activation occupy an emerging niche with limited clinical validation.
Established volume favors Nephrology; emerging adoption favors Immunology.
Delivery Mode:
Cost tier differentiation separates hospital-based infusion from community-accessible oral alternatives.
- Injectable:Intramuscular and depot formulations enable less frequent administration than intravenous equivalents. Cold-chain requirements limit distribution to specialty pharmacy networks.
- Oral:Small molecule C3 inhibitors promise patient self-administration outside infusion centers. Amyndas Pharmaceuticals and competitors prioritize bioavailability optimization for renal targeting.
- Intravenous:Monoclonal antibodies dominate current clinical practice, requiring hospital-based administration with specialist monitoring. EMA's rare disease framework mandates pediatric protocols for this modality.
- Subcutaneous:Home administration with nurse support is gaining traction through specialty pharmacy services in the United States and Germany.
Intravenous commands current revenue; subcutaneous and oral modalities are climbing the fastest.
End User:
Customer type segmentation tracks the shift from institutional diagnosis toward distributed care models.
- Hospitals:Academic medical hubs with electron microscopy capabilities anchor definitive diagnosis and first-line biologic therapy. Boston, London, and Tokyo clusters concentrate trial recruitment.
- Clinics:Community nephrology practices await oral alternatives to expand prescribing authority beyond referral centers.
- Laboratories:Pathology services with C3 staining and complement factor H mutation testing create diagnostic bottlenecks that delay treatment initiation.
- Homecare:Nurse-administered infusion services bypass hospital capacity constraints, with specialty pharmacy networks building cold-chain logistics for biologic delivery.
Hospitals retain diagnostic control; homecare services are gaining share fastest.
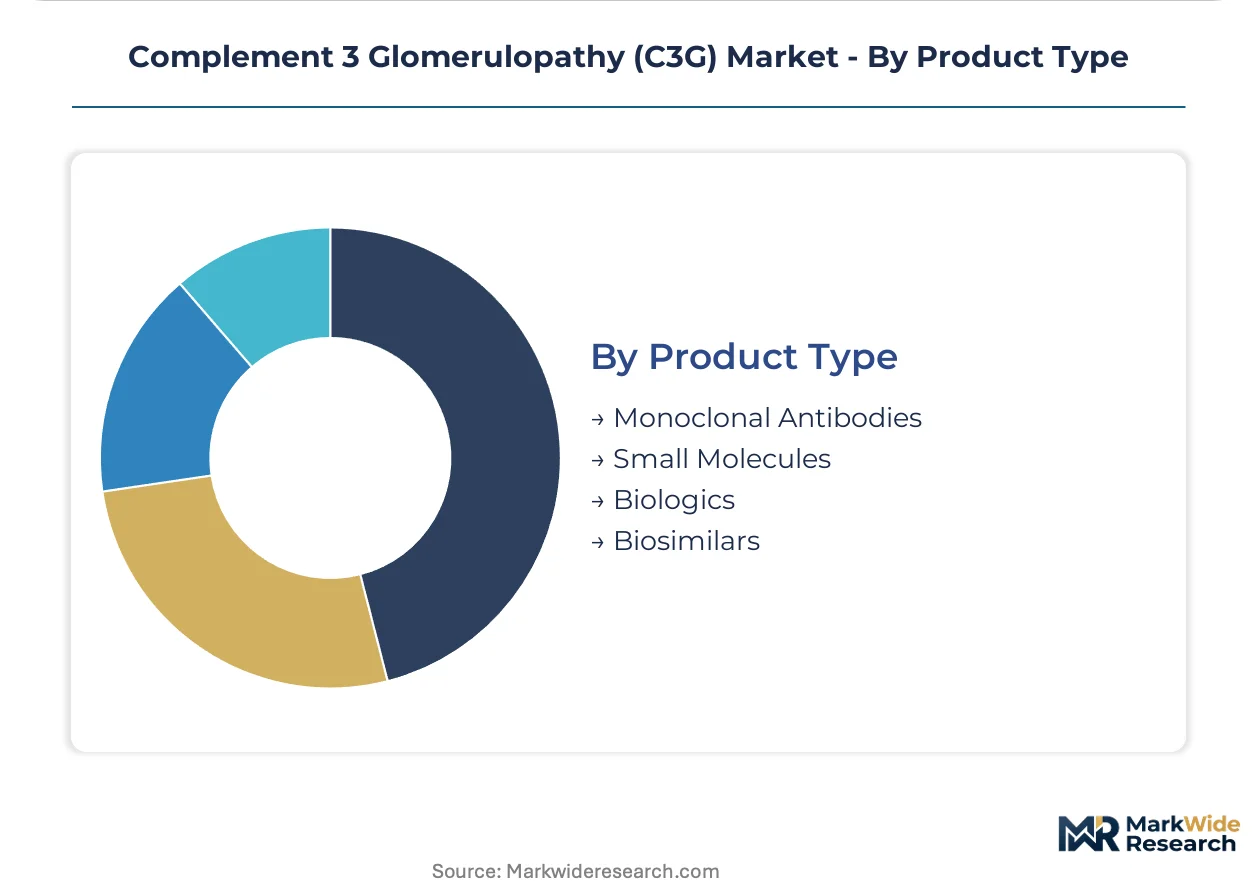
Product Type:
Technology maturity separates validated biologics from emerging small molecule platforms.
- Monoclonal Antibodies:C5-targeted agents from Alexion and competitors command established reimbursement with proven efficacy in complement-mediated diseases. Manufacturing complexity sustains premium pricing.
- Small Molecules:Peptide-based C3 inhibitors enable oral delivery with reduced immunogenicity risk. Amyndas Pharmaceuticals leads renal targeting optimization through molecular weight modification.
- Biologics:Recombinant complement regulators and fusion proteins occupy a middle tier with modular platform potential for rapid target switching.
- Biosimilars:Follow-on biologics remain pre-commercial for rare complement indications, with reference product exclusivity and complex immunogenicity assessment delaying entry.
Monoclonal antibodies dominate current value; small molecules represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug tax credits and EMA rare disease frameworks are compressing clinical timelines and concentrating investment in jurisdictions with established regulatory pathways for complement therapeutics.
United States
Academic medical hubs in Boston and New York anchor biopsy-confirmed diagnosis and first-line biologic therapy. The FDA's orphan drug designation pathway accelerates development through tax credits and market exclusivity provisions. Specialized glomerular disease centers cluster around Massachusetts General Hospital and Columbia University Irving Medical Center, driving patient recruitment for complement-targeted trials.
Germany
Reference networks for rare renal diseases coordinate multi-site trials across university hospitals in Berlin and Heidelberg. EMA's rare disease framework mandates pediatric investigation plans, forcing earlier juvenile dosing protocol establishment. The country's pathology laboratories with electron microscopy capabilities create diagnostic bottlenecks that delay treatment initiation in Bavaria and North Rhine-Westphalia.
Japan
PMDA's sakigake designation offers priority review for first-in-class complement therapeutics, attracting developers seeking expedited market access. Tokyo's glomerular disease specialists concentrate demand at Keio University Hospital and Tokyo Medical and Dental University. The country's aging nephrology workforce limits clinical trial site activation despite strong regulatory incentives.
United Kingdom
NHS England's specialized commissioning framework concentrates C3G treatment at designated renal centers in London and Manchester. The MHRA operates under EMA-aligned rare disease protocols while maintaining independent accelerated assessment pathways. Cambridge and Oxford academic hospitals host complement biology research programs that feed into clinical development pipelines.
France
ANSM's early access programs enable pre-approval supply agreements negotiated through patient advocacy consolidation. Parisian academic hospitals with integrated rheumatology-nephrology services anchor systemic complement modulation demand. The country's outcomes-based continuation criteria for rare disease funding create reimbursement complexity that fragments market access.
Complement 3 Glomerulopathy (C3G) Market Competitive Environment
On the supply side, the industry is consolidating around biologic platform specialists with established complement expertise and emerging peptide developers pursuing oral delivery differentiation. Large-cap pharmaceutical companies anchor the premium tier through acquisition-led portfolio expansion. Mid-cap biotech firms occupy the innovation tier with modular antibody technologies. Strategic moves center on diagnostic-therapeutic pairing and pediatric protocol co-development with European reference networks.
Within the complement platform archetype, Omeros Corporation and Alexion Pharmaceuticals exemplify established biologic developers with deep disease area expertise. Amyndas Pharmaceuticals SA occupies a distinct position among peptide-based specialists targeting improved renal bioavailability. These three entities represent the strategic spectrum from antibody-dependent infusion therapies to small molecule oral alternatives that could reshape patient compliance outside hospital settings.
| Leading Market Players |
|---|
| Omeros Corporation |
| Boehringer Ingelheim International GmbH |
| Alexion Pharmaceuticals |
| Sobi |
| Amyndas Pharmaceuticals SA |
| Apellis Pharmaceuticals |
| Amgen |
| Kira Pharmaceuticals |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Cold-chain logistics corridors connecting Boston to European distribution hubs dictate cost structures that amplify supply concentration effects. Biologic infusion therapies for C3G command premium positioning where temperature-controlled freight and specialized handling create natural price stratification between hospital-based and community delivery models.
Pricing Analysis
Certification level creates the primary spread, with FDA orphan-designated biologics anchoring premium tiers against emerging oral alternatives. Pricing stratifies across infusion-center administration, home-based nurse delivery, and prospective self-administered oral formats. Cost compression in standard-tier biologics is intensifying as peptide-based competitors advance renal-targeting claims. Academic medical centers exhibit lowest price sensitivity due to bundled reimbursement, while community nephrology practices await oral formulations to unlock prescribing authority.
Supply Chain Analysis
Lonza and Catalent hold contract manufacturing capacity for complement-targeted monoclonal antibodies, with Samsung Biologics expanding bioreactor footprint. Manufacturing concentrates in Switzerland, Singapore, and South Korea for fill-finish operations. Production draws from Chinese Hamster Ovary cell lines, single-use bioreactor systems, and affinity chromatography resins. Single-source vulnerability in C1 esterase inhibitor supply creates formulation bottlenecks. Distribution runs through specialty pharmacy networks with nurse-administered cold-chain delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized glomerular disease expertise represents the constraining asset, with fellowship-trained nephrologists concentrated at fewer than fifty academic centers worldwide. Pipeline progression depends on securing clinical trial access at these bottleneck sites.
For Market Incumbents: Harden diagnostic-therapeutic pairing through exclusive pathology laboratory partnerships that lock in biopsy referral flows. Deepen complement biology platforms with modular antibody technologies enabling rapid target switching against emerging peptide threats. Vertical integration into companion diagnostic co-development secures regulatory coordination advantages across FDA and EMA review pathways. For New Entrants and Emerging Players: Community nephrology practices in Germany's North Rhine-Westphalia and France's regional hospital networks represent the most penetrable entry point for oral C3 inhibitor formulations. Home infusion services in the United States offer secondary white-space for subcutaneous delivery modalities bypassing hospital capacity constraints. Outcomes-based contracting with single-payer systems anchors market access negotiations. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical divestitures of rare disease assets lacking complement platform integration. Long-term viability hinges on biomarker qualification progress enabling accelerated approval pathways. Watch FDA breakthrough therapy designation grants to peptide-based developers as inflection signal for oral modality disruption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Aligns C3 staining assays with therapeutic submissions to secure FDA biomarker qualification. |
| Pediatric Investigation Plan Filing | Meets EMA rare disease framework mandates to expand addressable patient populations. |
| Specialty Pharmacy Network Expansion | Builds cold-chain nurse-administered capabilities that bypass hospital infusion bottlenecks. |
| Oral Bioavailability Optimization | Shifts treatment delivery from academic centers to community nephrology practices. |
| Managed Access Program Negotiation | Consolidates procurement influence through patient advocacy pre-approval supply agreements. |
Study Parameters
Operator-level perspectives from nephrology department heads, specialty pharmacy distribution directors, regulatory affairs leads at complement-focused developers, and payer access specialists anchored the qualitative base. Primary interviews triangulated against FDA orphan drug designation filings, EMA rare disease framework submissions, ClinicalTrials.gov protocol registries, and European reference network coordination documents. Bottom-up patient population estimates and top-down therapeutic category spending assessments converged through iterative validation.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing around biomarker qualification timelines and pediatric protocol enrollment rates. Segmentation dimensions modeled include therapy area specialization, delivery mode infrastructure requirements, end-user facility type, and regional regulatory cluster. CAGRs derived from patient prevalence projections, treatment penetration assumptions, and pricing evolution by modality. Forecast inputs incorporated nephrology fellowship pipeline constraints and pathology laboratory capacity expansion plans.
Macroeconomic conditions sit as an overlay; deviation in biologic reimbursement policy, rare disease funding allocations, or cold-chain logistics costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway approvals and diagnostic adoption curves. Quarterly review of FDA breakthrough therapy designations, EMA pediatric investigation plan acceptances, and specialty pharmacy network expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Lipoprotein Metabolism Disorders Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Immunology Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
ADHD Therapeutics Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Ankylosing Spondylitis Market