
 Frontotemporal Dementia Management Market | 2026-2036
Frontotemporal Dementia Management Market Size, Share, and Industry Trends Forecast 2026-2036
Frontotemporal Dementia Management Market Foresight
Subscription-based disease monitoring platforms is expanding how pharmaceutical and device manufacturers monetize longitudinal patient relationships beyond one-time prescriptions. Alector leverages biomarker-driven trial designs to anchor its early-stage pipeline credibility among investigators. GSK sustains broad neurology infrastructure that competes across multiple neurodegenerative indications simultaneously. Denali Therapeutics specializes in blood-brain barrier platform technology that differentiates its delivery approach from conventional systemic administration.
Frontotemporal dementia management encompasses multidisciplinary interventions targeting behavioral variant and language variant subtypes of this tau- and TDP-43-proteinopathy, typically involving cholinesterase inhibitors, selective serotonin reuptake inhibitors, and structured caregiver training protocols. Pharmacological therapies occupy the largest current revenue pool given limited disease-modifying alternatives, while telehealth platforms represent the fastest-expanding deployment channel as remote cognitive assessment tools achieve regulatory validation. Behavioral interventions command premium reimbursement where specialized dementia care certification exists, though cognitive enhancers face margin compression from generic substitution patterns.
The FDA and EMA maintain divergent evidentiary standards for surrogate endpoints in neurodegenerative trials, complicating parallel development strategies for sponsors targeting both jurisdictions. HIPAA constraints on digital biomarker collection shape how telehealth platforms architect data flows across hospital-based and home healthcare settings. Stakeholders must monitor how CMS coverage determinations for novel diagnostics redistribute patient volume across neurology clinics and community care settings.
Market Dynamics
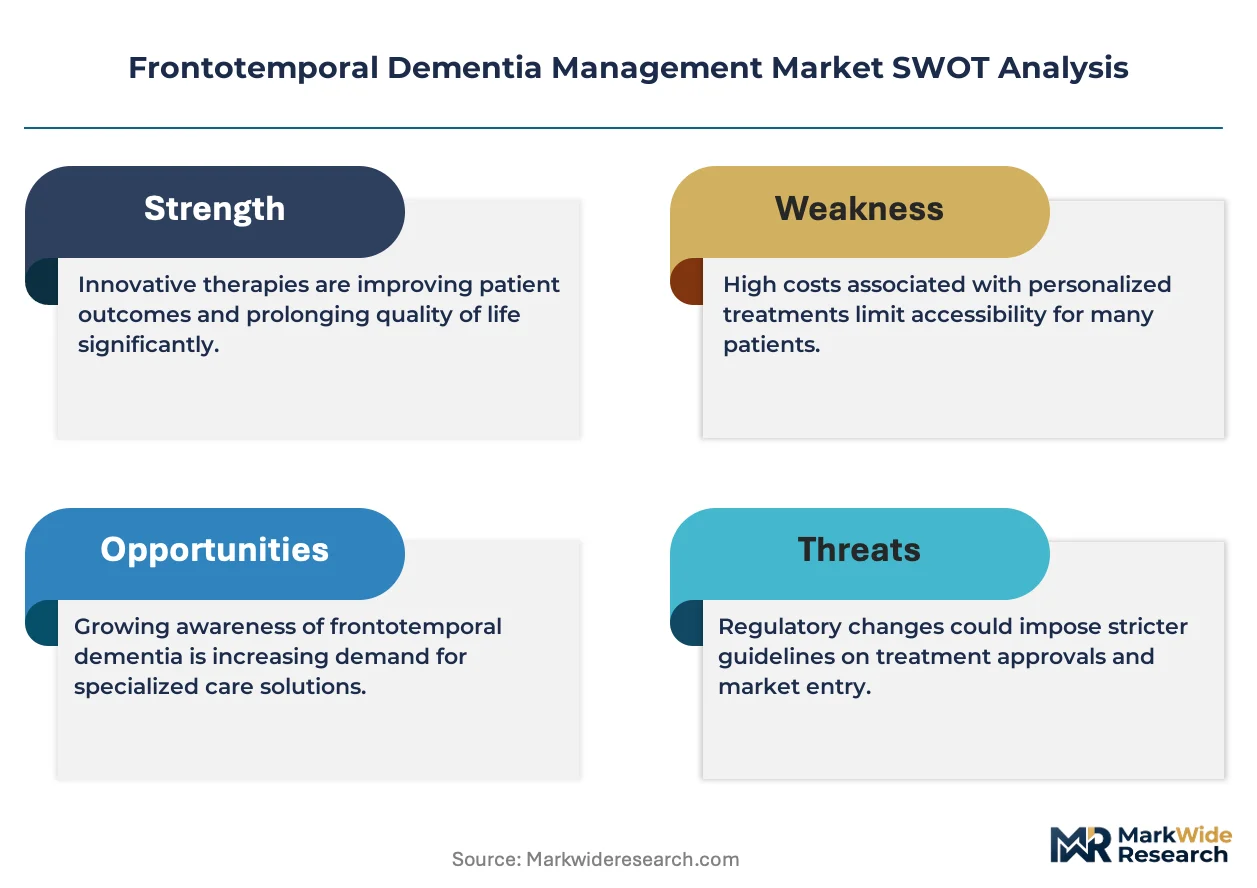
Accelerated FDA approval pathways for neurodegenerative therapies are compressing development timelines while forcing sponsors to build post-market evidence generation infrastructure earlier in the product lifecycle. This structural pressure is reshaping how clinical trial designs incorporate biomarker endpoints and how commercial teams prepare for conditional launches.
Growth Catalysts
- Biomarker-driven trial designs:Regulatory acceptance of tau and TDP-43 protein markers by the FDA is enabling smaller, faster efficacy studies that reduce enrollment burdens for rare dementia subtypes.
- Neurology clinic specialization:Academic medical centers in the United States are establishing dedicated frontotemporal dementia diagnostic protocols that standardize referral pathways and concentrate treatment-ready patient pools.
- Telehealth platform validation:Remote cognitive assessment tools achieving HIPAA-compliant data architectures are expanding addressable patient populations beyond urban hospital catchment areas.
Market Restraints
- Generic substitution pressure:Cholinesterase inhibitors facing patent expiration are compressing margins for symptomatic therapy portfolios across community pharmacy channels.
- Diagnostic specialist concentration:Accurate bvFTD and svPPA differentiation requires neurologist expertise concentrated in fewer than 200 US academic centers, creating access bottlenecks.
- EMA-FDA endpoint divergence:Divergent evidentiary standards for surrogate markers complicate parallel development strategies and force sponsors to run separate trials for European market access.
Strategic Opportunities
- Subscription monitoring models:Pharmaceutical manufacturers are monetizing longitudinal patient relationships through digital biomarker platforms that extend revenue beyond one-time prescriptions.
- Blood-brain barrier delivery platforms:Engineered transport technologies enabling targeted central nervous system drug delivery represent white space distinct from systemic administration approaches.
- Caregiver training certification:Structured behavioral intervention protocols achieving specialized dementia care reimbursement codes command premium pricing in Medicare Advantage networks.
Industry Challenges
- Neurodegenerative trialist scarcity:Investigators with frontotemporal dementia-specific recruitment experience are concentrated at a handful of US academic sites, stretching site activation timelines.
- Digital biomarker integration:Telehealth platforms face technical complexity embedding FDA-validated cognitive instruments into existing electronic health record workflows without disrupting clinical operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frontotemporal Dementia Management Market |
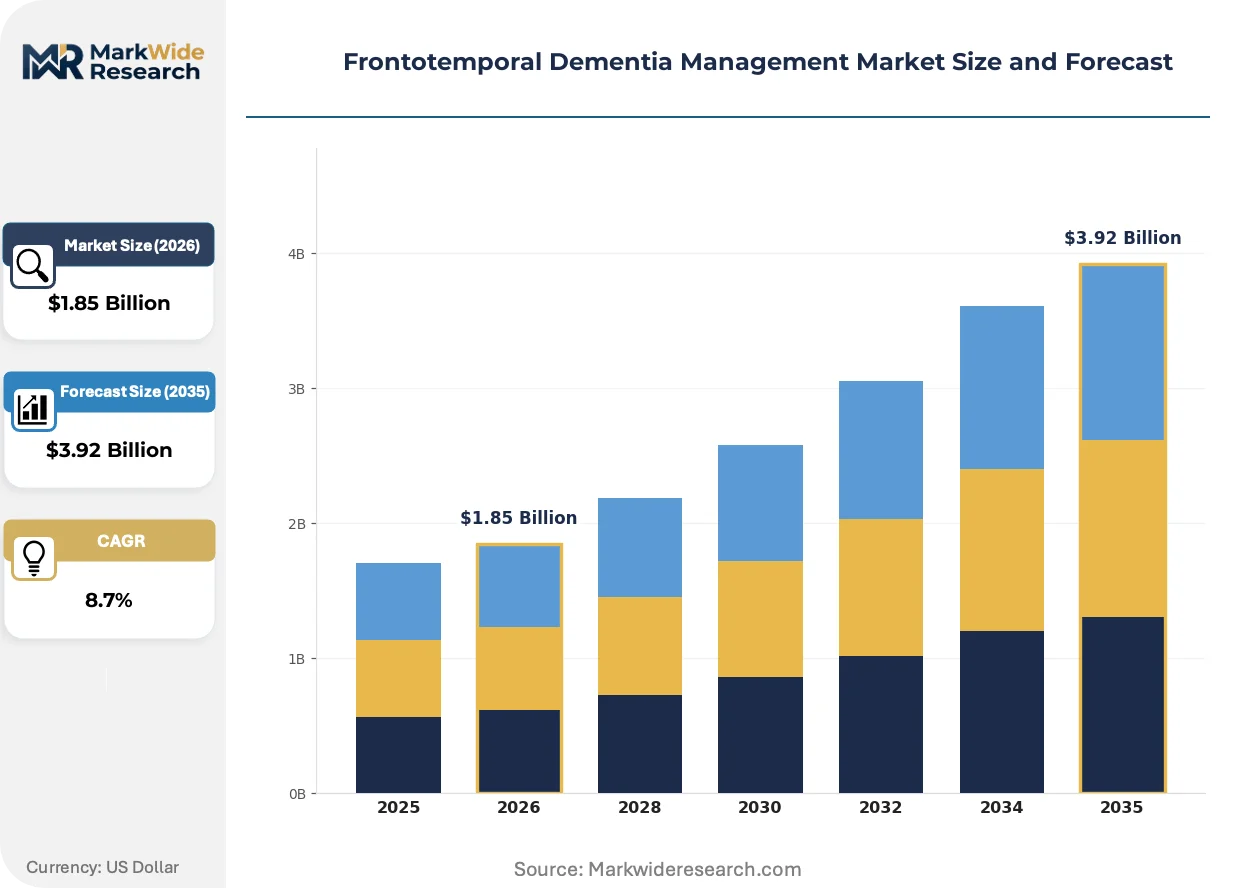
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmacological Therapies, Cognitive Enhancers, Antidepressants, Anxiolytics, Supportive Devices, Behavioral Interventions Application: Symptom Management, Disease Monitoring, Behavioral Control, Cognitive Rehabilitation, Caregiver Support End User: Neurology Clinics, Specialized Centers, Research Institutes, Care Facilities Deployment: Hospital-Based Services, Outpatient Clinics, Home Healthcare, Telehealth Platforms, Community Care Settings |
| Companies Covered | F. Hoffmann-La Roche Ltd., Alector, GSK, Astellas Pharma, Passage Bio, Denali Therapeutics, CervoMed, AviadoBio, NKGen Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frontotemporal Dementia Management Market Shifts & Advancements
Digital health infrastructure is actively redrawing how frontotemporal dementia care is delivered, monitored, and reimbursed across institutional and home-based settings. Three converging developments are restructuring competitive positioning and value capture mechanisms.
Remote cognitive assessment technology is decentralizing the locus of diagnostic evaluation from hospital-based memory clinics to patient homes. Neurology departments at academic medical centers are deploying tablet-based neuropsychological batteries that match in-person sensitivity for executive function measurement. This shift is compressing geographic barriers to specialist access while generating continuous data streams that pharmaceutical sponsors increasingly require for post-market commitment studies.
The FDA's accelerated approval pathway for neurodegenerative diseases is conditioning market entry on robust post-approval confirmatory trial infrastructure. Sponsors must now build patient registries and digital biomarker collection systems prior to launch rather than retrofitting evidence platforms after approval. Early-stage biotechnology developers are responding by embedding prospective real-world evidence architectures into phase 2 protocols.
Specialized dementia care certification is reshaping how behavioral interventions achieve reimbursement separation from generic psychiatric services. Medicare Advantage plans in California, Massachusetts, and Pennsylvania are piloting tiered provider networks that direct higher acuity bvFTD patients to certified care managers. This channel preference is forcing community neurology practices to pursue workforce training investments or risk patient volume diversion to academic center networks.
Frontotemporal Dementia Management Market Segmentation
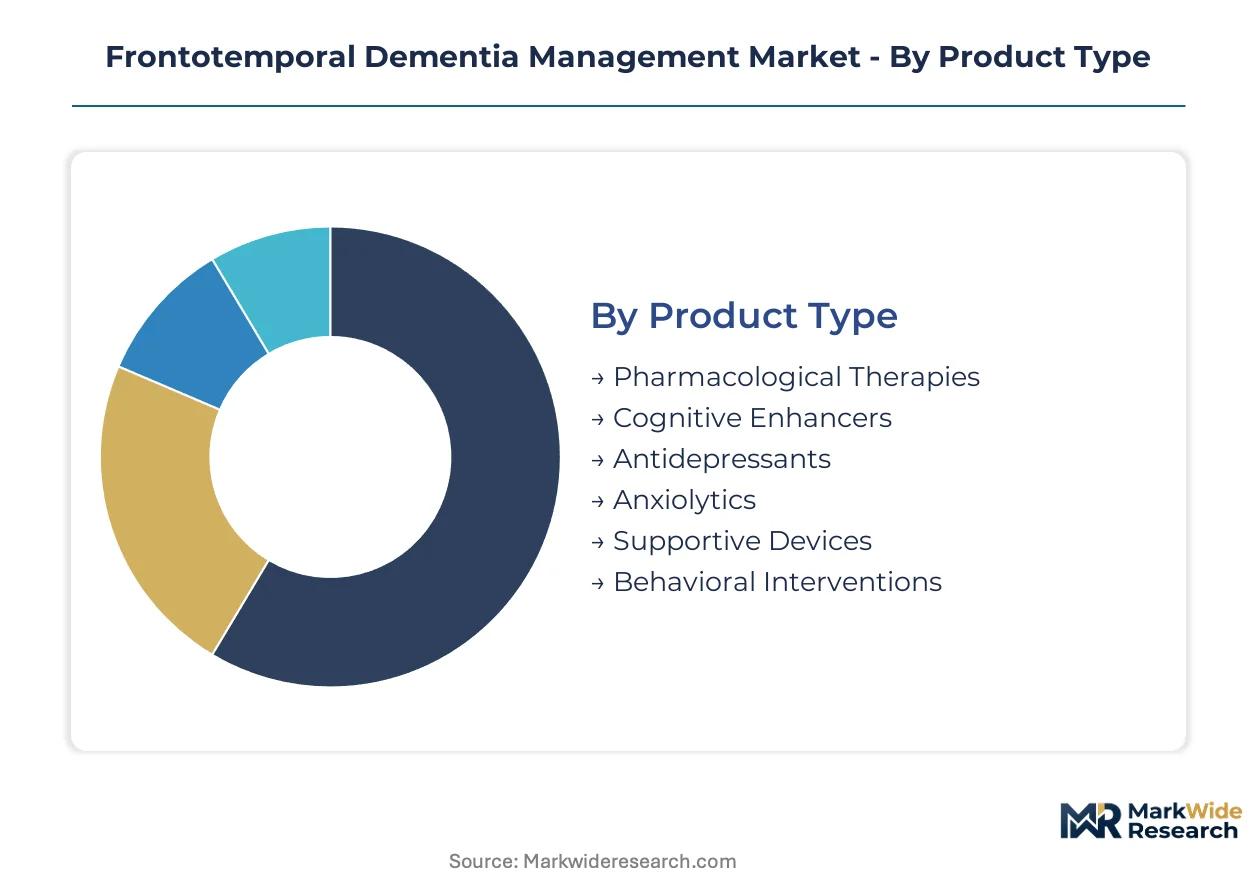
Segmentation in frontotemporal dementia management reflects how heterogeneous patient presentations—behavioral variant versus language variant subtypes—demand differentiated therapeutic approaches. Treatment pathways diverge based on whether the primary intervention targets tau pathology, TDP-43 proteinopathy, or downstream symptomatic manifestations.
Product Type:
Cost tier separates segments here, with disease-modifying candidates commanding development investment despite clinical uncertainty while symptomatic agents face generic compression.
- Pharmacological Therapies:Cholinesterase inhibitors and NMDA receptor antagonists constitute the current revenue foundation, though patent expirations are eroding margins across community pharmacy channels. Demand concentrates in Medicare Part D formularies where prior authorization requirements favor established agents over experimental protocols.
- Behavioral Interventions:Structured caregiver training and environmental modification protocols achieve premium reimbursement where specialized dementia care certification exists, particularly within Medicare Advantage networks in California and Massachusetts. Academic medical centers in Philadelphia and Boston are piloting bundled payment models that separate certified behavioral management from generic psychiatric services.
- Cognitive Enhancers:Off-label stimulant and nootropic use persists in academic center practices despite limited FDA validation for FTD-specific cognitive decline.
- Antidepressants:Selective serotonin reuptake inhibitors address disinhibition and compulsive behaviors in bvFTD patients through modulation of frontal lobe serotonergic pathways.
- Anxiolytics:Short-acting benzodiazepines and buspirone manage anxiety manifestations in language variant subtypes where behavioral disturbance is less prominent.
- Supportive Devices:Communication aids and safety monitoring technologies extend independent living duration for svPPA patients experiencing progressive anomia.
Pharmacological therapies lead volumes today; behavioral interventions are gaining share fastest as reimbursement codes for specialized dementia care achieve broader carrier adoption.
Application:
Application segmentation tracks how FTD management responsibilities distribute across the disease trajectory from first symptom recognition through advanced care.
- Symptom Management:Frontline interventions targeting executive dysfunction, apathy, and language impairment constitute the immediate clinical priority upon diagnostic confirmation. Neurology clinics at University of California San Francisco and Mayo Clinic Rochester anchor prescriptive volume for symptomatic protocols.
- Disease Monitoring:Longitudinal biomarker tracking and neuropsychological surveillance enable treatment adjustment and clinical trial eligibility determination. Subscription-based digital platforms from pharmaceutical sponsors are expanding how manufacturers monetize continuous patient relationships beyond one-time prescriptions.
- Behavioral Control:Non-pharmacological strategies for disinhibition and compulsive eating address the most distressing bvFTD manifestations for family caregivers.
- Cognitive Rehabilitation:Speech-language pathology and occupational therapy interventions attempt to preserve functional communication in svPPA and nfvPPA subtypes.
- Caregiver Support:Psychoeducation and respite services reduce institutionalization pressure by extending home-based care viability.
Symptom management dominates current expenditure; disease monitoring is expanding most quickly as remote assessment technologies achieve HIPAA-compliant validation.
End User:
Customer type here reflects how diagnostic complexity and treatment specialization concentrate in institutional settings with specific workforce capabilities.
- Neurology Clinics:Academic medical centers with dedicated cognitive and behavioral neurology divisions establish diagnostic protocols that standardize referral pathways and concentrate treatment-ready patient pools. Cleveland Clinic, Johns Hopkins, and Columbia University Irving Medical Center anchor US diagnostic volume.
- Specialized Centers:FTD-specific care programs at Massachusetts General Hospital and University of Pennsylvania integrate multidisciplinary teams spanning neurology, psychiatry, and genetic counseling.
- Research Institutes:NIH-funded Alzheimer's Disease Research Centers at University of California Los Angeles and University of Texas Southwestern drive biomarker discovery and therapeutic trial enrollment.
- Care Facilities:Memory care units with FTD-specific staff training manage advanced behavioral variant patients whose disinhibition exceeds standard dementia care protocols.
Neurology clinics lead volumes today; specialized centers are climbing the fastest as academic medical centers consolidate fragmented dementia services into dedicated programs.
Deployment:
Channel segmentation captures how care delivery location is shifting from hospital-based memory clinics toward decentralized models.
- Telehealth Platforms:Remote cognitive assessment tools achieving FDA validation for executive function measurement are compressing geographic barriers to specialist access. Tablet-based neuropsychological batteries deployed by University of Michigan and Duke University match in-person sensitivity while generating continuous data streams for post-market commitment studies.
- Home Healthcare:Skilled nursing and therapy services extend institutional protocols into residential settings for patients with limited mobility or rural residence. CMS coverage determinations for home-based dementia care are redistributing patient volume across community care settings.
- Hospital-Based Services:Inpatient consultation for diagnostic clarification and acute behavioral crisis management remains concentrated at academic centers.
- Outpatient Clinics:Community neurology practices without specialized FTD expertise serve as referral filters rather than definitive treatment sites.
- Community Care Settings:Adult day programs and senior centers provide structured supervision for patients with mild-to-moderate functional impairment.
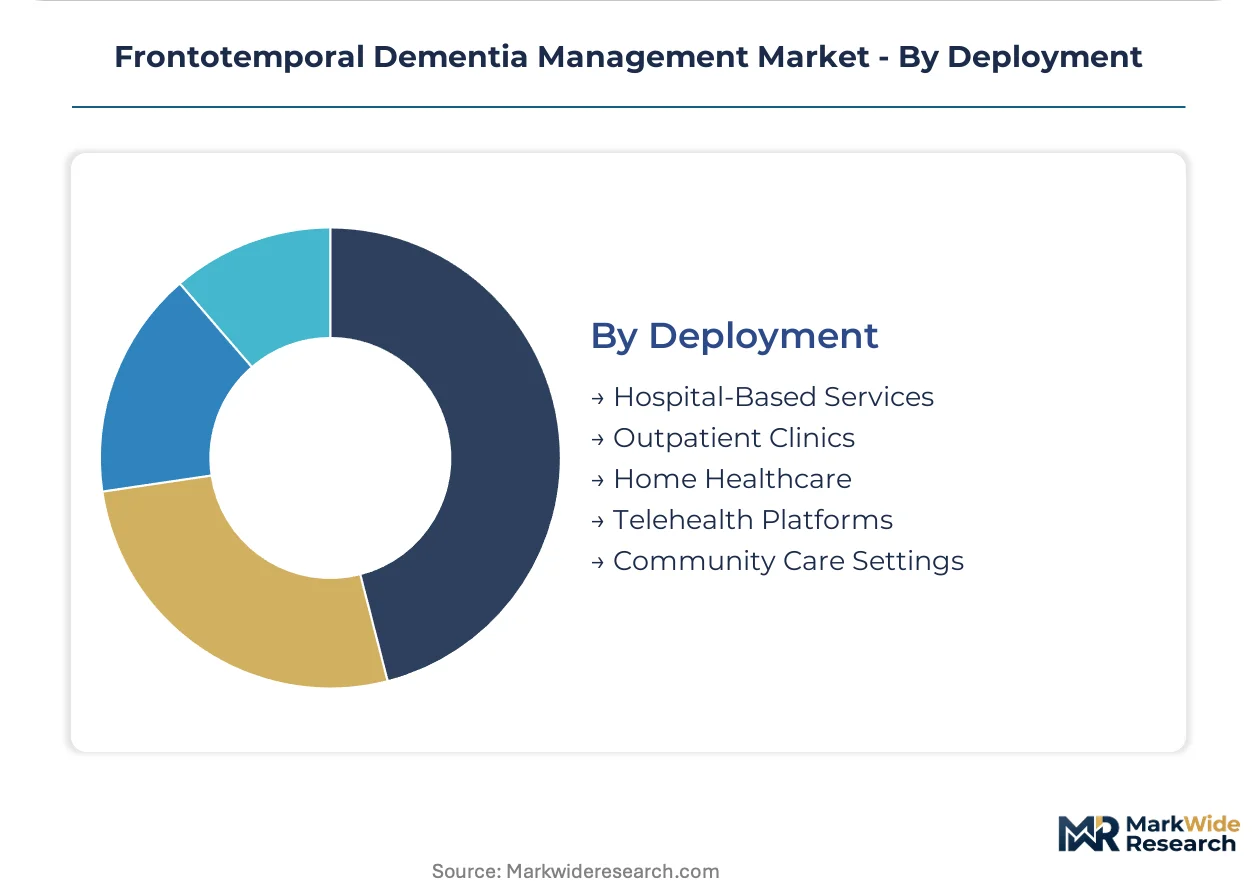
Hospital-based services lead volumes today; telehealth platforms are expanding most quickly as remote cognitive instruments achieve regulatory validation and HIPAA-compliant data architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers concentrate diagnostic expertise more densely than German university hospitals, yet both jurisdictions accelerate biomarker validation through divergent regulatory pathways. Japan's geriatric infrastructure and Australia's remote care networks generate distinct deployment models for cognitive assessment technologies.
United States
Academic medical centers at University of California San Francisco and Mayo Clinic Rochester anchor diagnostic volume through specialized frontotemporal dementia protocols. FDA accelerated approval pathways for neurodegenerative therapies compress development timelines while mandating earlier post-market evidence infrastructure. Cleveland Clinic and Johns Hopkins concentrate treatment-ready patient pools through standardized referral networks spanning urban hospital catchment areas.
Germany
University hospitals in Munich and Heidelberg establish diagnostic protocols that differentiate behavioral variant from language variant subtypes through integrated neuropsychology services. EMA evidentiary standards for surrogate endpoints in neurodegenerative trials diverge from FDA pathways, complicating parallel development strategies for sponsors. The country's national pharmaceutical regulator maintains stricter validation requirements for digital biomarker platforms than US counterparts.
Japan
PMDA consultation frameworks for rare dementia subtypes enable faster regulatory feedback on biomarker-driven trial designs. METI-funded geriatric technology programs accelerate validation of remote cognitive assessment tools for rural prefectures with aging demographics. Tokyo and Osaka academic centers concentrate investigator expertise while regional hospitals face diagnostic specialist scarcity for accurate bvFTD differentiation.
United Kingdom
NHS England's specialized commissioning frameworks direct behavioral variant patients toward designated tertiary neurology centers in London and Manchester. MHRA post-Brexit regulatory autonomy creates divergence from EMA evidentiary standards for surrogate markers in neurodegenerative trials. Oxford and Cambridge research institutes anchor biomarker discovery programs through NIHR-funded dementia research infrastructure.
Australia
TGA validation pathways for digital health technologies enable faster deployment of tablet-based neuropsychological batteries across rural and remote communities. Medicare coverage determinations for telehealth cognitive assessment redistribute patient volume from urban memory clinics toward decentralized primary care networks. University of Melbourne and University of Queensland anchor diagnostic standardization efforts through national dementia research partnerships.
Frontotemporal Dementia Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with disease-modifying developers commanding development investment despite clinical uncertainty while generic manufacturers capture symptomatic therapy volume. The vendor base concentrates around three strategic archetypes: blood-brain barrier platform specialists, biomarker-driven trial designers, and broad neurology infrastructure operators. Competitive positioning depends on M&A activity targeting delivery technologies and strategic partnerships embedding digital biomarker platforms into phase 2 protocols.
Within the platform technology tier, Denali Therapeutics and Alector exemplify divergent approaches to central nervous system drug development. Denali anchors its positioning through engineered transport technologies that differentiate delivery from conventional systemic administration. Alector occupies a position within the biomarker-driven archetype, leveraging protein marker strategies to anchor early-stage pipeline credibility among academic investigators. GSK sits within the broad infrastructure category, sustaining neurology capabilities that compete across multiple neurodegenerative indications simultaneously.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Alector |
| GSK |
| Astellas Pharma |
| Passage Bio |
| Denali Therapeutics |
| CervoMed |
| AviadoBio |
| NKGen Biotech |
| Others |
Supply & Pricing Matrix
FDA accelerated approval pathways for neurodegenerative therapies gate qualified supply access and premium-tier pricing for disease-modifying candidates, while generic cholinesterase inhibitors face margin compression across community pharmacy channels. This regulatory bifurcation concentrates pricing power with sponsors that build post-market evidence infrastructure early, forcing supply chain investments in biomarker collection and patient registry systems.
Pricing Analysis
Capacity additions in telehealth platform validation are reshaping price floors for remote cognitive assessment tools as HIPAA-compliant architectures achieve broader Medicare reimbursement. Three-tier pricing structure across premium, standard, and economy levels separates specialized dementia care certification from generic psychiatric services and unvalidated digital tools. Price differentiation hinges on biomarker integration depth and FDA validation status. Pricing pressure stems from generic substitution in symptomatic therapy portfolios. Academic medical centers show least price sensitivity; community neurology practices face acute budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from CMS and Medicare Advantage plans mandate multi-supplier qualification for behavioral intervention protocols and digital biomarker platforms. Manufacturing concentrates in the United States, Germany, and Japan, with raw material dependencies on tau and TDP-43 protein assay reagents, tablet-based neuropsychological battery hardware, and specialized dementia care workforce training. Supply chain risk centers on single-source vulnerability for blood-brain barrier delivery technologies. Distribution runs through academic medical center networks and neurology clinic referral systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA accelerated approval pathways for neurodegenerative therapies continuously expand addressable demand through conditional launch mechanisms and post-market commitment structures.
For Market Incumbents: To counter generic substitution pressure in cholinesterase inhibitor portfolios, prioritize backward integration into biomarker-driven trial infrastructure and secure exclusive channel arrangements with top-decile neurology clinics at University of California San Francisco and Mayo Clinic Rochester. Capacity addition in blood-brain barrier platform technologies offers defensive moat construction against systemic delivery competitors. For New Entrants and Emerging Players: Telehealth platform partnerships represent the most penetrable entry vector, particularly with Medicare Advantage networks in California and Massachusetts piloting tiered provider systems. Target caregiver training certification white space where specialized dementia care reimbursement codes command premium pricing. Go-to-market leverage rests on embedding FDA-validated cognitive instruments into existing electronic health record workflows at academic medical centers lacking in-house digital development capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among contract manufacturers and generic symptomatic therapy producers facing patent cliff pressures. Long-term viability favors platform technology specialists with validated central nervous system delivery mechanisms. Acquisition target archetype: biotechnology developers with phase 2 biomarker-driven protocols and established investigator relationships at NIH-funded Alzheimer's Disease Research Centers. Watch FDA guidance on surrogate endpoint acceptance as inflection indicator for parallel EMA development strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Driven Trial Design | FDA acceptance of tau and TDP-43 markers enables smaller efficacy studies reducing enrollment burdens. |
| Post-Market Evidence Infrastructure | Patient registries and digital biomarker collection systems satisfy accelerated approval commitment requirements. |
| Specialized Dementia Care Certification | Medicare Advantage tiered networks direct higher acuity patients to certified care managers. |
| Blood-Brain Barrier Platform Investment | Engineered transport technologies differentiate delivery from conventional systemic administration approaches. |
| Telehealth Platform Validation | Remote cognitive assessment tools expand addressable populations beyond urban hospital catchment areas. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors at Medicare Part D plans, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS coverage determination databases. Bottom-up patient volume modeling and top-down revenue triangulation anchored market size estimates.
Comparable-period anchoring tied projection horizons to historical diagnostic protocol adoption curves and therapeutic trial enrollment trajectories across the analysis window. Segmentation dimensions spanned product type, application, end user, and deployment channel with treatment line and regional regulatory cluster overlays. CAGRs derived from slope-consistency checks against biomarker validation timelines and reimbursement code expansion patterns. Forecast inputs incorporated neurology clinic specialization rates and telehealth platform HIPAA compliance validation status.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA-FDA endpoint divergence and CMS coverage determination timing for novel diagnostics. Deviation in FDA guidance on surrogate marker acceptance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hemangioma Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Focal Segmental Glomerulosclerosis (FSGS) Treatment Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Aldosteronism Treatment Market
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Fibrodysplasia Ossificans Progressiva (FOP) Treatment Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Market