
 Aflatoxicosis Treatment Market | 2026-2036
Aflatoxicosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Aflatoxicosis Treatment Market Analysis
Pharmaceutical-grade aflatoxin detoxification is bifurcating the competitive landscape between premium certified solutions and commodity-grade binders. BASF SE leverages its synthetic zeolite and bentonite portfolios to sustain dominance in European feed additive channels. Kemin Industries anchors its position through vertically integrated mineral sourcing and region-specific formulation labs. Zoetis differentiates via veterinary pharmaceutical distribution networks that extend into emerging livestock markets.
Aflatoxicosis treatment encompasses pharmaceutical and nutritional interventions designed to neutralize, adsorb, or mitigate tissue damage from aflatoxin B1 and related metabolites, with activated clay minerals achieving binding capacities exceeding 90% under gastric pH conditions. The primary purpose centers on preventing acute hepatic necrosis in livestock and reducing carcinogenic residue transfer into human food chains. Adsorbents occupy the largest revenue pool due to universal feed-integration requirements, while immunomodulators represent the fastest-expanding segment as producers seek alternatives to clay-based interventions. Injectable delivery modes command premium pricing in emergency therapeutic regimens, though oral administration dominates volume through feed-premix incorporation.
The FDA enforces aflatoxin action levels in corn and peanut products under the Federal Food, Drug, and Cosmetic Act, directly shaping product efficacy thresholds and analytical certification requirements for market entry. EFSA's CONTAM Panel evaluations and EU Regulation 1881/2006 establish maximum levels for aflatoxins in foodstuffs, creating parallel compliance architectures for exporters serving multiple jurisdictions. India's FSSAI notification of aflatoxin limits in spices and cereals adds a third regulatory pillar that manufacturers must navigate for Asia-Pacific access. Stakeholders must monitor evolving mycotoxin co-occurrence regulations and invest in multi-toxin binding platforms before single-species product registrations face restriction.
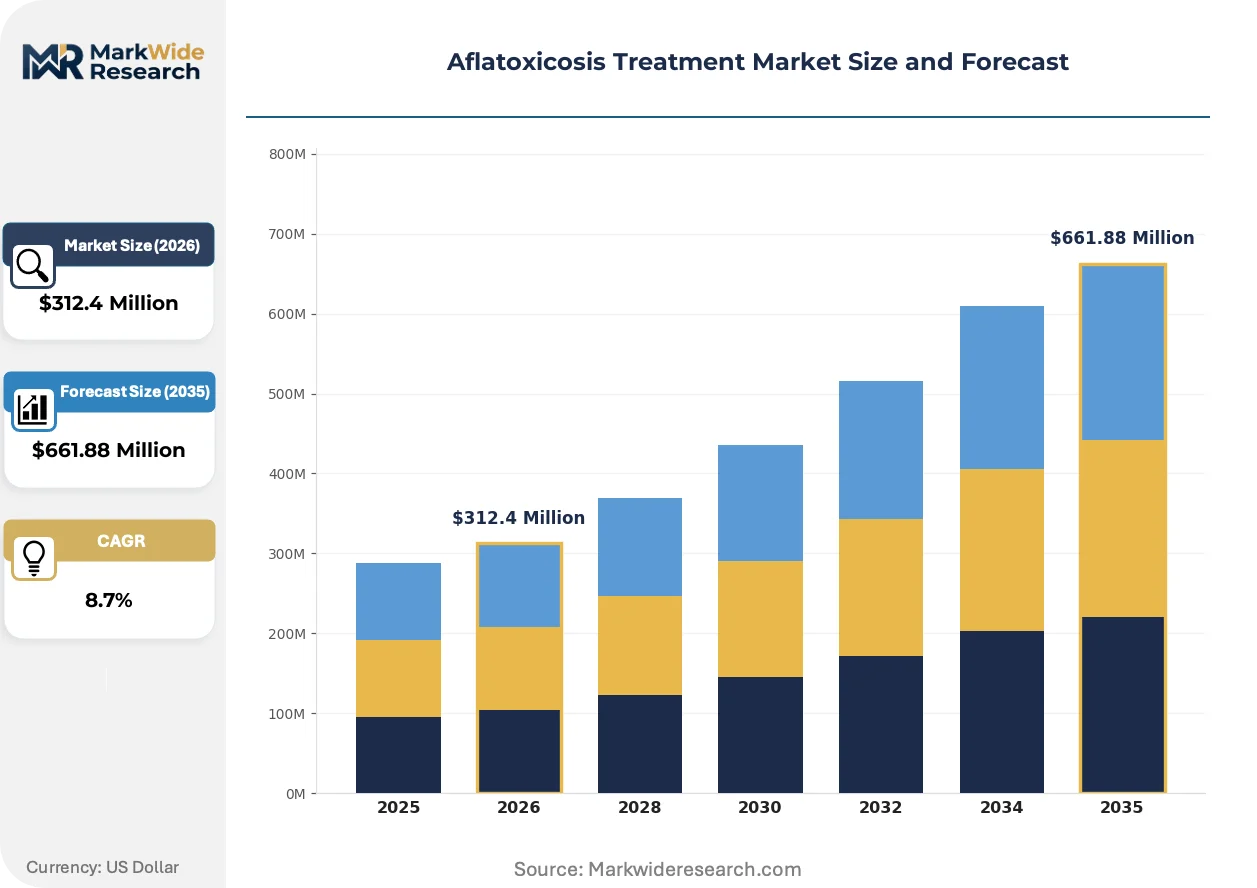
Market Dynamics
Regulatory tightening of aflatoxin maximum residue limits across feed and food supply chains is compressing product development cycles and forcing manufacturers toward multi-toxin binding platforms ahead of single-species obsolescence.
Growth Catalysts
- EFSA CONTAM Panel Evaluations:The European Food Safety Authority's ongoing risk assessments for mycotoxin co-occurrence are accelerating demand for broad-spectrum adsorbent formulations that exceed legacy single-toxin performance benchmarks.
- Poultry Sector Expansion:Industrial broiler operations in Brazil and India are scaling hepatoprotective feed additive programs to preempt liver condemnation rates and maintain export certification for EU-bound protein shipments.
- Synthetic Zeolite Advancement:Engineered clay mineral architectures with pH-stable binding cavities above 90% efficacy under gastric conditions are displacing unmodified bentonite in premium feed formulations.
Market Restraints
- Bentonite Supply Concentration:Premium-grade montmorillonite deposits cluster in specific mining districts, exposing formulators to input cost volatility when regional extraction quotas tighten.
- Immunomodulator Efficacy Variability:Biologic detoxification agents demonstrate inconsistent performance across fungal strain variants, limiting their substitution potential against mineral-based standards.
- FDA-EFSA Divergence:Differing analytical certification requirements for aflatoxin M1 in dairy products create dual compliance burdens for exporters serving both jurisdictions simultaneously.
Strategic Opportunities
- India Spice Export Corridor:FSSAI notification of aflatoxin limits in cardamom and chili creates immediate compliance-driven procurement for pre-shipment detoxification treatments in Kochi and Guntur processing clusters.
- Precision Livestock Monitoring:Integration of real-time mycotoxin biosensors with automated feed adjustment systems opens channel partnerships between treatment suppliers and agricultural technology platforms.
- EU Green Deal Alignment:Sustainability-linked feed additive procurement criteria favor mineral binders with verified low-carbon extraction profiles against synthetic chemical alternatives.
Industry Challenges
- Multi-Jurisdiction Registration Timelines:Obtaining simultaneous FDA Generally Recognized as Safe status and EFSA feed additive authorization extends product commercialization cycles by 18-24 months.
- Veterinary-Pharma Integration Complexity:Injectable hepatoprotective therapies require cold-chain distribution partnerships that conflict with existing feed additive logistics infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aflatoxicosis Treatment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifungal Agents, Adsorbents, Immunomodulators, Nutritional Supplements Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Home Care, Research Institutions Treatment Regimen: Preventive, Therapeutic, Supportive, Emergency |
| Companies Covered | Cargill Incorporated, BASF SE, Novus International, Inc., Kemin Industries, Inc., Alltech Inc., Impextraco NV, Nutreco N.V., Biomin Holding GmbH, Zoetis Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aflatoxicosis Treatment Market Emerging Trajectories
Biocatalytic detoxification approaches are advancing from laboratory validation toward commercial scale, while regulatory frameworks coalesce around co-occurrence assessment protocols that reshape product specification requirements.
Enzymatic aflatoxin B1 degradation using fungal oxidoreductase cocktails is decomposing the historical dominance of physical adsorption methods in high-value dairy applications. European organic dairy cooperatives are piloting these biologic interventions to meet residue limits without clay mineral carryover into milk fractions. This enzymatic shift is compressing R&D investment into mineral surface engineering as the primary competitive arena.
EU Regulation 1881/2006 amendments expanding maximum level categories to cover modified forms of aflatoxins are forcing reformulation of analytical standards and detection kits. Feed testing laboratories must upgrade LC-MS/MS protocols to quantify masked mycotoxins, driving parallel demand for binders effective against hydrolyzed metabolites. German and Dutch feed compounders are consolidating supplier lists to partners with certified multi-metabolite binding data packages.
Integrated service contracts bundling mycotoxin risk assessment, diagnostic testing, and treatment prescription are displacing transactional bulk binder sales in large-scale poultry integrators. Brazilian and US Midwest operations now specify outcome-based agreements tying supplier payments to liver health metrics in slaughtered birds. This performance-linked procurement model concentrates purchasing authority among veterinary distributors with diagnostic capabilities.
Aflatoxicosis Treatment Market Segmentation
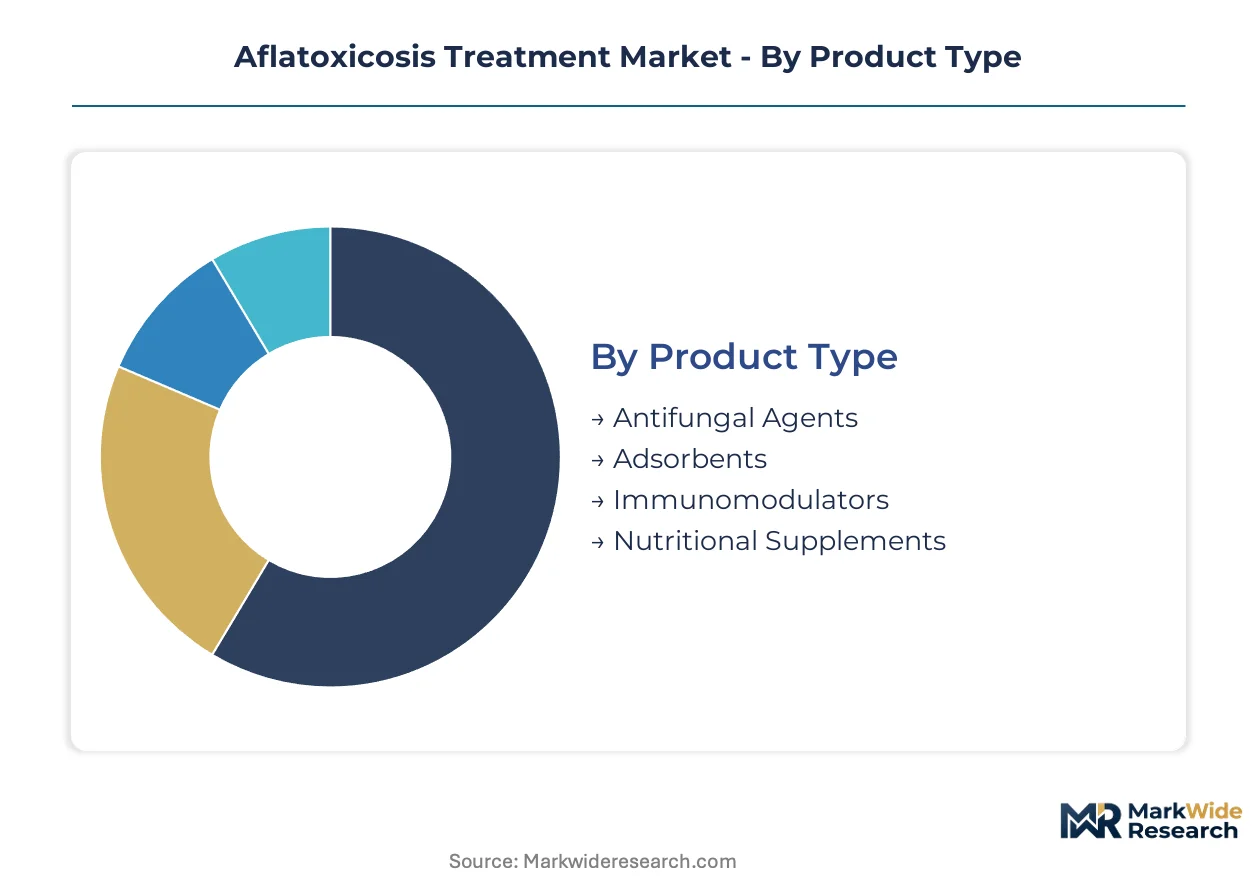
Segmentation in the aflatoxicosis treatment market reveals distinct procurement channels and pricing tiers that align with livestock operation scale and regulatory exposure. Each dimension—product chemistry, administration route, care setting, and clinical intent—channels through different distributor relationships and compliance requirements.
Product Type:
Channel mix varies sharply by chemistry: mineral adsorbents flow through feed compounders in bulk tonnage, while biologic agents route through veterinary pharmaceutical distributors with cold-chain capabilities.
- Adsorbents:Clay minerals and synthetic zeolites engineered with pH-stable binding cavities exceeding 90% efficacy under gastric conditions. Demand concentrates in Brazilian and US Midwest poultry integrators seeking to preempt liver condemnation and maintain EU export certification.
- Immunomodulators:Biologic detoxification agents including fungal oxidoreductase cocktails that degrade aflatoxin B1 enzymatically. European organic dairy cooperatives are piloting these interventions to eliminate clay mineral carryover into milk fractions while meeting EFSA residue limits.
- Antifungal Agents:Pharmaceutical compounds targeting fungal proliferation in stored feedstocks, primarily procured by large-scale grain elevators and feed mills with on-site mycology laboratories.
- Nutritional Supplements:Hepatoprotective vitamin and amino acid formulations supporting liver regeneration, distributed through farm supply retailers and direct-to-producer veterinary service programs.
By volume, Adsorbents leads. By growth pace, Immunomodulators is climbing the fastest.
Delivery Mode:
Cost tier stratification separates emergency therapeutic pricing from routine feed-premix economics, with injectable formats commanding 3-5x premiums over oral administration.
- Oral:Feed-premix and water-soluble formulations dominating volume through automated distribution systems in industrial broiler and layer operations across India and Brazil.
- Injectable:Emergency hepatoprotective therapies requiring cold-chain logistics partnerships that conflict with standard feed additive distribution infrastructure.
- Intravenous:Intensive care applications in veterinary teaching hospitals and referral centers managing acute hepatic necrosis outbreaks.
- Topical:Limited dermatological applications in companion animal settings, marginal to livestock-focused market volume.
Oral administration generates the highest absolute volume. Injectable formats are gaining share fastest in premium dairy segments.
End User:
Customer type determines contract structure: integrated poultry operations negotiate outcome-based agreements, while independent producers purchase through transactional distributor channels.
- Hospitals:Veterinary referral centers handling acute aflatoxicosis cases with diagnostic imaging and intensive care capabilities, concentrated in US land-grant university networks and European veterinary schools.
- Clinics:Mixed-animal practices in rural India and Brazil providing preventive feed assessment and treatment prescription services to smallholder livestock producers.
- Home Care:Producer-administered feed-premix programs supported by tele-veterinary consultation platforms, expanding fastest in Brazilian mid-scale poultry operations.
- Research Institutions:Universities and contract research organizations conducting efficacy studies for regulatory submissions to FDA and EFSA, sourcing pharmaceutical-grade reference materials.
Hospitals anchor premium therapeutic procurement. Home Care is expanding most quickly as precision livestock monitoring enables remote treatment adjustment.
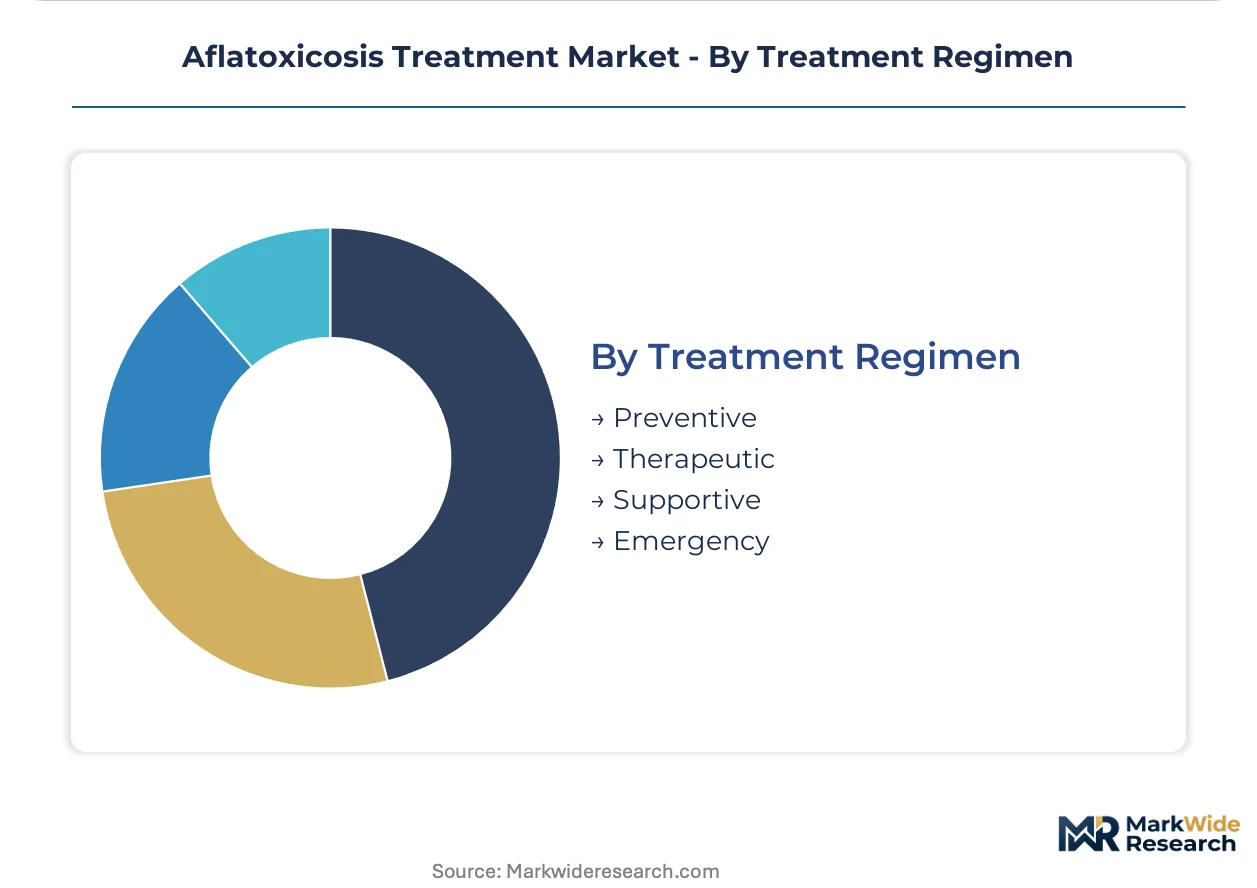
Treatment Regimen:
Maturity gradients separate established preventive protocols from emerging emergency response frameworks still consolidating clinical evidence bases.
- Preventive:Routine adsorbent incorporation in feed rations, now specified in supplier contracts tied to liver health metrics at slaughter in Brazilian and US integrator operations.
- Therapeutic:Active intervention protocols following confirmed mycotoxin exposure, combining adsorbent escalation with hepatoprotective pharmaceutical support.
- Supportive:Nutritional and metabolic management during recovery phases, typically delivered through extended water additive programs in dairy herds.
- Emergency:Intensive intervention for acute hepatic necrosis, requiring rapid diagnostic confirmation and injectable pharmaceutical administration in referral hospital settings.
Preventive regimens dominate absolute volume. Emergency protocols are gaining share fastest as real-time biosensor deployment enables rapid response triggering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for aflatoxicosis treatments varies sharply by geography: Brazilian poultry integrators negotiate outcome-based contracts while Indian smallholders prioritize low-cost bulk binders. This demand elasticity divergence shapes regional procurement patterns and supplier strategies.
United States
Midwest corn belt operations drive feed additive procurement as liver condemnation rates in broiler flocks trigger compliance investments. FDA action levels for aflatoxin in corn products enforce strict residue thresholds that elevate demand for certified adsorbents. Iowa and Illinois processing clusters concentrate bulk mineral sourcing contracts with veterinary distributors.
Brazil
Industrial broiler and layer operations scale hepatoprotective programs to maintain EU export certification for protein shipments. ANVISA feed additive regulations align with EFSA standards for aflatoxin M1 limits in dairy products. São Paulo and Paraná poultry integrators specify supplier contracts tied to slaughterhouse liver health metrics.
India
Warm-humid climates in groundnut and maize belts elevate fungal contamination risks across smallholder and commercial livestock operations. FSSAI notification of aflatoxin limits in spices and cereals mandates pre-shipment detoxification for export-bound cardamom and chili. Kochi and Guntur processing clusters concentrate compliance-driven procurement for pre-export treatments.
Germany
Organic dairy cooperatives pilot enzymatic detoxification to eliminate clay mineral carryover while meeting EFSA residue limits. EU Regulation 1881/2006 amendments expanding maximum level categories to modified aflatoxin forms drive LC-MS/MS protocol upgrades. Bavarian and Lower Saxon feed compounders consolidate supplier lists to partners with certified multi-metabolite binding data.
Netherlands
EU Green Deal sustainability criteria favor mineral binders with verified low-carbon extraction profiles against synthetic chemical alternatives. EFSA CONTAM Panel evaluations for mycotoxin co-occurrence accelerate demand for broad-spectrum adsorbent formulations. Rotterdam and Eindhoven distribution hubs channel feed additive exports to European poultry and dairy markets.
Aflatoxicosis Treatment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the aflatoxicosis treatment market. Synthetic zeolite engineering and enzymatic biologic development concentrate among diversified chemical and pharmaceutical conglomerates, while bulk bentonite sourcing and formulation dominate regional mineral processors. Three strategic archetypes define competitive positioning: premium certified solution providers, vertically integrated mineral specialists, and veterinary pharmaceutical distributors with diagnostic capabilities. Dominant competitive moves include backward integration into captive mineral deposits and outcome-based contract structuring tied to livestock health metrics.
Within the premium certified tier, BASF SE and Kemin Industries occupy positions anchored by synthetic zeolite portfolios and region-specific formulation laboratories. Among veterinary pharmaceutical distributors, Zoetis exemplifies the diagnostic-integrated service model extending into emerging livestock markets. Biomin Holding GmbH represents the European specialist archetype with concentrated feed additive authorization expertise across EFSA jurisdictions.
| Leading Market Players |
|---|
| Cargill Incorporated |
| BASF SE |
| Novus International, Inc. |
| Kemin Industries, Inc. |
| Alltech Inc. |
| Impextraco NV |
| Nutreco N.V. |
| Biomin Holding GmbH |
| Zoetis Inc. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at synthetic zeolite manufacturing facilities in Germany and the United States shapes both supply concentration and price floors for premium adsorbent grades. Scale economies in engineered clay mineral production compress margins for unmodified bentonite processors while elevating pricing power for certified multi-toxin binders serving EU and FDA jurisdictions.
Pricing Analysis
EFSA feed additive authorization and FDA Generally Recognized as Safe status dictate the pricing tier structure across the aflatoxicosis treatment market. Three-tier pricing structure across pharmaceutical-grade, certified feed-grade, and commodity mineral levels separates emergency injectable therapies from routine feed-premix adsorbents. Certification investment for dual-jurisdiction registration elevates price floors for premium tiers. Cost compression in commodity bentonite is intensifying because Brazilian and Indian bulk buyers consolidate procurement around volume-discounted contracts. Independent smallholder producers in India's groundnut belt exhibit highest price sensitivity, while EU organic dairy cooperatives accept premium positioning for enzymatic alternatives.
Supply Chain Analysis
The United States and Germany anchor synthetic zeolite engineering and pharmaceutical-grade formulation, while India and Brazil concentrate bulk bentonite processing and regional feed-premix manufacturing. Engineered clay minerals draw from captive montmorillonite deposits in Wyoming and Bavaria, with fungal oxidoreductase enzymes sourcing from specialized fermentation facilities in the Netherlands and Denmark. Single-source vulnerability in premium-grade mineral deposits exposes formulators to extraction quota disruptions when regional environmental regulations tighten. Distribution runs through veterinary pharmaceutical distributors with cold-chain capabilities for injectable therapies, alongside feed compounder channels for bulk adsorbent integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision livestock monitoring platforms are creating interoperability standards that reshape competitive boundaries between treatment suppliers and agricultural technology providers. This platform-economics inflection favors ecosystem orchestrators over standalone product vendors.
For Market Incumbents: Shield market position through backward integration into captive mineral deposits in Wyoming and Bavaria to secure input cost stability against extraction quota volatility. Accelerate certification investment for EFSA multi-metabolite binding data packages before regulatory amendments restrict single-species product registrations. Channel control through diagnostic-integrated service contracts locks out commodity competitors in Brazilian and US Midwest poultry integrator accounts.
For New Entrants and Emerging Players: Anchor in enzymatic biologic detoxification for European organic dairy segments where clay mineral carryover sensitivity creates substitution appetite. Target India's spice export processing clusters in Kochi and Guntur for pre-shipment compliance treatments under FSSAI notification requirements. Partner with precision livestock monitoring platforms for automated feed adjustment system integration as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors veterinary pharmaceutical distributors with diagnostic capabilities and cold-chain infrastructure over standalone mineral processors. Long-term viability rests on outcome-based contract structuring that ties supplier economics to livestock health metrics at slaughter. Acquisition focus should center on European feed additive specialists with concentrated EFSA authorization expertise. The signal to watch is regulatory convergence around mycotoxin co-occurrence assessment protocols that reshape product specification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Toxin Binding Platform Development | EFSA co-occurrence evaluations are accelerating demand for broad-spectrum formulations exceeding legacy single-toxin benchmarks. |
| Backward Integration into Mineral Deposits | Captive supply of Wyoming and Bavarian montmorillonite insulates formulators from regional extraction quota volatility. |
| Diagnostic-Integrated Service Contracts | Brazilian and US Midwest poultry integrators now specify outcome-based agreements tied to liver health metrics. |
| Enzymatic Biologic Scale-Up | European organic dairy cooperatives pilot fungal oxidoreductase cocktails to eliminate clay mineral carryover in milk fractions. |
| Precision Livestock Monitoring Partnerships | Real-time mycotoxin biosensor integration with automated feed adjustment opens channel partnerships with agtech platforms. |
Methodological Framework
A spread of perspectives from feed compounder procurement directors, veterinary pharmaceutical distributors, regulatory affairs specialists at mineral processing firms, and precision livestock technology developers converged on the working assumptions underlying this analysis. Primary interviews with stakeholders across Brazil, India, Germany, and the United States combined with secondary validation from FDA enforcement reports, EFSA CONTAM Panel evaluations, FSSAI notifications, and feed industry trade data. Bottom-up modeling of product-type volumes and top-down reconciliation against regional livestock population statistics ensured triangulation integrity.
Segmentation dimensions modeled span adsorbent chemistry tier, delivery mode stratification, end-user care setting, and treatment regimen intent across the projection horizon. Product-level growth trajectories derived from livestock sector expansion rates, regulatory tightening timelines, and substitution elasticity between mineral and biologic interventions. Forecast inputs incorporated poultry and dairy herd projections, grain contamination incidence patterns, and export certification requirement evolution.
Material uncertainties — regulatory divergence between FDA and EFSA, immunomodulator efficacy variability across fungal strain variants, and bentonite supply concentration disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about continued regulatory tightening trajectory and enzymatic technology maturation timelines. Recalibration cycles align with material shifts in mycotoxin co-occurrence regulatory frameworks and precision livestock monitoring platform adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Rumination Syndrome Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Asperger Syndrome Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Global Tourette Syndrome Treatment Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Eosinophilic Granulomatosis Market
Specialty Medicine
Severe Combined Immunodeficiency Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Polycystic Ovarian Syndrome Treatment Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
US Actinic Keratosis Treatment Market