
 Global Prurigo Nodularis Treatment Market | 2026-2036
Global Prurigo Nodularis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prurigo Nodularis Treatment Market Foresight
North American biopharma manufacturing capacity is decoupling from traditional small-molecule dermatology production as fill-finish lines for injectable biologics multiply across the region. Sanofi SA leverages its immunology infrastructure to sustain Dupixent positioning in prurigo nodularis adjacent indications. Incyte Corporation anchors its dermatology portfolio through JAK inhibitor specialization. Regeneron Pharmaceuticals competes via IL-4/IL-13 pathway dominance in atopic and pruritic conditions.
Prurigo Nodularis Treatment encompasses pharmacologic and non-pharmacologic interventions targeting chronic nodular skin lesions characterized by intense pruritus, including topical corticosteroids, systemic immunomodulators, biologic agents targeting interleukin pathways, and narrowband UVB phototherapy protocols administered across escalating care settings. The primary purpose is interrupting the itch-scratch cycle while resolving inflammatory nodules through neuroimmune modulation. Biologics represent the fastest-expanding product type as IL-31, IL-4, and JAK-targeted mechanisms displace conventional immunosuppressant reliance in refractory cases. Hospital-based administration still dominates biologic delivery, though dermatology clinics are capturing ambulatory infusion and injection volumes as prior authorization pathways mature.
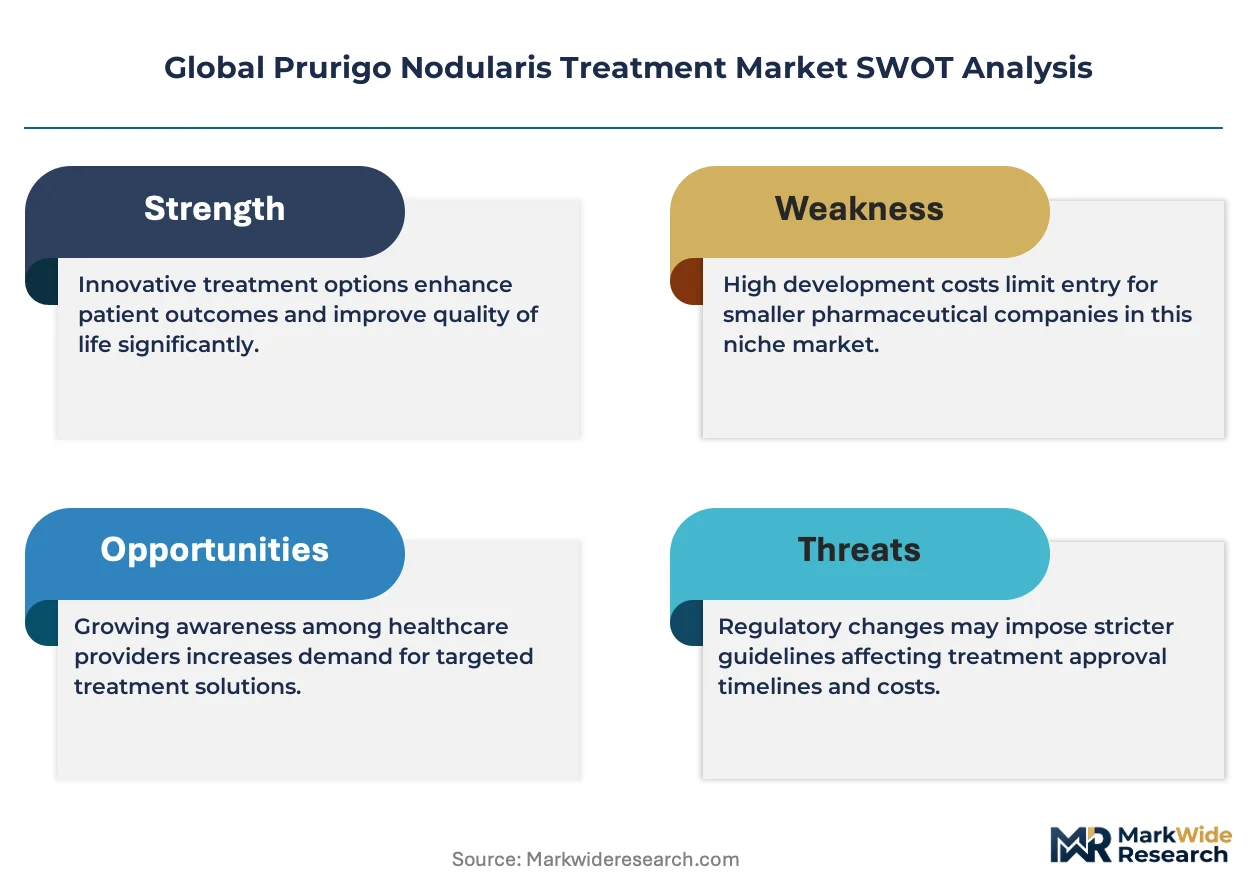
FDA breakthrough therapy designations and EMA PRIME eligibility for prurigo nodularis indications are compressing development timelines and reshaping payer negotiation leverage for novel biologics. The EU MDR and FDA cGMP standards for combination drug-device products govern autoinjector and pre-filled syringe formats increasingly preferred for subcutaneous biologic administration. Stakeholders must monitor how CMS national coverage determinations and Germany's G-BA benefit assessments for chronic pruritus biologics will restructure commercialization sequencing across the Atlantic corridor.
Market Dynamics
The prurigo nodularis treatment landscape is restructuring around biologic manufacturing scale-up, as fill-finish capacity for injectable IL-31 and JAK inhibitors pulls investment away from topical corticosteroid production lines.
Growth Catalysts
- Breakthrough Therapy Pathway:The FDA's accelerated review mechanism for chronic pruritus indications compresses clinical trial timelines and attracts development capital toward nodular prurigo mechanisms.
- Specialty Clinic Expansion:Dermatology centers in Germany, Japan, and the United States are adding dedicated infusion suites and injection training programs to capture biologic administration volumes.
- Neuroimmune Target Validation:IL-4/IL-13 and IL-31 pathway elucidation through academic medical center research is validating new biologic targets and expanding addressable patient populations.
Market Restraints
- Cold Chain Infrastructure Costs:Biologic stability requirements demand continuous 2-8°C distribution, elevating logistics expenditure and limiting pharmacy dispensing flexibility.
- Prior Authorization Friction:US payer step-therapy mandates and Germany's G-BA benefit assessment timelines delay treatment initiation and create administrative burden for prescribing physicians.
- Manufacturing Concentration:Fill-finish capacity for monoclonal antibodies clusters in Massachusetts, North Carolina, and Puerto Rico, creating geographic supply vulnerability and capacity allocation bottlenecks.
Strategic Opportunities
- Ambulatory Site-of-Care Migration:Dermatology clinics in Texas, Florida, and Ohio are capturing hospital outpatient infusion volumes through dedicated biologic administration programs.
- Autoinjector Device Convergence:Combination drug-device platforms integrating pre-filled syringes with patient-administered delivery are reducing nursing dependency and enabling home-based therapy.
- EMA PRIME Eligibility:The European Medicines Agency's priority medicines scheme offers accelerated assessment and enhanced regulatory support for novel pruritus biologics entering EU markets.
Industry Challenges
- Specialized Infusion Nursing Shortage:Biologic administration requires trained personnel for adverse event monitoring, and workforce gaps in ambulatory settings constrain clinic capacity expansion.
- Legacy System Integration:Electronic health record platforms in community dermatology practices lack interoperability with specialty pharmacy hubs, fragmenting patient monitoring and adherence tracking.
- EU MDR Compliance Timeline:Medical device regulation requirements for combination autoinjector products impose documentation burdens and notified body capacity constraints on device developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prurigo Nodularis Treatment Market |
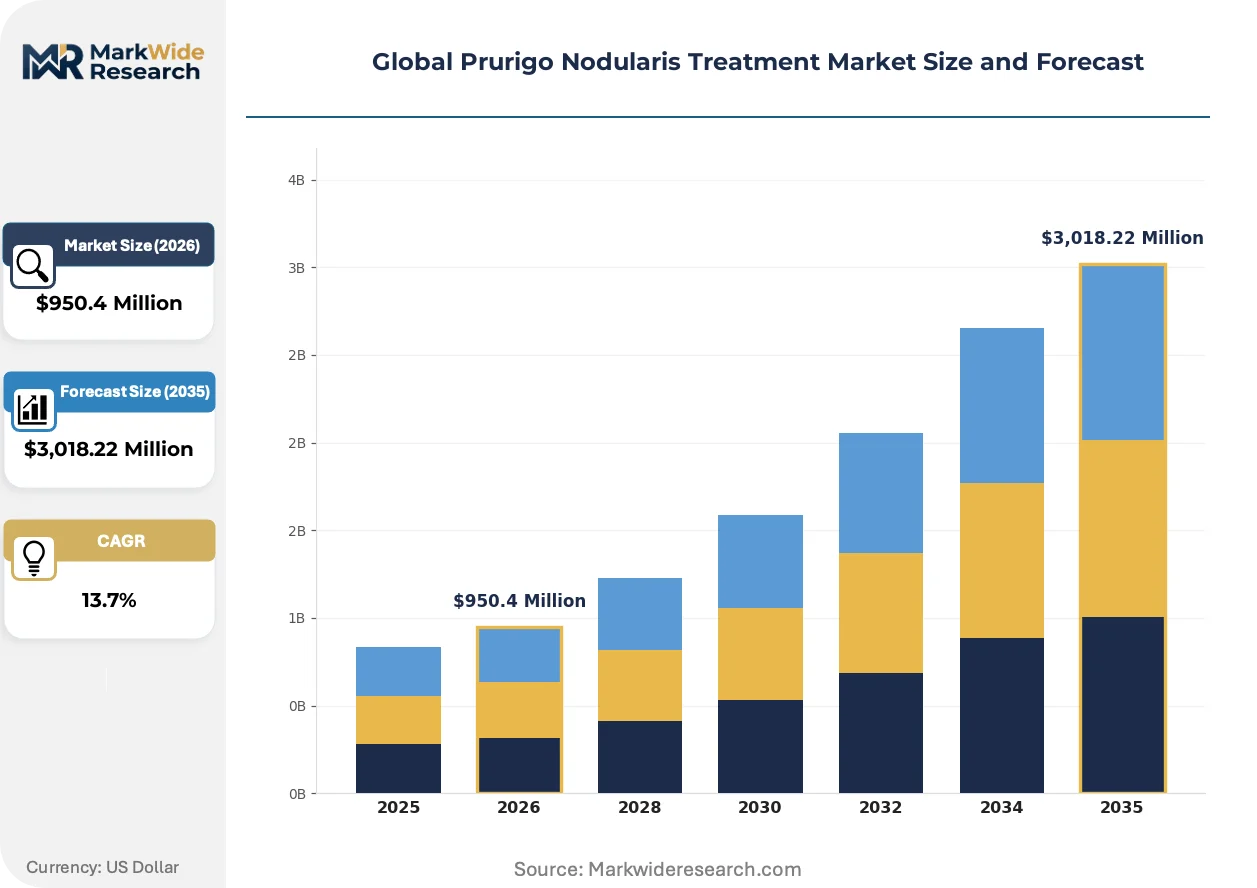
| Market Size in 2026 | $950.4 Million |
| Market Size in 2035 | $3,018.22 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Immunosuppressants, Antihistamines, Biologics, Phototherapy Therapy Area: Chronic Pruritus, Neuropathic Itch, Inflammatory Dermatoses, Allergic Dermatitis, Xerosis Care Setting: Hospitals, Dermatology Clinics, Specialty Clinics, Ambulatory Surgical Centers Distribution Channel: Pharmacies, Hospital Pharmacies, Online Retailers, Direct Sales |
| Companies Covered | Sanofi SA, Galderma SA, Pfizer Inc, GlaxoSmithKline plc, Johnson & Johnson Services Inc, Regeneron Pharmaceuticals, Novartis AG, Incyte Corporation, Merck & Co. Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prurigo Nodularis Treatment Market Shifts & Advancements
Biologics manufacturing is fragmenting production geography while regulatory pathways compress development timelines, reshaping how novel pruritus therapies reach patients across care settings.
Subcutaneous biologic delivery platforms are modularizing treatment administration by separating drug formulation from device engineering. Dermatology clinics in academic medical centers are adopting these platforms to shift infusion volumes from hospital outpatient departments. This modularization is compressing site-of-care requirements and enabling patient self-administration models that bypass traditional nursing dependency.
EMA's PRIME eligibility criteria and the FDA's breakthrough therapy designation are converging to create trans-Atlantic regulatory alignment for chronic pruritus indications. Developers are structuring parallel submission strategies to leverage accelerated timelines in both jurisdictions. Biologics targeting IL-31 and neurokinin receptors are capturing priority review resources previously allocated to oncology portfolios.
Academic medical centers are consolidating prescribing influence through prior authorization navigation services and specialty pharmacy integration. Community dermatology practices in California, New York, and Illinois are affiliating with hospital systems to access biologic procurement contracts and reimbursement support infrastructure. This concentration is visible most acutely in Medicaid managed care populations where payer-mandated step therapy requires institutional advocacy resources.
Global Prurigo Nodularis Treatment Market Segmentation
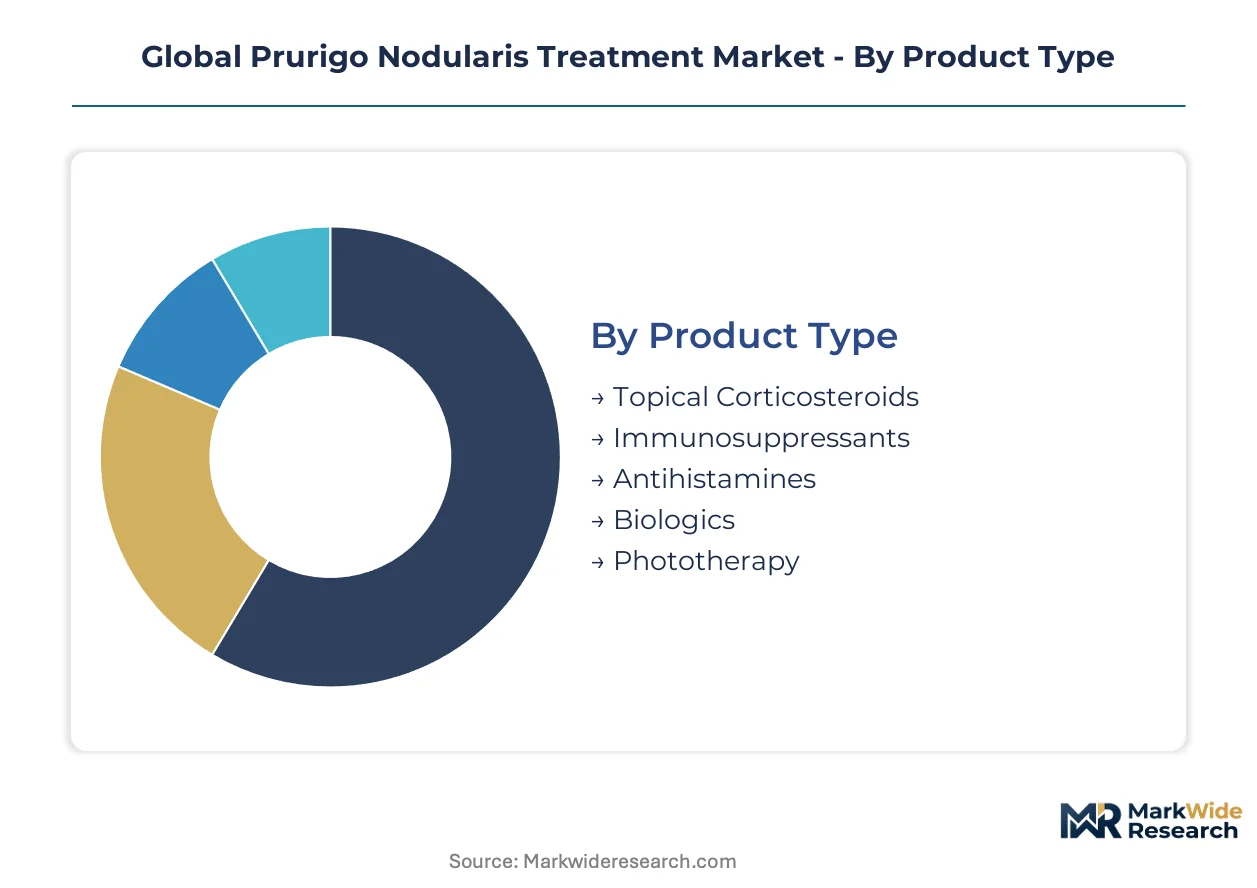
Prurigo nodularis treatment markets fragment across manufacturing intensity, clinical infrastructure requirements, and reimbursement pathways. Each segmentation dimension carries distinct capital commitments and margin profiles that shape competitive positioning.
Product Type:
Biologics command the steepest upfront manufacturing investment, requiring sterile fill-finish lines and cold-chain distribution networks that topical formulations bypass entirely.
- Biologics:Monoclonal antibodies and targeted cytokine inhibitors require single-use bioreactor systems and continuous 2-8°C stability protocols. Massachusetts and North Carolina manufacturing clusters absorb the majority of fill-finish capacity for IL-31 and JAK-targeted therapies, with Puerto Rico emerging as a secondary production node. Demand concentrates in academic medical centers where prior authorization navigation resources justify premium pricing.
- Phototherapy:Narrowband UVB equipment demands capital-intensive device installation and dedicated treatment room infrastructure. Germany and Japan specialty clinics are expanding phototherapy suites as step-therapy protocols delay biologic access, creating interim revenue streams while patients await insurance authorization.
- Topical Corticosteroids:Conventional small-molecule production utilizes existing pharmaceutical manufacturing lines with minimal retooling requirements.
- Immunosuppressants:Systemic agents like cyclosporine and methotrexate leverage generic manufacturing infrastructure across multiple supplier bases.
- Antihistamines:Oral formulations represent the lowest capital barrier, with commoditized production spreading across contract manufacturers.
Biologics absorb the bulk of installed capacity; phototherapy is expanding most quickly as clinics bridge access gaps.
Therapy Area:
Volume concentration follows disease severity gradients, with the most refractory indications justifying premium therapeutic investment.
- Chronic Pruritus:The core addressable population spans idiopathic and secondary etiologies with persistent symptoms exceeding six weeks. United States academic medical centers are consolidating prescribing influence through dedicated pruritus clinics that coordinate biologic procurement and prior authorization support.
- Neuropathic Itch:Nerve-mediated pruritus mechanisms are attracting neurokinin receptor antagonist development, with FDA breakthrough therapy designations compressing clinical timelines for novel targets.
- Inflammatory Dermatoses:Underlying autoimmune skin conditions drive biologic adoption where IL-4/IL-13 pathway modulation addresses multiple disease manifestations.
- Allergic Dermatitis:IgE-mediated mechanisms respond to antihistamine and corticosteroid protocols in mild-to-moderate presentations.
- Xerosis:Age-related skin barrier dysfunction represents high-volume, low-margin maintenance therapy with minimal biologic penetration.
Chronic pruritus captures dominant patient volume; neuropathic itch is gaining share fastest as mechanistic understanding deepens.
Care Setting:
Site-of-care migration is redistributing revenue across institutional and ambulatory channels as administration complexity varies.
- Hospitals:Inpatient and outpatient departments retain complex infusion protocols requiring adverse event monitoring infrastructure. Germany's university hospitals anchor biologic initiation protocols before step-down to community settings.
- Dermatology Clinics:Ambulatory specialty centers in Texas, Florida, and Ohio are capturing infusion volumes through dedicated biologic administration programs with trained nursing staff.
- Specialty Clinics:Focused pruritus and immunology centers concentrate expertise and payer contracting leverage.
- Ambulatory Surgical Centers:Limited penetration due to reimbursement constraints on non-procedural dermatologic services.
Hospitals retain the majority of complex infusion capacity; dermatology clinics are climbing the fastest as autoinjector devices enable site-of-care migration.
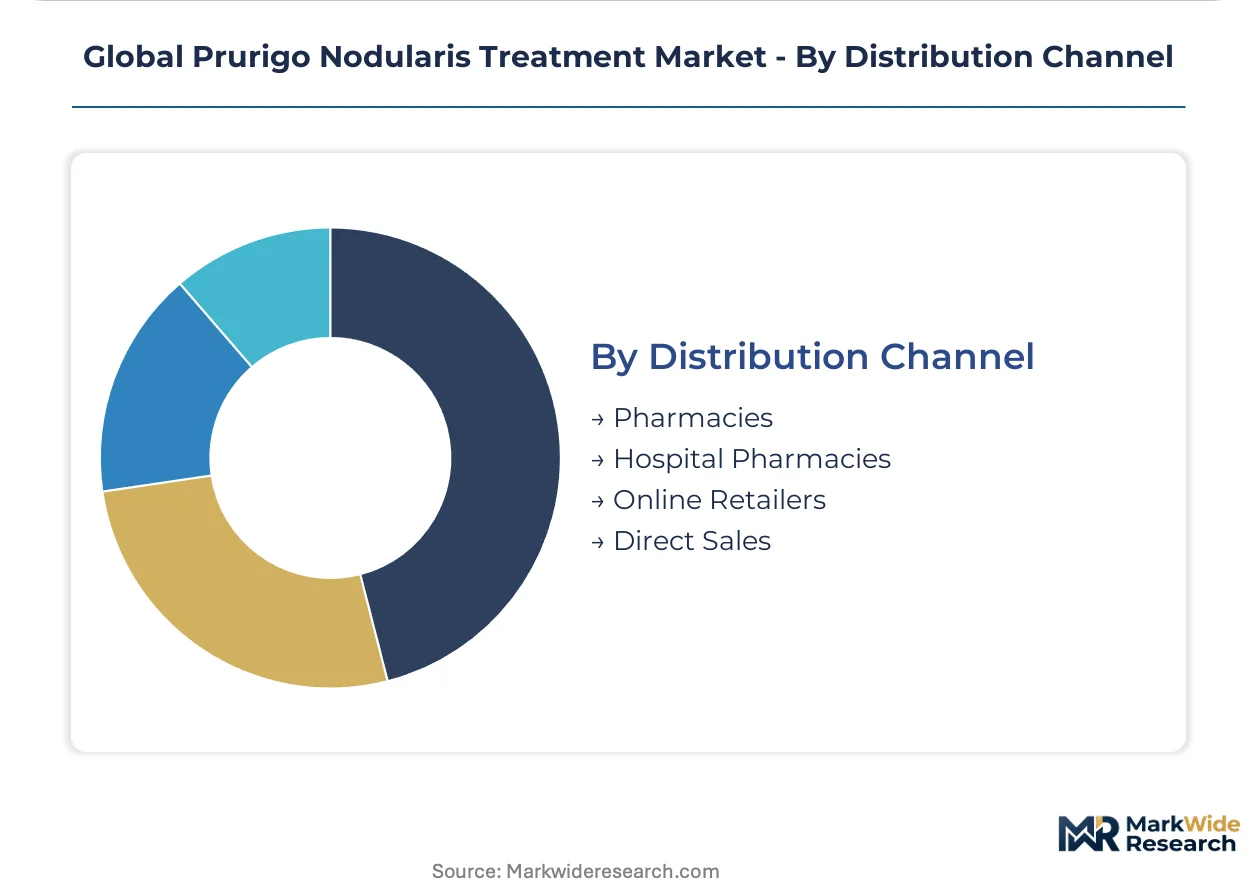
Distribution Channel:
Cold-chain requirements and payer mandates are concentrating volume in specialty pharmacy channels that traditional retail cannot replicate.
- Hospital Pharmacies:Captured within 340B pricing programs and institutional procurement contracts, these channels dominate biologic dispensing for inpatient initiations. United States academic medical centers leverage specialty pharmacy integration to manage prior authorization workflows.
- Pharmacies:Community retail maintains topical and oral generic volume despite limited biologic access.
- Online Retailers:Direct-to-patient models are expanding for maintenance therapies with established safety profiles.
- Direct Sales:Manufacturer-controlled distribution supports patient assistance programs and hub services for high-cost biologics.
Hospital pharmacies command the dominant share of biologic volume; direct sales channels are expanding most quickly as hub service models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts biologics manufacturing clusters anchor North American supply chains for injectable pruritus therapies, while German regulatory pathways shape European market entry sequencing.
United States
Academic medical centers in Boston and Durham drive IL-31 inhibitor clinical adoption through dedicated pruritus clinics. FDA breakthrough therapy designations compress development timelines for novel biologics. Puerto Rico's fill-finish facilities absorb secondary production capacity as mainland Massachusetts and North Carolina sites reach utilization limits.
Germany
G-BA benefit assessments for chronic pruritus biologics create reimbursement negotiation leverage that shapes EU commercialization sequencing. EMA PRIME eligibility accelerates assessment timelines for novel neurokinin receptor antagonists. Bavarian university hospitals anchor biologic initiation protocols before community step-down.
Japan
PMDA priority review vouchers accelerate prurigo nodularis indication approvals for IL-4/IL-13 pathway inhibitors. METI biomanufacturing subsidies expand single-use bioreactor capacity in Kansai and Kanto regions. Tokyo dermatology centers concentrate infusion nursing expertise for complex biologic administration.
United Kingdom
NICE technology appraisals for chronic pruritus therapies determine NHS commissioning thresholds and prescribing formularies. MHRA post-Brexit recognition pathways diverge from EMA centralized procedures for combination drug-device products. London academic medical centers consolidate prior authorization navigation services for specialty biologics.
India
CDSCO accelerated approval pathways for orphan dermatologic indications attract biosimilar development investment toward pruritus mechanisms. PLI scheme incentives expand sterile injectable capacity in Gujarat and Maharashtra manufacturing zones. Mumbai and Delhi specialty clinics capture phototherapy volumes as biologic access remains reimbursement-constrained.
Global Prurigo Nodularis Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue neuroimmune target specialization and autoinjector platform development. The vendor base stratifies across immunology-focused pharmaceutical conglomerates, dermatology-specialized biotech firms, and generic manufacturers of conventional systemic therapies. Three archetypes dominate: pathway specialists concentrating on IL-31 or JAK inhibition, immunology generalists leveraging existing biologics infrastructure, and device-integrated developers pursuing combination product differentiation. Capacity expansion and strategic licensing agreements represent the dominant competitive vectors as manufacturing scale determines market access.
Within the immunology generalist tier, Sanofi SA and Regeneron Pharmaceuticals exemplify large-cap developers repurposing existing biologic platforms for prurigo nodularis adjacent indications. Incyte Corporation occupies a position among JAK inhibitor specialists with dermatology portfolio concentration. These three anchors represent divergent mechanistic bets—IL-4/IL-13 pathway modulation versus JAK signal transduction interruption—that structure competitive positioning across academic medical center formularies.
| Leading Market Players |
|---|
| Sanofi SA |
| Galderma SA |
| Pfizer Inc |
| GlaxoSmithKline plc |
| Johnson & Johnson Services Inc |
| Regeneron Pharmaceuticals |
| Novartis AG |
| Incyte Corporation |
| Merck & Co. Inc |
| Others |
Supply & Pricing Matrix
Prior authorization navigation requirements from US commercial payers and Germany's G-BA are forcing manufacturers to bundle patient support services with biologic pricing, compressing net realized prices while elevating logistics costs for cold-chain distribution.
Pricing Analysis
Warranty and service bundling separates list pricing from net transaction values, with manufacturers absorbing hub services, copay assistance, and nurse training programs into contractual agreements. Pricing stratifies across premium biologics with autoinjector platforms, standard intravenous formulations, and economy-tier conventional immunosuppressants. Price differentiation hinges on FDA breakthrough therapy status and institutional procurement volume commitments. Cost compression in the standard tier is intensifying as biosimilar entrants target IL-4/IL-13 pathways. Medicaid managed care populations exhibit highest price sensitivity; academic medical centers with 340B pricing access demonstrate lowest net price elasticity.
Supply Chain Analysis
Direct-to-specialty pharmacy channels handle biologic dispensing for prior-authorized patients, bypassing retail distribution entirely. Fill-finish capacity concentrates in Massachusetts, North Carolina, and Puerto Rico, with Puerto Rico absorbing overflow from mainland utilization limits. Raw material dependencies include single-use bioreactor systems, pharmaceutical-grade filters, and temperature-controlled packaging materials. Tariff exposure on Chinese-sourced filtration media creates input cost vulnerability. Distribution runs through specialty pharmacy hubs integrated with manufacturer patient assistance programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable IL-31 and JAK-targeted biologics are displacing topical corticosteroid reliance in refractory prurigo nodularis cases, creating technology-transition investment windows for stakeholders positioned across the neuroimmune modulation value chain.
For Market Incumbents: Acquire autoinjector device engineering capabilities to differentiate combination product offerings from intravenous competitors. Secure fill-finish capacity reservations in Puerto Rico before Massachusetts and North Carolina sites reach utilization ceilings. Threat from JAK inhibitor specialists demands IL-31 pathway patent estate fortification through licensing agreements with academic medical center research programs. For New Entrants and Emerging Players: Launch via dermatology clinic direct partnerships in Texas, Florida, and Ohio where site-of-care migration concentrates ambulatory infusion volumes. Target neuropathic itch mechanisms as the most penetrable indication segment with limited incumbent presence. Pursue EMA PRIME eligibility to accelerate European market entry timelines ahead of established IL-4/IL-13 pathway competitors. For Investors and Strategic Acquirers: The window for entry favors JAK inhibitor specialists with dermatology portfolio concentration over immunology generalists with diluted indication focus. Long-term viability hinges on manufacturing scale advantages and prior authorization infrastructure ownership. Signal to watch: CMS national coverage determinations for chronic pruritus biologics as inflection indicator for Medicare reimbursement trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates FDA breakthrough therapy pathway access for IL-31 and neurokinin receptor targets. |
| Manufacturing Scale-Up | Puerto Rico fill-finish expansion absorbs capacity constraints from Massachusetts and North Carolina clusters. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses European assessment timelines for novel pruritus mechanisms. |
| Licensing Agreement | Academic medical center research partnerships validate neuroimmune targets and expand addressable populations. |
| Pipeline Diversification | JAK inhibitor specialization beyond dermatology creates optionality across immunology indications. |
Research Methodology
Multi-period observation of FDA breakthrough therapy designations, EMA PRIME eligibility decisions, and G-BA benefit assessment timelines anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, formulary directors at US academic medical centers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocol registries, and Germany's G-BA dossier documentation. Bottom-up patient population sizing and top-down manufacturer revenue triangulation structured market estimation.
Segment-weighting applied therapy area, product type, care setting, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from log-linear trend fitting to historical adoption curves and forward-adjusted for pipeline probability-weighted launch timing. Forecast inputs included prior authorization approval rate trajectories, specialty clinic capacity expansion plans, and cold-chain logistics cost indices.
Regulatory pathway delays, payer step-therapy mandate expansions, and fill-finish capacity allocation bottlenecks are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding biologic adoption velocity and site-of-care migration pace. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Immunology Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
Thoracic Outlet Syndrome Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Cellulitis Management Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Huntingtons Disease Treatment Market
Specialty Medicine
North America Precision Medicine Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Hypersensitivity Pneumonitis Market