
 Hepatitis Therapeutics Market | 2026-2036
Hepatitis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis Therapeutics Market Outlook
Outcome-based contracting for hepatitis C cures is repositioning how pharmaceutical manufacturers engage payers and health systems. Gilead Sciences leverages its dominant sofosbuvir franchise to sustain pricing power in high-income markets. AbbVie anchors its competitive position through specialized expertise in interferon-free combination regimens. Bristol-Myers Squibb differentiates via R&D intensity in immunomodulatory approaches for hepatitis B functional cure.
Hepatitis therapeutics comprise antiviral, immunomodulatory, and hepatoprotective agents formulated to suppress viral replication, reduce hepatic inflammation, or achieve sustained virologic response in infected patients. Direct-acting antivirals target specific viral proteins—NS3/4A protease, NS5B polymerase, or NS5A—with cure rates exceeding sustained virologic response at 12 weeks in most genotypes. The oral administration route dominates commercial volumes due to patient compliance advantages and outpatient dispensing economics, while intravenous delivery retains importance in hospitalized autoimmune and alcoholic hepatitis cases where rapid immunosuppression or corticosteroid therapy is required.
FDA breakthrough therapy designation and EMA PRIME eligibility compress regulatory review timelines for novel hepatitis B and D therapies, accelerating patient access but intensifying evidence generation requirements. The WHO prequalification program shapes demand in low- and middle-income countries by determining which generic direct-acting antiviral combinations qualify for bulk procurement. Stakeholders must monitor evolving reimbursement criteria for finite-duration versus chronic therapy paradigms as payers recalibrate budget impact models around cure-based value frameworks.
Market Dynamics
The shift from chronic disease management to finite-duration curative regimens is restructuring pharmaceutical economics, compressing revenue cycles while expanding per-patient value capture. Payer reimbursement frameworks now prioritize sustained virologic response metrics over lifetime treatment models.
Growth Catalysts
- Accelerated FDA Breakthrough Therapy pathways:Compressed review timelines for novel hepatitis B functional cures reduce development risk and speed patient access in the United States.
- Point-of-care diagnostics integration:Rapid viral load testing at community clinics in India and Brazil enables same-day treatment initiation, expanding addressable patient pools.
- Medicare and Medicaid bundled reimbursement:US federal programs now cover complete direct-acting antiviral courses under single episode-based payments, eliminating prior authorization barriers.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70 percent of direct-acting antiviral raw materials originate from Chinese and Indian contract manufacturers, creating supply vulnerability.
- EMA conditional marketing authorization evidence requirements:Post-approval confirmatory trials for hepatitis D therapies impose substantial follow-on investment obligations.
- Generic substitution pressure:Patent expirations for sofosbuvir-based regimens enable low-cost Indian and Egyptian manufacturers to undercut originator pricing in WHO prequalification markets.
Strategic Opportunities
- Hepatitis B functional cure white space:No approved therapy currently eliminates covalently closed circular DNA, creating first-mover advantage for capsid inhibitors and siRNA approaches.
- Sub-Saharan African public procurement:WHO Global Hepatitis Strategy targets and Global Fund co-financing open volume contracts for pangenotypic single-tablet regimens.
- Telemedicine-integrated adherence monitoring:Digital pill dispensers linked to mobile health platforms enable real-world evidence generation for payers in Germany and the Netherlands.
Industry Challenges
- Virology and hepatology specialist shortages:Treatment guideline complexity requires physicians trained in resistance profiling and drug-drug interaction management, particularly for HIV-hepatitis C coinfected populations.
- Real-world evidence infrastructure gaps:Post-market surveillance systems in low- and middle-income countries lack capacity to track reinfection rates and long-term hepatocellular carcinoma outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis Therapeutics Market |
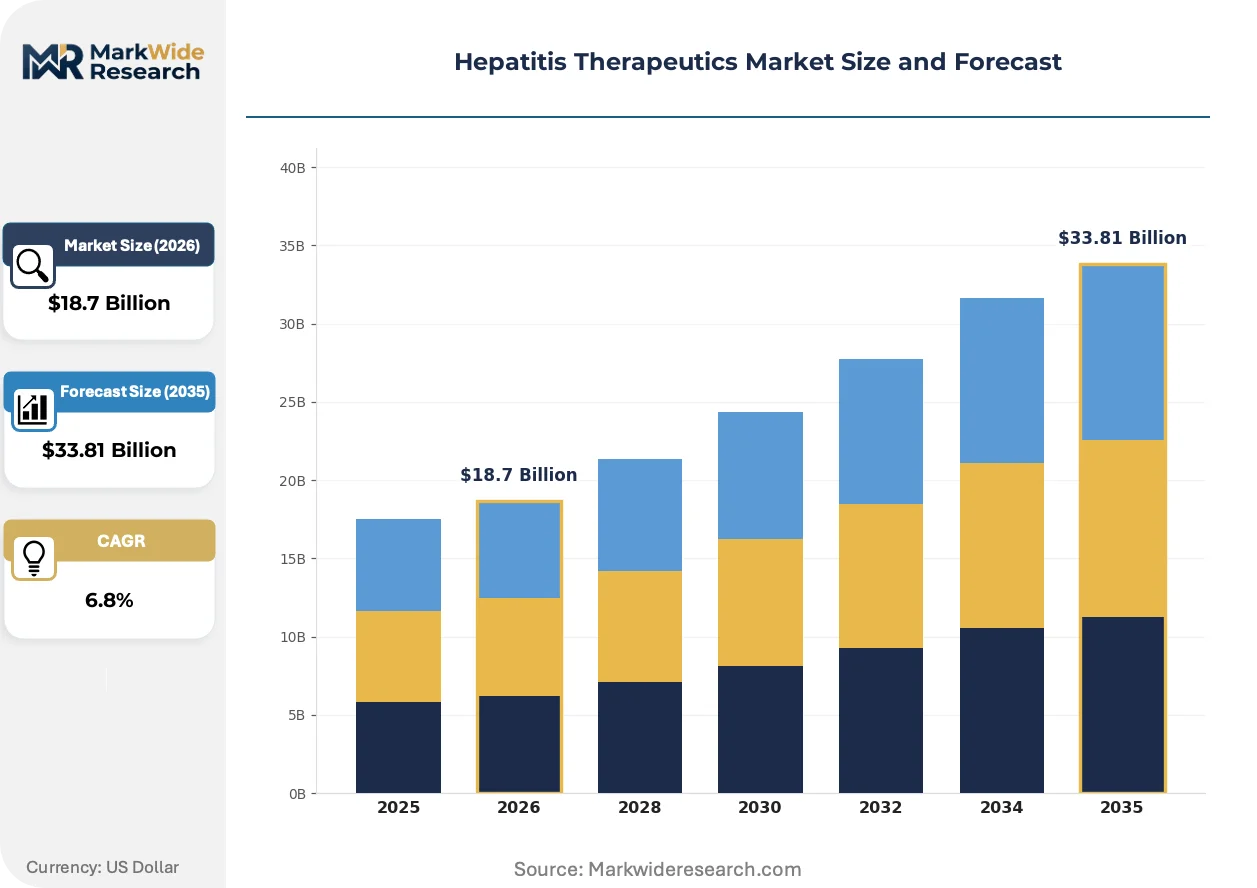
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interferons, Nucleotide Analogues, Direct-Acting Antivirals, Combination Therapy End User: Hospitals, Clinics, Outpatient Facilities, Research Laboratories Administration Route: Oral, Injectable, Intravenous, Topical Therapy Area: Drug-Induced Hepatitis, Viral Hepatitis, Autoimmune Hepatitis, Alcoholic Hepatitis |
| Companies Covered | Gilead Sciences, Bristol-Myers Squibb, AbbVie, Merck & Co., F. Hoffmann-La Roche, GSK, Cipla, Teva Pharmaceutical Industries, Lupin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis Therapeutics Market Strategic Shifts
Pharmaceutical development pipelines are pivoting toward combination platforms that simultaneously target multiple viral lifecycle stages, while diagnostic and delivery modalities converge to compress the test-to-treat interval.
RNA interference therapeutics targeting hepatitis B surface antigen production are decentralizing treatment access by enabling extended-interval dosing. Community health workers in Vietnam and Kenya administer subcutaneous injections during quarterly visits rather than requiring monthly hepatology appointments. This delivery model is compressing infrastructure requirements for national elimination programs.
EMA PRIME eligibility and FDA Breakthrough Therapy designation are converging to create harmonized evidence standards for hepatitis D therapies. Manufacturers now design Phase II trials to satisfy both agencies' accelerated pathways simultaneously, reducing regulatory duplication. European reference pricing systems are responding by establishing early access agreements contingent on confirmatory trial outcomes.
Hospital and pharmacy benefit managers are unbundling diagnostic and therapeutic procurement, creating separate contracting streams for viral genotyping laboratories and drug dispensers. United States integrated delivery networks now negotiate directly with specialty pharmacies for 340B-discounted direct-acting antivirals, bypassing traditional wholesale distribution. This channel fragmentation is most advanced in California and New York Medicaid managed care environments.
Hepatitis Therapeutics Market Segmentation
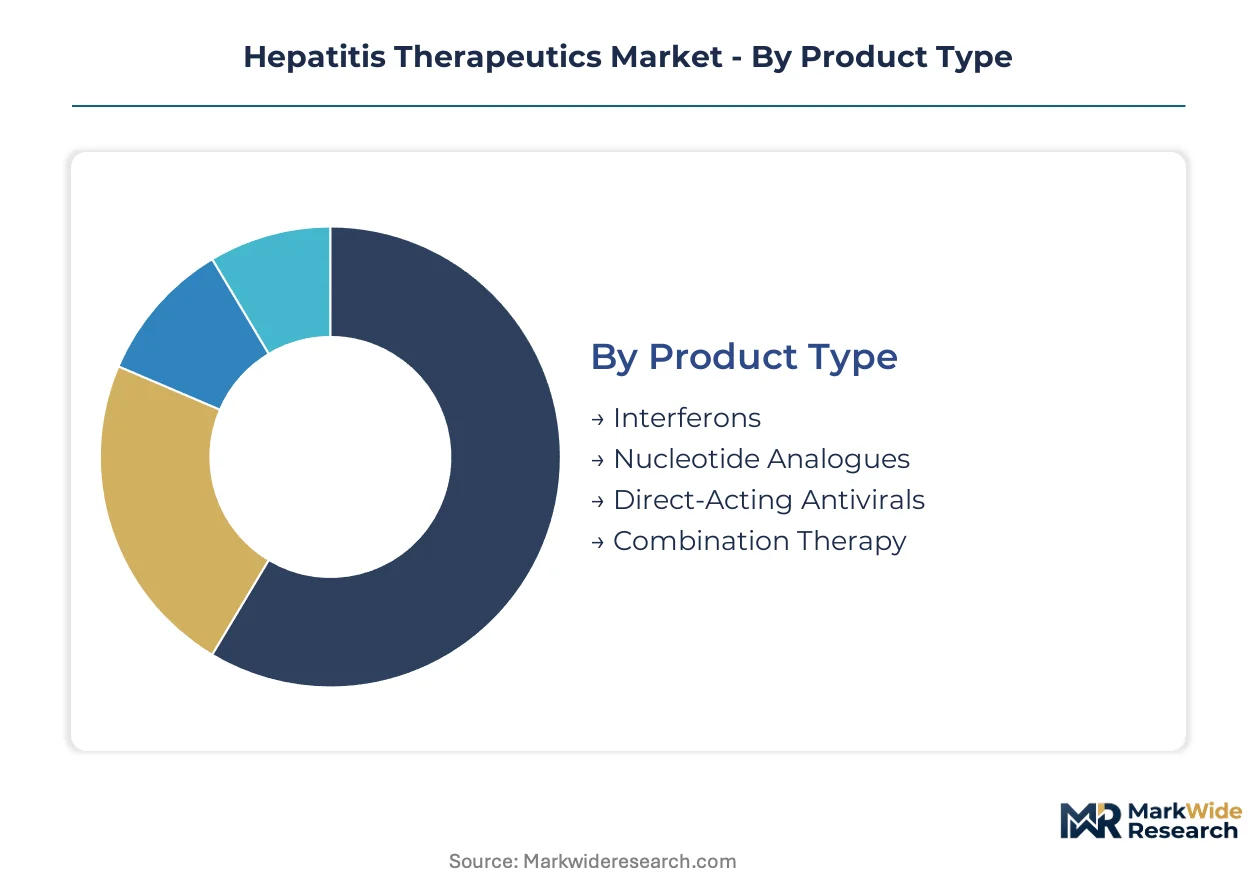
Segmentation in hepatitis therapeutics reveals how clinical utility, reimbursement pathways, and delivery infrastructure intersect to determine commercial priority. Manufacturers must align formulation decisions with specific care settings and disease etiologies to secure formulary placement and optimize patient adherence.
Product Type:
Technology differentiation across molecular mechanisms determines efficacy profiles, resistance barriers, and duration of therapy in hepatitis treatment protocols.
- Direct-Acting Antivirals:These agents target specific viral proteins—NS3/4A protease, NS5B polymerase, or NS5A—to interrupt hepatitis C replication with cure rates exceeding 95% at 12 weeks. Demand concentrates in United States Medicare and Medicaid programs where bundled reimbursement for finite-duration therapy has displaced chronic management models. Resistance-associated substitutions require genotype testing prior to selection.
- Combination Therapy:Multi-mechanism regimens pair nucleotide analogues with immunomodulators to address hepatitis B viral persistence through simultaneous suppression and immune restoration. Deployment is expanding in German and Dutch integrated care networks where telemedicine monitoring supports adherence to complex dosing schedules.
- Interferons:Immunomodulatory proteins administered via subcutaneous injection stimulate antiviral responses but carry tolerability limitations that have restricted use to salvage scenarios.
- Nucleotide Analogues:Reverse transcriptase inhibitors such as tenofovir and entecavir provide long-term viral suppression for hepatitis B through once-daily oral dosing.
Mature deployment sits with Nucleotide Analogues. Newer deployment is concentrated in Direct-Acting Antivirals.
End User:
Procurement authority and reimbursement mechanisms vary substantially across institutional settings, shaping manufacturer contracting strategies and distribution channel selection.
- Hospitals:Acute care institutions manage severe hepatitis presentations including fulminant liver failure and decompensated cirrhosis requiring inpatient monitoring. These facilities command purchasing leverage through 340B drug pricing programs in the United States, particularly in California and New York Medicaid managed care environments.
- Outpatient Facilities:Community-based centers in India and Brazil integrate point-of-care diagnostics with same-day treatment initiation, expanding access beyond specialist hepatology networks. Volume growth here is climbing the fastest as national elimination programs decentralize care.
- Clinics:Physician offices and specialty hepatology practices manage stable patients on chronic suppression therapy with periodic monitoring.
- Research Laboratories:Academic medical centers conduct Phase II and III trials for functional cure candidates, generating real-world evidence for regulatory submissions.
Procurement concentration favors Hospitals for high-cost curative regimens. Patient volume is shifting toward Outpatient Facilities.
Administration Route:
Delivery modality directly determines patient compliance economics, supervision requirements, and the feasibility of decentralized treatment models.
- Oral:Single-tablet regimens dominate hepatitis C commercial volumes due to outpatient dispensing economics and elimination of injection-related barriers. United States specialty pharmacies negotiate directly with integrated delivery networks for 340B-discounted inventory, bypassing traditional wholesale channels.
- Injectable:Subcutaneous RNA interference therapeutics enable extended-interval dosing for hepatitis B in Vietnam and Kenya, where community health workers administer quarterly injections. This delivery model compresses infrastructure requirements for national elimination programs.
- Intravenous:Hospital-administered delivery retains importance in autoimmune and alcoholic hepatitis cases requiring rapid immunosuppression or corticosteroid therapy.
- Topical:Limited application for cutaneous manifestations of hepatitis-related porphyria cutanea tarda in specialized dermatology settings.
Oral formulations capture the majority of prescription volume. Injectable platforms are gaining share fastest in resource-limited settings.
Therapy Area:
Disease etiology determines regulatory pathway, evidence requirements, and the competitive intensity of therapeutic development.
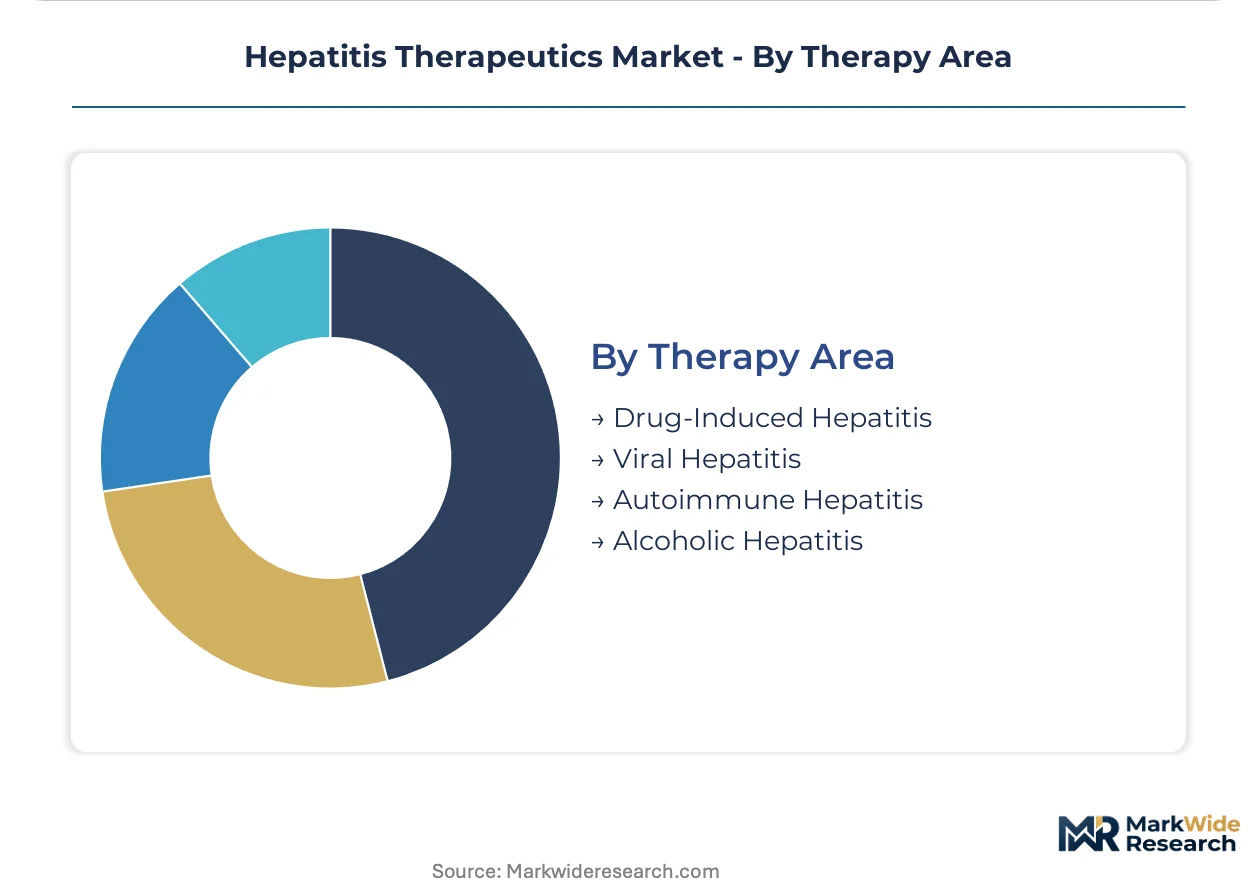
- Viral Hepatitis:Hepatitis B, C, and D infections drive the majority of pharmaceutical investment, with FDA Breakthrough Therapy and EMA PRIME designations compressing timelines for functional cure candidates. WHO prequalification shapes demand in low- and middle-income countries by determining generic direct-acting antiviral eligibility for bulk procurement.
- Autoimmune Hepatitis:Corticosteroid and azathioprine regimens require hepatology specialist oversight for monitoring of treatment response and adverse events, concentrating demand in academic medical centers with transplant capabilities.
- Alcoholic Hepatitis:Acute presentations requiring inpatient management with corticosteroids or pentoxifylline generate episodic hospital revenue rather than chronic pharmacy benefit.
- Drug-Induced Hepatitis:Causality assessment and withdrawal management predominate, with limited pharmaceutical intervention beyond supportive care and N-acetylcysteine for acetaminophen toxicity.
Clinical trial infrastructure and regulatory precedent are strongest in Viral Hepatitis. Unmet need is most acute in Autoimmune Hepatitis, where no approved therapies modify disease progression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotechnology corridor anchors pharmaceutical R&D concentration for hepatitis therapeutics, with the metropolitan area hosting dense clusters of clinical trial infrastructure and specialized hepatology research centers.
United States
Medicare bundled reimbursement for direct-acting antiviral courses drives hospital procurement consolidation. FDA Breakthrough Therapy designation compresses review timelines for hepatitis B functional cure candidates. California and New York Medicaid managed care environments pioneer 340B-discounted specialty pharmacy contracting.
Germany
Telemedicine-integrated adherence monitoring expands integrated care network capacity for complex combination regimens. EMA PRIME eligibility harmonizes evidence standards with FDA pathways for accelerated hepatitis D therapy access. The Rhine-Ruhr metropolitan region concentrates real-world evidence generation infrastructure.
India
Point-of-care diagnostics integration at community clinics enables same-day treatment initiation beyond specialist hepatology networks. CDSCO regulatory pathways and WHO prequalification determine generic direct-acting antiviral eligibility for bulk procurement. Maharashtra and Gujarat host active pharmaceutical ingredient manufacturing clusters serving global supply.
Brazil
National hepatitis elimination programs decentralize care through outpatient facility expansion in underserved municipalities. ANVISA regulatory alignment with WHO prequalification accelerates generic regimen registration. São Paulo state anchors clinical trial participation for pangenotypic single-tablet regimens.
China
Domestic nucleotide analogue production scales to meet chronic hepatitis B suppression demand across tiered hospital networks. NMPA accelerated review pathways target covalently closed circular DNA elimination approaches. The Yangtze River Delta concentrates biopharmaceutical manufacturing investment.
Hepatitis Therapeutics Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the hepatitis therapeutics value chain. The market structure consolidates around integrated pharmaceutical developers with captive manufacturing capabilities and specialized biotechnology firms pursuing novel mechanism platforms. Three archetypes dominate: originator developers of direct-acting antiviral franchises, generic manufacturers leveraging WHO prequalification for volume contracts, and emerging biotechnology specialists targeting functional cure white spaces. Competitive dynamics center on regulatory pathway execution speed and payer contracting sophistication rather than manufacturing scale alone.
Within the originator developer tier, Gilead Sciences and Bristol-Myers Squibb exemplify divergent strategic positioning—one anchored in established nucleotide analogue and direct-acting antiviral portfolios, the other representing immunomodulatory R&D intensity for hepatitis B functional cure approaches. AbbVie occupies a specialized position through interferon-free combination regimen expertise. Among generic manufacturers, Cipla and Teva Pharmaceutical Industries represent volume-scale suppliers positioned for WHO prequalification markets and 340B-discounted procurement channels.
| Leading Market Players |
|---|
| Gilead Sciences |
| Bristol-Myers Squibb |
| AbbVie |
| Merck & Co. |
| F. Hoffmann-La Roche |
| GSK |
| Cipla |
| Teva Pharmaceutical Industries |
| Lupin |
| Others |
Value Chain & Pricing Dynamics
Curative versus chronic therapy paradigms split pricing power between finite-course premium regimens and maintenance-priced generics, with supply chain configuration tracking this bifurcation through separate API sourcing clusters for originator and volume manufacturers.
Pricing Analysis
Margin tightening in originator direct-acting antiviral portfolios reflects patent cliff exposure and Indian generic entry into WHO prequalification markets. Three-tier pricing structure across premium originator, authorized generic, and unbranded commodity levels stratifies by FDA approval status and volume procurement scale. Cost-down pressure on pangenotypic single-tablet regimens accelerates because Egyptian and Indian manufacturers now qualify for Global Fund co-financing tenders. Medicare and Medicaid bundled reimbursement programs exhibit lowest price sensitivity; sub-Saharan African ministry tenders demonstrate highest.
Supply Chain Analysis
WHO prequalification and FDA approval status gate API sourcing eligibility, concentrating active pharmaceutical ingredient production in Maharashtra and Gujarat industrial corridors for generic direct-acting antivirals while originator manufacturers retain captive supply from Yangtze River Delta facilities. Key inputs include sofosbuvir intermediates, NS5A inhibitor precursors, and nucleotide analogue building blocks. Single-source vulnerability sits with Chinese contract manufacturers supplying over 70 percent of protease inhibitor raw materials. Distribution runs through 340B-discounted specialty pharmacy channels in United States integrated delivery networks and WHO prequalified bulk procurement pools in low-income countries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finite-course curative regimens create supply-constrained pricing power for manufacturers with FDA Breakthrough Therapy designation, as specialist manufacturing capacity for hepatitis B functional cure candidates remains bottlenecked by complex synthesis requirements.
For Market Incumbents: Deepen backward integration into NS5B polymerase inhibitor API production to defend margin position against Indian generic substitution pressure. Secure EMA PRIME eligibility early to compress regulatory timelines for hepatitis D combination therapies. Prioritize capacity addition in Rhine-Ruhr metropolitan region for real-world evidence generation infrastructure serving European reference pricing negotiations.
For New Entrants and Emerging Players: Capture hepatitis B functional cure white space through capsid inhibitor and siRNA platform development, where no approved therapy currently eliminates covalently closed circular DNA. Target sub-Saharan African public procurement channels for pangenotypic single-tablet regimens under WHO Global Hepatitis Strategy volume contracts. Deploy community health worker training programs as go-to-market angle for extended-interval injectable delivery in Vietnam and Kenya.
For Investors and Strategic Acquirers: Re-rating potential sits with RNA interference specialists given EMA-FDA harmonized evidence standards accelerating hepatitis B surface antigen suppression approaches. Long-term viability centers on platforms enabling functional cure rather than chronic suppression. Monitor FDA Breakthrough Therapy designation grants as inflection signal for pipeline value step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II designs satisfying both FDA and EMA accelerated pathways reduce regulatory duplication for hepatitis D therapies. |
| Regulatory Approval Pathway | EMA PRIME eligibility compresses review timelines and anchors European reference pricing negotiations. |
| Manufacturing Scale-Up | Maharashtra and Gujarat API clusters enable WHO prequalification for generic direct-acting antiviral bulk procurement. |
| Pipeline Diversification | Capsid inhibitor and siRNA approaches target covalently closed circular DNA elimination where no approved therapy exists. |
| Strategic Partnership | Telemedicine-integrated adherence monitoring partnerships expand German and Dutch integrated care network capacity. |
Study Parameters
Document review covered FDA Breakthrough Therapy designation filings, EMA PRIME eligibility decisions, WHO prequalification lists, and ClinicalTrials.gov registries, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary validation drew from CMS Medicare reimbursement databases, 340B drug pricing program disclosures, and national hepatitis elimination program procurement records. Bottom-up patient volume estimates and top-down pharmaceutical revenue benchmarks were triangulated across analysis sources.
Cross-referencing historical direct-acting antiviral adoption curves against expert panel input on hepatitis B functional cure timelines shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, administration route, therapy area, and regional regulatory cluster. CAGRs were derived from epidemiological prevalence projections, treatment rate assumptions, and pricing trajectory consensus. Forecast inputs incorporated WHO Global Hepatitis Strategy target achievement scenarios and Medicare bundled reimbursement policy stability assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA approval pathway success rates and generic entry timing in originator-protected markets. Forecasts reflect documented assumptions on sustained virologic response durability and reinfection rate stability. A model refresh is warranted upon material change in EMA conditional marketing authorization evidence requirements or WHO prequalification criteria revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Acne Therapeutics Market
Pharmaceuticals
North America Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Pharmaceutical Drug Delivery Market
Pharmaceuticals
Long-Acting Monoclonal Antibodies Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Myasthenia Gravis Therapeutics Market
Pharmaceuticals
Ciclopirox Olamine Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Global Cholera Vaccines Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Omega 3 Prescription Drugs Market