
 Hair Transplant Services Market | 2026-2036
Hair Transplant Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Transplant Services Market Foresight
Turkey is reshaping competitive dynamics in hair transplant services through its dense concentration of high-volume clinics serving cross-border patients. Bosley leverages its North American clinic network and brand recognition to sustain premium positioning across metropolitan markets. DHI Global anchors its expansion on proprietary direct implantation protocols that differentiate outcomes in saturated Asian and European cities. Aderans competes through integrated hair systems and surgical restoration under one corporate umbrella, extending service breadth beyond standalone transplant procedures.
Hair transplant services encompass surgical relocation of autologous follicular units from donor zones to areas affected by androgenetic alopecia or trauma, typically performed under local anesthesia with graft survival rates dependent on ischemia time and storage solution composition. The primary commercial purpose is permanent cosmetic restoration of hair density for patients experiencing pattern baldness. Follicular Unit Extraction dominates procedure volumes due to minimal scarring and faster recovery, though robotic hair restoration represents the fastest-growing technology segment as capital equipment costs decline and precision marketing attracts affluent demographics. Pay-per-procedure pricing still generates the largest revenue pool, but membership packages are gaining traction among chain clinics seeking recurring revenue and patient lock-in.
FDA oversight of robotic surgical devices and marketing claims for hair restoration outcomes shapes permissible promotional language and device certification pathways in the United States, while Turkey's Ministry of Health licensing requirements for medical tourism clinics establish baseline facility standards that influence international patient flows. Clinics must navigate divergent liability frameworks and advertising restrictions across jurisdictions where they solicit patients. Stakeholders should monitor regulatory harmonization efforts between medical tourism origin and destination countries, as credential reciprocity agreements could redistribute patient volumes and reshape competitive barriers.
Market Dynamics
Robotic-assisted extraction platforms are compressing procedure times and altering labor economics across hair transplant clinics, forcing traditional FUE operators to absorb capital costs or cede volume to automated competitors.
Growth Catalysts
- Medical Tourism Licensing Frameworks:Turkey's Ministry of Health facility certification standards for international patients have institutionalized cross-border patient flows and created predictable regulatory infrastructure for clinic expansion.
- Preventive Restoration Demand:Younger male demographics in their late twenties and early thirties are seeking intervention before advanced pattern baldness, expanding the addressable patient base beyond traditional late-stage candidates.
- Follicular Unit Extraction Maturation:Standardized punch sizes and motorized extraction devices have reduced operator skill barriers and shortened training curves for new technicians entering the field.
Market Restraints
- Donor Scarcity Constraints:Finite occipital donor zones impose hard limits on graft availability for advanced Norwood stage patients, restricting revenue per patient for severe cases.
- Turkish Clinic Concentration Risk:Istanbul's dense cluster of high-volume providers creates price compression and margin erosion that constrains pricing power across the European medical tourism corridor.
- FDA Device Certification Timelines:Premarket notification requirements for robotic surgical platforms delay technology diffusion and inflate compliance costs for US market entry.
Strategic Opportunities
- Membership Subscription Models:Chain clinics in metropolitan US markets are piloting annual packages combining maintenance procedures with pharmaceutical protocols to generate recurring revenue streams.
- Female Pattern Hair Loss:Underpenetrated female demographics experiencing diffuse thinning represent expansion potential as diagnostic protocols improve and marketing adapts beyond male-centric positioning.
- AI Graft Selection Algorithms:Machine learning integration with robotic systems promises to optimize follicle harvesting patterns and improve survival rates through predictive ischemia management.
Industry Challenges
- Technician Training Bottlenecks:Rapid clinic scaling in medical tourism hubs has outpaced accredited training programs for graft placement specialists, creating quality variance risks.
- Cross-Border Malpractice Jurisdiction:Patients seeking redress for unsatisfactory outcomes face fragmented legal frameworks between origin countries and Turkish surgical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Transplant Services Market |
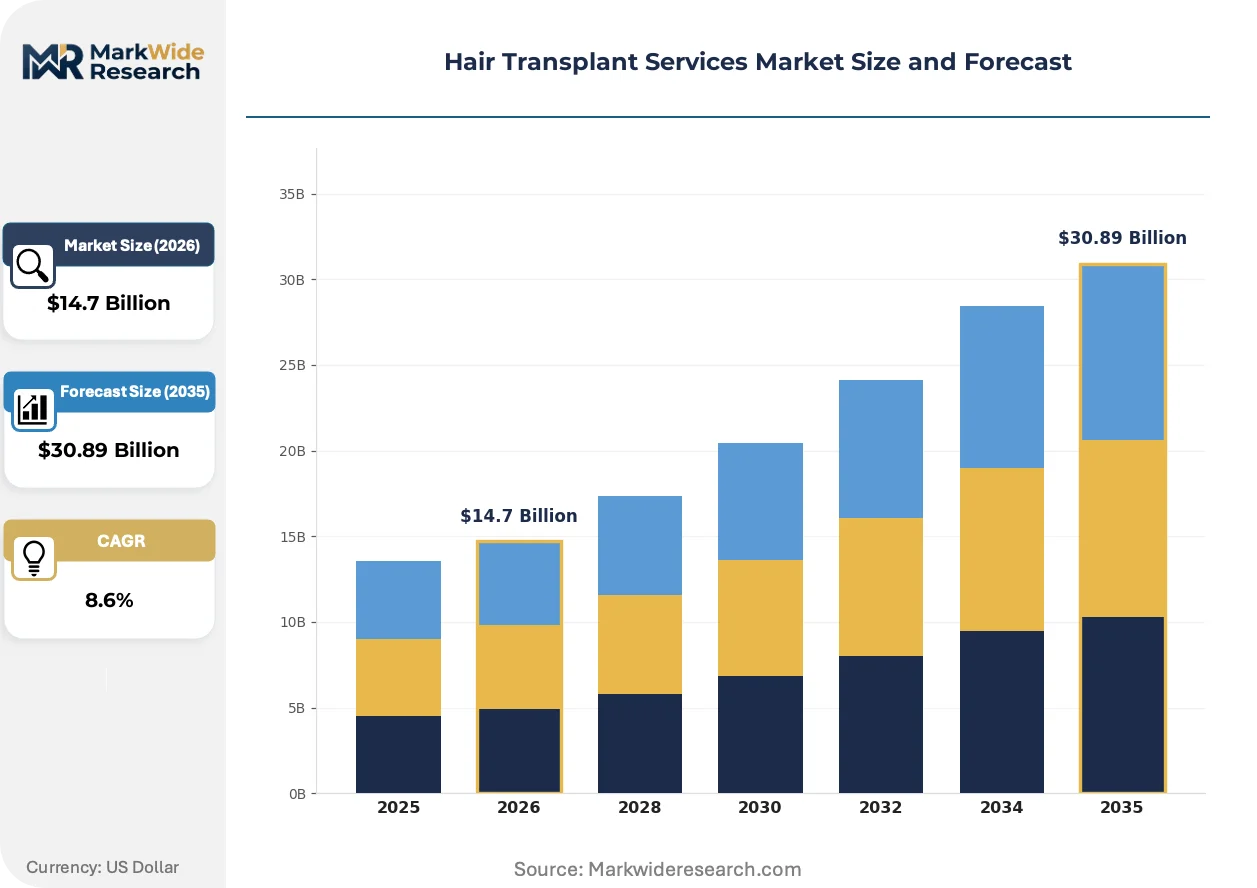
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Follicular Unit Extraction, Follicular Unit Transplantation, Robotic Hair Restoration, Scalp Micropigmentation Technology: Manual Extraction, Automated Systems, Platelet Rich Plasma, Bioenhanced Techniques End User: Clinics, Hospitals, Home Users, Research Institutions Pricing Model: Pay Per Procedure, Membership Packages, Subscription Plans, Insurance Coverage |
| Companies Covered | Bosley, DHI Global, Aderans, NeoGraft, Bernstein Medical, Venus Concept, Elite Hair Restoration, Eugenix, Hair Club, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Transplant Services Market Shifts & Advancements
Automation and algorithmic precision are displacing manual skill as the primary value driver in hair restoration, while regulatory bodies tighten oversight of outcome claims and device marketing.
Robotic hair restoration systems utilizing stereoscopic vision and AI-guided punch alignment are rendering obsolete the manual FUE approaches that dominated the previous decade. Affluent patients in Gulf states and North American metropolitan markets are demanding robotic-assisted procedures at premium price points. This technology compression is bifurcating the market into capital-intensive automated operators and cost-driven manual clinics.
REACH compliance requirements for surgical device materials and the EU Medical Device Regulation are tightening traceability standards for implantation instruments and storage solutions sold into European markets. Manufacturers must now document biocompatibility testing for graft preservation media and extraction punches. German and French clinic chains are consolidating supplier relationships to reduce compliance fragmentation across their networks.
Patients are increasingly researching providers through social media outcome documentation and peer review platforms before committing to cross-border travel. This transparency shift is compressing the traditional referral channel dominance of dermatologists and general practitioners. Turkish clinics with established influencer partnerships and verified patient video portfolios are capturing disproportionate inquiry volumes from Middle Eastern and African source markets.
Hair Transplant Services Market Segmentation
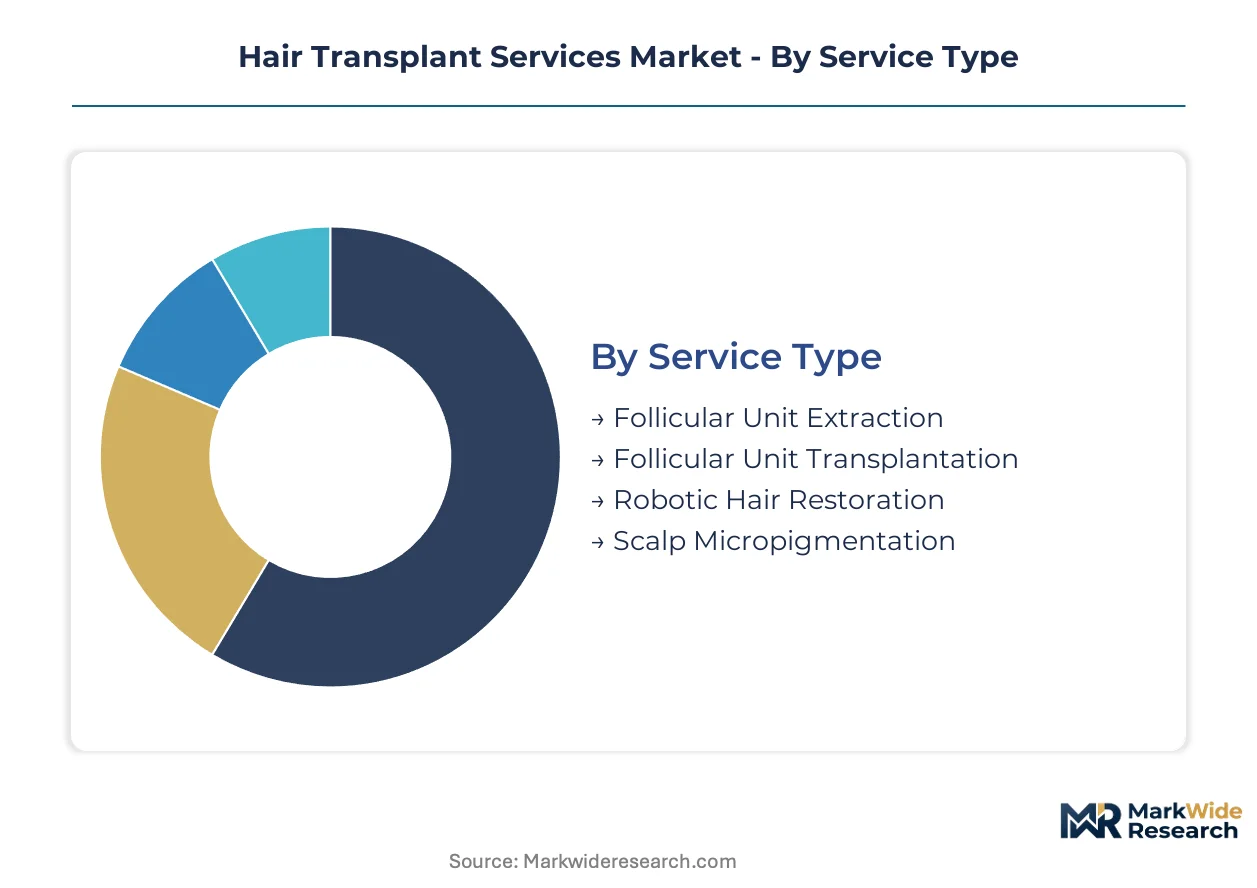
Hair transplant services fragment across four distinct dimensions that determine capital requirements, regulatory exposure, and patient acquisition economics. Service type and technology choices define clinical workflows and margin structures, while pricing model selection separates volume-driven operators from relationship-based practices.
Service Type:
Mature extraction methods dominate procedure volumes, yet emerging robotic platforms are compressing labor costs and expanding addressable patient bases.
- Follicular Unit Extraction:Individual follicular units are harvested via micro-punch tools from donor zones, leaving minimal scarring. Istanbul clinics process thousands of FUE procedures monthly for medical tourists from Germany, the UK, and Gulf states, with Turkish Ministry of Health facility certifications enabling predictable cross-border patient flows.
- Robotic Hair Restoration:Stereoscopic vision systems with AI-guided punch alignment automate follicle harvesting and placement. Affluent demographics in Saudi Arabia and the UAE demand robotic-assisted procedures at premium price points, compressing manual FUE margins across metropolitan Gulf markets.
- Follicular Unit Transplantation:Strip harvesting from donor zones enables high graft yields in single sessions. Remains relevant for advanced Norwood stage patients with extensive baldness requiring maximum follicle density.
- Scalp Micropigmentation:Cosmetic tattooing creates the appearance of shaved hair density. Appeals to patients seeking non-surgical alternatives or complementing surgical results with visual density enhancement.
Follicular Unit Extraction retains volume leadership; Robotic Hair Restoration holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive automated platforms from labor-dependent manual approaches, with biological adjuvants commanding premium positioning.
- Manual Extraction:Technician-operated punch tools require substantial training investment and exhibit operator-dependent outcome variance. Turkish high-volume clinics deploy armies of technicians to maintain throughput on manual systems.
- Automated Systems:Motorized extraction devices standardize punch depth and rotation speed, reducing skill barriers for new technicians entering the field.
- Platelet Rich Plasma:Autologous blood concentrate injections stimulate graft survival and post-procedure healing. US metropolitan clinics bundle PRP with surgical procedures to differentiate premium service tiers.
- Bioenhanced Techniques:Graft preservation media and storage solutions improve ischemia tolerance during extraction-to-implantation intervals. REACH compliance requirements for surgical device materials tighten traceability standards for European market entry.
Manual Extraction maintains installed base dominance; Bioenhanced Techniques are climbing the fastest as regulatory scrutiny intensifies on graft handling protocols.
End User:
Customer type determines capital intensity, with institutional operators absorbing device costs while individual practitioners seek flexible service arrangements.
- Clinics:Dedicated hair restoration facilities concentrate procedure volume and amortize robotic capital across high patient throughput. Chain clinics in US metropolitan markets pilot membership packages combining maintenance procedures with pharmaceutical protocols.
- Hospitals:Integrated surgical departments offer transplant services alongside dermatology and plastic surgery units. Academic medical centers in Germany and France train fellows on standardized protocols.
- Home Users:Topical pharmaceutical protocols and low-level laser devices address early-stage thinning. FDA oversight of marketing claims restricts promotional language for at-home hair restoration outcomes.
- Research Institutions:Universities and biotechnology firms investigate stem cell-based follicle regeneration and cloning techniques. Preclinical programs in Japan and South Korea explore next-generation hair multiplication protocols.
Clinics command the largest revenue pool; Research Institutions are gaining share fastest as regenerative medicine pipelines mature.
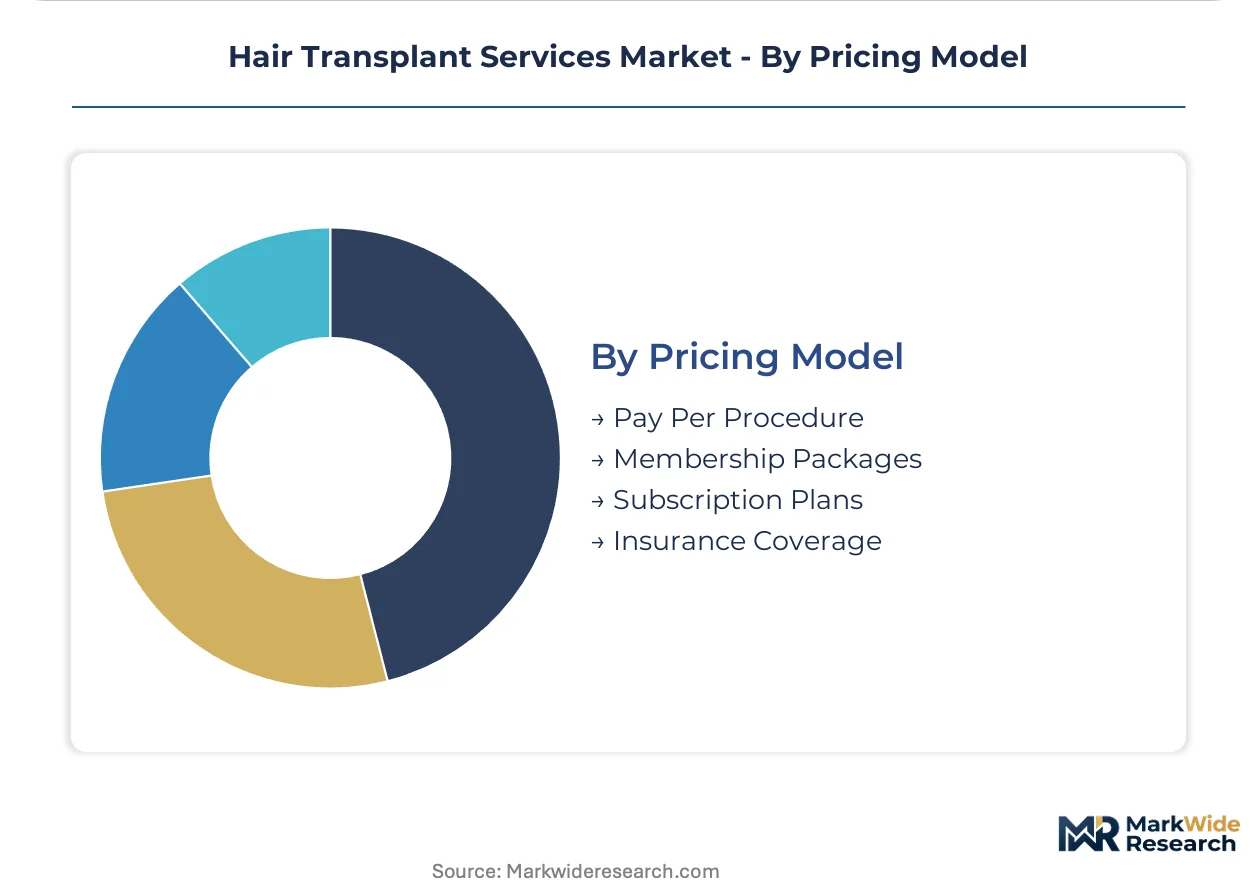
Pricing Model:
Margin structure separates transactional procedure economics from recurring revenue architectures that improve patient lifetime value.
- Pay Per Procedure:Single-transaction pricing dominates medical tourism corridors where patients seek discrete surgical interventions. Turkish clinics compete on transparent per-graft pricing visible on digital platforms.
- Membership Packages:Annual contracts bundle surgical procedures with maintenance treatments and pharmaceutical protocols. North American chain clinics deploy subscriptions to generate predictable recurring revenue.
- Subscription Plans:Monthly payment structures spread costs across extended periods, reducing upfront barriers for younger demographics seeking preventive restoration.
- Insurance Coverage:Limited reimbursement applies to trauma-related or reconstructive cases, with most cosmetic procedures excluded from standard health benefit plans.
Pay Per Procedure retains transaction volume leadership; Membership Packages demonstrate the steepest expansion trajectory as clinics pursue patient lock-in.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's Ministry of Health facility certification standards anchor the dominant geography, institutionalizing cross-border patient flows through predictable regulatory infrastructure that redistributes procedure volumes across international corridors.
United States
Affluent demographics in metropolitan markets demand robotic-assisted procedures at premium price points, compressing manual FUE margins across Gulf Coast and Northeast corridors. FDA premarket notification requirements for robotic surgical platforms delay technology diffusion and inflate compliance costs for device manufacturers. Bosley leverages its clinic network across Los Angeles, New York, and Miami to sustain premium positioning through brand recognition and metropolitan density.
Turkey
Istanbul's dense cluster of high-volume providers serves international medical tourists from Germany, the UK, and Gulf states, creating price compression across the European medical tourism corridor. Ministry of Health licensing requirements for medical tourism clinics establish baseline facility standards that influence patient flows. Hundreds of specialized clinics in Istanbul alone process thousands of FUE procedures monthly, with verified patient video portfolios capturing disproportionate inquiry volumes from Middle Eastern and African source markets.
Germany
Academic medical centers in Berlin and Munich train fellows on standardized protocols, extending influence across European technique adoption. REACH compliance requirements for surgical device materials tighten traceability standards for implantation instruments and storage solutions. German clinic chains consolidate supplier relationships to reduce compliance fragmentation across their networks, with Baden-Württemberg and Bavaria hosting concentrated restoration facilities.
Saudi Arabia
Affluent male demographics in Riyadh and Jeddah demand robotic-assisted procedures, driving premium price points that exceed manual FUE rates by substantial margins. SFDA oversight of medical device marketing shapes permissible promotional language for surgical outcomes. Dubai-based influencers and verified patient documentation on social media platforms redirect substantial inquiry volumes toward Turkish providers, though domestic clinics in the Eastern Province absorb preventive restoration demand from younger demographics.
India
Younger male demographics in Mumbai and Delhi seek preventive restoration before advanced pattern baldness, expanding the addressable patient base beyond traditional late-stage candidates. CDSCO regulation of surgical device imports creates compliance barriers for robotic platform entry. Eugenix and domestic clinic chains in Maharashtra and Karnataka compete on transparent per-graft pricing visible on digital platforms, with membership packages piloting among metropolitan operators to generate recurring revenue.
Hair Transplant Services Market Competitive Landscape
Capability concentration sits with technology-integrated chains that absorb capital costs for robotic platforms; scale advantage sits with high-volume manual operators in medical tourism corridors that amortize labor across thousands of monthly procedures. The market structure bifurcates into capital-intensive automated operators and cost-driven manual clinics, with neither tier achieving dominant consolidation. Three archetypes define competitive positioning: North American brand-network chains, Turkish volume-specialist aggregators, and Asian technique-differentiated boutiques. Dominant competitive moves include geographic expansion through clinic licensing and portfolio diversification into adjacent hair systems and pharmaceutical protocols.
Within the brand-network tier, Bosley and Hair Club anchor premium positioning across US metropolitan markets through clinic density and recognition. DHI Global exemplifies technique-differentiated expansion, occupying a position in saturated Asian and European cities through proprietary protocols. Aderans represents integrated-service breadth, extending beyond standalone transplant procedures to encompass hair systems under one corporate umbrella. These three players illustrate how competitive advantage fragments across distinct capability vectors rather than concentrating in unified market leadership.
| Leading Market Players |
|---|
| Bosley |
| DHI Global |
| Aderans |
| NeoGraft |
| Bernstein Medical |
| Venus Concept |
| Elite Hair Restoration |
| Eugenix |
| Hair Club |
| Others |
Supply & Pricing Matrix
Single-source dependency on Turkish Ministry of Health-licensed clinics for high-volume FUE procedures compresses margin spreads across European medical tourism corridors and forces supply chain concentration into Istanbul's dense provider cluster. This geographic chokepoint simultaneously enables transparent per-graft pricing visibility on digital platforms and constrains pricing power through intense local competition.
Pricing Analysis
Istanbul clinics command per-graft rates substantially below metropolitan US markets, creating a three-tier pricing structure across premium robotic-assisted, standard manual FUE, and economy high-volume tiers. Price differentiation rests on technology certification level—FDA-cleared robotic platforms versus manual systems—and geographic delivery cost arbitrage between medical tourism destinations and domestic metropolitan markets. Pricing pressure stems from Istanbul's clinic concentration, which forces transparent digital competition. Price-sensitive patients in Germany and the UK drive volume toward Turkish providers, while affluent Gulf state demographics show lowest sensitivity and demand premium robotic tiers.
Supply Chain Analysis
Extended payment terms from Turkish clinic aggregators to technician staffing agencies characterize supplier financing in this labor-intensive sector. Equipment supply concentrates in the United States, Germany, and South Korea for robotic platforms and motorized extraction devices. Raw material dependencies include surgical steel punches, graft preservation media, and local anesthetic formulations. Supply chain risk centers on single-source vulnerability for robotic system maintenance and proprietary software updates. Distribution runs through direct clinic procurement for capital equipment and regional pharmaceutical distributors for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits defensive moats through regulatory entrenchment: Ministry of Health facility certifications and FDA device clearances create multi-year barriers that protect incumbent positioning against rapid competitive entry.
For Market Incumbents: Insulate market position by deepening backward integration into technician training academies to lock in skilled labor supply and secure graft placement quality consistency. Pursue CE marking investment for robotic platform portfolios to preempt EU Medical Device Regulation compliance barriers. The emerging threat of AI-guided diagnostic tools from consumer technology entrants demands proactive certification investment to maintain clinical credibility. For New Entrants and Emerging Players: Pursue female pattern hair loss as the most penetrable demographic expansion vector, where diagnostic protocol gaps and male-centric marketing create white-space opportunity. Target membership subscription models in North American metropolitan markets where recurring revenue architectures remain underdeveloped. A direct-to-consumer digital acquisition channel leveraging verified patient video portfolios offers the strongest go-to-market angle against established referral networks. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors capital-intensive automated operators with installed robotic base and regulatory clearance runway. Long-term viability over the coming decade hinges on consolidation economics in medical tourism hubs and recurring revenue capture in metropolitan markets. Acquisition targets should demonstrate Ministry of Health certification and established Middle Eastern patient flow. The signal to watch is FDA clearance timelines for next-generation AI-integrated robotic platforms as inflection indicator for technology-leader repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Platform Certification | FDA and CE marking pathways determine competitive access to premium pricing tiers in US and EU markets. |
| Technician Training Academy Development | In-house graft placement programs reduce quality variance risks and accelerate clinic scaling velocity. |
| Membership Subscription Launch | Annual contracts combining procedures with pharmaceutical protocols generate predictable recurring revenue streams. |
| Female Diagnostic Protocol Investment | Diffuse thinning assessment tools unlock underpenetrated demographics beyond male pattern baldness. |
| Medical Tourism Licensing Expansion | Ministry of Health facility certifications institutionalize cross-border patient flows and regulatory credibility. |
Research Methodology
Desk research of FDA 510(k) filings, Turkish Ministry of Health facility registries, and EU Medical Device Regulation compliance databases preceded structured interviews with clinic chain operations directors, robotic platform biomedical engineers, and medical tourism patient coordinators. Secondary validation drew from hospital procurement databases, GPO contract repositories, and customs records for surgical device imports. Bottom-up procedure volume estimates triangulated against top-down market sizing from capital equipment installation bases.
Assumptions around robotic platform adoption velocity and medical tourism corridor stability were held fixed across baseline scenarios, while pricing tier compression and regulatory harmonization timelines were stress-tested. The analytical framework segmented by service type, technology tier, end-user facility class, and pricing model architecture across the projection horizon. CAGRs were derived from equipment shipment trajectories and clinic expansion pipelines. Forecast inputs incorporated graft survival rate improvements from bioenhanced storage solutions and AI-guided punch alignment maturation.
Sensitivities concentrate around FDA premarket notification delays, Turkish lira volatility effects on medical tourism pricing, and technician training program accreditation bottlenecks. Forecasts reflect documented assumptions regarding robotic capital cost decline curves and cross-border malpractice jurisdiction evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Sterilization Services Market
Healthcare Services
IVD Contract Manufacturing Services Market
Healthcare Services
Global Geriatric Care Services Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Contract Manufacturing Organization (CMO) Market
Healthcare Services
UK Pharmaceutical Logistics Market
Healthcare Services
US Concierge Medicine Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
In-Home Senior Care Franchises Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Medical Transcription Services Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Kids Sports Injury Treatment Market
Healthcare Services
Canada Corporate Wellness Market
Healthcare Services
United States Senior Living Market
Healthcare Services
Global Urgent Care Center Market