
 Rhabdomyosarcoma Market | 2026-2036
Rhabdomyosarcoma Market Size, Share, and Industry Trends Forecast 2026-2036
Rhabdomyosarcoma Market Outlook
Good Manufacturing Practice certification for oncology biologics is rotating the competitive landscape toward manufacturers with validated sterile production lines. Novartis AG leverages its CAR-T infrastructure to anchor rhabdomyosarcoma cell therapy development. Pfizer Inc. sustains clinical momentum through broad pediatric oncology portfolios. Bristol Myers Squibb Company differentiates via checkpoint inhibitor combinations in soft tissue sarcoma trials.
Rhabdomyosarcoma comprises malignant tumors of skeletal muscle origin, classified histologically into embryonal and alveolar subtypes with distinct FOXO1 fusion statuses guiding risk stratification. These neoplasms primarily arise in pediatric populations, demanding multimodal treatment protocols combining systemic therapy with local control measures. Chemotherapy occupies the dominant revenue position across product types due to frontline reliance on vincristine-dactinomycin-cyclophosphamide regimens. Targeted therapy represents the fastest-expanding segment as molecular profiling identifies actionable alterations in relapsed cases. Pediatric hospitals command the principal end-user margin pool given concentration of specialized multidisciplinary care.
FDA orphan drug incentives and EMA pediatric investigation plans shape trial design and commercial exclusivity timelines across the development pipeline. The country's national pharmaceutical regulator in Japan, PMDA, enforces comparable pediatric study requirements that filter market entry for new agents. Stakeholders must monitor biomarker-driven trial eligibility criteria that are fragmenting addressable populations across fusion-positive and fusion-negative disease subsets.
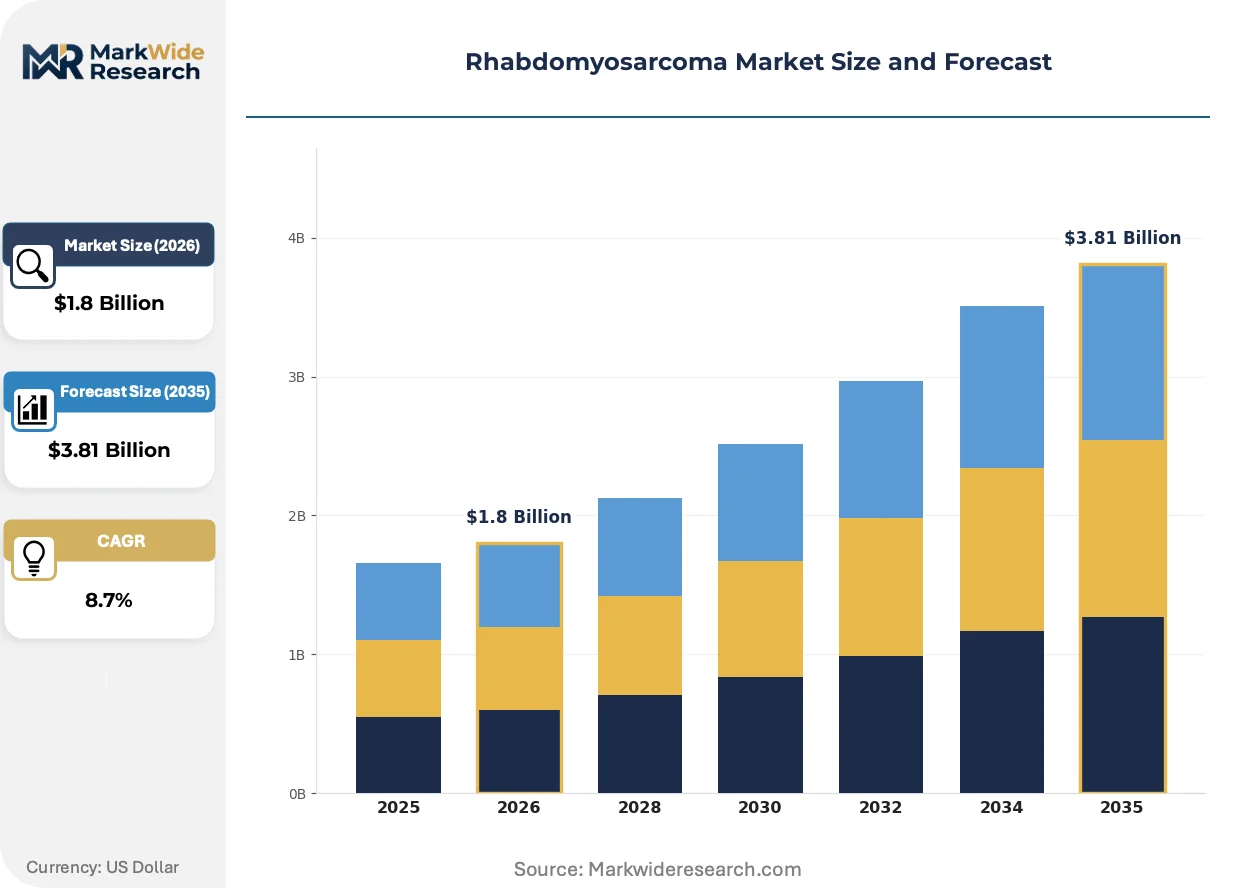
Market Dynamics
Combination therapy protocols are compressing treatment timelines and reshaping competitive positioning across pediatric oncology centers, forcing manufacturers to align clinical development with vincristine-dactinomycin-cyclophosphamide backbone compatibility.
Growth Catalysts
- FDA Orphan Drug Designation:The FDA's orphan drug incentives reduce trial costs and accelerate commercial exclusivity timelines for sponsors targeting fusion-positive subtypes.
- Pediatric Hospital Infrastructure:Specialized multidisciplinary care centers in the United States and Germany are consolidating patient volumes and driving protocol standardization.
- Biomarker-Guided Stratification:FOXO1 fusion status testing is segmenting addressable populations and enabling precision trial enrollment criteria.
Market Restraints
- Cold Chain Logistics Costs:Cell therapy candidates require validated cryogenic distribution networks that inflate per-dose delivery expenses.
- Single-Source API Concentration:Cyclophosphamide active pharmaceutical ingredient production clusters in China, creating geopolitical supply vulnerability.
- EMA Pediatric Investigation Plan Rigor:The European Medicines Agency's mandatory pediatric study requirements extend development timelines by 18-24 months for adult-onset agents.
Strategic Opportunities
- Relapsed/Refractory White Space:Second-line and later treatment settings lack approved targeted options, creating entry opportunity for molecularly-guided therapies.
- Japan Market Access:PMDA's comparable pediatric study requirements filter competition, rewarding early regulatory engagement with five-year exclusivity potential.
- CAR-T Manufacturing Convergence:Autologous cell therapy platforms from solid tumor applications are adapting infrastructure toward rhabdomyosarcoma antigen targets.
Industry Challenges
- Pediatric Trial Recruitment Bandwidth:Limited patient pools across fusion-negative and fusion-positive strata strain site activation timelines.
- Cross-Border Sample Logistics:Centralized biomarker testing requires harmonized material transfer agreements between United States and European academic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rhabdomyosarcoma Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Surgery, Radiation Therapy, Targeted Therapy End User: Pediatric Hospitals, Oncology Clinics, Research Institutions, Diagnostic Labs Therapy Area: Soft Tissue Sarcoma, Bone Sarcoma, Rare Cancers, Solid Tumors Treatment Stage: Initial, Adjuvant, Neoadjuvant, Advanced |
| Companies Covered | Novartis AG, Oasmia Pharmaceutical, Boehringer Ingelheim International GmbH, Celgene Corporation, Bellicum Pharmaceuticals, Inc., Pfizer Inc., Bristol Myers Squibb Company, Eisai Co., Ltd., Eli Lilly & Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rhabdomyosarcoma Market Strategic Shifts
Molecular profiling technologies are fragmenting historical histological classifications and enabling subtype-specific development strategies across the therapeutic pipeline.
Next-generation sequencing panels are supplanting conventional immunohistochemistry as the frontline diagnostic modality for fusion status determination. Pediatric oncology centers in the United States and Germany are adopting comprehensive genomic profiling within 72 hours of diagnosis. This shift is compressing time-to-treatment initiation and disqualifying patients from histology-only trials.
EMA's pediatric investigation plan mandates now require sponsors to submit age-appropriate formulation development strategies prior to Phase II initiation. This regulatory friction is diverting formulation resources toward oral liquid and mini-tablet presentations. Small-molecule developers targeting the United States and European Union simultaneously are sequencing submissions to align with these staggered requirements.
Academic medical centers are consolidating procurement authority through national pediatric oncology cooperative group networks. Traditional distributor relationships are yielding to direct manufacturer-contracting with Children's Oncology Group and Société Internationale d'Oncologie Pédiatrique. This concentration is most advanced in Germany, where university hospital alliances negotiate pan-European tender terms.
Rhabdomyosarcoma Market Segmentation
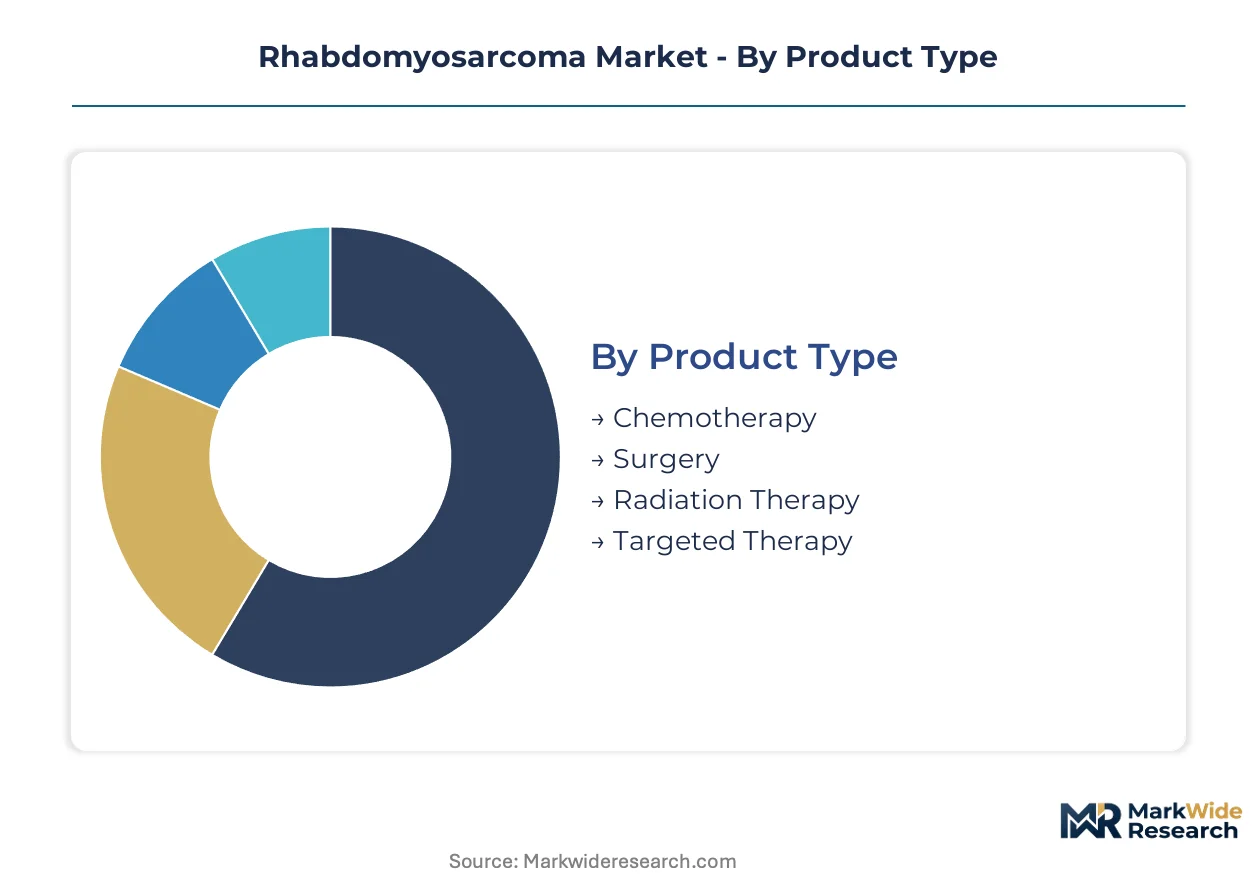
Molecular stratification is fragmenting addressable populations across rhabdomyosarcoma subtypes. Treatment protocols now demand segment-specific development strategies that align with fusion status testing and pediatric regulatory requirements.
Product Type:
Margin pools concentrate in systemic therapy modalities where frontline protocols generate recurring revenue across multi-year treatment courses.
- Chemotherapy:Vincristine-dactinomycin-cyclophosphamide regimens constitute the backbone of first-line pediatric protocols. Demand concentrates in United States pediatric hospitals where Children's Oncology Group standards govern protocol selection and reimbursement.
- Targeted Therapy:Small-molecule inhibitors and antibody-drug conjugates address relapsed fusion-positive disease through actionable kinase alterations. Germany's university hospital networks are expanding molecular tumor board adoption, accelerating precision therapy enrollment.
- Surgery:Local control measures complement systemic approaches for resectable primary tumors.
- Radiation Therapy:Proton beam facilities in specialized pediatric centers reduce late toxicity profiles compared to conventional photon delivery.
Chemotherapy holds installed capacity across frontline treatment slots. Targeted therapy is rotating up the share rankings as biomarker testing expands.
End User:
Volume gravitates toward centers with multidisciplinary infrastructure capable of coordinating complex pediatric oncology protocols.
- Pediatric Hospitals:Comprehensive cancer centers integrate surgical, medical, and radiation oncology with dedicated pediatric pharmacy compounding. United States academic medical centers command the principal patient volumes through Children's Oncology Group membership.
- Oncology Clinics:Community-based infusion centers handle stable maintenance chemotherapy for localized disease. Germany's regional pediatric oncology networks delegate lower-acuity care to certified satellite clinics.
- Research Institutions:Early-phase trial sites concentrate in major metropolitan academic corridors.
- Diagnostic Labs:Centralized reference laboratories process FOXO1 fusion testing for community hospitals lacking in-house molecular pathology.
Pediatric hospitals retain the deepest protocol penetration. Oncology clinics are rotating up the share rankings as maintenance therapy decentralizes.
Therapy Area:
Commercial development resources track toward indications with defined regulatory pathways and established cooperative group infrastructure.
- Soft Tissue Sarcoma:Rhabdomyosarcoma sits within this broader histological category, sharing trial eligibility with other pediatric sarcoma subtypes. EMA's pediatric investigation plan requirements apply uniformly across this classification.
- Rare Cancers:Orphan drug incentives from FDA and Japan's PMDA accelerate development timelines for sponsors targeting fusion-positive subpopulations.
- Bone Sarcoma:Distinct skeletal malignancies with separate cooperative group trial portfolios.
- Solid Tumors:Broad basket trial designs include rhabdomyosarcoma alongside other extracranial malignancies.
Soft tissue sarcoma holds installed capacity across cooperative group trial design. Rare cancers are rotating up the share rankings as orphan incentives attract sponsor investment.
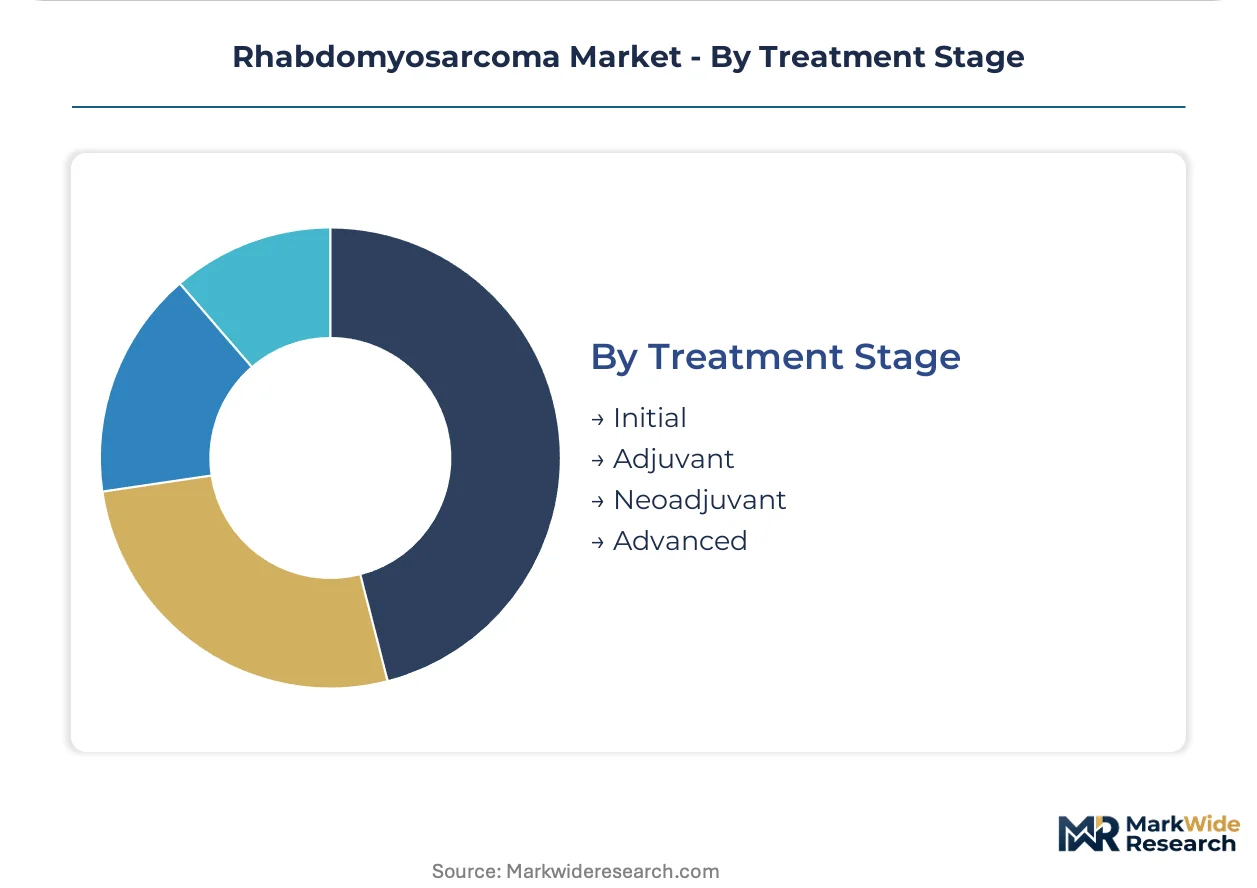
Treatment Stage:
Development pipelines stratify across risk-adapted protocols that compress or extend therapy intensity based on disease presentation.
- Initial:Intensive multi-agent induction regimens aim for rapid cytoreduction in newly diagnosed patients. United States pediatric hospitals standardize on Children's Oncology Group risk stratification protocols.
- Adjuvant:Consolidation therapy follows local control measures to address micrometastatic disease. Germany's Société Internationale d'Oncologie Pédiatrique-affiliated centers emphasize protocol adherence in this setting.
- Neoadjuvant:Preoperative systemic therapy reduces tumor burden to enable complete surgical resection.
- Advanced:Metastatic and relapsed disease settings lack approved targeted therapies, creating white space for molecularly-guided candidates.
Initial treatment holds installed capacity across frontline enrollment. Advanced disease settings are rotating up the share rankings as relapsed indications drive pipeline prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric oncology centers concentrate patient volumes in markets with established cooperative group infrastructure and orphan drug incentive frameworks. The United States and Germany anchor clinical trial density, while Japan and the United Kingdom expand biomarker-guided protocol adoption. Regulatory harmonization across FDA, EMA, and PMDA jurisdictions shapes cross-border development timelines.
United States
Children's Oncology Group membership drives protocol standardization across academic medical centers. FDA orphan drug designation accelerates commercial exclusivity timelines for fusion-positive subtypes. Boston and New York metropolitan corridors concentrate early-phase trial sites with centralized FOXO1 testing capabilities.
Germany
Société Internationale d'Oncologie Pédiatrique-affiliated university hospitals negotiate pan-European tender terms for combination chemotherapy. EMA pediatric investigation plan requirements filter market entry for adult-onset agents. Heidelberg and Berlin clusters lead molecular tumor board adoption for precision therapy enrollment.
Japan
PMDA's comparable pediatric study requirements reward early regulatory engagement with extended exclusivity windows. Domestic pharmaceutical sponsors prioritize oral liquid formulation development for age-appropriate dosing. Tokyo and Osaka academic centers consolidate relapsed/refractory trial recruitment.
United Kingdom
NHS specialized commissioning frameworks concentrate rhabdomyosarcoma care in designated pediatric principal treatment centers. MHRA alignment with EMA pediatric investigation plan timelines streamlines parallel submission strategies. London and Manchester hubs integrate next-generation sequencing into diagnostic pathways within 72 hours.
Canada
Health Canada pediatric regulatory pathways align with FDA orphan drug incentive structures for cross-border trial participation. Provincial health technology assessment bodies evaluate proton beam therapy coverage for local control measures. Toronto and Vancouver academic networks coordinate biomarker sample logistics with United States cooperative groups.
Rhabdomyosarcoma Market Competitive Environment
Player mix skews toward large-cap pharmaceutical conglomerates with established pediatric oncology portfolios and cell therapy infrastructure. Market structure consolidates around sponsors capable of navigating multi-jurisdictional regulatory requirements simultaneously. Three archetypes dominate: CAR-T platform operators leveraging autologous cell therapy manufacturing, checkpoint inhibitor specialists pursuing soft tissue sarcoma combinations, and precision oncology developers targeting actionable kinase alterations. Competitive moves center on strategic partnerships with cooperative group networks and backward integration into sterile biologics production.
Among Swiss-headquartered conglomerates, Novartis AG occupies a position exemplifying CAR-T infrastructure deployment toward pediatric solid tumor applications. Pfizer Inc. and Bristol Myers Squibb Company represent the large-cap archetype with broad oncology portfolios capable of sustaining clinical momentum across combination protocol development. These three entities anchor the competitive set through distinct platform strategies rather than overlapping therapeutic modalities.
| Leading Market Players |
|---|
| Novartis AG |
| Oasmia Pharmaceutical |
| Boehringer Ingelheim International GmbH |
| Celgene Corporation |
| Bellicum Pharmaceuticals, Inc. |
| Pfizer Inc. |
| Bristol Myers Squibb Company |
| Eisai Co., Ltd. |
| Eli Lilly & Company |
| Others |
Value Chain & Pricing Dynamics
Proton beam therapy substitution for conventional photon delivery is redrawing procurement geography across pediatric radiation oncology, simultaneously elevating capital equipment pricing in United States academic medical centers while compressing reimbursement margins for photon-only facilities. This modality shift concentrates purchasing authority through Children's Oncology Group-affiliated institutions capable of justifying superconducting cyclotron investments.
Pricing Analysis
Cost-plus contracts with pharmaceutical price indexation govern cyclophosphamide and vincristine procurement across United States pediatric hospitals. Three-tier pricing structure across premium CAR-T, standard chemotherapy, and economy supportive care separates Novartis AG's autologous cell therapy from generic alkylating agents. Price differentiation hinges on FDA orphan drug exclusivity windows and GMP certification tiers. Margins are tightening in frontline chemotherapy due to cooperative group tender consolidation, while relapsed/refractory targeted therapy commands premium positioning.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo trade lanes has inflated inbound logistics costs for cyclophosphamide API sourced from Chinese manufacturers. Active pharmaceutical ingredient production clusters in China and India, with fill-finish capacity concentrated in Germany and the United States. Supply chain risk centers on single-source API concentration for ifosfamide precursors. Distribution runs through national pediatric oncology cooperative group networks rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where biomarker testing and companion diagnostic protocols expand recurring revenue faster than drug substance margins alone.
For Market Incumbents: Compound clinical data assets through backward integration into FOXO1 fusion testing infrastructure, capturing diagnostic-to-therapeutic patient flow. Defend position by securing exclusive supply agreements with Children's Oncology Group procurement committees before formulary standardization completes. Threat vector: CAR-T platform operators leveraging autologous manufacturing scale to undercut pricing in relapsed settings. For New Entrants and Emerging Players: Relapsed/refractory molecular profiling services represent the most penetrable white space where incumbents under-serve community oncology clinics lacking in-house NGS capabilities. Target Germany's regional pediatric networks through Société Internationale d'Oncologie Pédiatrique tender participation. Go-to-market angle: 72-hour turnaround fusion status reporting enabling trial enrollment velocity. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision oncology developers with validated pediatric regulatory pathways. Long-term viability over the next decade rests on biomarker-driven addressable population expansion rather than histology-only label expansion. Acquisition target archetype: small-molecule developers with PMDA pediatric investigation plan alignment. Signal to watch: EMA pediatric investigation plan approval velocity as inflection indicator for commercial exclusivity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA orphan drug designation accelerates fusion-positive subtype enrollment timelines. |
| Regulatory Approval Pathway | PMDA pediatric study requirements reward early engagement with extended exclusivity windows. |
| Manufacturing Scale-Up | GMP-certified sterile biologics production anchors competitive positioning in cell therapy. |
| Pipeline Diversification | Checkpoint inhibitor combinations in soft tissue sarcoma trials expand addressable indications. |
| Strategic Partnership | Cooperative group network contracts concentrate procurement authority in pediatric hospitals. |
Study Parameters
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base. Primary interview data combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation cross-verified segment estimates.
Sensitivity analysis tested forecast robustness across the projection horizon. Segmentation dimensions modeled include treatment line, dosage form, patient population, and regional regulatory cluster. CAGRs derived from epidemiological incidence projections, protocol penetration curves, and pricing elasticity assumptions. Forecast inputs incorporated biomarker testing adoption rates and cooperative group protocol amendment timelines.
Forecasts assume regulatory continuity in FDA, EMA, and PMDA jurisdictions; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Americas Gerd and Nerd Treatment Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Global Breast Cancer Therapeutics Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Hypopigmentation Disorder Treatment Market
Specialty Medicine
Thyroid Cancer Therapeutics Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market