
 Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market | 2026-2036
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market Outlook
FDA Breakthrough Therapy designation and EMA PRIME eligibility is bifurcating which developers can secure accelerated review for novel CIDP therapies. CSL Behring leverages its plasma fractionation infrastructure to sustain stable immunoglobulin supply across multiple continents. Grifols dominates European collection center networks, while Takeda specializes in subcutaneous delivery innovations that reduce hospital dependency for chronic patients.
Chronic inflammatory demyelinating polyneuropathy treatment encompasses immunomodulatory and immunosuppressive interventions targeting autoimmune peripheral nerve demyelination, with intravenous immunoglobulin requiring 10% protein concentration and pH 4.0-4.5 for stable infusion. The primary purpose is to arrest progressive weakness, restore conduction velocity, and maintain functional mobility in patients with recurrent or sustained demyelination. Intravenous immunoglobulin commands the largest revenue pool due to established reimbursement and physician familiarity, though subcutaneous delivery is expanding fastest as homecare infrastructure matures. Corticosteroids retain significant first-line use in resource-constrained settings where biologic access remains limited.
FDA, EMA, and WHO prequalification standards collectively shape immunoglobulin manufacturing purity thresholds, viral inactivation protocols, and lot-release testing that determine which plasma-derived products reach patients. The EU AI Act and FDA guidance on real-world evidence are converging to redefine how post-market surveillance data supports label expansion for rare neurological indications. Stakeholders must monitor evolving biosimilar immunoglobulin pathways and payer willingness to reimburse home-based administration against hospital-based infusion economics.
Market Dynamics
Plasma fractionation capacity constraints are concentrating supply power among vertically integrated collectors, while subcutaneous delivery platforms are redistributing patient volume from hospital infusion suites toward homecare settings.
Growth Catalysts
- FDA Breakthrough Therapy Pathway:Accelerated review timelines for novel immunomodulatory candidates compress development cycles and attract venture funding toward rare neurological indications.
- Homecare Infrastructure Maturation:Specialty pharmacy networks in Germany and Japan now support cold-chain logistics for patient-administered immunoglobulin, expanding addressable chronic patient populations.
- EMA PRIME Eligibility:Priority medicines status grants enhanced regulatory dialogue and scientific advice, reducing uncertainty for developers targeting demyelinating disorders.
Market Restraints
- Plasma Collection Concentration:North American and European collection center networks dominate raw material supply, creating geographic vulnerability for fractionators without captive donor bases.
- IVIG Manufacturing Complexity:Viral inactivation protocols and lot-release testing requirements impose multi-week production timelines that limit rapid supply response to demand surges.
- Corticosteroid Substitution:Prednisone and dexamethasone protocols retain substantial first-line utilization in emerging markets where biologic reimbursement remains restricted.
Strategic Opportunities
- Biosimilar Immunoglobulin Pathways:EMA biosimilar guidelines for plasma-derived products create regulatory templates for follow-on entrants to challenge originator pricing.
- Real-World Evidence Integration:FDA guidance on electronic health record-derived efficacy data enables label expansion without prospective randomized trials.
- Subcutaneous Formulation Innovation:Recombinant hyaluronidase-facilitated SCIG administration reduces infusion frequency and opens pediatric and elderly segments previously excluded by venous access limitations.
Industry Challenges
- Specialized Neurology Nursing Shortage:Home infusion training requirements for SCIG administration outpace certified nurse availability in rural and suburban territories.
- Lot-to-Lot Immunoglobulin Variability:Polyclonal antibody titer fluctuations between plasma pools complicate individualized dosing optimization and therapeutic drug monitoring standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market |
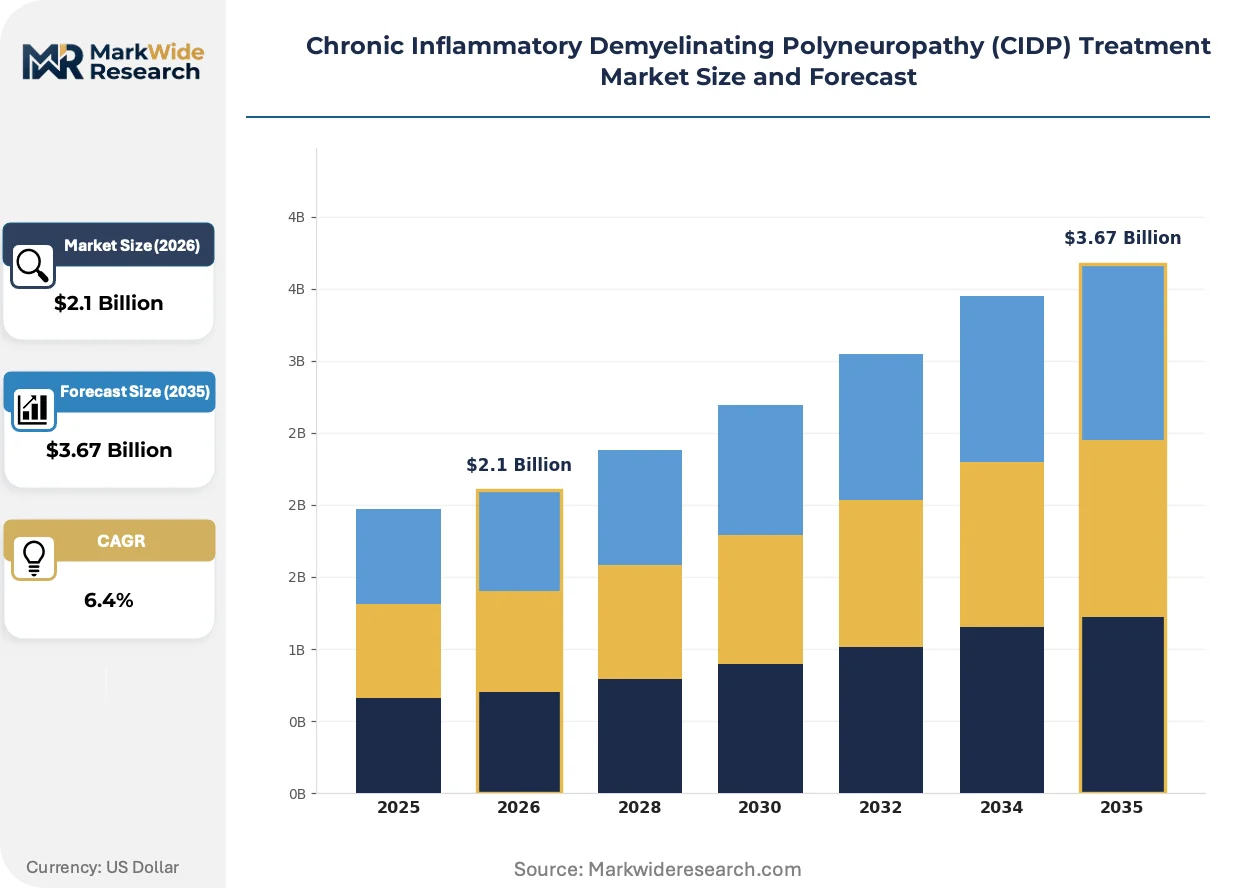
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Immunosuppressants, Corticosteroids, Intravenous Immunoglobulin, Plasma Exchange Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation End User: Hospitals, Clinics, Homecare, Specialty Centers Stage of Disease: Acute, Chronic, Relapsing-Remitting, Progressive |
| Companies Covered | Takeda, Kedrion, CSL Behring, Baxter International, Teijin Pharma, Octapharma, Grifols, Mitsubishi Tanabe Pharma Corporation, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market Strategic Shifts
Delivery modality innovation and regulatory data requirements are converging to reshape how chronic neurological therapies reach patients and demonstrate value.
Subcutaneous immunoglobulin formulations with recombinant hyaluronidase are displacing conventional IVIG protocols in maintenance-phase CIDP patients. Neurology practices in the United States and Germany are adopting these platforms to reduce hospital dependency and capture reimbursement for home-based administration. This displacement is compressing infusion center revenue per patient while expanding total treatable population through improved convenience adherence.
EMA's Medical Device Regulation and FDA's Digital Health Software Precertification Pilot are imposing new validation requirements on connected delivery devices used for patient-administered immunoglobulin. Manufacturers must now demonstrate cybersecurity resilience and algorithmic transparency for dose-tracking applications bundled with infusion pumps. European notified bodies are prioritizing review capacity toward combination product submissions, delaying pure-play device clearances.
Specialty pharmacies are assuming care coordination functions previously performed by hospital outpatient departments, including prior authorization management and adherence monitoring. This channel migration is most pronounced in United States Medicare Advantage populations where plan-sponsored home infusion benefits reduce total cost of care metrics. Payer pharmacy benefit managers are consolidating preferred network contracts around vertically integrated specialty distributors with captive nursing staff.
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market Segmentation
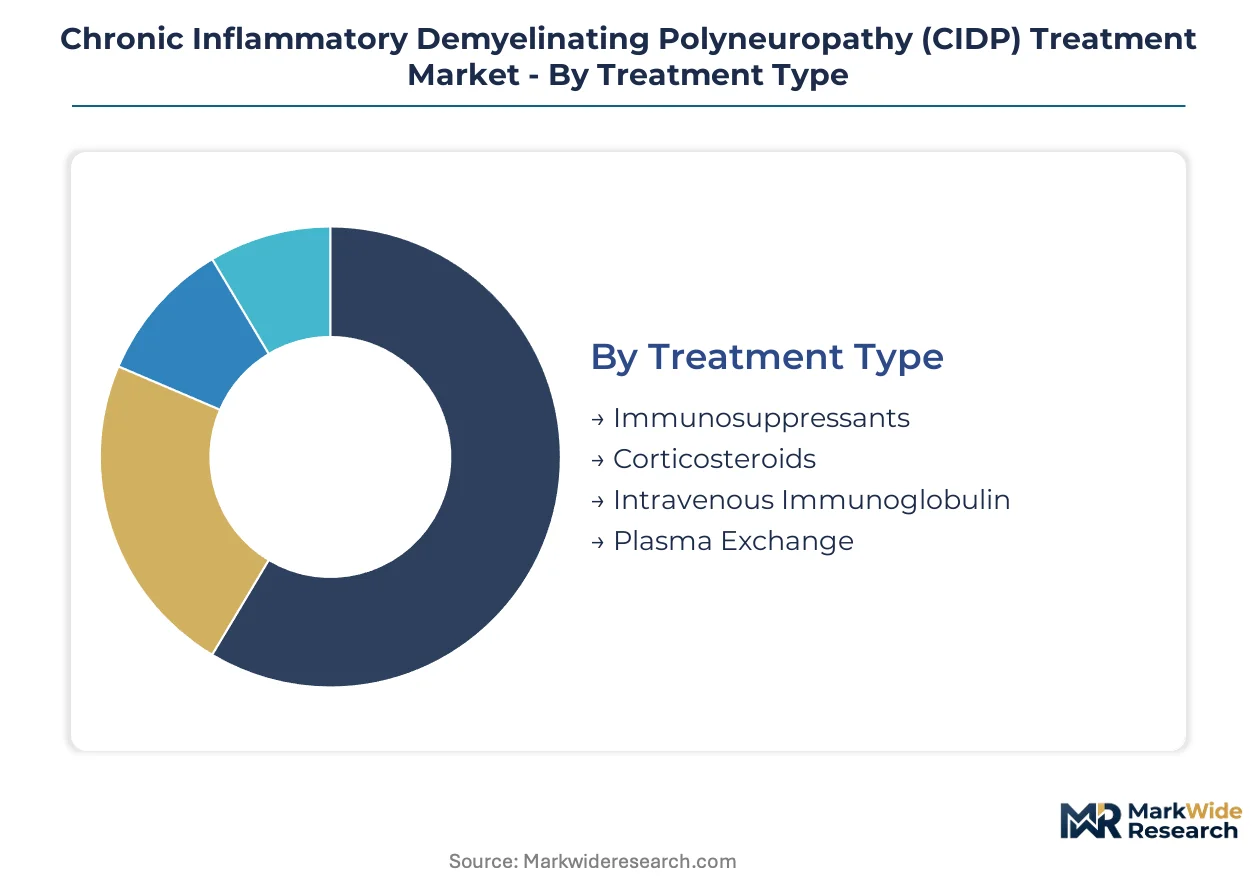
CIDP treatment flows through distinct clinical and commercial channels that shape reimbursement, patient adherence, and manufacturer strategy. Segmentation reveals where plasma-derived biologics command premium economics versus where corticosteroids retain volume dominance through cost constraints.
Treatment Type:
Intravenous immunoglobulin and corticosteroids flow through hospital outpatient departments with established prior authorization pathways, while immunosuppressants reach patients through specialty pharmacy networks with complex risk evaluation and mitigation strategies.
- Intravenous Immunoglobulin:Plasma-derived polyclonal antibodies at 10% protein concentration with pH stabilization between 4.0 and 4.5. Demand concentrates in United States Medicare populations and German statutory health insurance systems where reimbursement rates support chronic maintenance protocols. Manufacturing complexity and viral inactivation requirements limit supplier base to fractionators with captive plasma collection networks.
- Corticosteroids:Synthetic glucocorticoids including prednisone and dexamethasone administered in tapering protocols. Volume concentrates in emerging markets where biologic reimbursement remains restricted and first-line neurology practice favors cost-contained induction therapy. Substitution pressure intensifies as IVIG access expands through public health programs.
- Immunosuppressants:Azathioprine and mycoprazolate mofetil for refractory patients with inadequate IVIG response.
- Plasma Exchange:Therapeutic apheresis for acute exacerbations requiring rapid antibody removal.
By volume, corticosteroids lead. By growth pace, intravenous immunoglobulin is ahead.
Delivery Mode:
Route selection determines site-of-care economics and nursing resource allocation, with subcutaneous platforms redistributing patient volume from infusion centers toward home settings.
- Intravenous:Hospital-based infusion requiring certified nursing supervision and cold-chain logistics. United States and Japan maintain highest per-patient treatment rates through established outpatient reimbursement.
- Subcutaneous:Patient-administered immunoglobulin with recombinant hyaluronidase facilitating large-volume absorption. Germany and United States specialty pharmacies now support cold-chain home delivery, expanding chronic maintenance populations previously excluded by hospital dependency.
- Oral:Corticosteroid and immunosuppressant administration enabling self-management without infusion infrastructure.
- Inhalation:Limited application for pulmonary complications in select CIDP variants.
Intravenous delivery still captures the majority of immunoglobulin revenue, yet subcutaneous protocols are gaining share fastest among maintenance-phase patients.
End User:
Channel migration from hospital outpatient departments toward specialty pharmacies and homecare settings is compressing traditional infusion economics while expanding total addressable population.
- Hospitals:Academic medical centers with neuromuscular specialist density and apheresis capability. United States and Japanese tertiary centers dominate complex diagnostic workup and acute exacerbation management.
- Homecare:Medicare Advantage and German sickness fund contracts increasingly prefer home infusion for maintenance IVIG and SCIG, reducing total cost of care metrics.
- Clinics:Community neurology practices with limited apheresis access.
- Specialty Centers:Dedicated infusion suites with captive nursing staff and prior authorization expertise.
Hospitals retain the highest revenue per patient. Homecare is climbing the fastest as payer contracts shift site-of-care incentives.
Stage of Disease:
Disease trajectory determines treatment intensity and duration, with progressive phenotypes requiring sustained immunomodulation versus relapsing-remitting cases amenable to intermittent protocols.
- Chronic:Sustained demyelination requiring indefinite maintenance therapy with IVIG or SCIG. United States and Germany concentrate chronic patient volume through established neuromuscular referral networks.
- Relapsing-Remitting:Episodic weakness with complete or partial recovery between attacks, suitable for intermittent immunoglobulin pulses. Japanese diagnostic protocols identify this phenotype earlier, enabling treatment de-escalation during remission.
- Acute:Rapid-onset presentations requiring immediate IVIG or plasma exchange.
- Progressive:Steady functional decline with limited treatment response, often transitioning to supportive care.
Chronic stage patients generate the longest treatment duration. Relapsing-remitting presentations are expanding most quickly as diagnostic sensitivity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement harmonization across statutory health insurance systems is redistributing CIDP treatment volume toward outpatient and homecare channels. Germany's sickness fund consolidation and Japan's Diagnosis Procedure Combination revisions exemplify this shift. Plasma collection infrastructure and neuromuscular specialist density determine where immunoglobulin therapies achieve market penetration.
United States
Medicare Advantage plans now bundle home infusion benefits for IVIG and SCIG maintenance, shifting site-of-care economics toward specialty pharmacy networks. FDA Breakthrough Therapy designations for novel immunomodulatory candidates compress regulatory timelines and attract venture funding toward rare neurological indications. Boston and Baltimore academic medical centers anchor complex diagnostic workup and therapeutic apheresis capability.
Germany
Sickness fund contracts increasingly prefer home-based SCIG administration for chronic maintenance patients, reducing total cost of care metrics versus hospital outpatient departments. EMA PRIME eligibility grants enhanced regulatory dialogue for developers targeting demyelinating disorders. North Rhine-Westphalia concentrates plasma fractionation capacity and neuromuscular referral networks within European collection center infrastructure.
Japan
PMDA accelerated approval pathways for orphan neurological indications enable faster market entry for novel immunoglobulin formulations. Diagnosis Procedure Combination revisions incentivize earlier identification of relapsing-remitting phenotypes, enabling treatment de-escalation during remission periods. Tokyo and Osaka metropolitan areas maintain the highest per-patient treatment rates for IVIG protocols through established neuromuscular specialist density.
United Kingdom
NICE technology appraisals determine immunoglobulin access through cost-effectiveness thresholds that favor SCIG over IVIG where clinical equivalence is demonstrated. NHS England's specialized commissioning framework concentrates CIDP treatment within designated neuromuscular centers. London and Manchester academic hospitals coordinate plasma exchange capability and complex diagnostic referral pathways.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines market authorization for plasma-derived biologics while maintaining distinct pricing and reimbursement negotiations. Mandatory health insurance contracts cover home infusion nursing for SCIG administration, expanding chronic patient populations beyond hospital dependency. Basel and Zurich house plasma fractionation research clusters and specialized neurology practices.
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market Competitive Environment
Listed plasma fractionation leaders compete with private specialists across collection center ownership and subcutaneous delivery innovation. The vendor base concentrates among vertically integrated collectors with captive donor bases, while mid-cap specialists pursue formulation differentiation. Three archetypes dominate: plasma-derived biologic originators with global fractionation networks, subcutaneous delivery technology specialists, and regional immunoglobulin suppliers with concentrated geographic presence. Competitive moves center on backward integration into plasma collection and strategic partnerships for recombinant hyaluronidase licensing.
Among plasma fractionation originators, CSL Behring, Grifols, and Takeda exemplify the integrated archetype. CSL Behring occupies a position anchored in multi-continent plasma collection infrastructure. Grifols represents European collection center network dominance. Takeda sits within the subcutaneous delivery innovation tier through its specialization in patient-administered immunoglobulin platforms that reduce hospital dependency for chronic maintenance populations.
| Leading Market Players |
|---|
| Takeda |
| Kedrion |
| CSL Behring |
| Baxter International |
| Teijin Pharma |
| Octapharma |
| Grifols |
| Mitsubishi Tanabe Pharma Corporation |
| Pfizer |
| Others |
Value Chain & Pricing Dynamics
Twenty-one to twenty-eight day lot-release timelines for immunoglobulin batches tether pricing power directly to plasma collection density and fractionator capacity utilization. Manufacturers with captive donor networks in the United States and Germany command premium positioning against spot-market dependent competitors, while buyers in Japan and Switzerland absorb higher delivered costs through mandatory insurance frameworks.
Pricing Analysis
Certification level creates the primary spread between FDA-grade and standard-tier immunoglobulin products, with viral inactivation validation and pH stability documentation separating premium plasma-derived therapies from commodity-grade alternatives. Contract-based long-term offtake agreements dominate hospital procurement, though specialty pharmacies increasingly negotiate volume-scale rebates for home-based SCIG administration. Cost compression in the corticosteroid substitution tier intensifies as biosimilar pathways mature, while hospital outpatient departments show highest price sensitivity compared to Medicare Advantage plans bundling infusion benefits.
Supply Chain Analysis
Strategic stockpiling of plasma inventories dominates over just-in-time approaches, with fractionators maintaining ninety to one hundred twenty day raw material buffers against collection volatility. Supply concentrates in the United States, Germany, and Spain where collection center networks feed captive fractionation facilities, while viral inactivation reagents and recombinant hyaluronidase enzymes draw from specialized biochemical suppliers. Single-source vulnerability in recombinant protein inputs creates structural risk, with distribution running through vertically integrated specialty pharmacy networks that control cold-chain logistics and nursing deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated payer entities and specialty pharmacy networks, with Medicare Advantage plan consolidation and German sickness fund mergers reducing manufacturer pricing leverage across outpatient channels.
For Market Incumbents: Compound defensive positioning through backward integration into plasma collection networks and exclusive recombinant hyaluronidase licensing agreements that lock out formulation competitors. Threat from biosimilar immunoglobulin entrants demands accelerated investment in subcutaneous delivery device ecosystems that embed switching costs for chronic maintenance patients. For New Entrants and Emerging Players: Differentiate on pediatric and elderly patient segments previously excluded by venous access limitations, where recombinant hyaluronidase-facilitated SCIG administration opens addressable populations. White-space targets include homecare infrastructure in Japanese metropolitan corridors and Swiss mandatory insurance contracts covering nursing support, with go-to-market execution through specialty pharmacy partnerships rather than hospital formulary battles. For Investors and Strategic Acquirers: Long-term, this sits as a supply-constrained biologic infrastructure play because plasma collection network ownership determines sustainable margin capture against cyclical raw material costs. Acquisition targets center on mid-cap fractionators with underutilized collection capacity in European donor-dense regions. Signal to watch is EMA biosimilar guideline finalization for plasma-derived products, which would accelerate pricing compression and trigger consolidation imperatives.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive donor bases in United States and Germany insulate against raw material volatility and competitor encroachment. |
| Subcutaneous Formulation Development | Recombinant hyaluronidase integration reduces hospital dependency and unlocks Medicare Advantage reimbursement pathways. |
| Specialty Pharmacy Partnership | Preferred network contracts with captive nursing staff control site-of-care migration and adherence monitoring revenue. |
| EMA PRIME Designation Pursuit | Priority medicines status accelerates regulatory dialogue and reduces development uncertainty for novel immunomodulatory candidates. |
| Real-World Evidence Infrastructure | FDA guidance alignment enables label expansion through electronic health record-derived efficacy data without prospective trials. |
Study Parameters
Initial hypotheses were tested against primary input from plasma fractionation executives, specialty pharmacy operations directors, neuromuscular clinicians, and payer formulary managers, then refined through secondary validation against FDA filings, EMA assessment reports, ClinicalTrials.gov protocols, and Medicare claims databases. Bottom-up patient volume estimates by treatment line and administration route were cross-checked against top-down manufacturer revenue disclosures across the analysis window.
Variance decomposition across treatment type, delivery mode, disease stage, and regional regulatory cluster shaped the analytical framework, with CAGRs derived from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends. Forecast inputs incorporated plasma collection yield projections, neuromuscular specialist density trajectories, and reimbursement policy evolution in statutory health insurance systems.
The analysis sits within stated boundaries; outcomes outside sustained immunoglobulin reimbursement stability and plasma donor recruitment rates would require recalibration. Forecasts reflect documented assumptions regarding regulatory pathway harmonization and biosimilar market entry timing. Revision becomes warranted when EMA or FDA guidance on plasma-derived product interchangeability crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Whim Syndrome Management Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market
Specialty Medicine
Exanthema Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Acute Lymphocytic-Lymphoblastic Leukemia (ALL) Therapeutics Market
Specialty Medicine
US Mobile Physician Practice Market