
 Epistaxis Market | 2026-2036
Epistaxis Market Size, Share, and Industry Trends Forecast 2026-2036
Epistaxis Market Intelligence
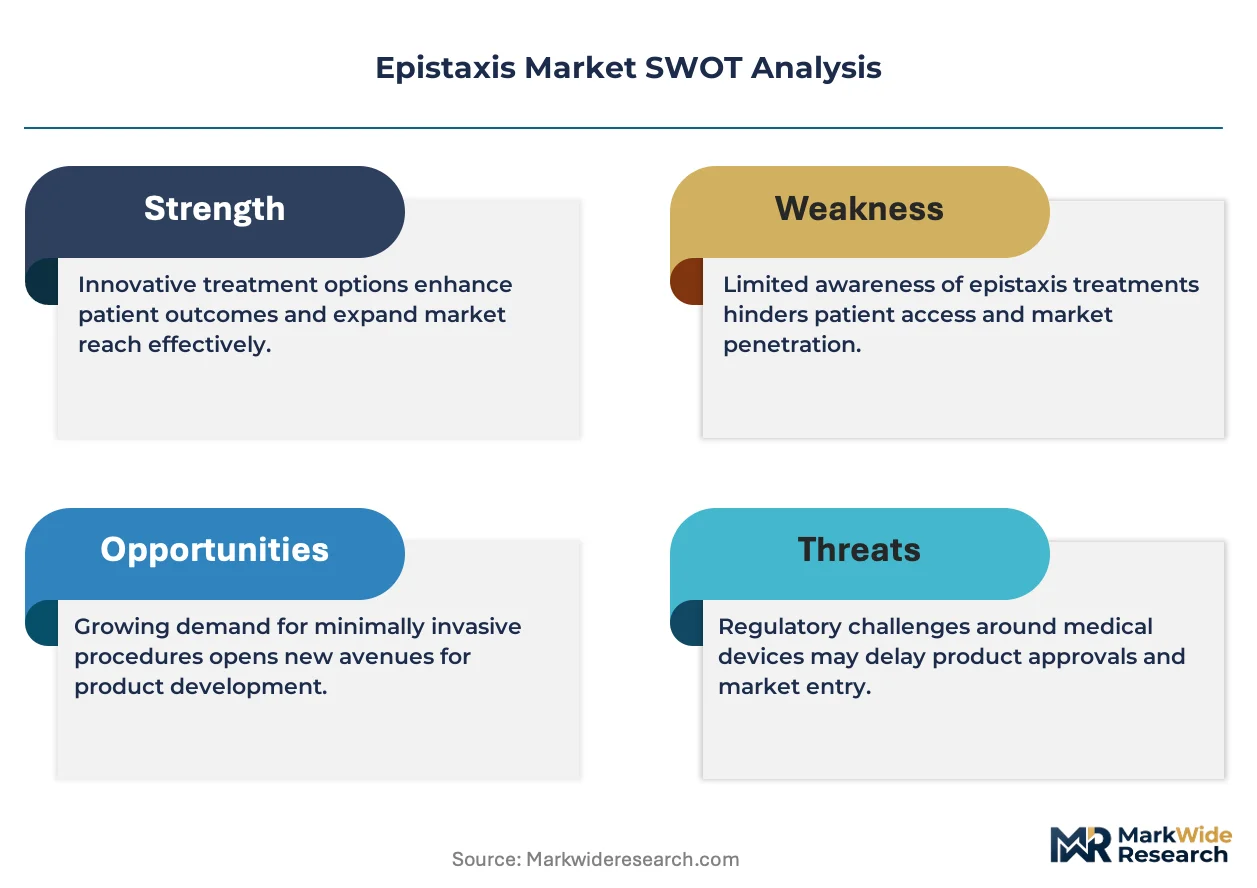
A shift from single-vendor contracts for nasal packing and hemostatic agents is decoupling hospital procurement from historical supplier relationships. This trend opens opportunities for specialized device manufacturers to gain access to large health systems. Medtronic leverages its extensive distribution network to supply hospitals with a broad portfolio of ENT devices. Johnson & Johnson competes through its development of advanced absorbable materials and topical hemostatic agents for surgical and emergency applications.
Epistaxis management involves medical interventions designed to control nasal hemorrhage. These products, such as nasal tampons and topical hemostatic agents, function by applying direct pressure or promoting physiological coagulation at the bleeding site. Nasal packing and topical hemostatic agents constitute the largest product segments, driven by their efficacy in emergency settings. Hospitals remain the dominant end-user channel, though specialized ENT clinics show faster adoption rates for managing patients with recurrent epistaxis.
Market access for epistaxis devices is governed by stringent regulatory approvals. The U.S. FDA's 510(k) clearance pathway and Europe's CE marking under the Medical Device Regulation (MDR) set high standards for safety and efficacy. In China, the NMPA imposes its own distinct registration requirements for imported medical products. Future competitive advantage will depend on navigating these diverse regulatory landscapes while demonstrating superior clinical outcomes.
Market Dynamics
The central dynamic in the epistaxis market is the unbundling of hospital procurement from long-standing, single-vendor contracts. This shift away from historical supplier relationships creates significant access for specialized device manufacturers to compete within large health systems on clinical and economic merit.
Growth Catalysts
- Advanced Absorbable Materials:The development of new biomaterials that dissolve in situ eliminates the need for painful packing removal, which accelerates adoption in post-surgical care and emergency medicine to improve patient outcomes and reduce follow-up visits.
- Specialized ENT Clinics:An increase in procedure volume within specialized otolaryngology clinics for managing chronic and recurrent nosebleeds establishes a concentrated, high-growth demand channel outside of traditional hospital emergency departments.
- Reimbursement Frameworks:Favorable reimbursement codes in the United States and parts of Europe for specific epistaxis interventions support the use of premium hemostatic agents and advanced nasal packing devices over traditional, lower-cost methods.
Market Restraints
- Cost-Containment Pressures:Hospital budget constraints, particularly within healthcare systems in the United States driven by group purchasing organizations, limit the widespread adoption of higher-priced, next-generation epistaxis treatments.
- Generic Alternatives:The persistent availability of low-cost traditional options, such as cotton gauze and basic nasal tampons, presents a significant substitution threat, especially in price-sensitive public health systems and emerging economies.
- MDR Compliance Burden:Europe's stringent Medical Device Regulation (MDR) introduces higher clinical evidence requirements and extended review timelines, creating a substantial regulatory barrier for new market entrants and product updates.
Strategic Opportunities
- Emerging Market Penetration:Underdeveloped markets for advanced epistaxis control, such as in India and Brazil, offer substantial growth potential for manufacturers able to introduce cost-effective and easy-to-use products tailored to local healthcare infrastructure.
- Drug-Device Combination Products:Integrating therapeutic agents like vasoconstrictors or analgesics directly into absorbable packing materials provides a pathway to create differentiated, high-value products with enhanced clinical efficacy.
- Direct-to-Clinic Sales Models:Establishing direct sales channels to high-volume ENT clinics allows manufacturers to bypass complex hospital distribution networks, enabling better margin control and fostering direct relationships with key end-users.
Industry Challenges
- Divergent Regulatory Navigation:Managing distinct and evolving submission requirements for the FDA in the U.S., the NMPA in China, and CE marking under MDR in Europe complicates global product launches and adds significant administrative overhead.
- Clinical Training Gaps:The effective use of novel hemostatic agents and advanced packing devices requires specific application techniques, necessitating costly and resource-intensive training programs for emergency and surgical staff to ensure patient safety.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epistaxis Market |
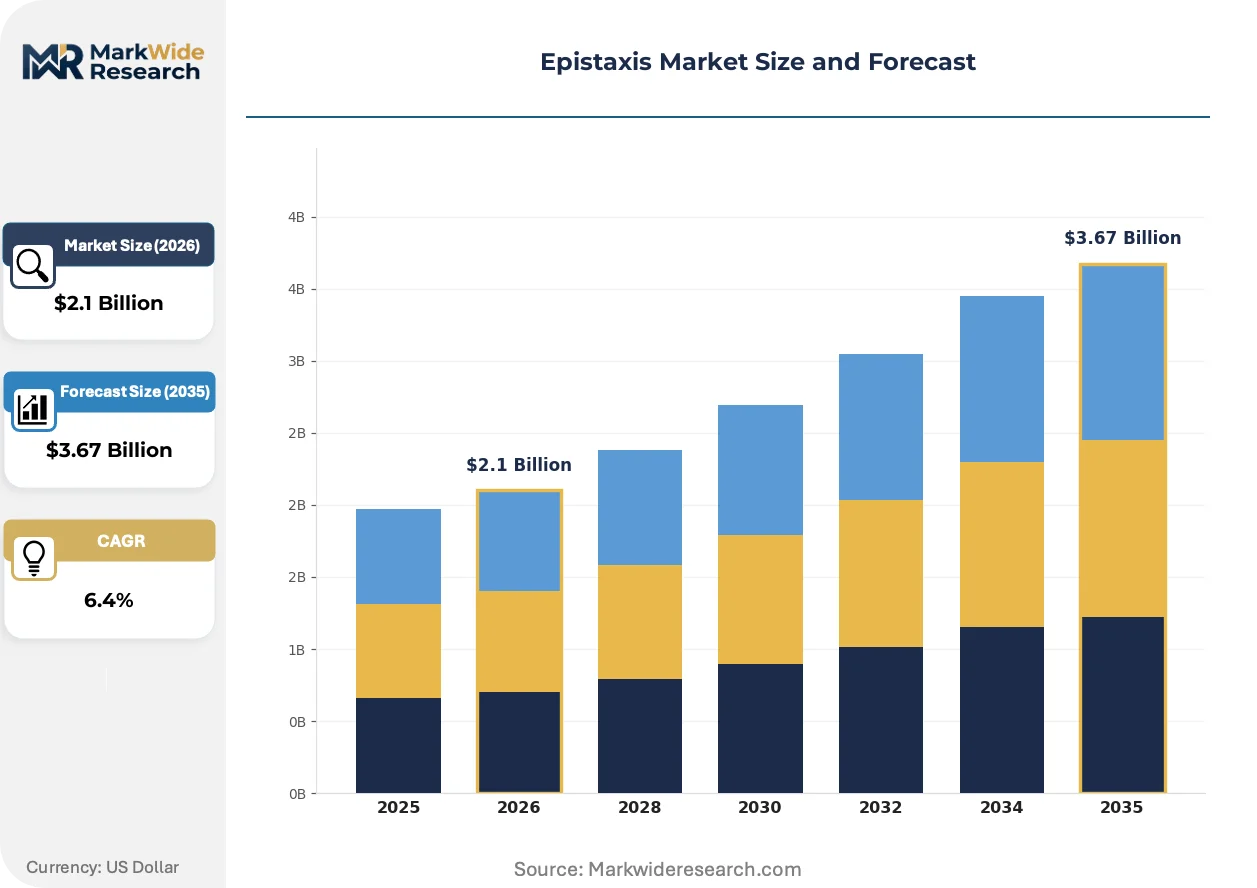
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nasal Packing, Topical Hemostatic Agents, Absorbable Materials, Nasal Tampons, Adhesive Bandages Therapy Area: Anterior Bleeding, Posterior Bleeding, Recurrent Nosebleeds, Traumatic Epistaxis, Idiopathic Epistaxis End User: Hospitals, Specialized ENT Clinics, Ambulance Services, Hematology Centers, Urgent Care Facilities Delivery Mode: Inpatient Procedures, Outpatient Care, Emergency Room Interventions, Homecare Treatment, Telemedicine Consultations |
| Companies Covered | Medtronic, Stryker, Smith & Nephew, Pfizer Inc., Johnson & Johnson, Bristol-Myers Squibb Co., Teleflex, Boston Scientific, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epistaxis Market Strategic Shifts & Innovations
The evolution of epistaxis management is defined by a clear pivot toward less invasive, more patient-centric solutions. This movement prioritizes faster recovery times and reduced patient trauma, driving innovation in both material science and device application systems beyond simple hemorrhage control.
Absorbable hemostatic agents, including oxidized regenerated cellulose and gelatin-based sponges, provide effective coagulation without requiring a second, often painful, removal procedure. These advanced materials are seeing rapid uptake in surgical suites and specialized ENT clinics where patient comfort and reduced follow-up are critical. The convergence of biomaterial science with ergonomic device design is electrifying the product development pipeline, enabling smaller, more effective applicators for targeted hemostasis.
The European Union's Medical Device Regulation (MDR) mandates more rigorous clinical data and continuous post-market surveillance for all medical devices sold within the bloc. This regulation significantly raises the bar for market entry and increases compliance costs, particularly for manufacturers of epistaxis products. The absorbable packing and novel hemostatic agent segments are most affected, as they must now generate more robust clinical evidence to secure or maintain CE marking.
A notable shift in hospital purchasing behavior involves the decoupling of ENT supply contracts, moving away from single-vendor agreements. This unbundling of bids for nasal packing and topical hemostatic agents disrupts the advantage of large-portfolio incumbents, creating openings for specialized manufacturers with innovative point solutions. This trend is most prominent within large integrated delivery networks (IDNs) in the United States, which seek to optimize both clinical performance and supply chain costs.
Epistaxis Market Segmentation
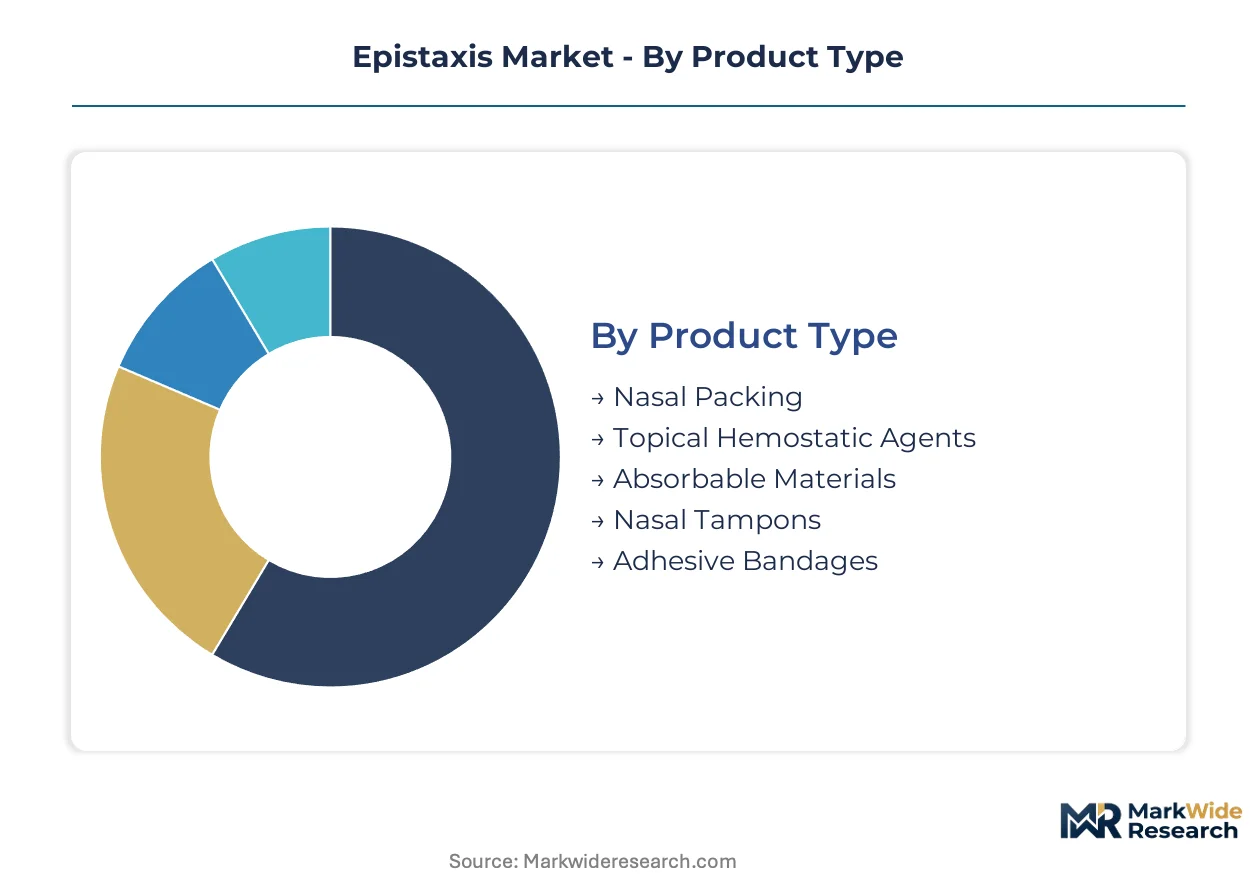
Segmentation in the epistaxis market reveals distinct product preferences and end-user requirements. Understanding these divisions helps manufacturers tailor solutions for specific clinical needs. The varied applications of hemostatic agents and packing materials drive differentiated market strategies. This granular view informs product development and market access efforts for effective hemorrhage control.
Product Type:
Product type segmentation highlights the varying regulatory scrutiny faced by epistaxis treatments, with advanced materials requiring more extensive clinical validation for approvals like CE marking and FDA 510(k).
- Topical Hemostatic Agents:These products, often containing thrombin or fibrinogen, actively promote clotting at the bleeding site. Demand concentrates in emergency departments and surgical settings, driven by the need for rapid hemorrhage control in acute epistaxis.
- Absorbable Materials:Comprising materials like oxidized regenerated cellulose or gelatin, these dissolve naturally, eliminating removal pain. Their adoption is accelerating in specialized ENT clinics and post-surgical care, as they enhance patient comfort and reduce follow-up appointments.
- Nasal Packing:Traditional nasal packing involves materials like gauze or sponges inserted to apply direct pressure.
- Nasal Tampons:These pre-formed, expandable devices provide quick and easy insertion for anterior nosebleeds.
- Adhesive Bandages:Primarily used for minor external epistaxis or after cautery, these offer light compression and protection.
Nasal Packing sits at the top of the volume ranking, with Absorbable Materials climbing the fastest.
Therapy Area:
Therapy area segmentation delineates epistaxis management strategies based on the specific anatomical location and underlying cause of bleeding.
- Recurrent Nosebleeds:This segment addresses chronic or repeated episodes, often managed in specialized ENT clinics with advanced diagnostic and treatment protocols. Demand is driven by patients seeking definitive long-term solutions beyond acute care.
- Anterior Bleeding:Originating from Kiesselbach's plexus, this common form of epistaxis is typically managed with simpler, less invasive interventions. Volume concentration is high in urgent care facilities and primary care settings due to its prevalence and ease of access.
- Posterior Bleeding:This more severe form originates deeper in the nasal cavity, requiring specialized interventions and often hospitalization.
- Traumatic Epistaxis:Caused by injury, this type necessitates rapid hemostasis, frequently in emergency rooms.
- Idiopathic Epistaxis:Bleeding without an identifiable cause, often managed symptomatically or through comprehensive diagnostic workups.
Anterior Bleeding accounts for the highest prevalence, while Posterior Bleeding demands the most complex interventions.
End User:
End-user segmentation reflects varied procurement patterns and service delivery models across different healthcare institutions.
- Hospitals:These institutions represent the largest end-user segment, handling a broad spectrum of epistaxis cases, from emergency to surgical interventions. Their procurement volumes are substantial, often driven by group purchasing organizations for cost efficiency.
- Specialized ENT Clinics:These clinics focus on chronic and recurrent epistaxis, utilizing advanced diagnostic tools and specialized treatment modalities. They exhibit faster adoption rates for premium hemostatic agents and absorbable packing materials, valuing patient comfort and reduced follow-up.
- Ambulance Services:These provide initial on-scene management for acute epistaxis, relying on basic hemostatic agents and packing.
- Hematology Centers:Patients with underlying bleeding disorders receive specialized epistaxis care within these centers.
- Urgent Care Facilities:These facilities manage non-life-threatening epistaxis cases, offering convenient access for immediate treatment.
Hospitals command the largest share of device consumption, but Specialized ENT Clinics are gaining market share fastest.
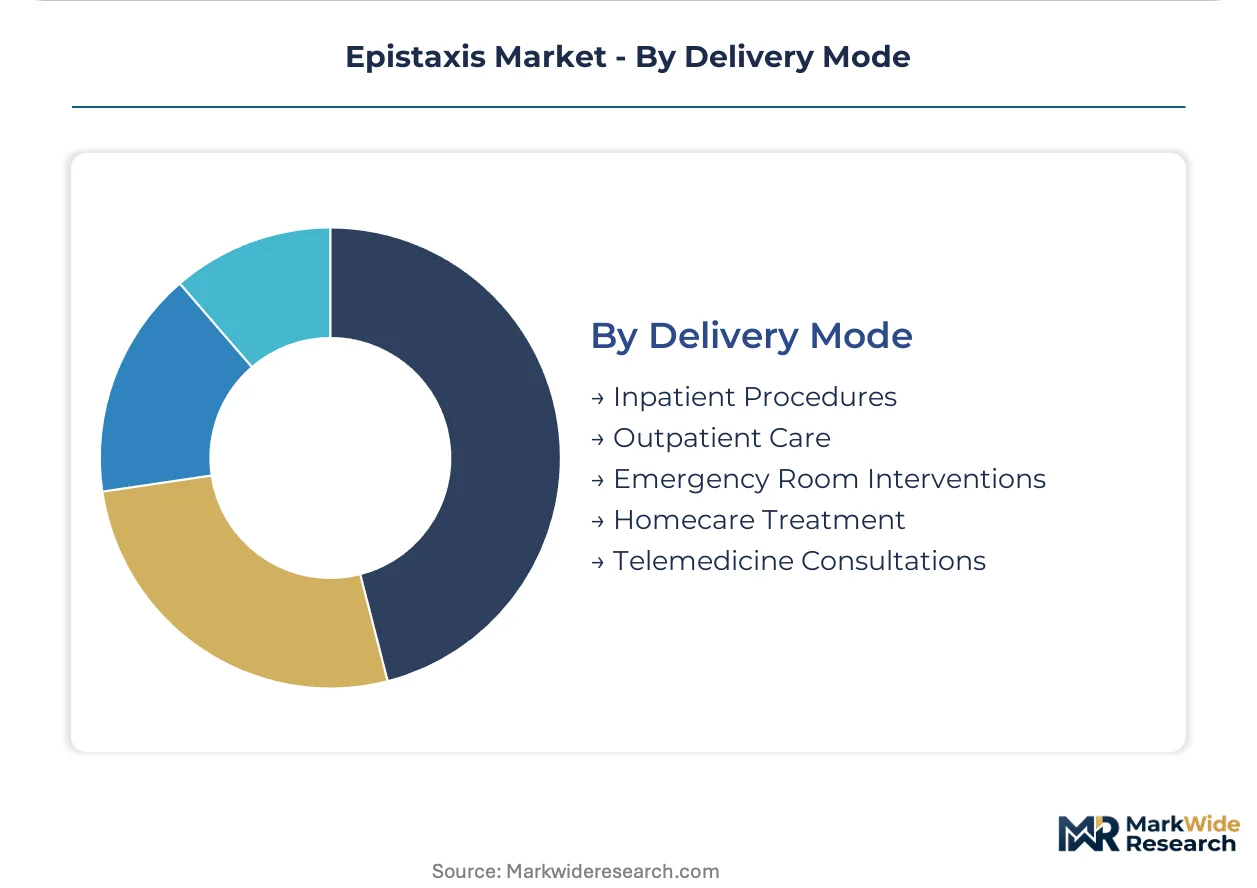
Delivery Mode:
Delivery mode segmentation illustrates the diverse points of patient interaction and care settings for epistaxis management.
- Emergency Room Interventions:This segment encompasses acute, often severe, epistaxis cases requiring immediate medical attention and rapid hemostasis. Demand concentrates on fast-acting topical agents and robust nasal packing for urgent hemorrhage control.
- Outpatient Care:This mode handles less severe or follow-up epistaxis cases, including minor procedures and device removal. Its growth is supported by the increasing shift towards cost-effective, clinic-based treatments for stable patients.
- Inpatient Procedures:Reserved for complex or refractory epistaxis, these often involve surgical interventions and extended hospital stays.
- Homecare Treatment:This involves self-management using simple first-aid methods or prescribed nasal sprays for mild cases.
- Telemedicine Consultations:Used for initial assessment, follow-up, or patient education, offering remote guidance for epistaxis management.
Emergency Room Interventions represent the immediate care backbone, while Outpatient Care and Homecare Treatment offer enhanced patient convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory landscapes and market access complexities often drive strategic decisions, leading to a degree of regulatory arbitrage where manufacturers optimize production or sales efforts based on cost-of-compliance gaps. This dynamic influences the distribution and adoption of epistaxis management solutions, with some regions offering more streamlined pathways for novel devices than others. Diverse healthcare infrastructures further shape regional demand for advanced hemostatic agents.
United States
High procedure volumes and established reimbursement frameworks for ENT interventions drive significant demand for advanced epistaxis products. The U.S. FDA's 510(k) clearance pathway provides a structured route for medical device market entry, supporting innovation. Major medical device clusters in states like California and Massachusetts foster continuous development of new biomaterials and device designs.
Germany
A strong emphasis on clinical evidence and patient safety underpins demand for premium epistaxis solutions within Germany's advanced healthcare system. CE marking under the Medical Device Regulation (MDR) sets stringent standards for product approval across Europe. The MedTech cluster in Tuttlingen, known as the "medical valley," remains a hub for surgical instrument and device manufacturing.
China
A large patient population and a rapidly expanding healthcare infrastructure create substantial opportunities for epistaxis market growth, particularly for cost-effective solutions. The NMPA imposes distinct registration requirements for imported medical products, influencing market entry strategies. Manufacturing and R&D centers in cities like Shanghai and Shenzhen are increasingly focusing on domestic medical device innovation.
India
Significant unmet medical needs and an increasing prevalence of chronic diseases contribute to the demand for accessible epistaxis treatments. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, with efforts to streamline approval processes for essential products. Hyderabad and Bengaluru are emerging as key centers for medical technology development and manufacturing.
Brazil
Expanding public and private healthcare investments are improving access to medical care, boosting the market for epistaxis management products across Brazil. ANVISA, the national health surveillance agency, oversees medical device registration and post-market surveillance. Sao Paulo and Rio de Janeiro serve as major medical device distribution and innovation hubs within Latin America.
Epistaxis Market Key Industry Players
Established producers occupy the standard tier of the epistaxis market, leveraging extensive distribution networks, while emerging entrants pursue niche opportunities in specialized biomaterials and patient-centric designs. The market structure reflects a blend of large, diversified medical device conglomerates and smaller, specialized innovators. Key competitive moves include strategic partnerships to expand product portfolios and continuous investment in R&D for next-generation hemostatic technologies.
Medtronic, a global leader in medical technology, exemplifies a diversified approach, offering a broad portfolio of ENT devices that includes epistaxis solutions. Johnson & Johnson occupies a strong position through its development of advanced absorbable materials and topical hemostatic agents for various surgical and emergency applications. Teleflex, known for its specialized medical devices, also competes by providing solutions that enhance procedural efficiency and patient comfort in epistaxis management.
| Leading Market Players |
|---|
| Medtronic |
| Stryker |
| Smith & Nephew |
| Pfizer Inc. |
| Johnson & Johnson |
| Bristol-Myers Squibb Co. |
| Teleflex |
| Boston Scientific |
| Becton, Dickinson and Company |
| Others |
Cost & Logistics Intelligence
Biomaterial commodity prices, particularly for oxidized regenerated cellulose, cascade through the epistaxis market, influencing the cost structures of advanced absorbable materials and their final pricing tiers. This directly affects manufacturer margins and hospital procurement budgets.
Pricing Analysis
Input-cost pass-through significantly impacts the epistaxis market, particularly for specialized biomaterials. Pricing stratifies across premium, standard, and economy tiers, driven by clinical efficacy and regulatory approval status like FDA 510(k). Pricing softness reflects hospital budget constraints and group purchasing organization influence, especially for traditional nasal packing. Specialized ENT clinics exhibit lower price sensitivity for advanced absorbable materials due to enhanced patient comfort.
Supply Chain Analysis
Single-source vulnerability sits with specialized biomaterial suppliers for advanced absorbable products. Supply concentrates across China for basic components, Germany for precision manufacturing, and the United States for innovative polymer development. Regulatory restrictions, particularly CE marking requirements under MDR, pose a significant structural risk for imported components. Distribution runs through established hospital networks and direct sales channels to specialized ENT clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epistaxis market is a late-cycle quality story, with demand shifting towards premium, patient-centric solutions that prioritize comfort and faster recovery. This movement accelerates the adoption of advanced absorbable materials.
For Market Incumbents:Deepen R&D investment into novel biomaterials and drug-device combination products to counter the unbundling of hospital procurement contracts. Expand strategic partnerships with specialized device manufacturers to broaden portfolio offerings. Reinforce channel control through extensive distribution networks, leveraging existing relationships with large health systems. Invest in robust clinical evidence to navigate stringent regulatory pathways like the EU MDR.
For New Entrants and Emerging Players:Begin with targeted market penetration in specialized ENT clinics, focusing on absorbable materials for recurrent nosebleeds. Develop cost-effective, easy-to-use products tailored for emerging markets like India and Brazil. Establish direct sales channels to bypass complex hospital distribution networks, fostering closer relationships with key end-users. Highlight superior clinical outcomes and patient comfort in marketing efforts.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory hurdles for novel devices increase and clinical evidence becomes paramount. Long-term viability favors companies with differentiated, clinically validated products over the next five to ten years. Target specialized device manufacturers holding strong intellectual property in absorbable materials or unique hemostatic agents. The signal to watch is the successful regulatory approval of drug-device combination products.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Biomaterial R&D | Drives product differentiation and enhances patient comfort in post-surgical care. |
| Targeted Emerging Market Entry | Captures growth in underserved regions like India and Brazil with cost-effective solutions. |
| Direct-to-Clinic Sales Channel | Bypasses complex hospital procurement, fostering direct end-user relationships. |
| MDR Compliance Investment | Secures continued market access in Europe for advanced epistaxis products. |
| Drug-Device Combination Development | Creates high-value products with enhanced clinical efficacy and competitive advantage. |
Research Approach
Bottom-up end-user modeling reconciled against top-down manufacturer supply-side tracking forms the analytical core of this study. Primary interviews with ENT specialists, hospital procurement managers, and medical device engineers provided qualitative insights. Secondary validation drew from FDA 510(k) filings, CE marking documentation, and medical device company annual reports. This triangulation ensures robust data integrity and market understanding.
An input-output matrix underpins the quantitative forecast, mapping demand drivers to supply-side capabilities across the analysis window. Segmentation dimensions include product type, therapy area, end-user, delivery mode, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical growth trends and projected adoption rates for advanced absorbable materials. Key forecast inputs include procedure volumes in specialized ENT clinics and regulatory approval timelines for novel hemostatic agents.
Several conditions sit outside the modeled scope, including specific company-level R&D budgets and detailed cost-benefit analyses for individual hospital systems. Forecasts reflect assumptions regarding reimbursement stability and global supply chain logistics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Central Pontine Myelinolysis Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Global Stroke Therapeutics Market
Specialty Medicine
Rheumatoid Arthritis Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Psoriatic Arthritis (Psa) Treatment Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
Global Prurigo Nodularis Treatment Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Cellulitis Management Market