
 Cervical Cancer Therapeutics Market | 2026-2036
Cervical Cancer Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Cancer Therapeutics Market Analysis
Biologics are repositioning small-molecule chemotherapy as the backbone of first-line cervical cancer protocols. Merck & Co., Inc. leverages its checkpoint inhibitor franchise to dominate immuno-oncology combinations in this indication. F. Hoffmann-La Roche Ltd anchors its portfolio through companion diagnostic-linked targeted therapy development. Bristol-Myers Squibb Company competes with dual immunotherapy regimens that extend survival curves in recurrent and metastatic settings.
Cervical cancer therapeutics comprise systemic agents designed to eliminate, control, or palliate malignant neoplasms of the cervix uteri, including platinum-based cytotoxics, monoclonal antibodies against PD-1/PD-L1 pathways, and vascular endothelial growth factor inhibitors administered via intravenous infusion with defined dosing cycles. Immunotherapy now leads product-type revenue generation as checkpoint inhibitors displace conventional chemotherapy in frontline maintenance, while targeted therapy represents the fastest-expanding margin pool due to biomarker-driven patient selection. Stage IV application segments command premium pricing due to limited curative alternatives and chronic treatment duration.
FDA oncology breakthrough therapy designation and EMA conditional marketing authorization frameworks compress development timelines and shape competitive access for novel cervical cancer agents. The WHO cervical cancer elimination initiative and national screening program expansions in India and China are redirecting patient flows toward earlier-stage detection and curative-intent therapy. Stakeholders must monitor biomarker testing infrastructure buildout and biosimilar entry timelines to calibrate portfolio prioritization and geographic resource allocation.
Market Dynamics
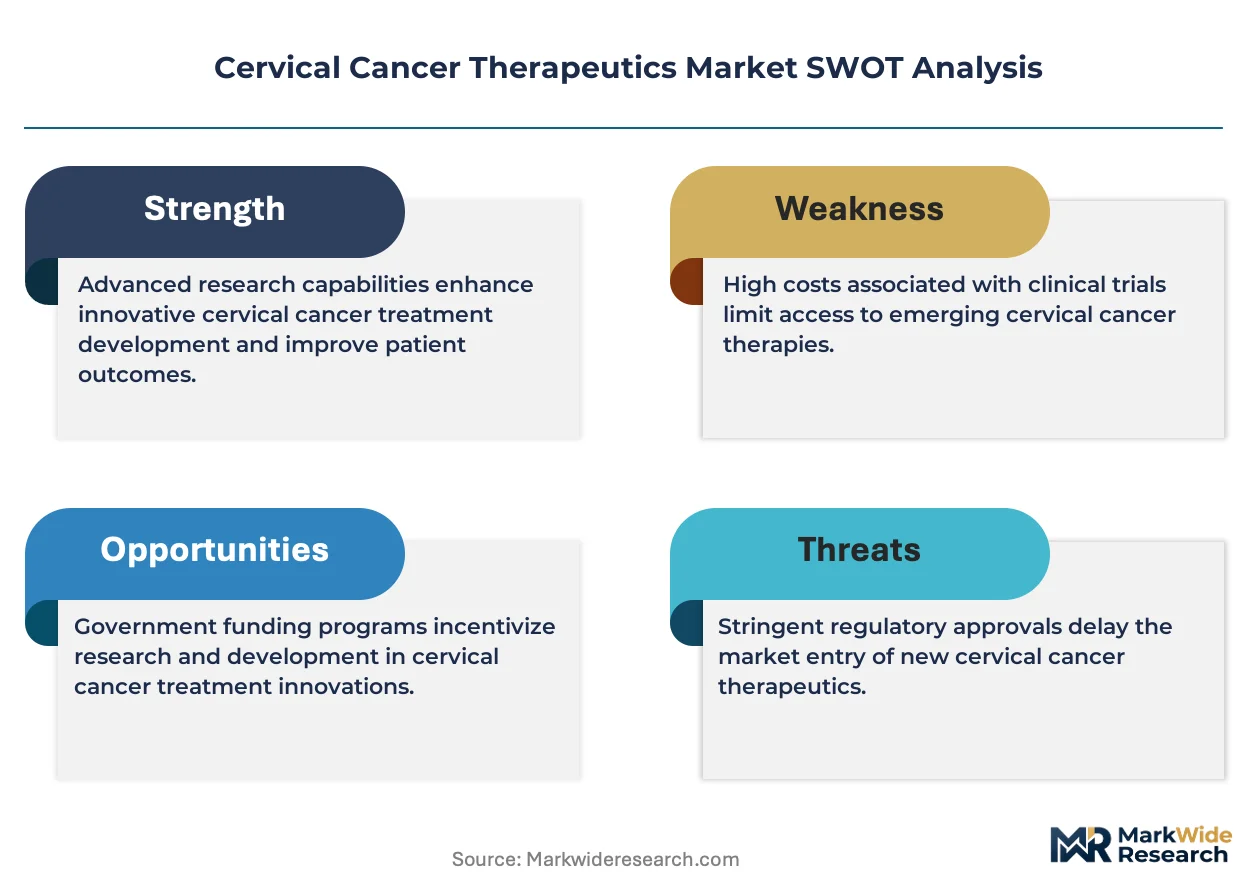
Checkpoint inhibitor combinations are restructuring first-line cervical cancer treatment hierarchies, compressing chemotherapy's historical dominance and concentrating market power around immuno-oncology portfolios with companion diagnostic requirements.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's expedited review pathway compresses development timelines for novel PD-1/PD-L1 inhibitors, accelerating patient access to combination regimens in recurrent and metastatic settings.
- Biomarker Testing Infrastructure:PD-L1 expression and tumor mutational burden assays are expanding across hospital-based oncology departments, enabling precision patient selection for targeted immunotherapy protocols.
- India and China:National cervical cancer elimination initiatives and screening program expansions in these markets are redirecting patient flows toward earlier-stage detection and curative-intent systemic therapy.
Market Restraints
- Platinum Supply Concentration:Reliance on concentrated mining operations in South Africa and Russia for cisplatin and carboplatin precursors creates input cost volatility and supply security risks for cytotoxic chemotherapy backbones.
- EMA Conditional Marketing Authorization:The requirement for confirmatory trial completion within defined timelines creates regulatory friction and reimbursement uncertainty for novel agents approved under accelerated pathways.
- Checkpoint Inhibitor Manufacturing Complexity:Monoclonal antibody production requires specialized bioreactor capacity concentrated among a limited supplier base, constraining volume scalability and creating bottleneck risks.
Strategic Opportunities
- Biosimilar Entry Timelines:Patent expirations for reference biologics are opening white space for biosimilar developers to capture margin-sensitive segments in European and emerging markets.
- Telemedicine-Enabled Patient Monitoring:Remote infusion supervision and adverse event management are reducing treatment center capacity constraints and expanding addressable patient populations in rural geographies.
- WHO Cervical Cancer Elimination Initiative:The 90-70-90 targets are creating policy tailwinds for vaccine-therapy integration and screening-treatment linkage programs in low- and middle-income country markets.
Industry Challenges
- Companion Diagnostic Co-Development:Synchronized FDA approval timelines for therapeutics and their associated biomarker assays create execution complexity and launch delay risks.
- Cold Chain Logistics for Biologics:Temperature-controlled distribution requirements for checkpoint inhibitors strain last-mile infrastructure in emerging markets, limiting geographic penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Cancer Therapeutics Market |
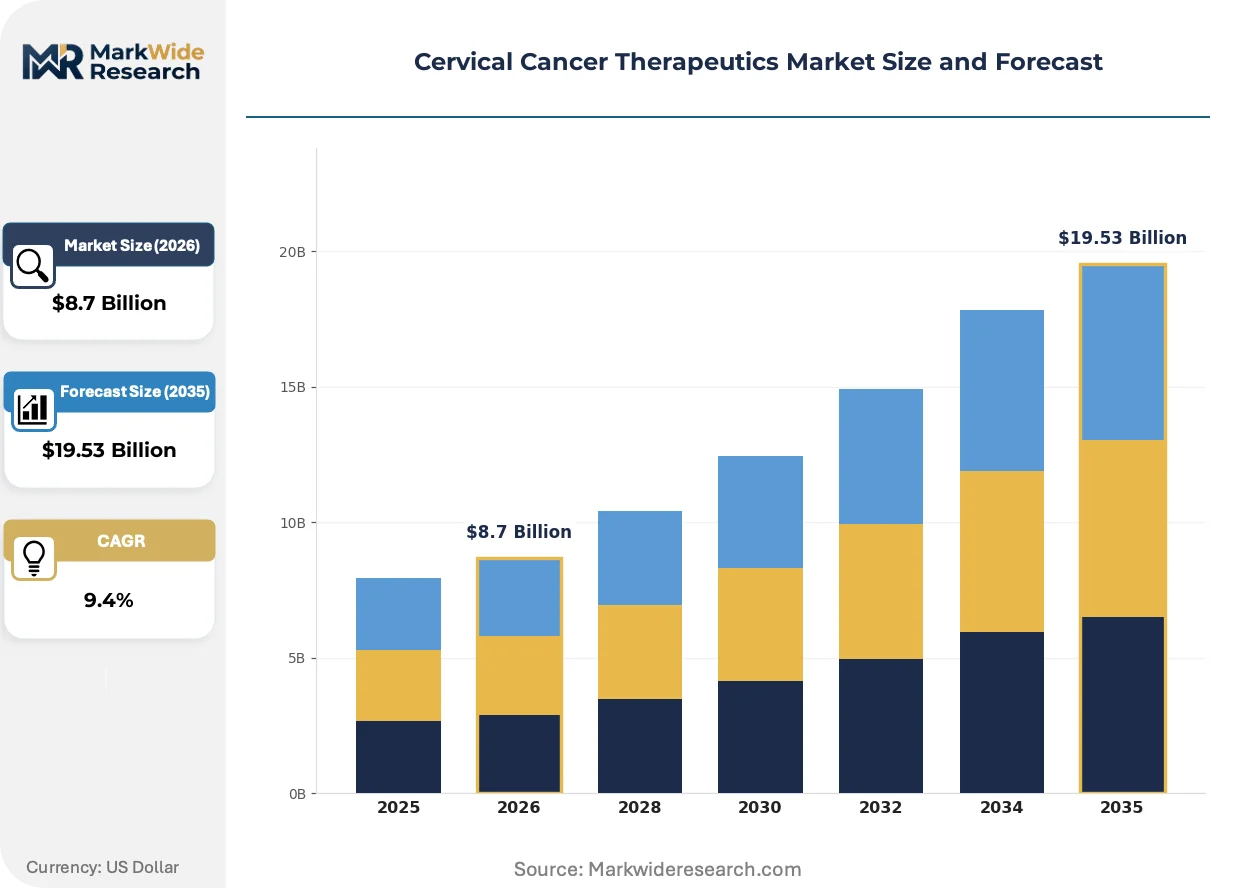
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Hormonal Therapy Application: Stage I, Stage II, Stage III, Stage IV Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Research Institutes, Homecare |
| Companies Covered | Merck & Co., Inc., F. Hoffmann-La Roche Ltd, Pfizer Inc., Seagen Inc., Bristol-Myers Squibb Company, GSK plc, AstraZeneca PLC, Novartis AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Cancer Therapeutics Market Emerging Trajectories
Antibody-drug conjugates and bispecific constructs are entering late-stage development, promising to fragment the current checkpoint inhibitor oligopoly and create new combination paradigms beyond PD-1/PD-L1 blockade.
Antibody-drug conjugates targeting tissue factor and other tumor-associated antigens are electrifying the pipeline for recurrent cervical cancer, with several candidates advancing through Phase III evaluation. Academic medical centers and specialized gynecologic oncology units are prioritizing enrollment in these trials, compressing traditional development timelines. This modality is electrifying competitive positioning by enabling targeted payload delivery that may circumvent resistance mechanisms to existing immunotherapy.
The EMA's revised Pharmaceutical Strategy and Health Technology Assessment harmonization initiatives are reshaping market access pathways for novel oncology agents across European member states. Manufacturers must now navigate parallel scientific advice procedures and joint clinical assessments that compress pricing negotiation windows. Oncology departments in Germany, France, and Italy are adapting procurement processes to accommodate these compressed timelines while maintaining formulary control.
Hospital pharmacy committees are consolidating vendor relationships for oncology therapeutics, shifting from multi-source purchasing to preferred provider agreements with integrated service components. This concentration is displacing traditional distributor intermediaries in favor of direct manufacturer-to-health system contracts with embedded clinical support. The United States and Western European markets exhibit the most pronounced consolidation, with integrated delivery networks capturing increasing share of infusion center volume.
Cervical Cancer Therapeutics Market Segmentation
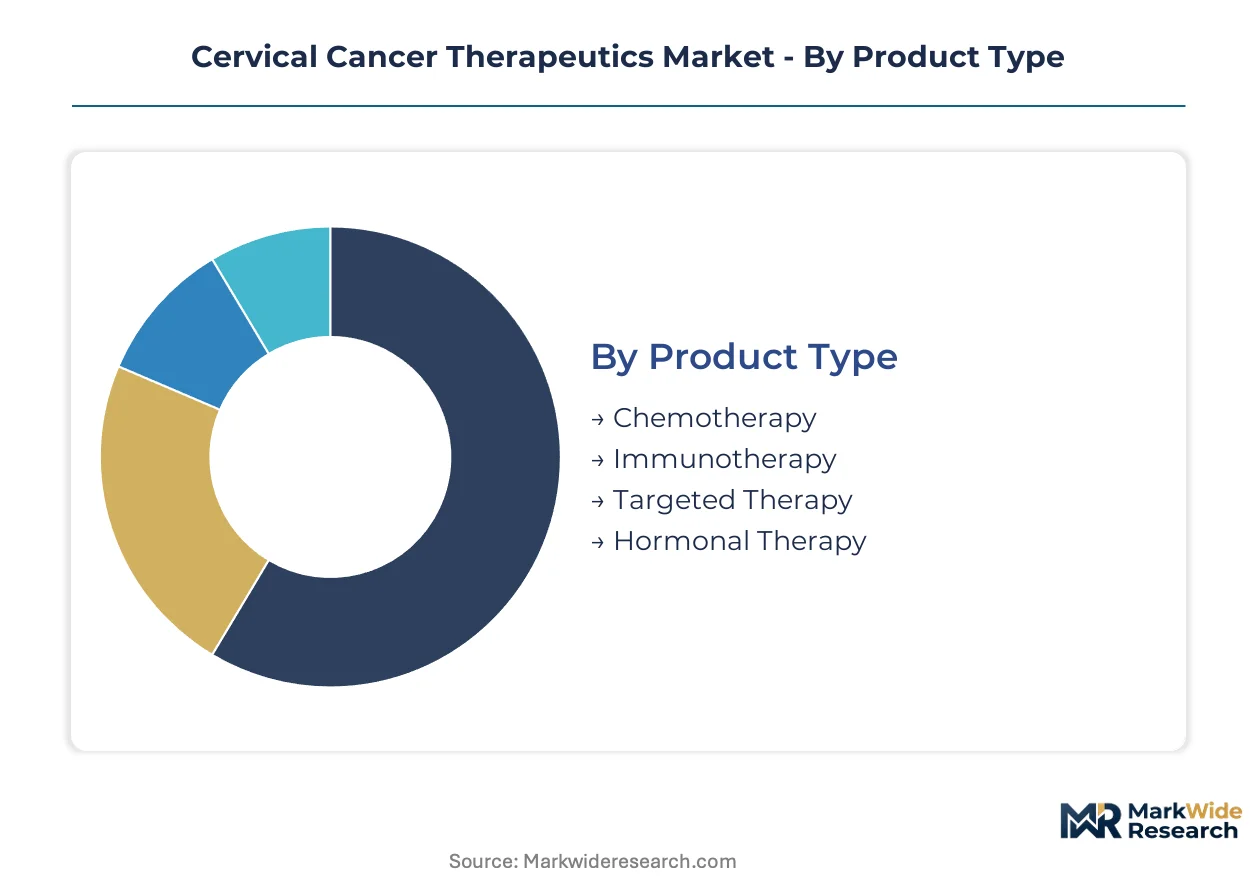
Cervical cancer therapeutics segment along four critical dimensions that determine manufacturing investment, regulatory pathway selection, and commercial access strategy. Each category carries distinct margin profiles and supply chain requirements that reshape portfolio prioritization for developers and procurement decisions for hospital systems.
Product Type:
Supply concentration for active pharmaceutical ingredients varies sharply across modalities, with biologics manufacturing capacity constraining immunotherapy expansion while small-molecule chemotherapies face precursor sourcing vulnerabilities.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways require specialized bioreactor capacity concentrated among contract manufacturing organizations in the United States, Germany, and Switzerland. Hospital-based oncology departments in the United States and Western Europe are concentrating demand around pembrolizumab-based combinations following FDA breakthrough therapy designations that compressed approval timelines.
- Chemotherapy:Platinum-based cytotoxics including cisplatin and carboplatin rely on concentrated precursor mining operations in South Africa and Russia, creating input cost volatility and supply security risks that strain hospital pharmacy procurement committees. The modality retains backbone status in neoadjuvant protocols despite immunotherapy displacement in maintenance settings.
- Targeted Therapy:Vascular endothelial growth factor inhibitors and companion diagnostic-linked agents are gaining share fastest in biomarker-screened patient populations across academic medical centers.
- Hormonal Therapy:Endocrine-modulating agents maintain niche application in select histologic subtypes with limited pipeline investment relative to immuno-oncology.
Today's leader: Immunotherapy. Tomorrow's challenger: Targeted Therapy.
Application:
Stage-specific treatment hierarchies determine pricing power and chronic therapy duration, with later-stage applications commanding premium reimbursement due to limited curative alternatives and extended treatment windows.
- Stage IV:Recurrent and metastatic disease settings concentrate the highest value per patient through combination immunotherapy protocols with chronic administration cycles. The United States and Germany exhibit the most pronounced pricing premiums for checkpoint inhibitor maintenance, driven by favorable reimbursement mechanics for oncology therapeutics in advanced disease.
- Stage III:Locally advanced cervical cancer represents the fastest-expanding addressable population as screening program expansions in India and China redirect patient flows toward earlier detection with curative-intent systemic therapy combined with radiation.
- Stage II:Regional disease management relies on neoadjuvant chemotherapy followed by surgical intervention, with immunotherapy integration still under Phase III evaluation.
- Stage I:Early-stage disease predominantly employs surgical resection with limited systemic therapy penetration outside clinical trial settings.
Stage IV commands current revenue concentration. Stage III offers the steepest expansion trajectory.
Delivery Mode:
Route of administration shapes cold chain infrastructure requirements, patient compliance profiles, and site-of-care economics for infusion centers versus retail pharmacy dispensing.
- Intravenous:Infusion-dependent checkpoint inhibitors and cytotoxics dominate hospital outpatient revenue capture, requiring specialized nursing capacity and adverse event monitoring infrastructure concentrated in urban academic medical centers.
- Oral:Small-molecule targeted agents enable patient self-administration and telemedicine-enabled monitoring, reducing treatment center capacity constraints and expanding rural geographic penetration where infusion infrastructure is scarce.
- Subcutaneous:Self-injectable formulations are emerging for select immunotherapy agents, promising to fragment site-of-care concentration and shift volume toward specialty pharmacy distribution.
- Topical:Localized application maintains limited role in pre-malignant lesion management with minimal systemic therapeutic overlap.
Intravenous anchors current hospital economics. Oral formulations are compressing site-of-care dependency fastest.
End User:
Customer concentration is restructuring around integrated delivery networks and specialized gynecologic oncology units that capture high-complexity cervical cancer cases and consolidate vendor relationships through preferred provider agreements.
- Hospitals:Tertiary care centers with dedicated gynecologic oncology programs concentrate checkpoint inhibitor volume through embedded clinical trial infrastructure and multidisciplinary tumor boards. Integrated delivery networks in the United States and hospital systems in Germany and France are consolidating procurement through direct manufacturer contracts with embedded biomarker testing and patient support services.
- Clinics:Community oncology practices face margin pressure as hospital outpatient departments capture immunotherapy administration under the 340B program in the United States and similar centralized purchasing mechanisms in European markets.
- Research Institutes:Academic medical centers drive pipeline enrollment for antibody-drug conjugates and bispecific constructs, compressing traditional development timelines through prioritized patient access.
- Homecare:Subcutaneous administration and oral agents are enabling limited shift toward home-based therapy supervision, though regulatory and reimbursement frameworks lag formulation innovation.
Hospitals dominate current volume capture. Research Institutes are concentrating pipeline influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates the highest value cervical cancer therapeutics demand through its hospital-based oncology networks and academic medical centers. FDA breakthrough therapy designations for checkpoint inhibitor combinations have compressed approval timelines and redirected patient flows toward immunotherapy maintenance protocols. Geographic variation in reimbursement mechanics creates pricing premiums in metropolitan clusters with integrated delivery network dominance.
United States
Hospital outpatient departments capture immunotherapy volume through the 340B program, concentrating demand in tertiary care centers with embedded clinical trial infrastructure. FDA oncology breakthrough therapy designations accelerate patient access to pembrolizumab-based combinations in recurrent settings. The Greater Boston and San Francisco Bay Area clusters anchor pipeline enrollment for antibody-drug conjugates through specialized gynecologic oncology units.
Germany
Health Technology Assessment harmonization initiatives compress pricing negotiation windows for novel oncology agents across statutory health insurance funds. The EMA's joint clinical assessment procedures require parallel scientific advice navigation for market access. The Rhine-Ruhr and Munich metropolitan regions concentrate hospital pharmacy procurement consolidation through direct manufacturer contracts with embedded biomarker testing services.
China
National cervical cancer elimination targets redirect patient flows toward earlier-stage detection with curative-intent systemic therapy combined with radiation. NMPA priority review pathways for innovative oncology drugs accelerate domestic and imported agent approvals. The Yangtze River Delta and Pearl River Delta clusters dominate biomarker testing infrastructure buildout across hospital-based oncology departments.
India
National screening program expansions under the WHO cervical cancer elimination initiative are creating addressable populations for stage III systemic therapy. CDSCO accelerated approval pathways for oncology therapeutics enable faster market entry for immunotherapy combinations. Maharashtra and Karnataka concentrate tertiary care oncology capacity through public-private hospital networks with embedded clinical trial access.
Japan
PMDA sakigake designation system compresses development timelines for novel immuno-oncology agents in recurrent cervical cancer. The national health insurance price listing system creates predictable reimbursement for checkpoint inhibitor maintenance protocols. The Kanto and Kansai metropolitan clusters concentrate gynecologic oncology specialization through designated cancer care hospitals with multidisciplinary tumor boards.
Cervical Cancer Therapeutics Market Vendor Landscape
Global majors compete with regional champions across regulatory pathway navigation and biomarker-linked commercialization strategies. The market structure concentrates around checkpoint inhibitor portfolios with companion diagnostic requirements, creating tiered competition between immuno-oncology specialists and diversified pharmaceutical conglomerates. Three archetypes dominate: integrated biopharmaceutical conglomerates with diagnostic divisions, pure-play oncology specialists with antibody-drug conjugate pipelines, and emerging biosimilar developers targeting margin-sensitive segments. Competitive moves center on companion diagnostic co-development partnerships and preferred provider agreements with integrated delivery networks.
Within the integrated biopharmaceutical tier, Merck & Co., Inc. and F. Hoffmann-La Roche Ltd occupy positions defined by checkpoint inhibitor franchises and diagnostic-linked therapy development. Bristol-Myers Squibb Company exemplifies the dual immunotherapy regimen specialist archetype in recurrent and metastatic settings. These three anchors represent distinct competitive vectors: diagnostic-therapy integration, combination regimen leadership, and survival curve extension in advanced disease.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd |
| Pfizer Inc. |
| Seagen Inc. |
| Bristol-Myers Squibb Company |
| GSK plc |
| AstraZeneca PLC |
| Novartis AG |
| Sanofi |
| Others |
Supply Flow & Price Mechanics
Checkpoint inhibitor manufacturing scale-up is compressing per-dose production economics while concentrating bioreactor capacity among contract manufacturing organizations in the United States, Germany, and Switzerland. This dual effect simultaneously reduces marginal costs for pembrolizumab-based regimens and creates supply bottleneck risks that reshape procurement negotiations between hospital systems and manufacturers.
Pricing Analysis
Input-cost pass-through from platinum precursor volatility directly affects chemotherapy backbone pricing, with cisplatin and carboplatin exposed to mining concentration in South Africa and Russia. Three-tier pricing structure across premium, standard, and economy levels separates branded checkpoint inhibitors from biosimilar entrants and cytotoxic generics. Pricing pressure stems from EMA conditional marketing authorization requirements that compress reimbursement negotiation windows. Community oncology practices exhibit highest price sensitivity due to 340B program displacement, while academic medical centers absorb premium pricing through embedded clinical trial infrastructure.
Supply Chain Analysis
EMA good manufacturing practice certification and FDA biologics license application requirements gate supplier qualification for monoclonal antibody production. Active pharmaceutical ingredient sourcing concentrates in China and India for small-molecule chemotherapies, while biologic drug substance manufacturing anchors in the United States, Germany, and Switzerland. Platinum group metal extraction draws from concentrated mining operations creating commodity price volatility exposure. Distribution runs through direct manufacturer-to-health system contracts with embedded cold chain logistics, displacing traditional wholesale intermediaries in favor of integrated service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cervical cancer therapeutics rests on biosimilar entry timelines compressing reference biologic pricing and enabling premium-tier maintenance for novel antibody-drug conjugates. Hospital pharmacy consolidation and companion diagnostic bundling create additional pricing power for integrated manufacturers.
For Market Incumbents: To counter biosimilar entry threatening pembrolizumab franchise value, deepen companion diagnostic co-development partnerships with Foundation Medicine and Agilent to lock in biomarker-linked prescribing. Secure preferred provider agreements with integrated delivery networks in Texas and Florida that concentrate gynecologic oncology volume through 340B-eligible hospital outpatient departments.
For New Entrants and Emerging Players: The premium-to-economy price gap in checkpoint inhibitor maintenance creates white-space capture opportunity for subcutaneous formulation specialists targeting rural infusion capacity constraints. Prioritize CDSCO accelerated approval pathways in Maharashtra and Karnataka where public-private hospital networks expand addressable populations. Position through telemedicine-enabled adverse event monitoring to reduce site-of-care dependency.
For Investors and Strategic Acquirers: Valuations sit cheapest among antibody-drug conjugate developers with Phase III-ready tissue factor programs lacking commercial infrastructure. Five-to-ten-year viability favors platforms with multiple tumor-type applications beyond cervical cancer. Monitor FDA breakthrough therapy designation velocity as inflection signal for competitive access compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Foundation Medicine partnerships with Merck and Roche synchronize biomarker assay approval with therapeutic launch timelines. |
| Biosimilar Manufacturing Scale-Up | Samsung Biologics and Celltrion capacity additions target European margin-sensitive segments as patent cliffs approach. |
| Subcutaneous Formulation Development | Self-injectable checkpoint inhibitors fragment site-of-care concentration toward specialty pharmacy distribution. |
| Integrated Delivery Network Contracting | Direct manufacturer agreements with Texas and Florida hospital systems embed patient support and biomarker testing services. |
| Antibody-Drug Conjugate Pipeline Advancement | Seagen and GSK tissue factor programs circumvent PD-1 resistance mechanisms in recurrent disease settings. |
Methodological Framework
Multiple input streams — executive interviews with formulary directors and regulatory affairs leads, hospital procurement database analysis, and clinical trial enrollment tracking — were reconciled against FDA filings, EMA submissions, and ClinicalTrials.gov records. Drug development executives at checkpoint inhibitor manufacturers, payer access specialists at national health insurance funds, and gynecologic oncology unit directors at academic medical centers provided primary perspective. Bottom-up patient-flow modeling and top-down revenue triangulation validated segmentation outputs across product type, application stage, and delivery mode dimensions.
Cross-referencing historical approval velocity against expert panel input shaped the analytical framework across the analysis window. Segmentation dimensions modeled include treatment line, administration route, PD-L1 biomarker status, and regional regulatory cluster. CAGRs were derived from patent expiration impact assessment, biosimilar penetration curves, and screening program expansion trajectories in India and China. Forecast inputs incorporated WHO cervical cancer elimination initiative policy commitments and NMPA priority review pathway utilization rates.
The model assumes a particular technology adoption path; alternative pathways for antibody-drug conjugate displacement of checkpoint inhibitor maintenance would alter the outlook. Forecasts reflect assumptions regarding EMA conditional marketing authorization confirmatory trial completion rates and platinum supply chain stability. A model refresh is warranted upon material change in FDA breakthrough therapy designation velocity or biosimilar interchangeability determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Acute Hepatic Porphyria (AHP) Treatment Market
Specialty Medicine
Immunology Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Polyarticular Juvenile Idiopathic Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Dupuytrens Disease Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Global Phenylketonuria Treatment Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Piriformis Syndrome Treatment Market