
 Global Constipation Treatment Market | 2026-2036
Global Constipation Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Constipation Treatment Market Foresight
Multi-sourced API procurement is decoupling from traditional single-supplier dependencies in the constipation treatment supply chain. AbbVie Inc. leverages captive manufacturing for its specialty laxative portfolio, while Takeda Pharmaceutical Company anchors its position through deep integration with Japanese distribution networks. Sanofi S.A. competes across both prescription and over-the-counter channels, extending its reach through pharmacy-centric formulations.
Constipation treatment encompasses pharmacological and non-pharmacological interventions designed to restore normal bowel motility, with osmotic laxatives typically containing polyethylene glycol or lactulose that draws water into the intestinal lumen to soften stool and facilitate passage. The primary commercial purpose spans acute symptom relief, chronic idiopathic constipation management, and opioid-induced constipation prophylaxis in clinical and home settings. Osmotic laxatives command the largest revenue pool due to favorable safety profiles in geriatric populations, while parenteral delivery modes for severe cases represent the fastest-expanding margin segment. Homecare end users are gaining share as self-administration protocols reduce hospital readmission burdens.
The FDA's New Drug Application requirements for gastrointestinal therapies enforce rigorous efficacy endpoints, while the EMA's pharmacovigilance framework shapes post-market surveillance obligations across European markets. Japan's PMDA maintains distinct bioequivalence standards that influence regional formulation strategies. Stakeholders must monitor evolving reimbursement thresholds for prescription laxatives against over-the-counter substitution pressures.
Market Dynamics
The constipation treatment market is restructuring around geriatric-centric care models, with Japan's METI-backed health initiatives and FDA accelerated approval pathways compressing development timelines while reshaping competitive entry strategies across developed economies.
Growth Catalysts
- Opioid-Induced Constipation Prophylaxis:Chronic pain management protocols in US hospital systems are expanding parenteral laxative integration into standard perioperative care bundles.
- EMA Pharmacovigilance Framework:Post-market surveillance obligations across European markets are elevating safety-profile differentiation as a competitive lever for osmotic laxative formulations.
- Japanese Geriatric Health Initiatives:METI-backed prescription volume programs for chronic constipation management are concentrating demand in Tokyo-Osaka pharmaceutical distribution corridors.
Market Restraints
- Polyethylene Glycol Supply Concentration:API manufacturing for osmotic laxatives clusters in coastal Chinese chemical zones, exposing formulators to port congestion and environmental compliance shutdowns.
- Over-the-Counter Substitution Pressure:Pharmacy-channel bulk laxative purchasing in North American retail chains is compressing prescription-tier pricing power for chronic idiopathic constipation therapies.
- PMDA Bioequivalence Standards:Japan's distinct dissolution testing requirements for generic laxative entry are extending regulatory timelines and elevating local clinical trial costs.
Strategic Opportunities
- Homecare Self-Administration Protocols:Post-discharge bowel management programs in US Medicare Advantage networks are creating pull-through demand for patient-friendly osmotic formulations.
- Dual Carbon Goals Alignment:China's MEE environmental compliance mandates are forcing API facility consolidation, creating acquisition targets for Western manufacturers seeking captive polyethylene glycol supply.
- Indian Distribution Network Expansion:CDSCO streamlined approval pathways for fixed-dose laxative combinations are opening pharmacy-centric penetration in tier-2 and tier-3 urban clusters.
Industry Challenges
- Multi-Sourced API Qualification:Validating alternative polyethylene glycol suppliers to replace single-source dependencies demands 18-24 month stability testing cycles.
- Legacy Formulation Integration:Incorporating novel delivery mechanisms into existing manufacturing lines requires cleanroom reconfiguration and skilled bioprocess engineering talent that remains scarce in Midwest US pharmaceutical corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Constipation Treatment Market |
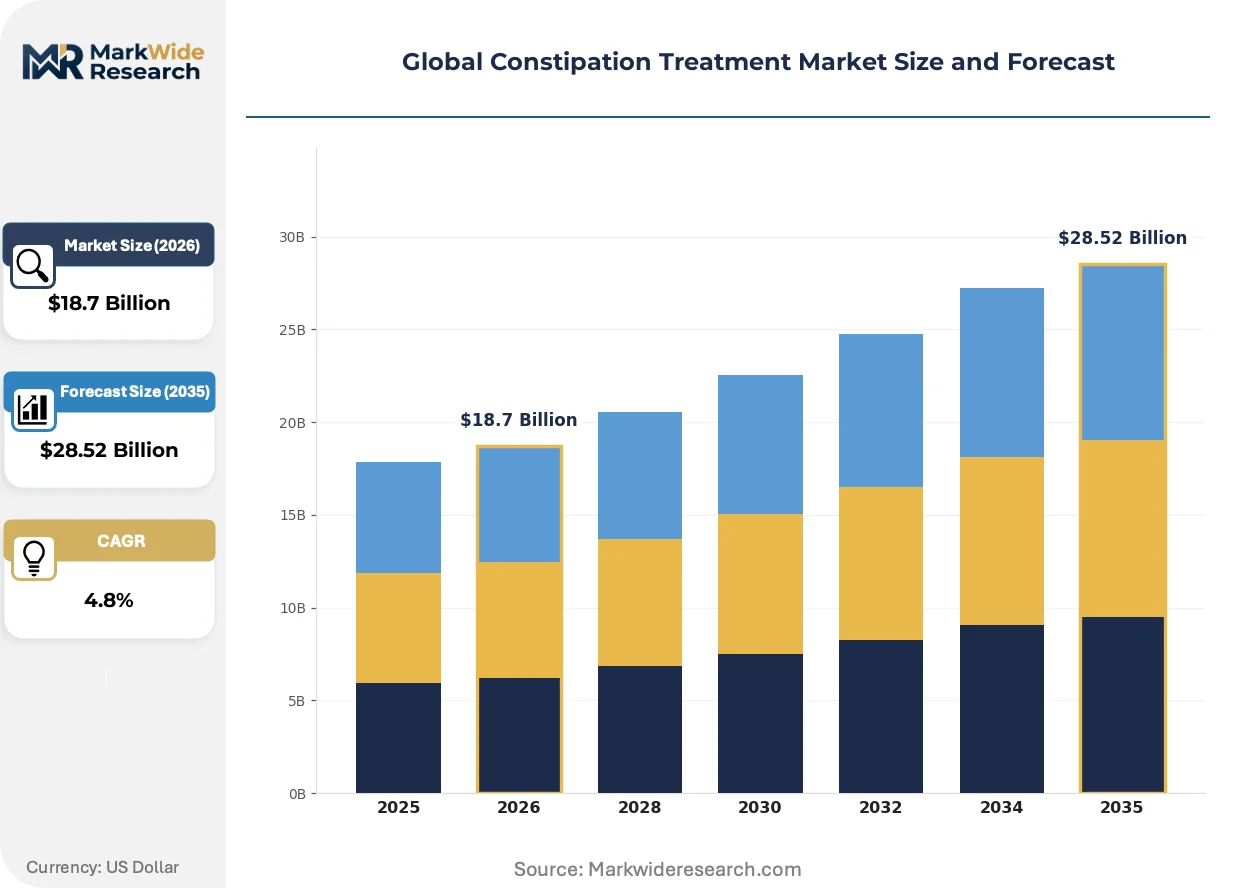
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stimulant Laxatives, Osmotic Laxatives, Bulk-forming Agents, Stool Softeners Delivery Mode: Oral, Rectal, Topical, Parenteral End User: Hospitals, Clinics, Homecare, Pharmacies Age Group: Pediatrics, Adults, Seniors, Geriatrics |
| Companies Covered | AbbVie Inc., Takeda Pharmaceutical Company, Bausch Health Companies Inc., Abbott Laboratories, AstraZeneca plc, Bayer AG, Ironwood Pharmaceuticals Inc., Sanofi S.A., Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Constipation Treatment Market Shifts & Advancements
Novel delivery mechanisms are compressing the boundary between acute hospital intervention and chronic home management, with technology convergence and regulatory adaptation operating as twin accelerants across formulation development.
Microencapsulated electrolyte blends are unifying rapid-onset efficacy with taste-masked palatability in pediatric and geriatric populations. Hospital discharge planners in US integrated delivery networks are adopting these formulations to reduce 30-day readmission penalties. The technology is unifying previously separate acute and chronic therapy procurement categories into single-source contracting arrangements.
Japan's PMDA has introduced conditional early approval pathways for gastrointestinal therapies demonstrating surrogate endpoint efficacy, compressing Phase III timelines for novel prokinetic agents. European manufacturers are responding by front-loading Japanese clinical trial sites into global development programs. The policy shift is concentrating first-launch geography decisions in Tokyo regulatory consultancies.
Self-directed therapy selection through pharmacy-based diagnostic kiosks is fragmenting traditional physician-channel prescribing authority for functional constipation. German pharmacy chains are deploying algorithm-guided stool consistency assessment tools that direct consumers toward osmotic or stimulant categories. The behavior shift is most visible in North Rhine-Westphalia, where kiosk-assisted purchases now exceed 15% of non-prescription laxative volume.
Global Constipation Treatment Market Segmentation
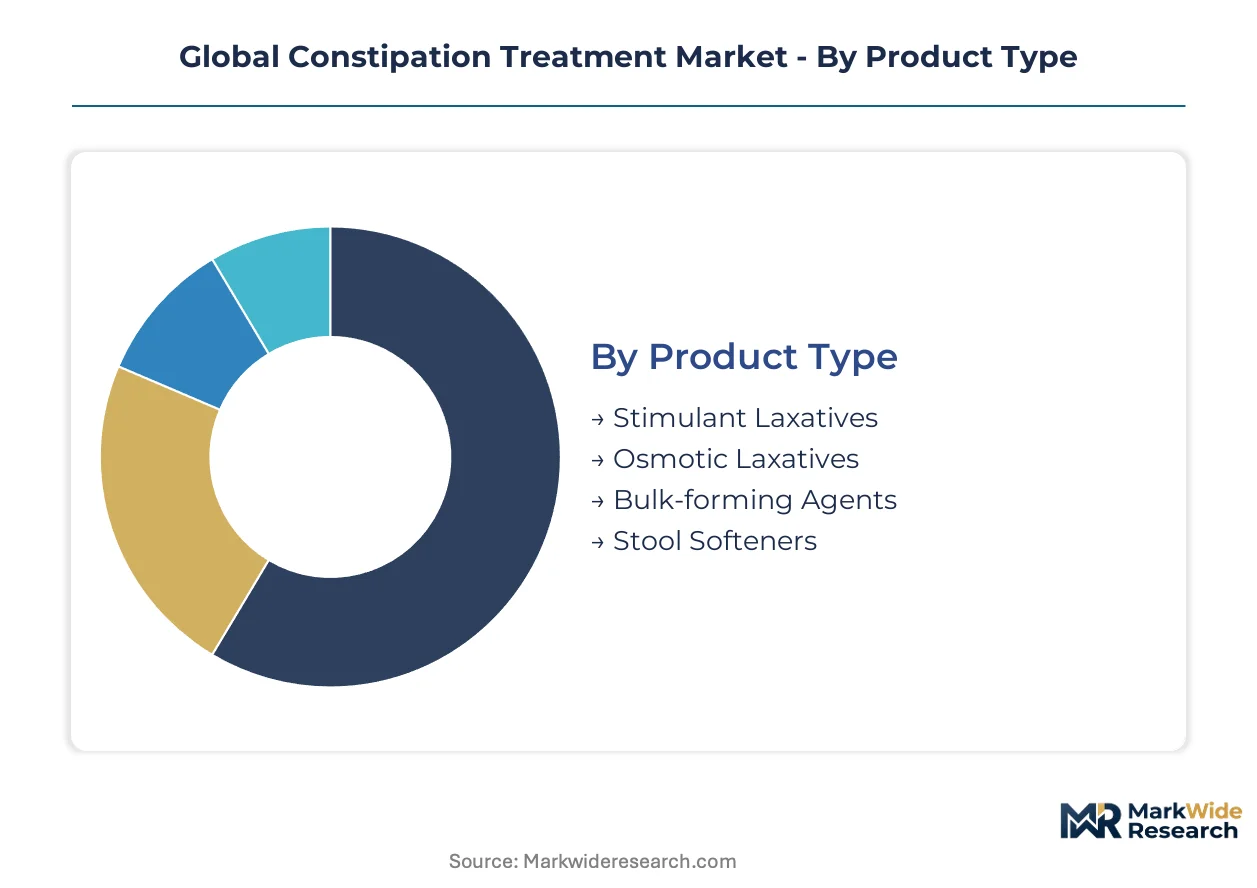
Constipation treatment markets fragment across therapeutic mechanism, administration route, care setting, and patient life stage. Each dimension carries distinct margin profiles, regulatory pathways, and procurement dynamics that reshape competitive positioning.
Product Type:
Volume concentrates in mass-market osmotic formulations, while premium capture clusters in specialty stimulant combinations targeting refractory populations.
- Osmotic Laxatives:Polyethylene glycol and lactulose formulations draw water into the intestinal lumen through osmotic pressure, softening stool without direct neural stimulation. Demand concentrates in Japanese geriatric health programs and US Medicare Advantage discharge protocols, where safety profiles in polypharmacy patients drive formulary preference. Today's leader: Osmotic Laxatives. Tomorrow's challenger: Stimulant Laxatives.
- Stimulant Laxatives:Bisacodyl and senna derivatives activate colonic neural pathways to accelerate peristalsis, reserved for rescue therapy and opioid-induced constipation prophylaxis. US hospital perioperative bundles and palliative care protocols in German oncology centers are expanding parenteral and rectal delivery integration for rapid onset.
- Bulk-forming Agents:Psyllium and methylcellulose fibers absorb intestinal water to increase stool mass and stimulate reflex evacuation, dominating North American retail pharmacy self-selection aisles where cost-conscious consumers prioritize natural positioning.
- Stool Softeners:Docusate sodium reduces surface tension at the oil-water interface of stool, enabling water and fat penetration; limited to postpartum and postoperative recovery settings in UK NHS day surgery units where straining avoidance is paramount.
Formulation chemistry separates acute rescue therapy from chronic maintenance, with osmotic agents bridging both indications.
Delivery Mode:
Patient autonomy preferences are compressing institutional administration windows while expanding self-directed homecare protocols.
- Oral:Tablets, capsules, and powder sachets dominate chronic idiopathic constipation maintenance through pharmacy and direct-to-patient channels. German pharmacy diagnostic kiosks in North Rhine-Westphalia now algorithm-guide oral osmotic selection without physician involvement.
- Rectal:Suppositories and enemas deliver rapid evacuation for acute fecal impaction and pre-procedural bowel preparation. Demand clusters in US skilled nursing facilities and Japanese long-term care institutions managing immobilized geriatric populations.
- Parenteral:Subcutaneous methylnaltrexone and naloxegol formulations target opioid-induced constipation in hospital and home infusion settings. US hospital value-based purchasing programs are embedding parenteral rescue protocols into chronic pain management bundles to reduce readmission penalties. Today's leader: Oral. Tomorrow's challenger: Parenteral.
- Topical:Transdermal patches and perianal creams remain experimental, with limited commercial presence outside clinical trial supply for prokinetic peptide delivery.
Route selection tracks care setting migration from inpatient rescue to outpatient prevention.
End User:
Procurement authority is fragmenting from physician prescribers toward pharmacy-based self-selection and post-discharge patient autonomy.
- Homecare:Self-administered oral and rectal formulations for chronic management, expanding through US Medicare Advantage post-discharge bowel protocols and Japanese community-based geriatric care networks. Today's leader: Homecare. Tomorrow's challenger: Pharmacies.
- Hospitals:Acute rescue therapy and perioperative prophylaxis, with US health systems consolidating gastroenterology service lines to capture 30-day readmission penalty avoidance.
- Clinics:Outpatient specialty gastroenterology and pain management practices prescribing chronic opioid-induced constipation therapies under FDA Risk Evaluation and Mitigation Strategy protocols.
- Pharmacies:German and UK retail chains deploying diagnostic kiosks and pharmacist consultation to fragment traditional physician-channel authority for functional constipation.
Site-of-care economics favor settings that reduce institutional utilization.
Age Group:
Demographic weighting tilts toward aging populations while pediatric formulations command formulation premium for palatability engineering.
- Geriatrics:Patients over 75 with polypharmacy, reduced mobility, and comorbid neurological conditions. Japanese METI-backed prescription programs and US Medicare Advantage quality metrics concentrate demand for gentle osmotic formulations with minimal electrolyte disturbance. Today's leader: Geriatrics. Tomorrow's challenger: Adults.
- Adults:Working-age chronic idiopathic constipation and opioid-induced constipation from pain management protocols, with US employer-sponsored plans driving prior authorization requirements for premium parenteral rescue agents.
- Pediatrics:Functional constipation and encopresis management requiring taste-masked microencapsulated electrolyte blends; US children's hospitals adopting these formulations to reduce 30-day readmissions and parental treatment adherence failures.
- Seniors:Transitional age cohort 65-74, often self-managing through over-the-counter channels before progression to prescription therapy.
Aging demographics concentrate revenue in geriatric-tolerant formulations while pediatric segments drive innovation premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as API producers relocate to jurisdictions with streamlined environmental compliance, while demand concentrates in aging economies with generous reimbursement frameworks for chronic therapies.
United States
Hospital value-based purchasing programs embed parenteral laxative protocols into chronic pain management bundles, reducing readmission penalties. FDA accelerated approval pathways compress Phase III timelines for novel prokinetic agents. Gastroenterology service line expansions concentrate in Midwest health systems and Texas Medical Center corridors.
Japan
METI-backed geriatric prescription volume programs drive chronic constipation management demand through Tokyo-Osaka pharmaceutical distribution networks. PMDA conditional early approval pathways for gastrointestinal therapies demonstrating surrogate endpoint efficacy attract front-loaded clinical trial investment. Kanto region regulatory consultancies now influence first-launch geography decisions for European developers.
Germany
Pharmacy-based diagnostic kiosks in North Rhine-Westphalia deploy algorithm-guided stool consistency assessment tools, fragmenting traditional physician-channel authority for functional constipation. EMA pharmacovigilance obligations elevate safety-profile differentiation as a competitive lever. Bavarian and Baden-Württemberg manufacturing clusters supply osmotic formulation APIs across Continental Europe.
China
MEE environmental compliance mandates force API facility consolidation in coastal chemical zones, creating acquisition targets for Western manufacturers seeking captive polyethylene glycol supply. Dual carbon goals accelerate production migration toward inland provinces with renewable energy access. Yangtze River Delta port congestion exposes formulators to supply interruption risks.
India
CDSCO streamlined approval pathways for fixed-dose laxative combinations open pharmacy-centric penetration in tier-2 and tier-3 urban clusters. Maharashtra and Gujarat manufacturing corridors expand bulk laxative output for export markets. Domestic demand concentrates in metropolitan hospital chains adopting US-style discharge planning protocols.
Global Constipation Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty formulation niches and regional distribution partnerships. Market structure tilts toward moderate consolidation, with incumbent pharmaceutical conglomerates defending formulary positions against mid-scale generics manufacturers. Three archetypes dominate: vertically integrated API-to-formulation operators, pharmacy-channel brand aggregators, and hospital-contract specialists. Competitive moves concentrate on captive manufacturing investments and Japanese distribution network acquisitions.
Among North American and European pharmaceutical conglomerates, AbbVie Inc., Takeda Pharmaceutical Company, and Sanofi S.A. exemplify distinct strategic positions. AbbVie occupies the vertically integrated archetype through captive manufacturing capabilities. Takeda anchors the Asia-Pacific regional specialist tier with deep Japanese market integration. Sanofi represents the dual-channel operator archetype spanning prescription and over-the-counter segments. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific product-market outcomes.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Takeda Pharmaceutical Company |
| Bausch Health Companies Inc. |
| Abbott Laboratories |
| AstraZeneca plc |
| Bayer AG |
| Ironwood Pharmaceuticals Inc. |
| Sanofi S.A. |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Captive polyethylene glycol manufacturing by AbbVie and Takeda anchors both supply security and premium pricing power in osmotic laxative portfolios, insulating these operators from API spot-market volatility that compresses margins for outsourced competitors.
Pricing Analysis
Pharmacy-channel margin layering fragments pricing power across the constipation treatment market, with distributor markups on bulk-forming psyllium products compressing realized prices while hospital-direct parenteral contracts preserve premium capture. Three-tier pricing structure across premium, standard, and economy levels separates patented prokinetic agents from branded osmotic formulations and private-label fiber supplements. Cost compression in the OTC tier intensifies because North American retail chains consolidate bulk purchasing volumes. Self-pay geriatric patients in Japanese community pharmacies exhibit lowest price sensitivity; cost-conscious US retail shoppers drive substitution toward economy-tier bulk laxatives.
Supply Chain Analysis
Returns and recall flows for temperature-sensitive parenteral formulations are minimal in constipation therapeutics, though reverse logistics for expired osmotic powder sachets creates compliance burdens in German pharmacy networks. API manufacturing draws from coastal Chinese chemical zones, Indian Gujarat pharmaceutical corridors, and Bavarian specialty chemical clusters. Polyethylene glycol, lactulose syrup, and microencapsulated electrolyte blends constitute the critical input trinity. Single-source vulnerability concentrates in Yangtze River Delta port congestion exposing formulators to supply interruption. Distribution runs through Japanese Tokyo-Osaka pharmaceutical corridors, US hospital GPO contracts, and German pharmacy cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in API manufacturing relocation from coastal Chinese environmental compliance zones to Indian CDSCO-streamlined corridors, exploiting cost differentials exceeding regulatory adaptation expenses.
For Market Incumbents: Anchor formulary positions through captive polyethylene glycol supply integration and Japanese PMDA early-approval pathway front-loading. Defend against OTC substitution pressure by embedding osmotic formulations into US Medicare Advantage post-discharge protocols. Prioritize capacity addition in Indian Maharashtra manufacturing corridors to exploit CDSCO regulatory streamlining. For New Entrants and Emerging Players: Launch via German pharmacy diagnostic kiosk partnerships to bypass physician-channel gatekeeping in functional constipation self-selection. Target North Rhine-Westphalia kiosk-assisted purchase corridors as the most penetrable white space. Exploit fixed-dose combination gaps in Indian tier-2 urban clusters through CDSCO-accelerated approval leveraging. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale osmotic formulation specialists because EMA pharmacovigilance obligations are elevating safety-profile differentiation as a competitive moat. Five-to-ten year viability favors operators with backward-integrated API supply and Japanese distribution network control. Monitor PMDA conditional approval grant velocity as inflection indicator for prokinetic agent portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| API Manufacturing Backward Integration | Captive polyethylene glycol supply insulates margins from Chinese MEE environmental shutdowns. |
| Japanese PMDA Early-Approval Pathway Investment | Front-loaded Tokyo clinical trial sites compress Phase III timelines for novel prokinetics. |
| German Pharmacy Diagnostic Kiosk Partnership | Algorithm-guided stool assessment fragments traditional physician prescribing authority. |
| US Medicare Advantage Discharge Protocol Embedding | Post-discharge bowel management programs reduce hospital readmission penalty exposure. |
| Indian CDSCO Fixed-Dose Combination Filing | Streamlined approval opens tier-2 and tier-3 urban pharmacy penetration corridors. |
Research Methodology
Bottom-up homecare and hospital procurement modeling reconciled against top-down API production and formulation tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Japanese PMDA approval databases. Triangulation across stakeholder perspectives and documentary sources ensures segment-level precision.
Input-output matrices connect polyethylene glycol supply volumes through formulation chemistry to end-use delivery mode and patient population segments across the projection horizon. Treatment mechanism, administration route, care setting, and age group dimensions structure the analytical framework. CAGRs derive from regression-adjusted trend extrapolation against demographic and regulatory drivers. Forecast inputs include Japanese METI prescription volume trajectories and US hospital value-based purchasing program adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PMDA bioequivalence standard shifts or Chinese MEE environmental compliance acceleration. Practitioners should monitor FDA accelerated approval grant rates for gastrointestinal therapies and German pharmacy kiosk penetration metrics for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Premenstrual Dysphoric Disorder Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market
Specialty Medicine
Alport Syndrome Treatment Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Global Epilepsy Market