
 Dementia Management Market | 2026-2036
Dementia Management Market Size, Share, and Industry Trends Forecast 2026-2036
Dementia Management Market Outlook
The FDA accelerated approval pathway is expanding the cost-of-entry calculus for dementia drug developers, demanding larger confirmatory trial commitments before full commercialization. Eisai Co., Ltd. leverages its lecanemab manufacturing scale to anchor supply chains across North American infusion networks. Biogen Inc. sustains competitive relevance through its established neurology infrastructure and prescriber relationships in Alzheimer's Disease.
Dementia management encompasses the coordinated delivery of pharmacological interventions, cognitive rehabilitation protocols, assistive devices, and caregiver support systems designed to slow disease progression and maintain functional independence in neurodegenerative conditions. Drug therapy dominates current revenue pools, though assistive technology segments are attracting capital as sensor-based home monitoring achieves clinical validation. Telemedicine delivery modes are expanding fastest among end-user channels, driven by workforce shortages in long-term facilities and payer pressure to reduce institutional care costs.
FDA, EMA, and WHO standards collectively shape trial design requirements, biomarker acceptance criteria, and post-market surveillance obligations for dementia therapeutics. The FDA's draft guidance on digital health technologies for neurological conditions is creating new regulatory benchmarks for cognitive assessment tools. Stakeholders must monitor evolving payer coverage policies for combination therapy regimens that pair disease-modifying drugs with digital therapeutics.
Market Dynamics
Medicare coverage determinations for disease-modifying therapies are restructuring prescriber economics and pulling capital toward confirmatory trial infrastructure. This reimbursement pivot is compressing commercialization timelines while elevating manufacturing scale requirements.
Growth Catalysts
- FDA Accelerated Approval Pathway:The pathway compresses time-to-market for amyloid-clearing monoclonal antibodies, drawing venture funding into Phase III confirmatory trials. Developers must pre-commit to post-market efficacy studies before full commercialization.
- Value-Based Care Contracts:CMS Innovation Center models tie reimbursement to cognitive outcome metrics, incentivizing health systems to adopt remote monitoring platforms for early intervention.
- Biomarker-Defined Enrollment:PET imaging and CSF testing protocols are refining trial populations, improving signal detection and reducing sample size requirements for regulatory submission.
Market Restraints
- Infusion Network Concentration:North American specialty pharmacy capacity limits patient access to intravenous disease-modifying therapies, creating geographic inequity in treatment availability.
- Biologic Manufacturing Complexity:Cold-chain requirements for monoclonal antibodies elevate per-dose production costs and constrain batch scalability.
- Confirmatory Trial Burden:FDA mandates for ongoing efficacy studies extend R&D capital lock-up periods, compressing returns for developers without platform scale.
Strategic Opportunities
- Digital Therapeutic Pairing:Cognitive training software combined with pharmacotherapy opens reimbursement codes under Medicare's remote therapeutic monitoring framework.
- Home-Based Diagnostic Kits:Blood-based biomarker assays enable pre-symptomatic screening outside clinical settings, expanding addressable populations.
- Japan's Dementia Prevention Initiative:METI-funded regional care hubs create procurement channels for integrated assistive technology platforms.
Industry Challenges
- Specialized Neurology Workforce Scarcity:Fellowship-trained cognitive neurologists remain concentrated in academic medical centers, limiting community-based diagnosis capacity.
- Legacy EHR Integration Friction:Cognitive assessment data from digital tools lacks standardized interoperability with hospital record systems, complicating care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dementia Management Market |
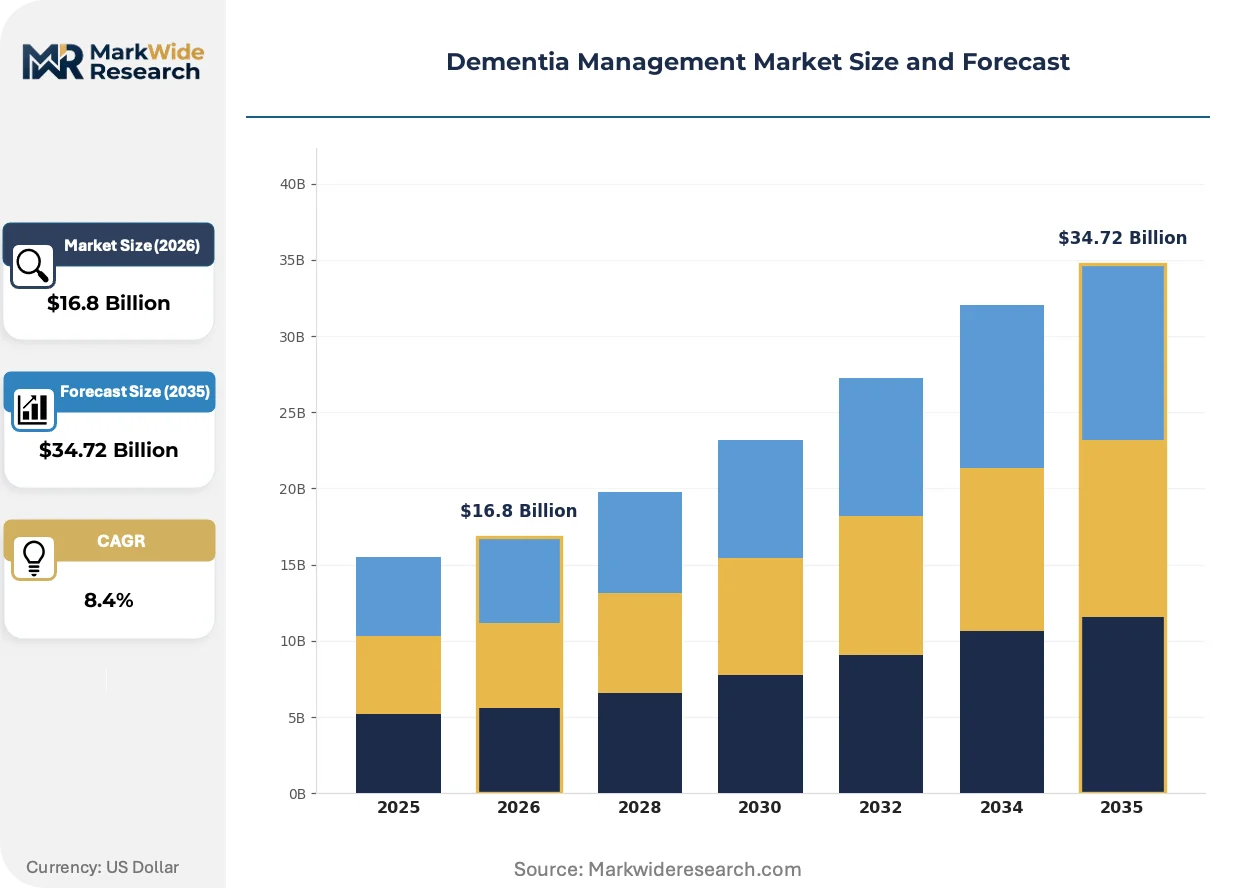
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $34.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug Therapy, Cognitive Stimulation, Assistive Technology, Caregiver Support End User: Clinical Settings, Home Care, Long-term Facilities, Telemedicine Delivery Mode: In-person, Online, Hybrid, Mobile Applications Therapy Area: Alzheimer's Disease, Vascular Dementia, Lewy Body Dementia, Frontotemporal Dementia |
| Companies Covered | Eisai Co., Ltd., Biogen Inc., Eli Lilly and Company, Novartis AG, Roche Holding AG, AbbVie Inc., Johnson & Johnson, Pfizer Inc., Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dementia Management Market Strategic Shifts
Sensor-based passive monitoring is displacing scheduled clinical assessments as the primary data source for disease progression tracking. This shift is compressing trial endpoints and enabling decentralized study designs.
Artificial intelligence algorithms analyzing speech patterns and gait metrics are integrating into wearable devices for continuous functional assessment. Home care agencies in the United States and Germany are piloting these systems for fall-risk prediction and medication adherence monitoring. The technology is integrating longitudinal behavioral data into payer risk-adjustment models, reshaping how capitated contracts price dementia care episodes.
The FDA's draft guidance on digital health technologies for neurological conditions is establishing validation benchmarks for cognitive assessment software. Developers must now demonstrate equivalence to paper-based neuropsychological batteries before marketing claims. Medical device divisions at academic medical centers in Boston and San Francisco are building internal validation labs to accelerate regulatory submission timelines.
Family caregivers are purchasing direct-to-consumer genetic testing for APOE status, creating demand for pre-symptomatic counseling infrastructure. Employer-sponsored health plans in technology and finance sectors are adding memory clinic navigation benefits. This behavioral shift concentrates demand in metropolitan areas with established neurology referral networks, widening rural-urban access gaps.
Dementia Management Market Segmentation
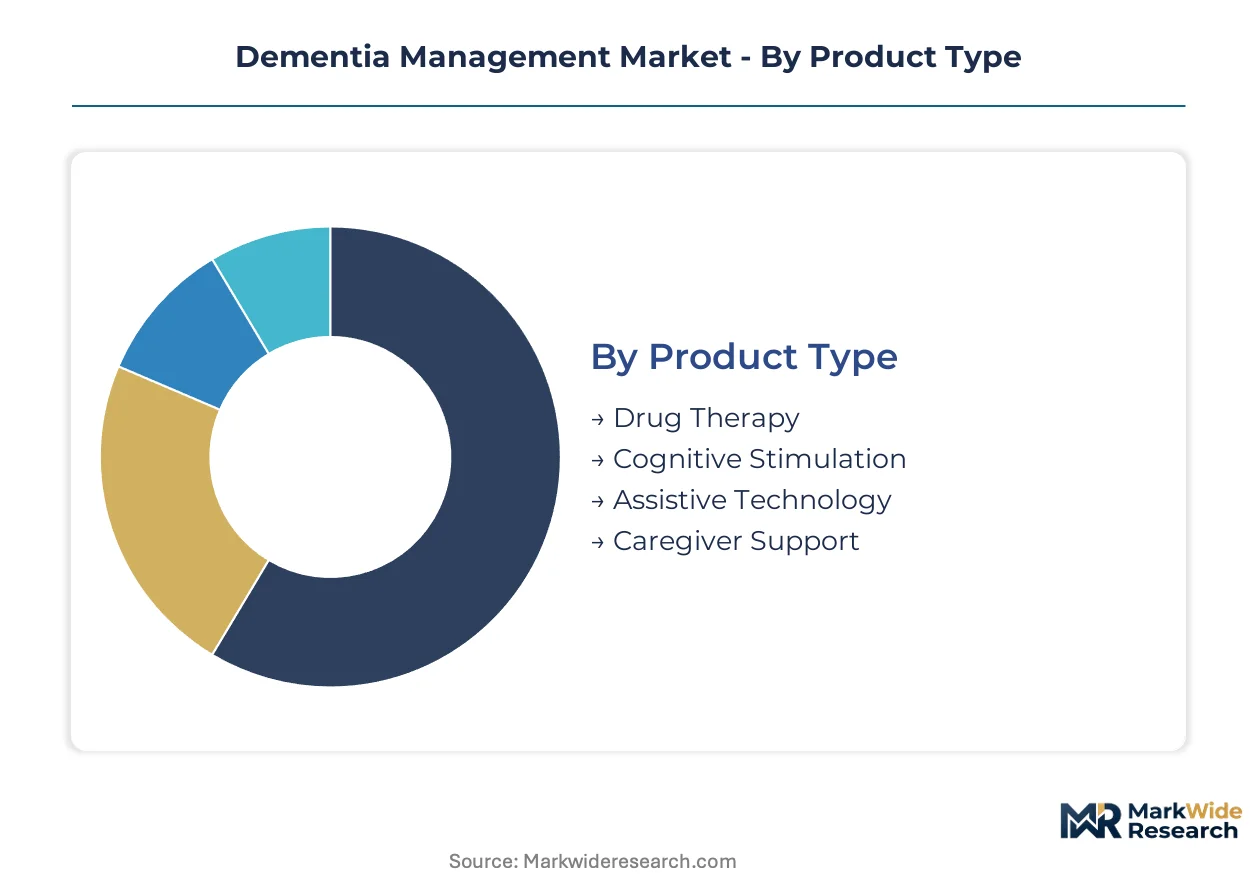
Dementia management markets fragment across therapeutic modalities, care settings, and disease phenotypes. Capital allocation patterns diverge sharply between biologic manufacturing infrastructure and digital service platforms. Understanding segment-level economics reveals where reimbursement tailwinds concentrate versus where cost pressures dominate.
Product Type:
Drug therapy commands the steepest upfront capital requirements, with monoclonal antibody manufacturing facilities demanding billion-dollar investments before first commercial batch.
- Drug Therapy:Amyloid-clearing monoclonal antibodies and symptomatic treatments require cold-chain biologics infrastructure. Demand concentrates in United States infusion networks as Medicare coverage determinations reshape prescriber economics and site-of-care decisions.
- Cognitive Stimulation:Structured cognitive training protocols and reminiscence therapy programs deploy through digital platforms and in-person sessions. German memory clinics and United States health systems are integrating these into value-based dementia care contracts tied to outcome metrics.
- Assistive Technology:Sensor-based home monitoring and GPS tracking devices.
- Caregiver Support:Respite services, training programs, and counseling infrastructure.
Most installed capacity flows through Drug Therapy. Expansion is steepest in Assistive Technology.
End User:
Volume distribution tracks reimbursement site-of-care policies, with telemedicine channels gaining share fastest as workforce constraints bite.
- Clinical Settings:Memory clinics, neurology practices, and hospital outpatient departments deliver diagnosis and infusion services. United States academic medical centers anchor monoclonal antibody administration while community neurology practices face capacity constraints from specialized workforce scarcity.
- Home Care:In-home nursing, personal care assistance, and remote monitoring deployment. Medicare's remote therapeutic monitoring framework is expanding reimbursement for sensor-based cognitive assessment in United States home health agencies.
- Long-term Facilities:Skilled nursing and assisted living dementia care units.
- Telemedicine:Virtual cognitive assessment and care coordination platforms.
Clinical Settings retain the highest revenue per patient episode. Telemedicine is climbing the fastest as labor shortages force decentralization.
Delivery Mode:
Platform economics diverge between high-touch in-person services and scalable digital infrastructure with minimal marginal cost.
- In-person:Face-to-face clinical consultations, home visits, and facility-based care delivery. Japan's METI-funded regional dementia care hubs are expanding in-person assessment capacity as part of national prevention initiatives.
- Online:Web-based cognitive training, caregiver education portals, and virtual support groups. German statutory health insurers are reimbursing online cognitive rehabilitation modules under digital health application frameworks.
- Hybrid:Blended care models combining scheduled in-person visits with continuous remote monitoring.
- Mobile Applications:Smartphone-based cognitive assessment and medication adherence tools.
In-person delivery still captures the majority of reimbursed encounters. Mobile Applications are gaining share fastest among working-age caregiver populations.
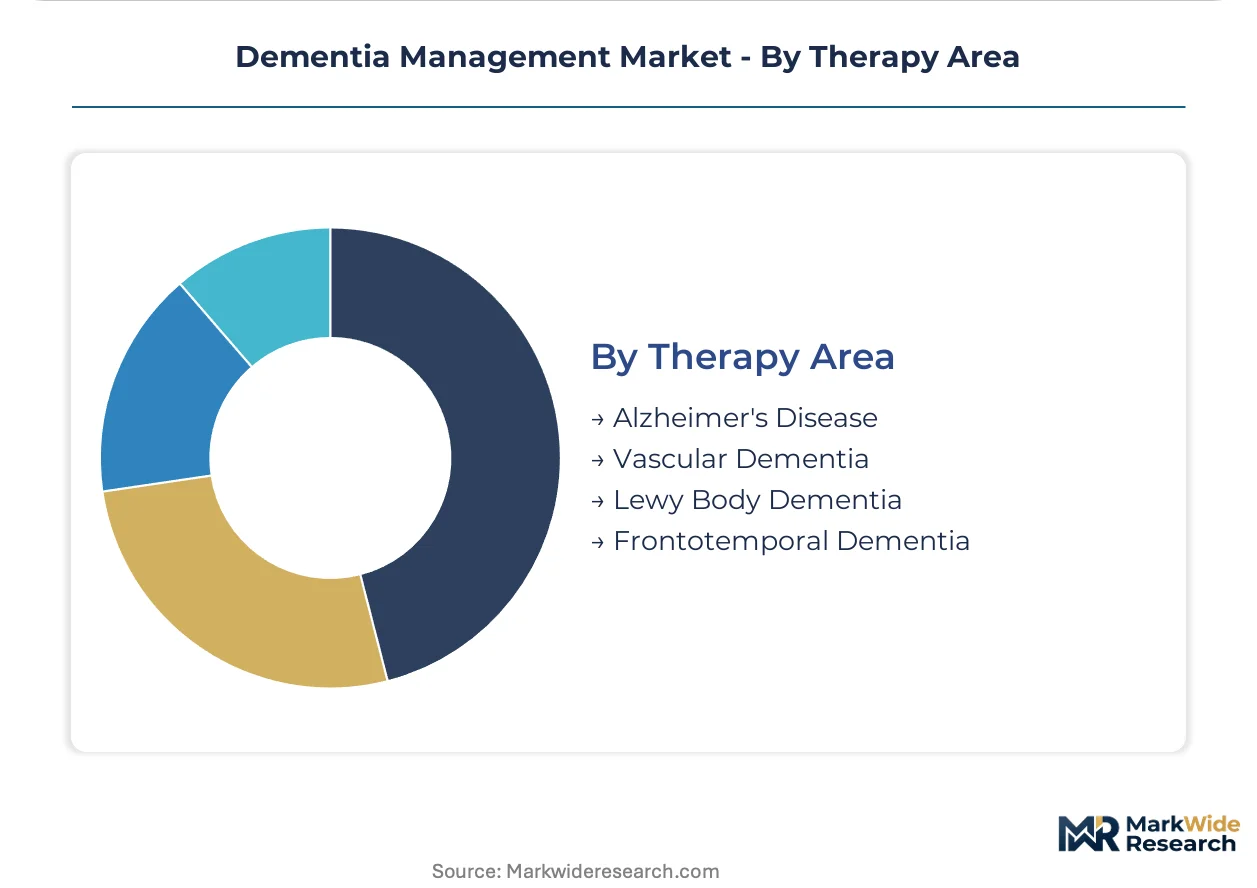
Therapy Area:
Addressable population size and biomarker validation maturity determine clinical trial investment intensity across dementia phenotypes.
- Alzheimer's Disease:The largest therapeutic focus with established amyloid and tau biomarker pathways. FDA accelerated approval pathways have concentrated Phase III investment here, though confirmatory trial burdens extend capital lock-up periods for developers.
- Vascular Dementia:Mixed pathology presentations combining neurodegenerative and cerebrovascular mechanisms. United States Veterans Health Administration systems are prioritizing vascular risk factor management integration into dementia care protocols.
- Lewy Body Dementia:Parkinson's disease dementia and dementia with Lewy bodies requiring differential diagnostic protocols.
- Frontotemporal Dementia:Early-onset phenotypes with distinct genetic and clinical profiles.
Alzheimer's Disease absorbs the dominant share of R&D expenditure. Frontotemporal Dementia is expanding most quickly in genetic screening and biomarker development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dementia management infrastructure first achieved commercial scale in the United States during the 1980s academic medical center expansion, with European and Asian markets subsequently adapting reimbursement frameworks to match evolving therapeutic modalities.
United States
Medicare coverage determinations for monoclonal antibody therapies concentrate patient volume in academic infusion centers across Boston, Baltimore, and San Francisco. FDA accelerated approval pathways compress development timelines while demanding expanded confirmatory trial infrastructure. The Veterans Health Administration operates specialized dementia care protocols integrating vascular risk management across its hospital network.
Germany
Statutory health insurance reimbursement for digital cognitive rehabilitation modules expands addressable populations beyond traditional clinical settings. The country's digital health application framework creates regulatory clarity for software-based interventions. Memory clinics in Munich and Heidelberg anchor integrated care models combining pharmacotherapy with structured cognitive training programs.
Japan
METI-funded regional dementia care hubs distribute assessment capacity across prefectural health systems. The national dementia prevention initiative directs procurement toward integrated assistive technology platforms. Osaka and Nagoya medical device clusters specialize in sensor-based home monitoring systems for aging-in-place populations.
United Kingdom
NHS long-term plan commitments expand memory clinic capacity within integrated care systems. NICE technology appraisals determine formulary placement for disease-modifying therapies across England. The Cambridge and Oxford neuroscience clusters concentrate biomarker research infrastructure and early-phase clinical trial operations.
Switzerland
Swissmedic regulatory pathways attract Phase I/II dementia drug development through streamlined investigator-initiated trial frameworks. Cantonal health insurance mandates ensure universal coverage for cognitive assessment services. The Basel pharmaceutical corridor hosts contract manufacturing organizations specializing in biologic drug substance production.
Dementia Management Market Competitive Environment
The competitive structure tilts toward biopharma incumbents with established neurology infrastructure and cold-chain manufacturing scale. Market concentration remains elevated at the therapeutic development tier, while assistive technology and digital service segments fragment across specialized vendors. Three archetypes dominate: monoclonal antibody developers with infusion network partnerships, digital therapeutic platforms seeking reimbursement codes, and integrated care coordinators bundling pharmacotherapy with remote monitoring. Capacity expansion and strategic partnerships represent the dominant competitive moves, with developers pre-committing to post-market study infrastructure to secure accelerated approvals.
Within the monoclonal antibody developer tier, Eisai Co., Ltd. and Biogen Inc. occupy positions shaped by manufacturing scale requirements and prescriber relationship density. Eli Lilly and Company exemplifies the integrated pharmaceutical archetype combining therapeutic development with diagnostic biomarker infrastructure. These three entities anchor competitive dynamics around confirmatory trial commitments and site-of-care economics rather than traditional promotional intensity.
| Leading Market Players |
|---|
| Eisai Co., Ltd. |
| Biogen Inc. |
| Eli Lilly and Company |
| Novartis AG |
| Roche Holding AG |
| AbbVie Inc. |
| Johnson & Johnson |
| Pfizer Inc. |
| Lundbeck A/S |
| Others |
Value Chain & Pricing Dynamics
Amyloid-clearing monoclonal antibody manufacturers command premium pricing tiers against symptomatic treatment generics, with that bifurcation manifesting in cold-chain biologics infrastructure investments upstream and site-of-care economics downstream. Bundled infusion services at academic medical centers in the United States absorb margin through specialty pharmacy handling fees, while unbundled digital therapeutic subscriptions face reimbursement code fragmentation across Medicare Advantage plans.
Pricing Analysis
Bundled infusion-administration packages versus unbundled drug-only procurement define the dominant pricing split. Three-tier pricing structure across premium biologics, standard small-molecule symptomatics, and economy generic equivalents differentiates by FDA approval pathway and biomarker-defined eligibility. Pricing pressure stems from confirmatory trial cost recovery mandates compressing net margins for developers without platform scale. Medicare Advantage plans exhibit highest price sensitivity, while self-funded employer health plans demonstrate lowest sensitivity due to memory clinic navigation benefit commitments.
Supply Chain Analysis
Warehouse-distribution layers for monoclonal antibodies operate through regional distribution centers in the United States, Switzerland, and Japan with validated cold-chain continuity. Active pharmaceutical ingredients draw from bioreactor facilities in Basel, North Carolina, and Osaka with single-source dependency on porcine-derived media components. Supply chain risk centers on customs clearance delays for temperature-sensitive batches at transatlantic logistics chokepoints. Distribution runs through specialty pharmacy networks with hub-and-spoke patterns radiating from academic infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where prescriber economics now favor integrated care coordinators bundling pharmacotherapy with remote monitoring over standalone drug vendors. That demand-shift toward premium specifications reflects Medicare's remote therapeutic monitoring framework expansion.
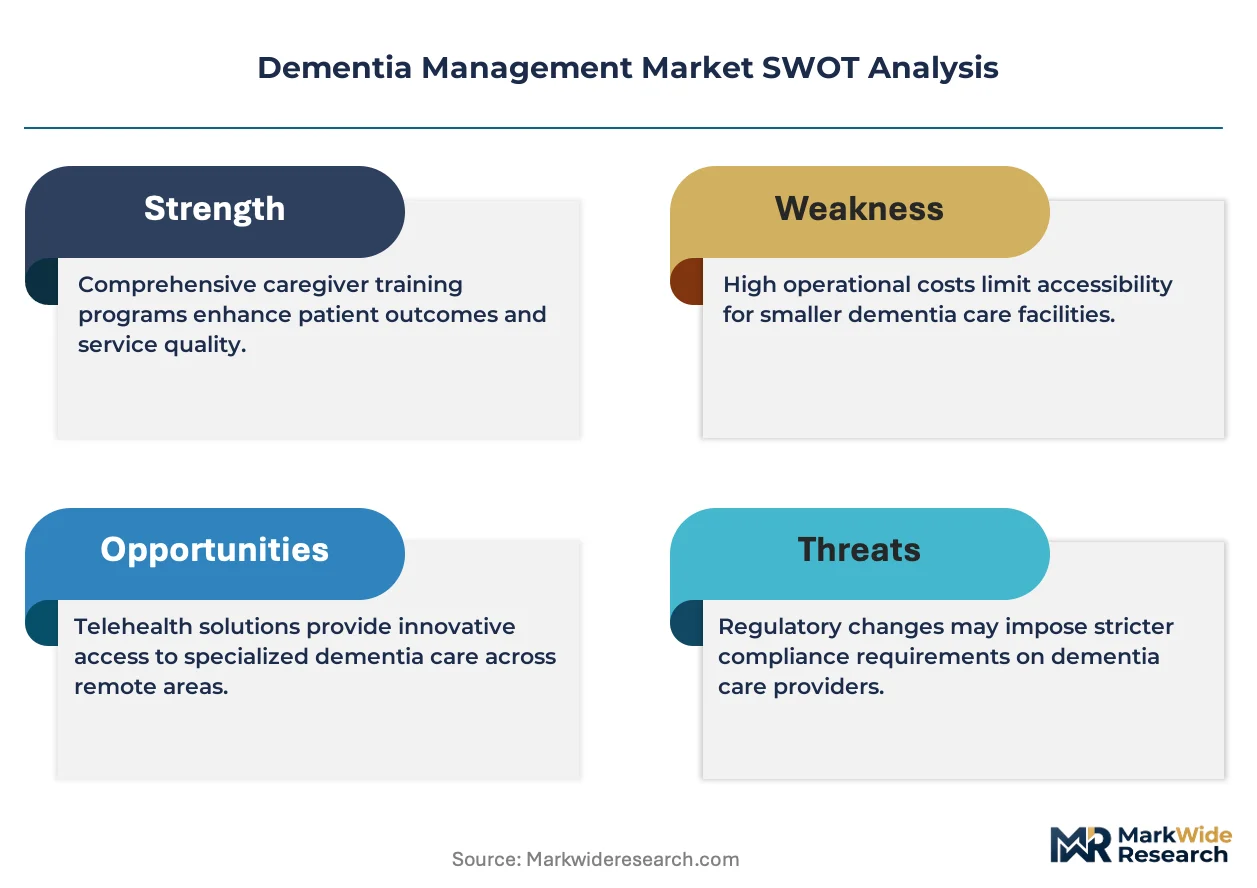
For Market Incumbents: Deploy manufacturing scale commitments as the primary defensive lever. Anchor infusion network partnerships at academic medical centers to lock site-of-care access against emerging digital therapeutic entrants. Pre-commit to post-market confirmatory trial infrastructure before FDA accelerated approval grants to compress competitor entry windows. For New Entrants and Emerging Players: The price-point gap between premium monoclonal antibody infusion bundles and economy caregiver support services opens white-space at the hybrid care coordination tier. Target home health agencies in United States metropolitan areas with established neurology referral networks as the most penetrable channel. Pursue Medicare remote therapeutic monitoring code qualification as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with digital therapeutic platforms possessing FDA draft guidance validation for cognitive assessment equivalence. Long-term viability hinges on reimbursement code density rather than clinical efficacy alone across the extended analysis window. Monitor CMS Innovation Center value-based dementia care contract announcements as the critical inflection signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Confirmatory Trial Infrastructure Pre-Commitment | Secures FDA accelerated approval pathway access before competitor manufacturing scale advantages harden. |
| Specialty Pharmacy Network Partnership | Locks patient access capacity at academic infusion centers in Boston, Baltimore, and San Francisco. |
| Digital Therapeutic FDA Validation Lab Investment | Establishes equivalence to paper-based neuropsychological batteries under draft guidance benchmarks. |
| Remote Monitoring Reimbursement Strategy | Captures Medicare remote therapeutic monitoring codes for sensor-based cognitive assessment deployment. |
| Biomarker-Defined Enrollment Protocol Development | Reduces sample size requirements through PET imaging and CSF testing population refinement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare coverage determinations. Bottom-up patient-flow modeling and top-down reimbursement spend analysis triangulated volume and value estimates.
Comparable historical reference periods anchored the forecast window to pre-accelerated approval and post-accelerated approval regulatory epochs. Segmentation dimensions spanned therapeutic modality, care setting, disease phenotype, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to biomarker adoption rates and infusion network capacity expansion. Forecast inputs incorporated Medicare coverage determination timelines and digital health technology validation benchmarks.
Caveats apply where FDA confirmatory trial outcome revisions or CMS reimbursement code denials could materially shift the outlook. Forecasts reflect documented assumptions about biomarker test penetration and specialty pharmacy workforce availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
South America Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Hypertrophic Cardiomyopathy (HCM) Therapeutics Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Global Gastrointestinal Stromal Tumors Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Severe Hypertriglyceridemia (SHTG) Treatment Market
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Cerebral Folate Deficiency Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Intraductal Papilloma Market