
 Global Hepatitis C Testing Market | 2026-2036
Global Hepatitis C Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hepatitis C Testing Market Foresight
Hospital procurement networks across Southeast Asia and Latin America are reconfiguring hepatitis C testing contracts to favor vendors with integrated platform solutions. Abbott Laboratories leverages its automated immunoassay architecture to anchor large reference laboratory accounts in Mexico and Thailand. Siemens Healthineers competes through decentralized chemiluminescence instruments positioned at mid-volume regional hospitals.
Hepatitis C testing encompasses serological, molecular, and immunological assays designed to detect viral antibodies, RNA, or core antigens in human serum or plasma, with PCR-based RNA quantification serving as the confirmatory standard for active infection. The primary purpose spans blood safety screening, clinical diagnosis, and treatment response monitoring across healthcare systems. RNA tests and genotyping assays command premium positioning due to their essential role in directing direct-acting antiviral therapy selection, while rapid diagnostic tests extend access into point-of-care settings with lower infrastructure requirements. Diagnostic laboratories absorb the majority of volume through centralized high-throughput processing, though blood banks sustain stable demand tied to mandatory donor screening protocols.
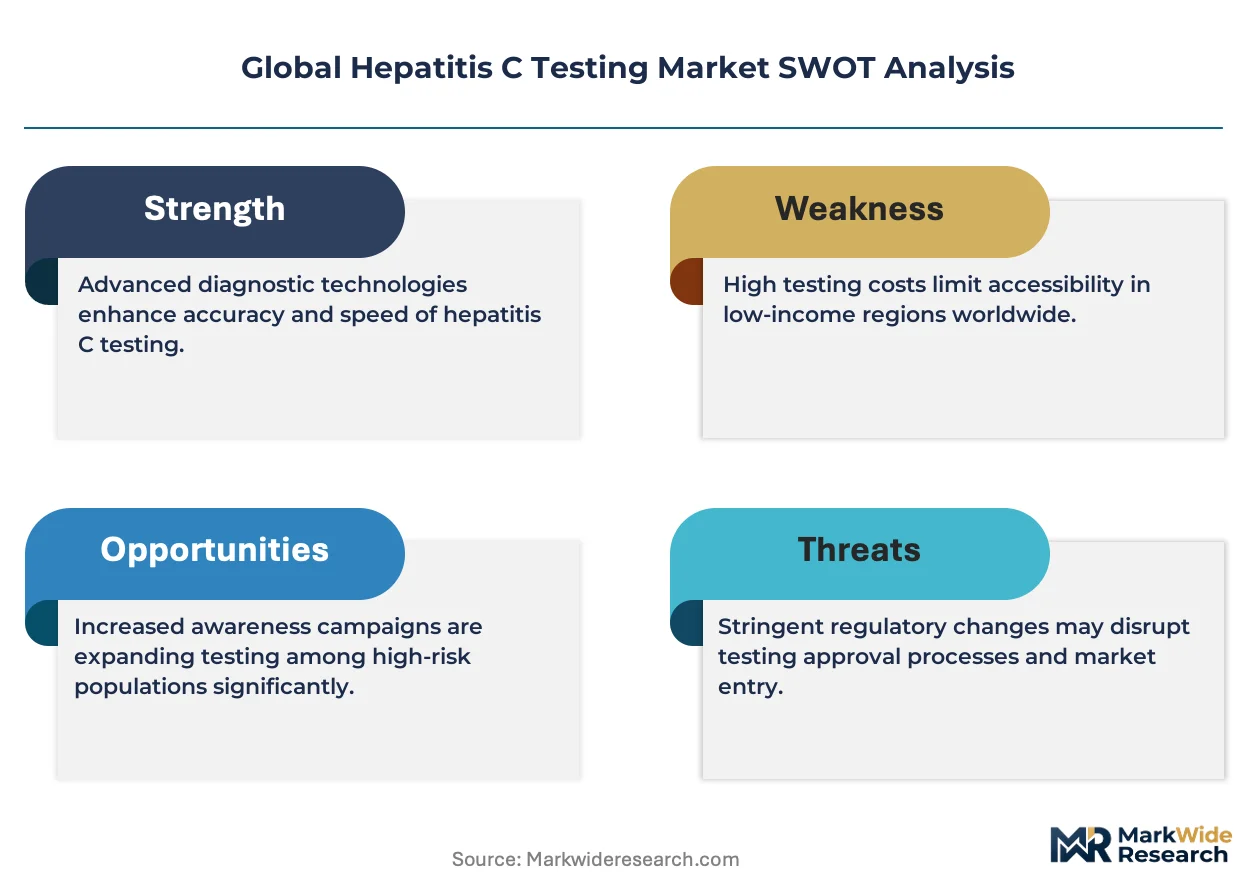
FDA oversight shapes assay validation requirements and premarket pathways for nucleic acid tests in the United States, while EMA and WHO prequalification frameworks govern access for manufacturers targeting European and low-income country procurement pools. India's CDSCO and BIS standards create additional compliance layers for imported diagnostic kits entering its national viral hepatitis program. Stakeholders must monitor evolving WHO treatment guidelines and country-level elimination commitments to align product portfolios with shifting testing algorithms and reimbursement structures.
Market Dynamics
Nucleic acid amplification technologies are compressing the diagnostic window for hepatitis C detection, forcing laboratories to retire serological platforms and reconfigure capital allocation toward integrated molecular systems.
Growth Catalysts
- WHO Elimination Frameworks:National viral hepatitis programs in India and Brazil are mandating expanded screening access, creating sustained procurement pipelines for high-throughput testing platforms.
- Blood Bank Modernization:Emerging economy blood safety protocols are upgrading from rapid tests to nucleic acid screening, driving replacement demand across Southeast Asian and Latin American transfusion services.
- Direct-Acting Antiviral Therapy Expansion:Genotype-guided treatment selection requires RNA quantification and subtyping assays, cementing molecular diagnostics as the clinical standard before therapy initiation.
Market Restraints
- Reagent Supply Concentration:Polymerase and fluorescent probe manufacturing clusters in specific East Asian jurisdictions create vulnerability to export licensing disruptions.
- Capital Intensity of Platform Migration:Mid-volume regional hospitals face stranded asset risk from immunoassay instruments with remaining depreciation schedules.
- Substitution by Simplified Treatment Algorithms:Pan-genotypic direct-acting antiviral regimens in some health systems reduce the clinical utility of genotyping assays, compressing the addressable market for subtyping products.
Strategic Opportunities
- Point-of-Care Decentralization:Fingerstick capillary blood collection and cartridge-based RNA detection enable testing outside centralized laboratories, opening access in rural India and sub-Saharan African clinics.
- Integration with HIV and Hepatitis B Panels:Multiplex platform development allows simultaneous detection across viral hepatitis targets, aligning with integrated screening programs in Thailand and Vietnam.
- EMA and WHO Prequalification Pathways:Streamlined regulatory convergence for manufacturers targeting European and low-income country procurement pools reduces duplicate validation costs.
Industry Challenges
- Molecular Diagnostics Specialist Shortage:Clinical laboratory scientist training programs in Brazil and Mexico are not producing sufficient personnel to operate complex nucleic acid platforms at scale.
- Legacy System Interoperability:Regional hospital laboratory information systems in Southeast Asia lack HL7 connectivity standards, complicating automated result reporting for new instrument installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hepatitis C Testing Market |
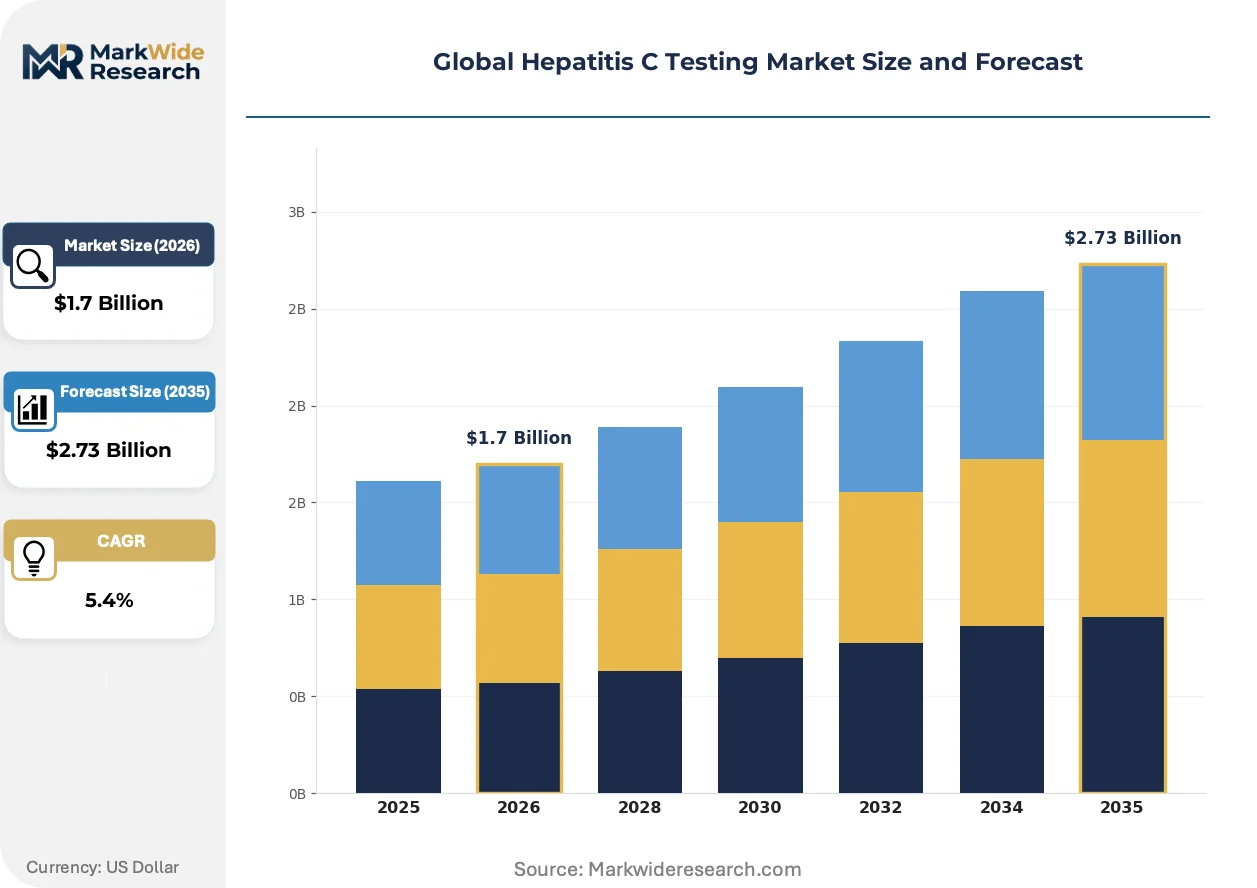
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibody Tests, RNA Tests, Antigen Tests, Genotyping Assays Application: Blood Screening, Clinical Diagnostics, Therapeutic Monitoring, Research Studies End User: Diagnostic Laboratories, Blood Banks, Research Institutes, Pharmaceutical Companies Technology: ELISA, PCR, Chemiluminescence Immunoassay, Rapid Diagnostic Tests |
| Companies Covered | Abbott Laboratories, Bio-Rad Laboratories, Siemens Healthineers, OraSure Technologies, F. Hoffmann-La Roche, QIAGEN, Bayer AG, Ortho Clinical Diagnostics, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hepatitis C Testing Market Shifts & Advancements
Automation and assay miniaturization are converging to redefine where hepatitis C testing occurs, collapsing the traditional boundary between centralized reference laboratories and distributed care settings.
Real-time PCR and transcription-mediated amplification systems are rendering obsolete batch-processed serological workflows in high-throughput blood bank environments. National transfusion services in Thailand and Argentina are consolidating procurement around closed-system molecular platforms that eliminate open-tube handling. This technology compression is reducing turnaround times from days to hours while simultaneously lowering skilled labor requirements.
India's CDSCO has tightened import registration requirements for hepatitis C diagnostic kits, mandating local stability studies and post-market surveillance commitments that extend approval timelines. Domestic manufacturers with established BIS certification infrastructure are capturing share in the national viral hepatitis program procurement cycles. Multinational suppliers are responding by establishing in-country technical service centers and regional distribution partnerships.
Bundled reagent rental contracts are displacing capital purchase models for mid-volume hospital laboratories. Instrument placement agreements with minimum volume commitments now dominate procurement negotiations in Mexico and Colombia. This financing shift transfers utilization risk to manufacturers while locking hospitals into single-vendor consumable ecosystems, consolidating supplier relationships over multi-year contract periods.
Global Hepatitis C Testing Market Segmentation
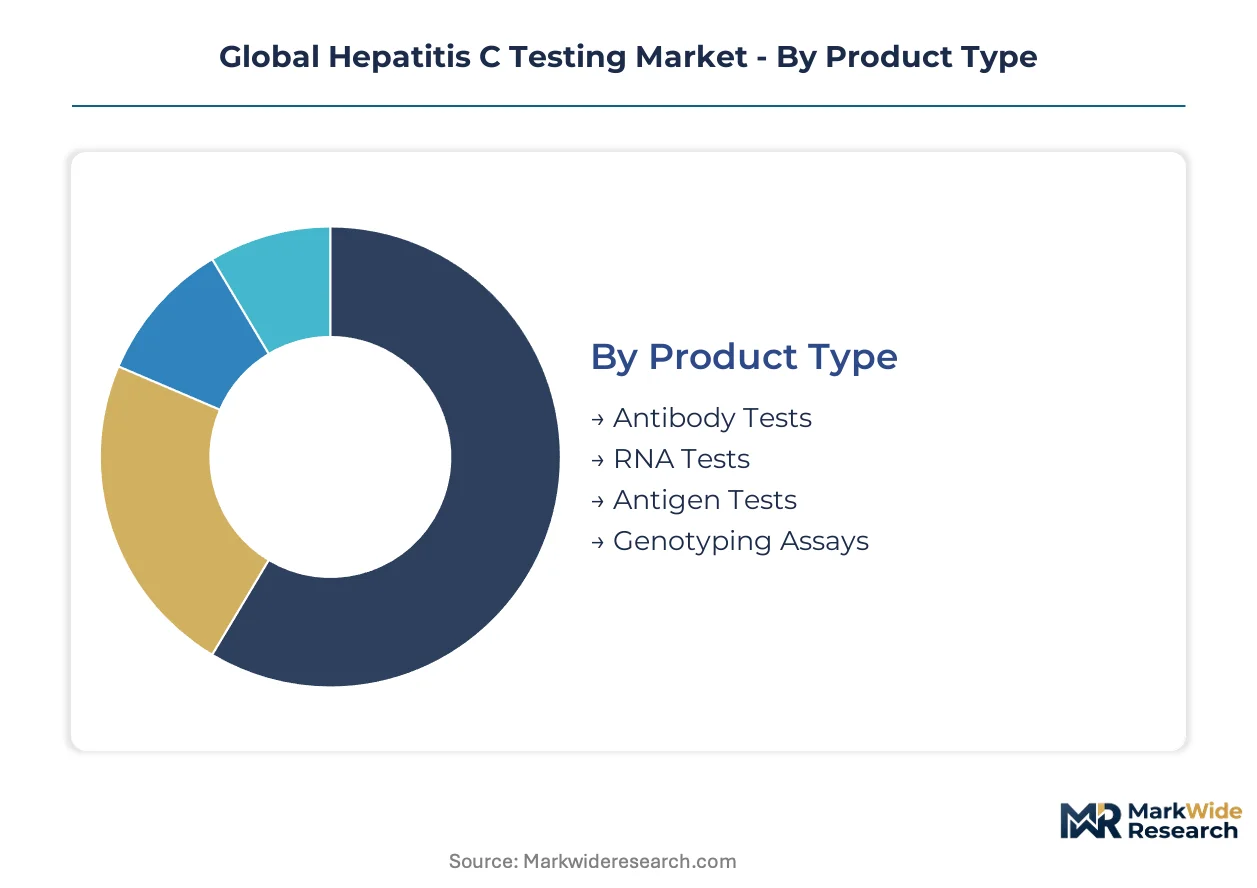
Hepatitis C testing segments diverge sharply across technology maturity and care setting. Product architecture, end-user infrastructure, and regulatory pathway requirements create distinct commercial territories with divergent margin profiles and capital intensity.
Product Type:
Mature serological platforms coexist with emerging molecular assays in a bifurcated product landscape where diagnostic accuracy requirements dictate selection hierarchy.
- RNA Tests:Nucleic acid amplification platforms detect viral load through real-time PCR or transcription-mediated amplification with limits of detection below 15 IU/mL. Blood banks in Thailand and Argentina are consolidating procurement around closed-system molecular platforms that eliminate open-tube handling, driven by WHO prequalification requirements for nucleic acid screening.
- Antibody Tests:Enzyme immunoassay and chemiluminescence systems detect anti-HCV antibodies in serum or plasma, serving as the initial screening tier in most national algorithms. Mid-volume regional hospitals in Mexico and Colombia favor these platforms for their lower capital thresholds and established reimbursement codes, though they face displacement pressure from RNA confirmation protocols.
- Antigen Tests:Core antigen detection offers intermediate sensitivity between serology and RNA methods, with particular utility in resource-limited settings lacking molecular infrastructure.
- Genotyping Assays:Sequence analysis and hybridization techniques determine HCV subtypes to guide direct-acting antiviral selection, though pan-genotypic regimens are compressing clinical demand in some health systems.
RNA Tests retain volume leadership in high-throughput settings; Antigen Tests hold the steepest expansion curve among point-of-care deployments.
Application:
Application segments stratify across institutional buyer types with divergent procurement cycles and performance specifications.
- Clinical Diagnostics:Patient-facing detection workflows span symptomatic presentation screening, confirmatory testing, and pre-treatment staging across hospital outpatient departments and community health centers. India's national viral hepatitis program is mandating expanded screening access through its public health infrastructure, creating sustained procurement pipelines for integrated platform solutions.
- Blood Screening:Donor testing protocols require high-sensitivity detection with documented traceability for transfusion safety compliance. National transfusion services are upgrading from rapid tests to nucleic acid screening, driving replacement demand across Southeast Asian and Latin American blood services.
- Therapeutic Monitoring:Sustained virologic response assessment and relapse detection support treatment course management.
- Research Studies:Epidemiological surveillance and clinical trial endpoints generate specialized demand for standardized assay panels.
Blood Screening commands the highest per-test pricing tier; Clinical Diagnostics generates the broadest geographic penetration.
End User:
End-user concentration reflects infrastructure gradients between centralized laboratory networks and distributed care settings.
- Diagnostic Laboratories:Reference laboratories and hospital-based facilities process the majority of testing volume through automated high-throughput systems. Abbott Laboratories anchors large reference laboratory accounts in Mexico and Thailand through integrated immunoassay architectures with multi-year consumable contracts.
- Blood Banks:National transfusion services and hospital-based donor centers sustain stable demand tied to mandatory screening protocols with stringent turnaround requirements. Emerging economy blood safety protocols are upgrading technical specifications, creating equipment replacement cycles.
- Research Institutes:Academic medical centers and public health laboratories support surveillance and method validation studies.
- Pharmaceutical Companies:Clinical trial operations and companion diagnostic development generate specialized procurement with custom assay requirements.
Diagnostic Laboratories absorb the majority of commercial volume; Blood Banks maintain the most predictable procurement cadence.
Technology:
Technology platforms span a cost-capability spectrum from manual rapid tests to fully automated molecular systems.
- PCR:Polymerase chain reaction and real-time amplification systems provide quantitative viral load measurement with gold-standard sensitivity for active infection confirmation. Siemens Healthineers competes through decentralized chemiluminescence instruments positioned at mid-volume regional hospitals, though PCR is displacing these platforms in confirmatory workflows.
- Chemiluminescence Immunoassay:Automated light-emission detection systems deliver high-throughput antibody screening with reduced manual handling.
- ELISA:Enzyme-linked immunosorbent assays remain prevalent in resource-constrained settings for initial antibody detection.
- Rapid Diagnostic Tests:Lateral flow and immunochromatographic devices enable fingerstick capillary blood collection outside centralized laboratories, opening access in rural India and sub-Saharan African clinics with minimal infrastructure requirements.
PCR commands premium positioning for confirmatory testing; Rapid Diagnostic Tests are expanding most quickly in decentralized care models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India and Brazil extract pricing premiums from donor screening mandates that Mexico and Argentina cannot match, creating a two-tier procurement landscape across emerging economy blood services.
United States
FDA premarket pathways for nucleic acid tests sustain validation costs that favor established platform vendors. Hospital procurement networks favor integrated immunoassay architectures with multi-year consumable contracts. Reference laboratory clusters in Texas and California anchor high-throughput molecular testing volumes.
India
CDSCO import registration requirements with local stability studies extend approval timelines for foreign kit manufacturers. The national viral hepatitis program mandates expanded screening access through public health infrastructure. Domestic manufacturers with BIS certification capture share in government procurement cycles centered on Maharashtra and Gujarat.
Brazil
ANVISA oversight shapes assay validation requirements for molecular diagnostics entering the national health system. Blood bank modernization drives replacement demand from serological to nucleic acid screening platforms. São Paulo and Minas Gerais concentrate transfusion service upgrades and clinical laboratory expansion.
Thailand
WHO prequalification requirements for blood safety screening consolidate procurement around closed-system molecular platforms. National transfusion services eliminate open-tube handling to reduce turnaround times. Bangkok anchors regional reference laboratory capacity serving Mekong sub-region elimination programs.
Germany
EMA frameworks govern access for manufacturers targeting European procurement pools with streamlined regulatory convergence. Chemiluminescence instruments at mid-volume regional hospitals face displacement pressure from RNA confirmation protocols. Bavaria and Baden-Württemberg concentrate diagnostics manufacturing and reference laboratory networks.
Global Hepatitis C Testing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The vendor base compresses around three to five full-line suppliers with automated architectures, while regional distributors fragment the point-of-care segment. Strategic archetypes span integrated immunoassay platform builders, molecular diagnostics specialists, and rapid test commodity suppliers. Competitive moves concentrate on bundled reagent rental contracts and in-country technical service center establishment.
Among North American platform builders, Abbott Laboratories and OraSure Technologies exemplify divergent positioning—Abbott anchoring large reference laboratory accounts through automated system architectures, OraSure occupying the decentralized testing tier with fingerstick collection formats. Siemens Healthineers represents the European integrated diagnostics archetype competing through mid-volume hospital instrument placement. These three entities illustrate how geographic origin and company structure map to distinct competitive territories without overlapping core value propositions.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| OraSure Technologies |
| F. Hoffmann-La Roche |
| QIAGEN |
| Bayer AG |
| Ortho Clinical Diagnostics |
| Thermo Fisher Scientific |
| Others |
Supply & Pricing Matrix
Overcapacity in East Asian polymerase manufacturing clusters compresses reagent margins while simultaneously enabling aggressive instrument placement pricing for nucleic acid platforms in India and Brazil. This utilization imbalance transfers bargaining power downstream to blood bank procurement networks and consolidated hospital systems.
Pricing Analysis
Configured-to-order pricing for closed-system molecular platforms commands 40-60% premiums over standard chemiluminescence instrument packages. The dominant structure runs through bundled reagent rental contracts with minimum volume commitments that lock hospitals into single-vendor consumable ecosystems. Price differentiation hinges on WHO prequalification status and local regulatory certification tier, with CDSCO-registered kits in India extracting additional premiums. Pricing pressure stems from pan-genotypic antiviral regimens reducing genotyping assay utility. Public health programs in Brazil and Thailand show highest price sensitivity; reference laboratories in Germany and the United States demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk planning for fluorescent probe and polymerase reagent sourcing. Manufacturing concentrates in China, South Korea, and Singapore for nucleic acid amplification components. The ecosystem draws from specialized enzyme fermentation facilities, precision optics for real-time detection, and medical-grade plastics for cartridge production. Single-source vulnerability clusters around transcription-mediated amplification chemistry patents held by select suppliers. Distribution runs through regional technical service centers in Mexico City, São Paulo, and Bangkok that anchor multi-year consumable logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatitis C testing market is recovering from pandemic-induced screening backlogs as national elimination programs in India and Brazil restart procurement cycles. This cyclical rebound concentrates in blood bank modernization and point-of-care decentralization initiatives.
For Market Incumbents: Harden platform stickiness through backward integration into reagent manufacturing in India and Brazil, insulating against CDSCO import licensing disruptions. Deepen hospital system partnerships in Thailand and Mexico with multi-year technical service commitments that raise switching costs for challenger instruments. Consolidate reference laboratory accounts by embedding genotyping assays within automated immunoassay architectures before pan-genotypic regimens fully displace subtyping demand. For New Entrants and Emerging Players: Pursue point-of-care RNA detection white space in rural India and sub-Saharan African clinics where fingerstick capillary collection meets minimal infrastructure requirements. Target blood bank procurement in Argentina and Colombia where national transfusion services are upgrading from rapid tests to nucleic acid screening. Lead with cartridge-based molecular systems that eliminate cold-chain dependencies and reduce skilled labor requirements. For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturers with established BIS certification infrastructure and in-country stability study capabilities. Long-term viability rests on regulatory convergence between EMA and WHO prequalification pathways that reduces duplicate validation burdens. Watch for inflection signals in India's national viral hepatitis program procurement scale-up and Brazil's ANVISA molecular diagnostics registration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks procurement access for blood banks in Thailand and Argentina transitioning to nucleic acid screening. |
| Point-of-Care Platform Launch | Extends testing reach into rural Indian clinics and sub-Saharan African settings with minimal laboratory infrastructure. |
| Reagent Manufacturing Scale-Up | Reduces import dependency risks for polymerase and probe supplies concentrated in East Asian jurisdictions. |
| Hospital System Partnership | Secures multi-year consumable contracts with reference laboratories in Mexico and Colombia. |
| Multiplex Panel Development | Aligns with integrated hepatitis B and HIV screening programs in Thailand and Vietnam. |
Research Methodology
Cross-validation between hospital procurement database analysis and blood bank modernization program documentation anchors the qualitative findings. Primary interviews with clinical laboratory directors, biomedical engineers, GPO contracts managers, and national transfusion service procurement officers were combined with secondary validation through FDA 510(k) filings, EMA submission records, WHO prequalification lists, and CDSCO import registration databases. Bottom-up instrument placement tracking and top-down national program budget analysis were triangulated to reconcile volume estimates.
Calibration against historical platform replacement cycles and reagent consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology platform, application purpose, end-user infrastructure tier, and regional regulatory cluster. CAGRs were derived from trend extrapolation of nucleic acid amplification adoption curves and serological platform retirement rates. Forecast inputs incorporated national viral hepatitis program commitment timelines and blood bank technical specification upgrade schedules.
Sensitivities concentrate around WHO treatment guideline revisions, pan-genotypic antiviral regimen adoption velocity, and East Asian export licensing disruptions for critical reagent components. Forecasts reflect assumptions about procurement cycle continuity and instrument placement financing availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Cell Free DNA Testing Market