
 Solid Tumor Therapeutics Market | 2026-2036
Solid Tumor Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Tumor Therapeutics Market Outlook
The capital-intensity divergence between biologics manufacturers and small-molecule specialists is reorganizing competitive hierarchies in solid tumor development. Bristol-Myers Squibb leverages its integrated immuno-oncology infrastructure to sustain leadership in checkpoint inhibitor supply. AstraZeneca anchors its position through deep antibody-drug conjugate pipelines across multiple tumor types. Novartis differentiates via radioligand therapy manufacturing scale that competitors struggle to replicate.
Solid tumor therapeutics comprise pharmaceutical agents engineered to interrupt oncogenic signaling, disrupt tumor vasculature, or mobilize immune recognition against malignant epithelial and mesenchymal neoplasms. These modalities function through targeted binding of cell-surface receptors, intracellular kinase inhibition, or engineered T-cell priming to achieve cytoreduction and disease control. Immunotherapy segments command premium positioning as PD-1/PD-L1 and CAR-T platforms displace cytotoxic chemotherapy in frontline settings across lung and breast malignancies. Precision medicine segments attract concentrated R&D investment as biomarker-driven patient selection improves response rates and payer willingness-to-reimburse. Targeted therapy segments retain substantial volume share in colorectal and prostate cancer where receptor tyrosine kinase inhibition maintains established efficacy profiles.
FDA breakthrough therapy designation, EMA PRIME eligibility, and Japan PMDA sakigake designation collectively compress regulatory review timelines for novel solid tumor modalities. These frameworks reshape demand by rewarding sponsors who generate robust biomarker data and adaptive trial designs with earlier market access and favorable reimbursement positioning. Stakeholders must monitor evolving FDA Project Optimus dose-optimization requirements and EU HTA convergence timelines to anticipate how evidence standards will redistribute competitive advantage across therapy classes.
Market Dynamics
Precision-guided therapy development is compressing clinical timelines while fragmenting manufacturing capabilities across biologics, radiopharmaceuticals, and small-molecule platforms. FDA Project Optimus dose-optimization mandates and EMA HTA convergence are forcing sponsors to front-load biomarker evidence generation before pivotal trials.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy designation and EMA PRIME eligibility compress review timelines for novel modalities. Sponsors with robust biomarker data gain earlier market access.
- Biomarker-Driven Patient Selection:Companion diagnostic integration improves response rates and payer willingness-to-reimburse. Oncology clinics prioritize precision regimens over empirical chemotherapy.
- Immuno-Oncology Infrastructure Investment:United States, Germany, and Japan expand manufacturing capacity for PD-1/PD-L1 and CAR-T platforms. Reimbursement frameworks in these markets favor innovative therapeutics.
Market Restraints
- Manufacturing Scale Limitations:Radioligand therapy production requires specialized isotope handling facilities. Competitors struggle to replicate Novartis's manufacturing footprint.
- Clinical Trial Complexity:Adaptive trial designs demand larger upfront investment in biomarker infrastructure. Small sponsors face capital constraints for patient stratification.
- Reimbursement Heterogeneity:Payer evidence requirements vary across United States, Germany, and Japan. HTA bodies impose divergent cost-effectiveness thresholds.
Strategic Opportunities
- Antibody-Drug Conjugate Expansion:Deep pipelines across multiple tumor types attract concentrated R&D investment. AstraZeneca anchors position through platform diversification.
- Radioligand Therapy Scale:Manufacturing differentiation creates sustainable competitive moats. Isotope supply chain control determines market access velocity.
- Checkpoint Inhibitor Combination Regimens:Frontline displacement of cytotoxic chemotherapy in lung and breast malignancies opens volume expansion. Bristol-Myers Squibb leverages integrated infrastructure.
Industry Challenges
- Talent Scarcity in Radiochemistry:Specialized isotope handling expertise concentrates in limited geographic clusters. Training pipelines fail to match manufacturing expansion.
- Legacy System Integration:Biomarker data platforms require interoperability with existing electronic health records. Oncology clinics face workflow disruption during transition.
- IP Fragmentation Across Modalities:Antibody-drug conjugate patents span payload, linker, and targeting domains. Licensing complexity delays combination therapy development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Tumor Therapeutics Market |
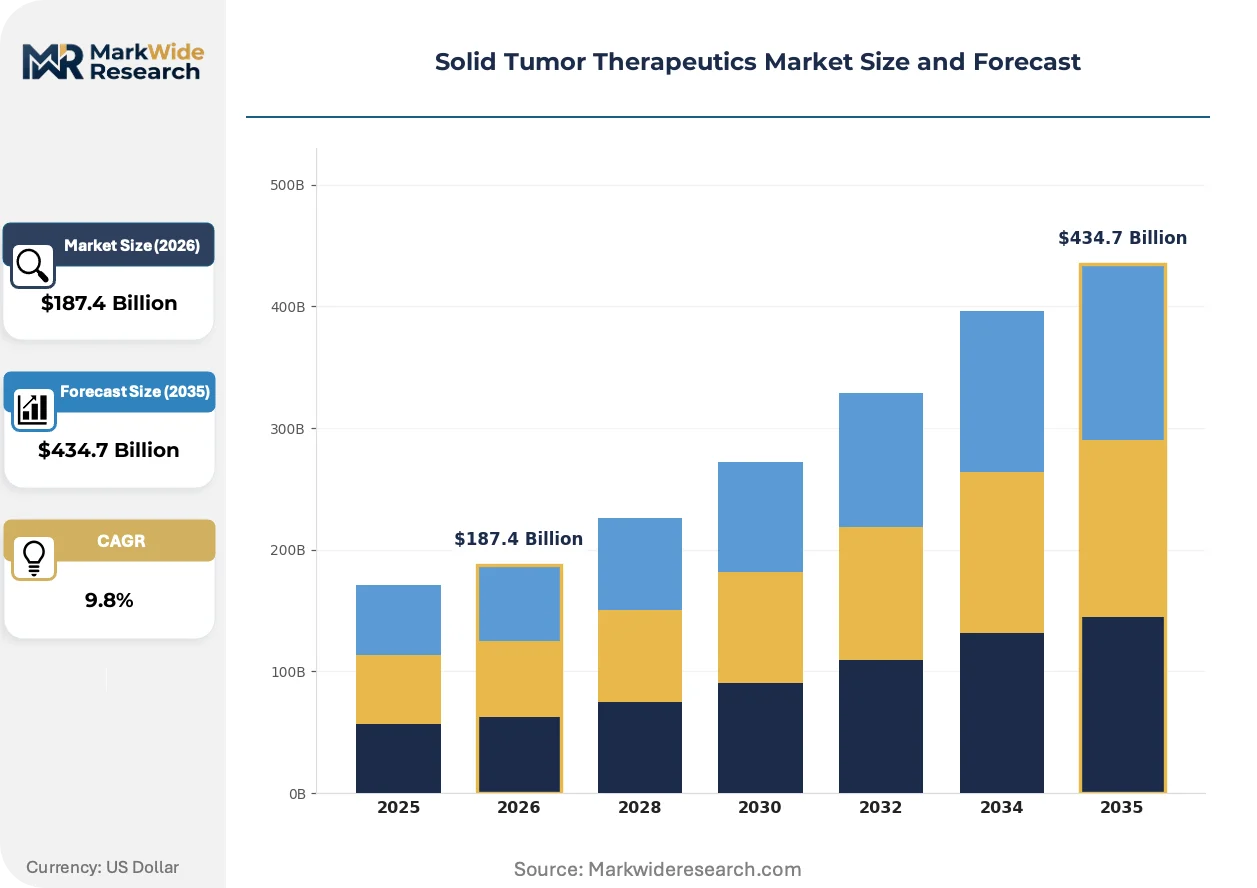
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $434.7 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Precision Medicine Therapy Area: Breast Cancer, Lung Cancer, Colorectal Cancer, Prostate Cancer End User: Hospitals, Oncology Clinics, Research Institutes, Homecare Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal |
| Companies Covered | AstraZeneca, Pfizer, Johnson & Johnson, Bristol-Myers Squibb, Eli Lilly and Company, Amgen, Novartis, F. Hoffmann-La Roche, Merck & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Tumor Therapeutics Market Strategic Shifts
Technology convergence between immuno-oncology and precision medicine is redefining therapeutic development paradigms. Regulatory frameworks are adapting to compress timelines for novel modalities while raising evidence standards.
Antibody-drug conjugates with site-specific conjugation chemistry are supplanting traditional lysine-based coupling methods. Oncology clinics in the United States and Germany prioritize these constructs for improved therapeutic index and reduced off-target toxicity. The shift is compressing development timelines for sponsors who master the manufacturing complexity.
EMA's accelerated assessment pathways and FDA Project Optimus dose-optimization requirements are reshaping clinical trial design. Sponsors must generate robust exposure-response data earlier in development. Small-molecule specialists face particular pressure to adapt biomarker strategies that biologics manufacturers have already integrated.
Hospital procurement departments are consolidating vendor relationships around integrated diagnostic-therapeutic platforms. Single-source contracts for companion diagnostic and drug supply are displacing fragmented purchasing across separate categories. This concentration is most visible in United States academic medical centers and German university hospitals.
Solid Tumor Therapeutics Market Segmentation
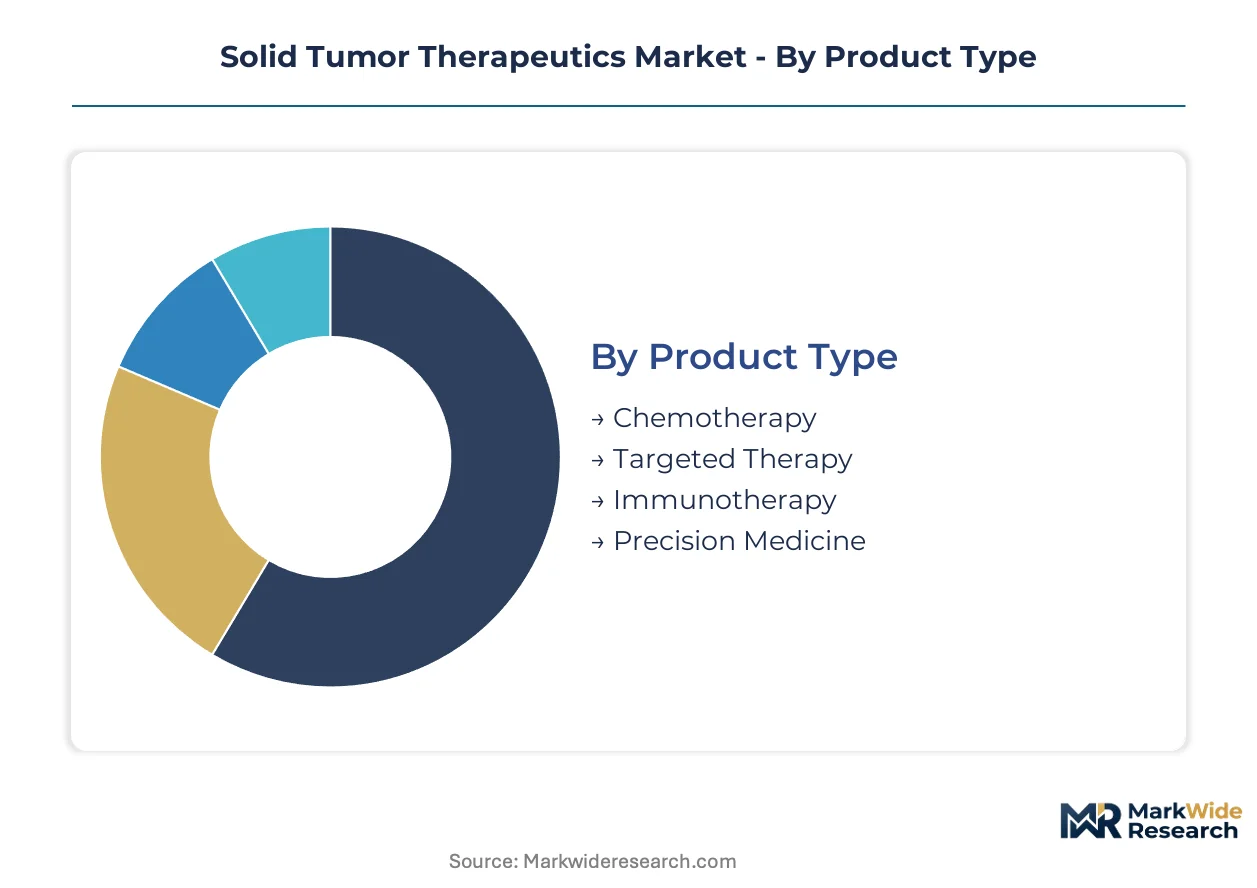
Solid tumor therapeutics fragment across four distinct dimensions that determine pricing power, distribution channels, and regulatory pathway selection. Each segmentation axis reveals divergent margin structures and competitive intensity profiles.
Product Type:
Immunotherapy concentrates manufacturing investment in the United States and Germany, while chemotherapy retains volume leadership in price-sensitive markets across Asia.
- Immunotherapy:Engineered biologics mobilize immune recognition through PD-1/PD-L1 checkpoint blockade and CAR-T priming. Demand clusters in academic medical centers across the United States and German university hospitals where reimbursement frameworks favor innovative modalities. Manufacturing scale limitations constrain supply expansion.
- Precision Medicine:Biomarker-driven regimens match targeted agents to specific oncogenic alterations. Oncology clinics in Japan and the United States prioritize these constructs for improved response rates and payer willingness-to-reimburse. Companion diagnostic integration compresses development timelines.
- Targeted Therapy:Small-molecule kinase inhibitors interrupt oncogenic signaling in receptor-driven malignancies. Volume concentrates in colorectal and prostate cancer indications.
- Chemotherapy:Cytotoxic agents disrupt DNA replication and cell division through non-selective mechanisms. Retains substantial volume in emerging markets with constrained reimbursement.
Immunotherapy commands the established base. The steepest expansion runs through Precision Medicine.
Therapy Area:
Application concentration determines clinical trial infrastructure requirements and regulatory evidence standards across tumor types.
- Lung Cancer:Non-small cell and small cell histologies drive frontline immunotherapy adoption. PD-1/PD-L1 displacement of cytotoxic chemotherapy concentrates in the United States and Japan. Biomarker stratification by EGFR, ALK, and KRAS status fragments treatment algorithms.
- Breast Cancer:HER2-directed antibody-drug conjugates and hormone receptor-targeted regimens define precision approaches. German and United States oncology clinics prioritize CDK4/6 inhibitor combinations in hormone receptor-positive disease.
- Colorectal Cancer:Anti-EGFR monoclonal antibodies and VEGF inhibitors maintain established efficacy in RAS wild-type populations. Reimbursement heterogeneity limits immunotherapy penetration.
- Prostate Cancer:Androgen receptor pathway inhibitors and radioligand therapies address castration-resistant disease. Novartis's manufacturing scale in radiopharmaceuticals creates competitive differentiation.
Lung Cancer anchors current revenue concentration. Breast Cancer is gaining share fastest among emerging modalities.
End User:
Customer type segmentation reveals divergent procurement patterns and service intensity requirements.
- Oncology Clinics:Outpatient infusion centers and specialized cancer treatment facilities. United States and Germany lead adoption of precision-guided regimens with integrated diagnostic platforms.
- Hospitals:Inpatient oncology units and academic medical centers. Complex case management and clinical trial access drive site selection.
- Research Institutes:Contract research organizations and academic research centers. Early-phase trial execution and biomarker discovery focus.
- Homecare:Oral oncology dispensing and patient support services. Expanding in markets with mature specialty pharmacy infrastructure.
Hospitals retain the volume base. Oncology Clinics show the steepest expansion trajectory.
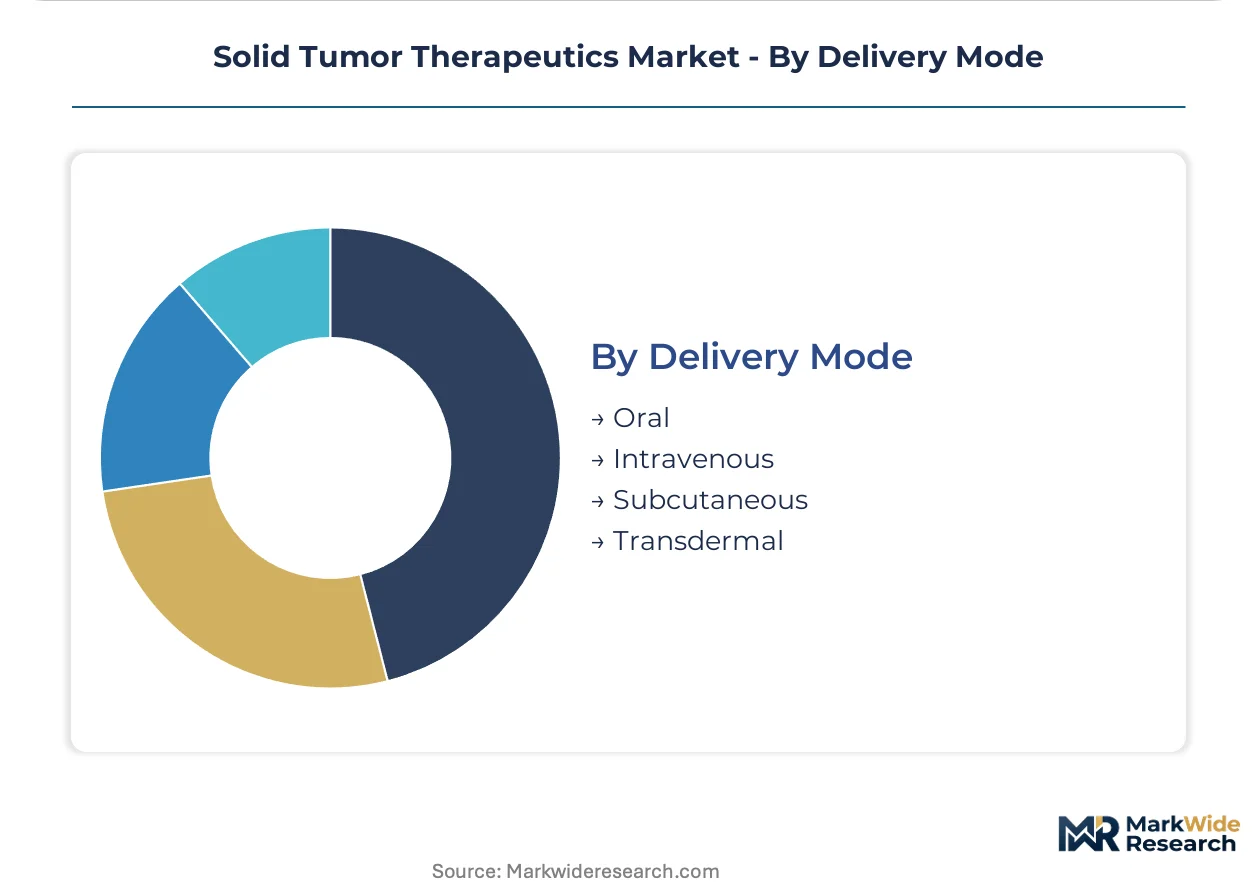
Delivery Mode:
Administration route determines manufacturing format, cold chain requirements, and patient compliance profiles.
- Intravenous:Infusion-based delivery for monoclonal antibodies, antibody-drug conjugates, and checkpoint inhibitors. Requires specialized oncology clinic infrastructure in the United States, Germany, and Japan.
- Oral:Small-molecule kinase inhibitors and hormone therapies enable outpatient management. Preferred in prostate and breast cancer for patient convenience.
- Subcutaneous:Reduced infusion time and clinic burden for selected immunotherapy agents. Manufacturing complexity limits portfolio breadth.
- Transdermal:Emerging delivery for supportive care agents and hormone modulation. Limited therapeutic application in solid tumors.
Intravenous dominates current therapeutic value. Oral formulations are expanding most quickly across patient preference-driven markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for solid tumor therapeutics varies sharply across geographies, with United States and German oncology clinics absorbing premium precision-medicine costs while emerging markets remain tethered to chemotherapy volume. This divergence is reshaping where manufacturers deploy immuno-oncology infrastructure versus generic small-molecule capacity.
United States
FDA breakthrough therapy designation and IRA drug pricing provisions create dual pressures on commercial strategy. The agency's Project Optimus dose-optimization mandates are compressing clinical timelines for sponsors with robust biomarker data. Manufacturing investment clusters in Greater Boston and the San Francisco Bay Area, where academic medical centers anchor early adoption of CAR-T and radioligand platforms.
Germany
EMA accelerated assessment pathways and HTA convergence timelines reward sponsors who front-load evidence generation. The country's national pharmaceutical regulator, BfArM, coordinates with G-BA on early benefit assessments that determine reimbursement velocity. Industrial concentration in Munich and Heidelberg supports antibody-drug conjugate manufacturing scale that supplies European university hospitals.
Japan
PMDA sakigake designation compresses regulatory review for novel oncology modalities, particularly in lung and gastric malignancies where biomarker stratification is advancing fastest. METI industrial policy supports domestic biologics manufacturing expansion. The Kanto region around Tokyo anchors precision-medicine adoption, with Yokohama emerging as a hub for companion diagnostic integration.
China
NMPA priority review pathways for innovative oncology drugs are shortening approval timelines, though reimbursement negotiation pressure constrains pricing power. The country's national pharmaceutical regulator emphasizes local clinical trial data for registration. Manufacturing gravity centers on Suzhou and Shanghai in the Yangtze River Delta, where domestic PD-1 developers are scaling production for regional export.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund access schemes create staged reimbursement pathways that favor therapies with mature overall survival data. The MHRA post-Brexit regulatory autonomy is diverging from EMA timelines on select modalities. The Golden Triangle between London, Cambridge, and Oxford concentrates early-phase trial execution and radiochemistry expertise for radioligand development.
Solid Tumor Therapeutics Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in solid tumor therapeutics, with scale advantages in manufacturing and regulatory navigation determining tier membership. The upper tier commands checkpoint inhibitor and antibody-drug conjugate markets through captive biologics infrastructure, while mid-cap specialists concentrate on radiopharmaceuticals or niche kinase inhibitors. Three archetypes dominate: diversified pharmaceutical conglomerates with immuno-oncology platforms, biologics-focused developers with deep ADC pipelines, and radiochemistry specialists with isotope supply chain control. Competitive dynamics center on strategic partnerships for combination regimens and manufacturing capacity expansion for novel modalities.
Among diversified pharmaceutical conglomerates, Bristol-Myers Squibb and AstraZeneca occupy positions that exemplify distinct strategic vectors—one anchored in checkpoint inhibitor infrastructure, the other in antibody-drug conjugate platform diversification. Novartis represents the radiochemistry specialist archetype, with manufacturing scale in radioligand therapies that competitors struggle to replicate. These three companies illustrate how therapeutic modality focus, rather than geographic origin, is reorganizing competitive hierarchies in precision oncology.
| Leading Market Players |
|---|
| AstraZeneca |
| Pfizer |
| Johnson & Johnson |
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| Amgen |
| Novartis |
| F. Hoffmann-La Roche |
| Merck & Co. |
| Others |
Value Chain & Pricing Dynamics
FDA Project Optimus dose-optimization requirements gate both manufacturing qualification and price differentiation in solid tumor therapeutics, compressing development timelines for sponsors with biomarker infrastructure while fragmenting competitive positioning across precision medicine tiers. Payer evidence demands in the United States, Germany, and Japan create divergent pricing corridors that manufacturers must navigate through specialized distribution partnerships.
Pricing Analysis
After-sales revenue from companion diagnostic bundling and patient support services drives lifetime value in precision oncology. Three-tier pricing structure across premium immuno-oncology biologics, standard targeted small-molecules, and economy chemotherapy generics segments the market by therapeutic modality and biomarker complexity. Price differentiation hinges on FDA breakthrough therapy designation status and integrated diagnostic-therapeutic platform certification. Pricing pressure stems from IRA drug pricing provisions in the United States, with Medicare negotiation authority compressing margins on mature oncology assets. Academic medical centers show lowest price sensitivity due to research funding insulation, while community oncology clinics in price-sensitive markets exhibit highest sensitivity to reimbursement velocity.
Supply Chain Analysis
Inbound logistics costs for cold-chain biologics and radioisotope half-life constraints compress distribution windows for time-sensitive oncology therapeutics. Manufacturing concentration clusters in the United States, Germany, and Switzerland for monoclonal antibody production, with Japan and South Korea expanding biologics capacity under industrial policy support. Raw material dependencies center on Chinese heparin and recombinant protein supplies, specialized German bioreactor engineering, and Canadian medical isotope reactor capacity. Single-source vulnerability in lutetium-177 and actinium-225 radiopharmaceutical supply chains creates critical bottlenecks for radioligand therapy expansion. Distribution runs through integrated specialty pharmacy networks and hospital procurement consortia that consolidate vendor relationships around single-source diagnostic-therapeutic contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radiochemistry expertise and isotope handling infrastructure represent acute capability gaps that constrain manufacturing expansion and reshape competitive hierarchies in precision oncology. Sponsors who secure specialized talent pools and captive isotope supply chains gain asymmetric advantage in radioligand therapy commercialization.
For Market Incumbents: Consolidate manufacturing scale in antibody-drug conjugate and radioligand platforms through backward integration into isotope supply chains and bioreactor capacity expansion in Greater Boston and Munich clusters. Defend against emerging biologics specialists by deepening companion diagnostic partnerships that lock in oncology clinic procurement relationships. Prioritize FDA Project Optimus compliance infrastructure to accelerate dose-optimization evidence generation and compress regulatory review timelines relative to competitors. For New Entrants and Emerging Players: Differentiate on radiochemistry specialization and site-specific conjugation chemistry manufacturing that incumbent small-molecule specialists struggle to replicate. Target white-space opportunities in prostate cancer radioligand therapy and lung cancer bispecific antibody combinations where manufacturing complexity creates sustainable moats. Pursue go-to-market strategies anchored to Japanese PMDA sakigake designation and German G-BA early benefit assessment pathways that reward novel modality sponsors with accelerated reimbursement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across radiopharmaceutical manufacturing sub-segments, favoring sponsors with established isotope supply chain control and specialized handling infrastructure. Long-term viability in solid tumor therapeutics hinges on platform diversification across precision medicine modalities rather than single-asset dependency. Acquisition targets should display integrated diagnostic-therapeutic development capabilities and biomarker-driven patient selection infrastructure. Monitor FDA Project Optimus enforcement patterns and EMA HTA convergence timelines as inflection indicators for evidence standard redistribution across therapy classes.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive isotope supply chains in radioligand therapy compress competitor market access velocity. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation accelerates commercial launch timelines for novel oncology modalities. |
| Pipeline Diversification | Antibody-drug conjugate platform expansion across multiple tumor types reduces single-indication risk. |
| Strategic Partnership | Companion diagnostic integration locks in oncology clinic procurement and biomarker-driven patient selection. |
| Clinical Trial Advancement | Adaptive trial designs with robust exposure-response data satisfy FDA Project Optimus dose-optimization mandates. |
Study Parameters
Cross-validation between primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchors the qualitative findings in operational reality. Secondary validation draws from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases to triangulate market sizing assumptions. Bottom-up patient-flow modeling and top-down pharmaceutical revenue aggregation converge through iterative reconciliation across the analysis window.
Sensitivity analysis frameworks test forecast robustness against biomarker adoption velocity, regulatory pathway duration, and reimbursement negotiation outcomes across the projection horizon. Segmentation dimensions encompass therapy modality, tumor type, treatment line, administration route, and regional regulatory cluster. CAGRs derive from fitted growth curves calibrated to historical approval velocity and analog product launch trajectories. Forecast inputs incorporate clinical trial success rates, manufacturing capacity expansion announcements, and payer access specialist survey data on willingness-to-reimburse thresholds.
Material uncertainties — regulatory pathway delays, manufacturing scale-up bottlenecks, and reimbursement negotiation outcomes — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding biomarker infrastructure penetration and precision medicine adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Progressive Supranuclear Palsy (PSP) Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Global Hammertoe Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Bullous Pemphigoid Treatment Market
Specialty Medicine
Primary Biliary Cholangitis (PBC) Treatment Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Global Neurotrophic Keratitis Treatment Market
Specialty Medicine
Chimeric Antigen Receptor (CAR) T-Cell Therapy Market
Specialty Medicine
Transient Ischemic Attack Market
Specialty Medicine
Hypoactive Sexual Desire Disorder Treatment Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market