
 Liver Fibrosis Treatment Market | 2026-2036
Liver Fibrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Liver Fibrosis Treatment Market Outlook
FDA Breakthrough Therapy designation is bifurcating the competitive landscape into validated innovators and aspirant entrants. Gilead Sciences, Inc. anchors its position through sustained R&D intensity in antiviral platforms. Vertex Pharmaceuticals Incorporated differentiates via specialized expertise in cystic fibrosis mechanisms translated to hepatic applications. Pfizer Inc. competes through manufacturing scale that supports global distribution of combination regimens.
Liver fibrosis treatment encompasses pharmacological interventions targeting collagen deposition, inflammation modulation, and hepatocyte regeneration, with functional parameters measured by non-invasive elastography scores and histological staging systems. The primary commercial purpose is halting or reversing fibrotic progression before cirrhosis develops. Antiviral therapies and combination therapies represent the dominant product categories, with fibrosis inhibitors emerging as the fastest-growing segment due to novel targets in TGF-beta and LOXL2 pathways. Oral administration leads delivery modes for chronic management, while intravenous routes concentrate in acute hospital settings.
FDA, EMA, and Japan's PMDA govern trial design, endpoint validation, and post-market surveillance across the three largest country markets, with harmonized ICH guidelines streamlining multi-regional development. The EU AI Act and FDA's evolving digital health frameworks are beginning to shape how AI-enabled diagnostics integrate with therapeutic decision-making. Stakeholders must monitor how conditional approval pathways and real-world evidence requirements shift the balance between speed-to-market and confirmatory trial investment.
Market Dynamics
FDA accelerated approval pathways are compressing development timelines for breakthrough liver fibrosis therapies, forcing incumbents to match R&D velocity while hospital procurement consolidates around elastography-validated protocols.
Growth Catalysts
- EMA Conditional Marketing Authorization:European regulators are streamlining pathways for novel TGF-beta inhibitors, reducing time-to-market for fibrosis reversal candidates.
- Hospital-based hepatology centers:Specialized treatment hubs in Germany and the United States are driving protocol standardization and combination therapy adoption.
- Non-invasive elastography:FibroScan and shear wave technologies are expanding patient screening capacity beyond traditional biopsy constraints.
Market Restraints
- Biomaterial input concentration:Recombinant protein production relies on concentrated Chinese contract manufacturing capacity, creating supply vulnerability.
- Histological endpoint requirements:FDA and EMA still mandate liver biopsy confirmation for full approval, limiting label expansion.
- Gene therapy substitution threat:CRISPR-based hepatocyte editing programs in early clinical stages threaten small-molecule fibrosis inhibitor pipelines.
Strategic Opportunities
- Underpenetrated Japanese market:PMDA's Sakigake designation offers priority review for fibrosis therapies addressing NASH-related progression.
- AI-enabled diagnostic convergence:Machine learning integration with elastography scoring is creating companion diagnostic partnerships.
- Real-world evidence frameworks:FDA's Project Orbis and EMA's DARWIN EU are enabling post-approval label expansion through observational data.
Industry Challenges
- Translational medicine talent scarcity:Hepatology clinical trial design requires specialized expertise in fibrosis staging correlation that outstrips available personnel.
- Legacy IT integration friction:Hospital electronic health record systems require costly adaptation to incorporate AI-derived fibrosis risk scores into workflow.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liver Fibrosis Treatment Market |
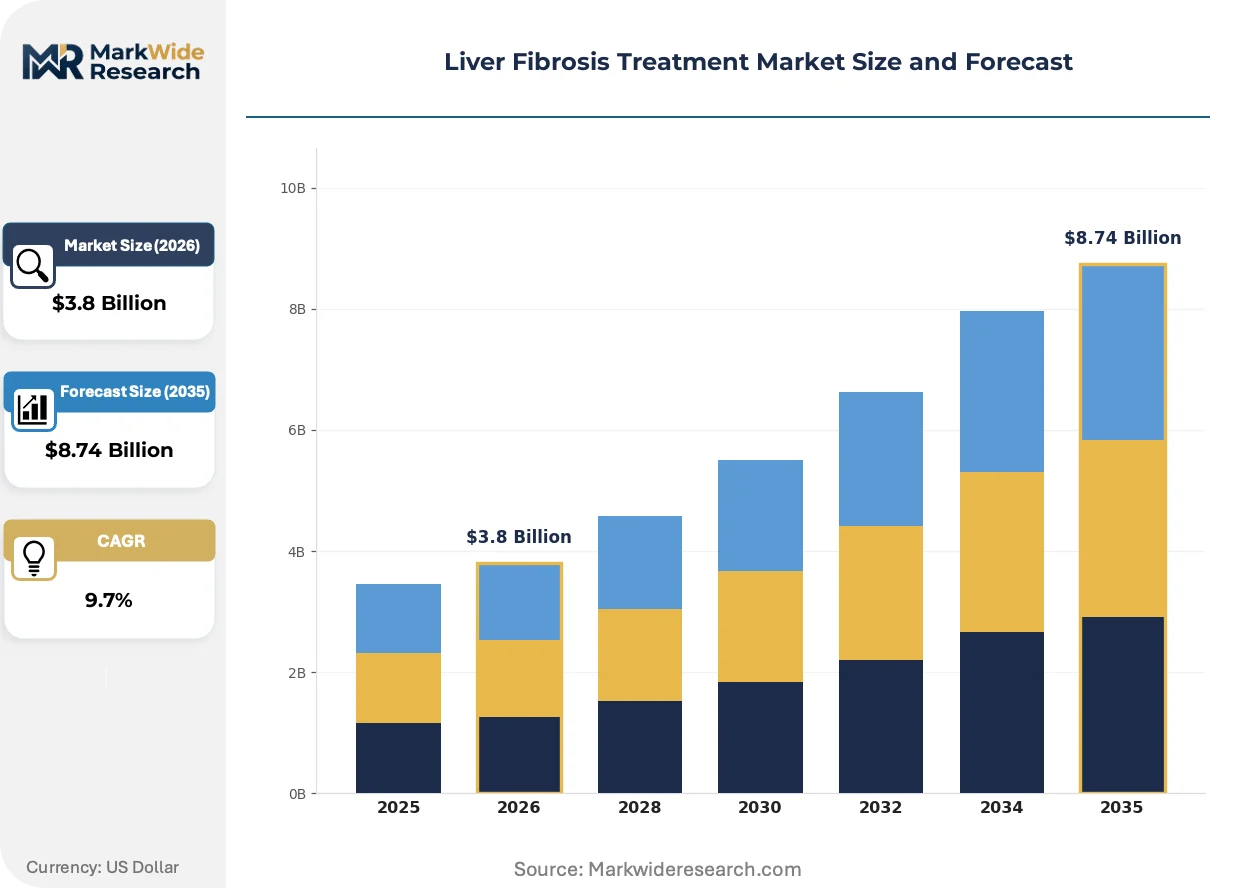
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiviral Therapies, Immune Modulators, Fibrosis Inhibitors, Combination Therapies Delivery Mode: Oral Administration, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Home Care, Specialty Centers Application: Chronic Hepatitis, Non-Alcoholic Steatohepatitis, Alcoholic Liver Disease, Others |
| Companies Covered | Johnson & Johnson, Vertex Pharmaceuticals Incorporated, Gilead Sciences, Inc., FibroGen, Inc., Pfizer Inc., Merck & Co., Inc., Novartis AG, Pharmaxis Limited, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liver Fibrosis Treatment Market Strategic Shifts
Biomarker-driven patient stratification is supplanting empirical prescribing in hepatology, with pharmaceutical developers and diagnostic firms converging on integrated therapy-test offerings.
LOXL2-targeted monoclonal antibodies are supplanting broad-spectrum anti-inflammatory approaches in late-stage NASH trials. Hepatology centers in the United States are prioritizing these candidates for their mechanistic specificity in collagen cross-link inhibition. The shift is compressing development investment in non-selective cytokine modulators.
EU AI Act risk classification requirements are reshaping how diagnostic algorithms gain CE marking for fibrosis staging. Developers must now document training data provenance and performance across demographic subgroups. German and French notified bodies are enforcing these standards most stringently, delaying market entry for non-compliant software.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts rather than point-solution purchasing. Gastroenterology departments in Japan and the United States are leading this consolidation, bundling elastography hardware, software analytics, and therapeutic protocols under single-source agreements. The model reduces administrative burden but raises switching costs for emerging competitors.
Liver Fibrosis Treatment Market Segmentation
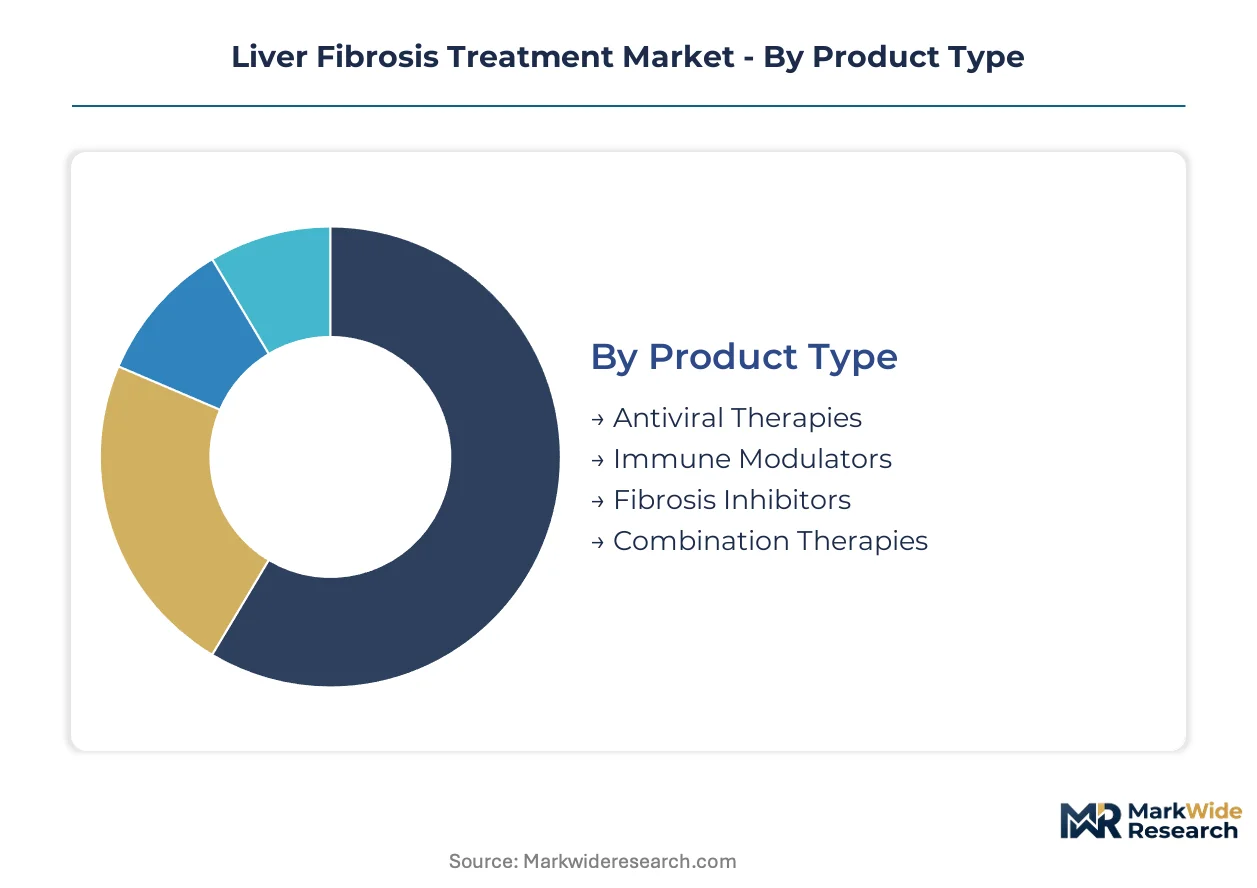
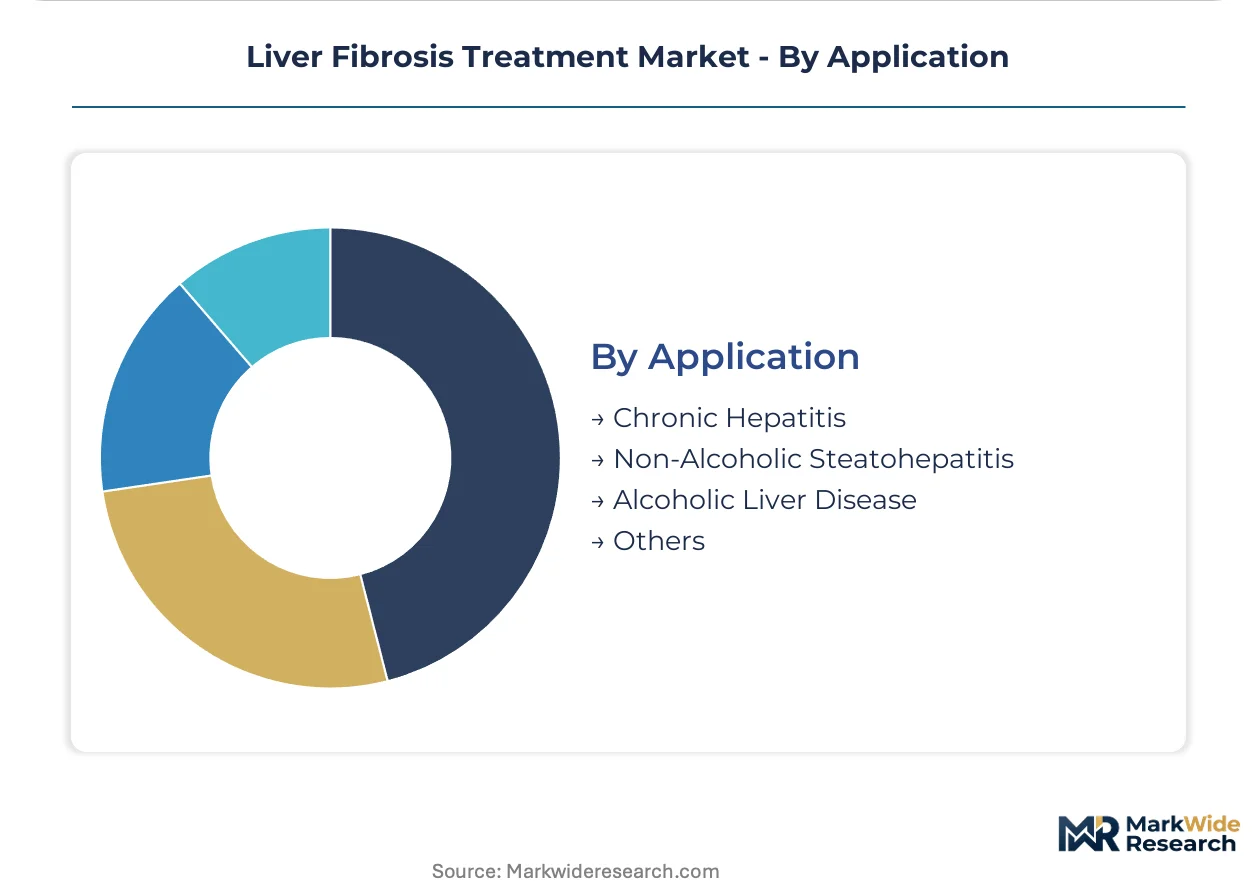
Segmentation in liver fibrosis treatment reveals how regulatory pathways, staging technologies, and care settings reshape commercial strategy. Pharmaceutical developers and diagnostic firms align product portfolios with distinct patient pathways and reimbursement structures across hepatology centers.
Product Type:
FDA breakthrough designation and EMA conditional authorization create divergent commercial timelines across therapeutic classes, with accelerated pathways favoring mechanisms demonstrating histological fibrosis reversal.
- Antiviral Therapies:Direct-acting agents targeting hepatitis B and C viral replication remain the backbone of etiological treatment. Hospital-based hepatology centers in the United States and Germany prioritize these agents for their established reimbursement codes and elastography-measurable outcomes.
- Combination Therapies:Regimens pairing antivirals with fibrosis modulators command premium positioning in specialty centers. Japanese hepatology protocols under PMDA guidance increasingly adopt these combinations for NASH-related progression, driven by Sakigake-designated products entering the market.
- Immune Modulators:Broad-spectrum cytokine inhibitors face compressed investment as LOXL2-targeted alternatives advance.
- Fibrosis Inhibitors:TGF-beta and LOXL2 pathway antagonists represent the steepest expansion trajectory, with novel targets displacing empirical anti-inflammatory approaches in late-stage trials.
Established volume favors antiviral therapies; emerging adoption favors fibrosis inhibitors.
Delivery Mode:
Patient adherence requirements and site-of-care economics determine formulation investment, with chronic management favoring patient-administered options and acute decompensation requiring supervised administration.
- Oral Administration:Small-molecule formulations dominate chronic outpatient management, enabling patient self-administration and reducing hepatology center capacity constraints. German and United States reimbursement frameworks favor oral regimens for their lower per-treatment administration costs.
- Intravenous:Hospital-based infusion protocols concentrate in acute settings and combination regimens requiring therapeutic drug monitoring. Japanese specialty centers utilize IV delivery for investigational fibrosis inhibitors under controlled access programs.
- Injectable:Subcutaneous biologics occupy a narrowing middle ground as oral small-molecule potency improves.
- Transdermal:Limited penetration due to molecular weight constraints of protein-based fibrosis modulators.
Procurement consolidation around oral platforms intensifies; IV partnerships with hospital networks defend specialty positioning.
End User:
Capital equipment requirements and protocol complexity stratify access, with elastography-validated staging capabilities concentrating demand in settings capable of longitudinal monitoring.
- Hospitals:Integrated hepatology centers in the United States, Germany, and Japan anchor demand through FibroScan-equipped facilities and multidisciplinary care teams. These institutions capture the majority of combination therapy initiations and clinical trial enrollment.
- Specialty Centers:Dedicated liver clinics in France and the United Kingdom leverage focused expertise to attract complex NASH and alcoholic liver disease cases. EU AI Act compliance requirements for diagnostic algorithms are reshaping vendor selection in these settings.
- Clinics:Community gastroenterology practices handle stable antiviral maintenance with limited staging capacity.
- Home Care:Oral antiviral dispensing extends to this channel where monitoring infrastructure permits.
Revenue concentration favors hospitals; patient access expansion favors specialty centers.
Application:
Etiological diversity drives biomarker stratification and trial design, with each indication presenting distinct regulatory endpoints and competitive dynamics.
- Non-Alcoholic Steatohepatitis:Metabolic disease mechanisms attract the majority of novel fibrosis inhibitor development, with LOXL2 and TGF-beta programs prioritizing this population. United States hepatology centers lead enrollment for NASH-specific trials.
- Chronic Hepatitis:Viral suppression goals are well-established, with antiviral therapy penetration highest in Japanese and German screening programs. Histological endpoint requirements from FDA and EMA maintain biopsy confirmation standards for label expansion.
- Alcoholic Liver Disease:Abstinence counseling integration complicates pharmacological trial design and reimbursement.
- Others:Autoimmune and cholestatic indications represent niche development targets with orphan pathway potential.
Development investment concentrates in NASH; regulatory clarity favors chronic hepatitis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA breakthrough therapy incentives and Japan's Sakigake designation are concentrating clinical trial investment in hepatology centers with established elastography infrastructure. Reimbursement pathways for combination regimens diverge sharply across national health technology assessment frameworks.
United States
Specialized hepatology centers in Boston, New York, and San Francisco anchor demand for LOXL2-targeted therapies under FDA accelerated approval pathways. Medicare coverage determinations for non-invasive staging are expanding FibroScan deployment beyond academic medical centers. The Mayo Clinic and Cleveland Clinic networks are standardizing combination therapy protocols for NASH-related fibrosis.
Germany
Hospital-based hepatology departments in Munich and Hamburg drive adoption of TGF-beta inhibitors through EMA conditional marketing authorization frameworks. The Federal Joint Committee's benefit assessment procedures for novel fibrosis therapies create predictable reimbursement timelines. Heidelberg and Berlin clusters concentrate Phase III trial enrollment for European label expansion.
Japan
PMDA's Sakigake priority review system is attracting NASH-focused development programs to Tokyo and Osaka hepatology centers. National health insurance price premiums for breakthrough-designated therapies incentivize domestic clinical investment. Yokohama-based contract research organizations are specializing in fibrosis endpoint validation for Asian patient populations.
United Kingdom
NICE technology appraisals for fibrosis reversal therapies are concentrating prescribing authority in London and Manchester tertiary centers. The NHS England specialized commissioning framework restricts combination therapy initiation to designated liver units. Cambridge and Oxford research hospitals are integrating AI-enabled elastography scoring into therapeutic decision workflows.
Switzerland
Swissmedic's streamlined authorization for orphan fibrosis indications supports Basel and Zurich hepatology centers in early-access programs. Mandatory health insurance coverage for innovative therapies reduces patient cost barriers relative to neighboring markets. The Lausanne University Hospital network is pioneering real-world evidence collection for post-approval label expansion.
Liver Fibrosis Treatment Market Competitive Environment
Player mix skews toward integrated pharmaceutical conglomerates with antiviral platforms and emerging biotech specialists with mechanistic precision in collagen biology. Market structure exhibits tiered consolidation, with three to four firms capturing majority share in established antiviral segments while fibrosis inhibitor development fragments across venture-backed entrants. Dominant strategic archetypes include platform-scale antiviral developers, precision-target biologics specialists, and diagnostic-therapeutic integrators. Competitive moves center on hospital network exclusivity agreements and companion diagnostic co-development partnerships.
Among the integrated pharmaceutical conglomerates, Gilead Sciences, Inc. and Pfizer Inc. exemplify platform-scale archetypes with manufacturing infrastructure supporting global distribution. Vertex Pharmaceuticals Incorporated occupies a distinct position translating cystic fibrosis mechanistic expertise into hepatic applications. These three firms collectively represent the convergence of antiviral legacy assets and fibrosis-targeted pipeline expansion that characterizes current competitive positioning.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Vertex Pharmaceuticals Incorporated |
| Gilead Sciences, Inc. |
| FibroGen, Inc. |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Pharmaxis Limited |
| Bristol-Myers Squibb |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements for recombinant protein inputs lock in both supply access and price visibility for fibrosis inhibitor developers, with Chinese contract manufacturing capacity commanding premium reservation fees under FDA and EMA quality audits.
Pricing Analysis
Certification level (FDA-breakthrough versus standard IND-grade) creates the primary spread across therapeutic classes, with three-tier pricing structure across premium, standard, and economy levels stratifying by elastography validation requirements. LOXL2-targeted biologics command premium positioning in United States hepatology centers, while oral antiviral generics face cost compression in German outpatient reimbursement. Hospital procurement committees demonstrate lowest price sensitivity for combination regimens with companion diagnostics, whereas community clinics exhibit highest sensitivity to per-patient administration costs.
Supply Chain Analysis
China and India anchor recombinant protein production for fibrosis modulators, with South Korea emerging as a secondary hub for monoclonal antibody fill-finish. Active pharmaceutical ingredient synthesis draws from concentrated coastal manufacturing zones, while sterile biologics production rests on specialized cold-chain infrastructure. Single-source vulnerability concentrates in TGF-beta inhibitor precursor supply, with distribution running through hospital-based specialty pharmacy networks rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in liver fibrosis treatment are reaching an inflection as AI-enabled elastography scoring creates interoperability standards between diagnostic hardware and therapeutic protocols, consolidating vendor ecosystems around integrated data layers.
For Market Incumbents: Secure exclusive FibroScan placement contracts across United States academic medical center networks before LOXL2-targeted competitors achieve formulary inclusion. Deepen backward integration into recombinant protein production to offset Chinese manufacturing concentration risk. Prioritize FDA breakthrough therapy designation maintenance through confirmatory trial investment. For New Entrants and Emerging Players: PMDA Sakigake fast-track designation offers the most penetrable regulatory pathway for NASH-focused fibrosis inhibitors seeking priority review. Target Japanese hepatology centers with combination therapy protocols addressing unmet metabolic disease progression. Pursue companion diagnostic co-development partnerships with AI-elastography developers to differentiate mechanistic claims. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic-therapeutic integrators with hospital platform contracts spanning hardware, software, and protocol licensing. Five-to-ten year viability favors precision-target biologics specialists with validated collagen biology mechanisms over broad-spectrum anti-inflammatory developers. Monitor FDA Project Orbis participation rates as inflection indicator for post-approval label expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerated approval compresses development timelines for LOXL2-targeted candidates in United States hepatology centers. |
| Companion Diagnostic Partnership | AI-elastography integration creates differentiated positioning for fibrosis reversal therapies with validated staging correlation. |
| Hospital Network Exclusivity Agreement | Single-source platform contracts in Germany and Japan raise switching costs for emerging competitors. |
| EMA Conditional Marketing Authorization | Streamlined European pathways enable earlier revenue recognition for TGF-beta inhibitor programs. |
| Real-World Evidence Framework Participation | FDA Project Orbis and EMA DARWIN EU access supports post-approval label expansion through observational data. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing across antiviral, combination, and fibrosis inhibitor therapeutic classes.
Across the analysis window, forecasts segment by treatment line, administration route, patient population, and regional regulatory cluster. CAGRs derive from epidemiological progression modeling, reimbursement pathway velocity, and elastography penetration assumptions. Inputs include PMDA Sakigake designation timelines, EMA conditional authorization conversion rates, and Medicare coverage determination patterns for non-invasive staging.
Underlying assumptions cover regulatory pathway stability, biomarker validation consensus, and hospital procurement consolidation trajectories, with deviation risk concentrated in gene therapy substitution timelines and AI diagnostic algorithm approval velocity. Recalibration cycles align with material shifts in FDA breakthrough designation criteria and real-world evidence framework adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Liver Cancer Treatment Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Lung Disease Therapeutics Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Bronchiectasis Therapeutic Market
Specialty Medicine
Bipolar Disorders Treatment Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Ulcerative Colitis Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Hypophosphatasia Treatment Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Intramedullary Osteosarcoma Treatment Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Chromoblastomycosis Treatment Market