
 Global Aircraft Pumps Market | 2026-2036
Global Aircraft Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Pumps Market Intelligence
A consolidation wave among Tier-2 suppliers in the United States and France is recalibrating the supply chain for specialized pump components. Major integrators like Parker-Hannifin Corporation leverage extensive product portfolios to serve both OEM and MRO channels. Safran specializes in complex engine and landing gear systems, integrating its own advanced hydraulic and fuel pumps. Meanwhile, Woodward, Inc. competes on the basis of its precision control systems for fuel and actuation applications.
Aircraft pumps are devices that move fluids like fuel, hydraulic oil, or coolant at specific pressures and flow rates within aviation systems. They must operate reliably under extreme temperature and G-force conditions, often using materials like titanium and aluminum alloys. Hydraulic pumps constitute the largest product segment, while electric-driven fuel pumps for Unmanned Aerial Vehicles represent a high-growth area. Commercial aircraft applications drive procurement volume, primarily through the Original Equipment Manufacturer (OEM) end-user channel.
Component airworthiness and certification are governed by bodies such as the FAA in the United States and EASA in Europe. Material and substance regulations, including REACH in the EU and equivalent standards from China's MEE, influence material selection for pump manufacturing. Navigating divergent certification pathways for novel electric and hybrid-electric propulsion systems is a critical challenge for pump developers.
Market Dynamics
The fundamental transition toward more-electric aircraft architectures is the central force reshaping the aircraft pumps market. This shift necessitates entirely new pump designs that integrate power electronics and manage complex thermal loads, moving beyond traditional mechanical and hydraulic systems.
Growth Catalysts
- UAV Sector Demand:The proliferation of Unmanned Aerial Vehicles (UAVs) for military and commercial use drives requirements for highly efficient, miniaturized fuel and hydraulic pumps that offer superior power-to-weight ratios.
- Chinese Aircraft Production:The ramp-up of commercial aircraft manufacturing in China, including programs like the COMAC C919, creates a significant, geographically concentrated source of new-build pump procurement for the entire supply chain.
- More-Electric Architectures:The architectural shift away from pneumatic and hydraulic power toward electrical systems on new platforms like the Boeing 787 and Airbus A350 creates organic demand for advanced electric-driven pumps for actuation and cooling.
Market Restraints
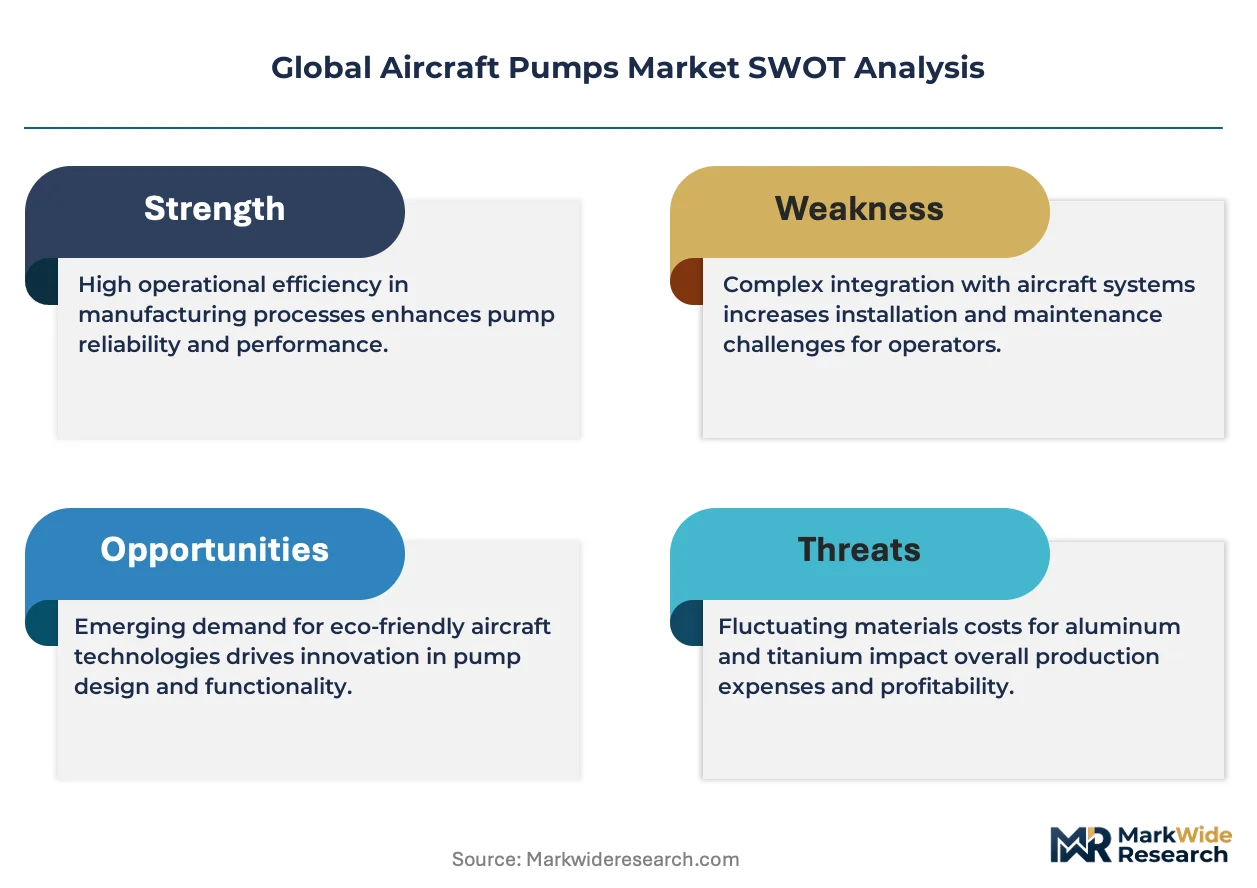
- Material Cost Volatility:Reliance on specialized materials like titanium and aerospace-grade aluminum alloys, whose prices are subject to geopolitical and supply chain pressures, creates significant cost uncertainty for pump manufacturers.
- Stringent Certification Cycles:The lengthy and expensive airworthiness certification processes mandated by bodies like the FAA and EASA for flight-critical components substantially increase development timelines and costs, acting as a barrier to rapid innovation.
- Extreme Operating Requirements:The necessity for pumps to function flawlessly under extreme G-forces, wide temperature ranges, and high-vibration environments limits the pool of qualified suppliers and restricts the use of lower-cost, commercial-off-the-shelf technologies.
Strategic Opportunities
- Hybrid-Electric Propulsion Systems:The development of hybrid-electric and all-electric aircraft opens a major opportunity for pumps in novel applications, particularly for cooling power electronics, batteries, and high-power-density electric motors.
- Integrated Pump Electronics:Converging pump mechanics with on-board power electronics and health monitoring sensors allows suppliers to offer higher-value, smarter systems that enable predictive maintenance and improved system diagnostics.
- MRO Channel Expansion:The growing global fleet of new-generation aircraft creates a substantial, long-term opportunity for suppliers to capture high-margin aftermarket revenue through Maintenance, Repair, and Overhaul (MRO) services and spare parts.
Industry Challenges
- Divergent Certification Pathways:Developers face uncertainty in navigating inconsistent and evolving certification standards from regulators like the FAA and EASA for novel components intended for hybrid-electric propulsion systems.
- Tier-2 Supplier Consolidation:A consolidation wave among specialized component suppliers in the United States and France increases dependency on a smaller number of key sources, creating potential supply chain risks for major integrators.
- Multidisciplinary Skill Gaps:Designing next-generation electric pumps requires engineering teams to possess a blend of mechanical, fluid dynamics, power electronics, and software expertise, a talent combination that is currently scarce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Pumps Market |
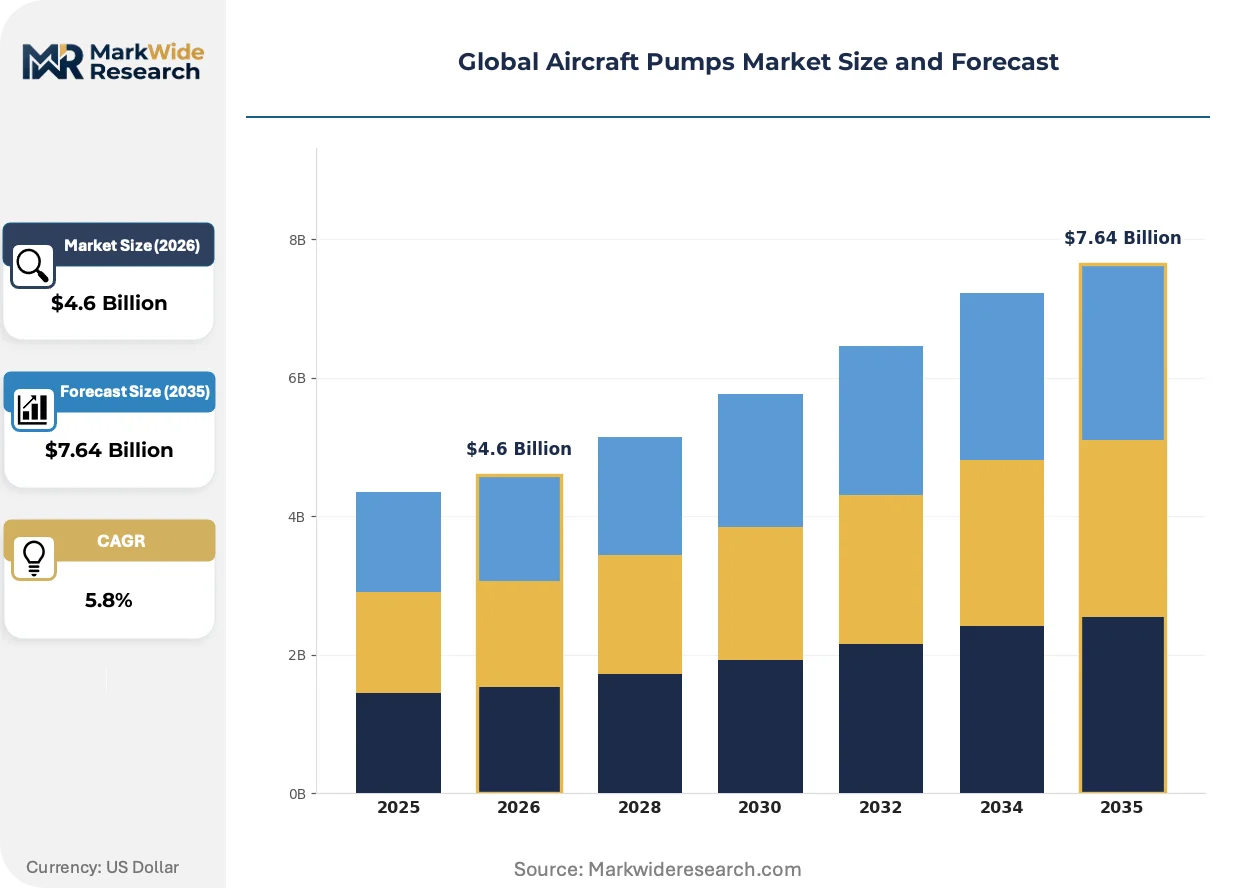
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $7.64 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pumps, Fuel Pumps, Oil Pumps, Water Pumps, Vacuum Pumps Technology: Gear, Centrifugal, Diaphragm, Piston, Vane Application: Commercial Aircraft, Military Aircraft, General Aviation, Unmanned Aerial Vehicles, Business Jets End User: Original Equipment Manufacturers, Maintenance Repair Organizations, Aircraft Operators, Repair Stations |
| Companies Covered | Safran, Eaton Corporation plc, Parker-Hannifin Corporation, Woodward, Inc., Crane Co., Collins Aerospace, Honeywell International, Inc., AeroControlex, Zodiac Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Pumps Market Strategic Shifts & Innovations
Electrification and digitalization are transforming aircraft pumps from standalone mechanical devices into integrated mechatronic systems. This evolution is driven by demands for higher efficiency, predictive maintenance capabilities, and compliance with stricter environmental regulations, reshaping component design and supplier competencies.
Smart pumps integrating embedded sensors and health-monitoring software are becoming a key area of innovation. Original Equipment Manufacturers and MRO providers are the primary adopters, seeking to enable predictive maintenance schedules. This technology is expanding into a core enabler for condition-based maintenance strategies that maximize aircraft availability by minimizing unscheduled component failures.
The EU's REACH regulation places significant constraints on materials historically used in pump manufacturing and associated hydraulic fluids. This directive compels component makers to invest heavily in R&D to qualify and certify compliant alternatives, such as new alloys, seals, and coatings. The hydraulic systems and landing gear segments are most affected, accelerating the validation of chrome-free alternatives within European supply chains.
Airlines and MRO service providers are increasingly prioritizing total lifecycle cost over initial unit price for critical components. This behavioral shift disrupts traditional transactional sales models, favoring long-term service agreements that bundle repairs, spares, and reliability guarantees. This trend is most pronounced in the maintenance programs for wide-body commercial aircraft, where fleet availability is the paramount economic driver.
Global Aircraft Pumps Market Segmentation
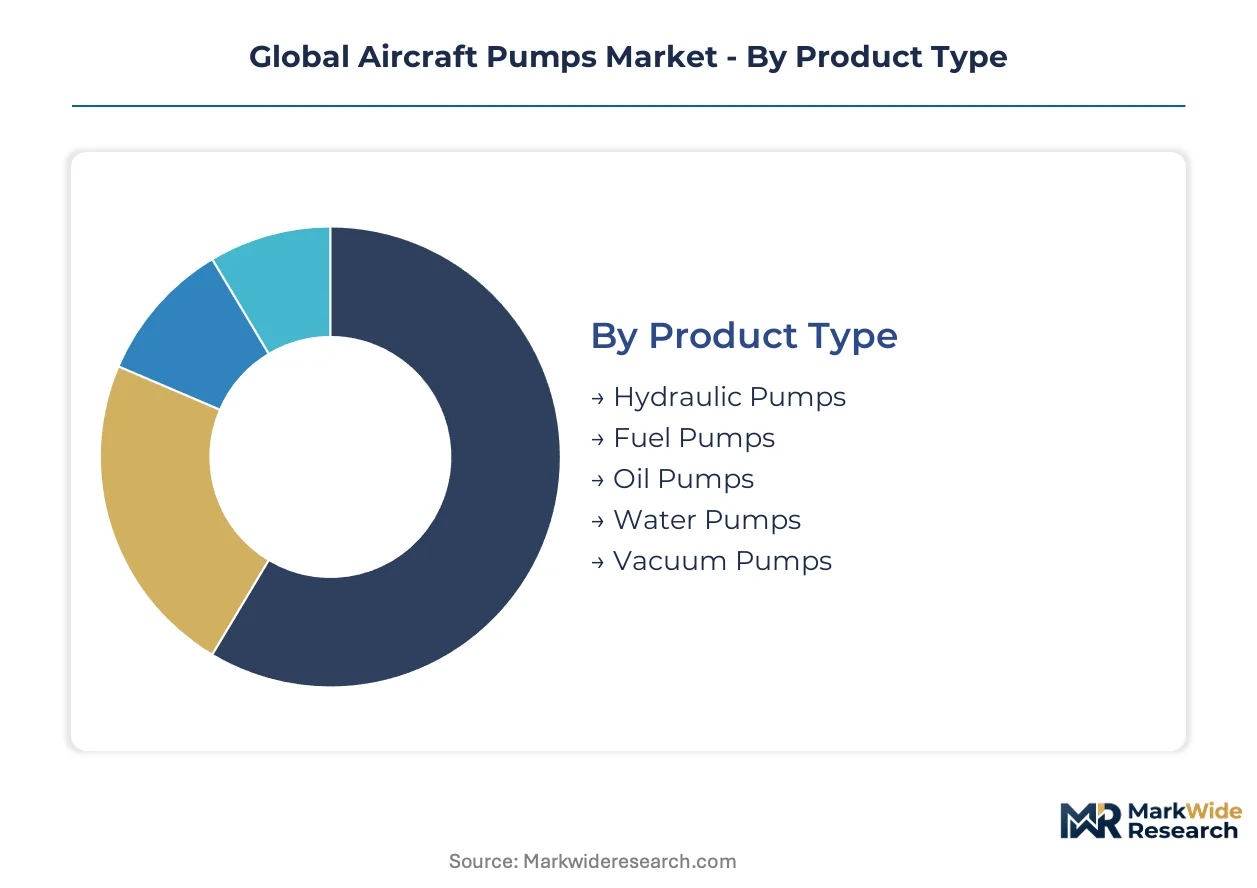
The global aircraft pumps market is structurally segmented to reflect the diverse technical specifications, operational applications, and end-user procurement channels that define this critical aerospace component sector. Understanding these segments is vital for stakeholders to pinpoint demand concentrations and technological shifts within the industry.
Product Type:
The aircraft pumps market categorizes components by their primary fluid handling technology and operational function.
- Hydraulic Pumps:These devices move hydraulic oil at specific pressures and flow rates, forming the backbone of aircraft actuation systems. Commercial aircraft applications drive the largest procurement volume for this product type.
- Fuel Pumps:Essential for transferring fuel from tanks to engines, these pumps must operate reliably across diverse flight conditions. Electric-driven versions for Unmanned Aerial Vehicles represent a high-growth area due to efficiency demands.
- Oil Pumps:These components circulate lubricating oil within engine systems, ensuring optimal performance and cooling of critical moving parts.
- Water Pumps:Specialized water pumps manage coolant flow for thermal regulation in advanced aircraft systems, particularly for power electronics and environmental control.
- Vacuum Pumps:These devices create negative pressure for specific aircraft systems, including de-icing or environmental control applications.
Mature deployment sits with hydraulic pumps. Newer deployment is concentrated in electric-driven fuel pumps for UAVs.
Technology:
Pump technology selection often hinges on specific application requirements, balancing efficiency with pressure and flow demands.
- Piston:These pumps utilize reciprocating plungers to generate high-pressure fluid flow, crucial for robust hydraulic actuation systems. They are critical components in large commercial aircraft landing gear and flight control systems.
- Gear:Employing intermeshing gears to displace fluid, gear pumps provide reliable flow for fuel and lubrication systems. This technology finds extensive use in both commercial and military aircraft engines due to its durability.
- Centrifugal:Centrifugal pumps use rotational kinetic energy to move fluids, often for lower pressure, high-flow applications such as coolant circulation within thermal management systems.
- Diaphragm:Utilizing a flexible membrane to pump fluids, diaphragm pumps are suitable for applications requiring fluid isolation or precise dosing, particularly in niche aircraft systems.
- Vane:Vane pumps utilize rotating vanes to create positive displacement, commonly found in vacuum or lower-pressure hydraulic applications where consistent flow is required.
Specific designs like piston pumps are optimized for high-pressure hydraulic systems, while gear designs address reliable fuel and oil circulation.
Application:
The market segments by aircraft type, reflecting distinct operational environments and procurement scales.
- Commercial Aircraft:This segment represents the largest volume for pump procurement, driven by global fleet expansion and new aircraft deliveries from manufacturers like COMAC. These platforms require robust pumps for hydraulic, fuel, and cooling systems.
- Unmanned Aerial Vehicles:This segment demands miniaturized, high-efficiency fuel and hydraulic pumps with superior power-to-weight ratios. Military and commercial drone proliferation is a significant growth catalyst for this application.
- Military Aircraft:Military aircraft require pumps designed for extreme operational conditions and high performance in combat and transport platforms, emphasizing durability and mission readiness.
- General Aviation:This category includes pumps for smaller piston-engine and turboprop aircraft, focusing on reliability and cost-effectiveness for private and training fleets.
- Business Jets:Business jets utilize specialized pumps for sophisticated hydraulic and fuel systems, emphasizing passenger comfort, operational efficiency, and extended range capabilities.
The largest procurement volumes stem from commercial aircraft, with unmanned aerial vehicles exhibiting rapid expansion.
End User:
End-user segmentation highlights the diverse procurement channels and service needs across the aircraft lifecycle.
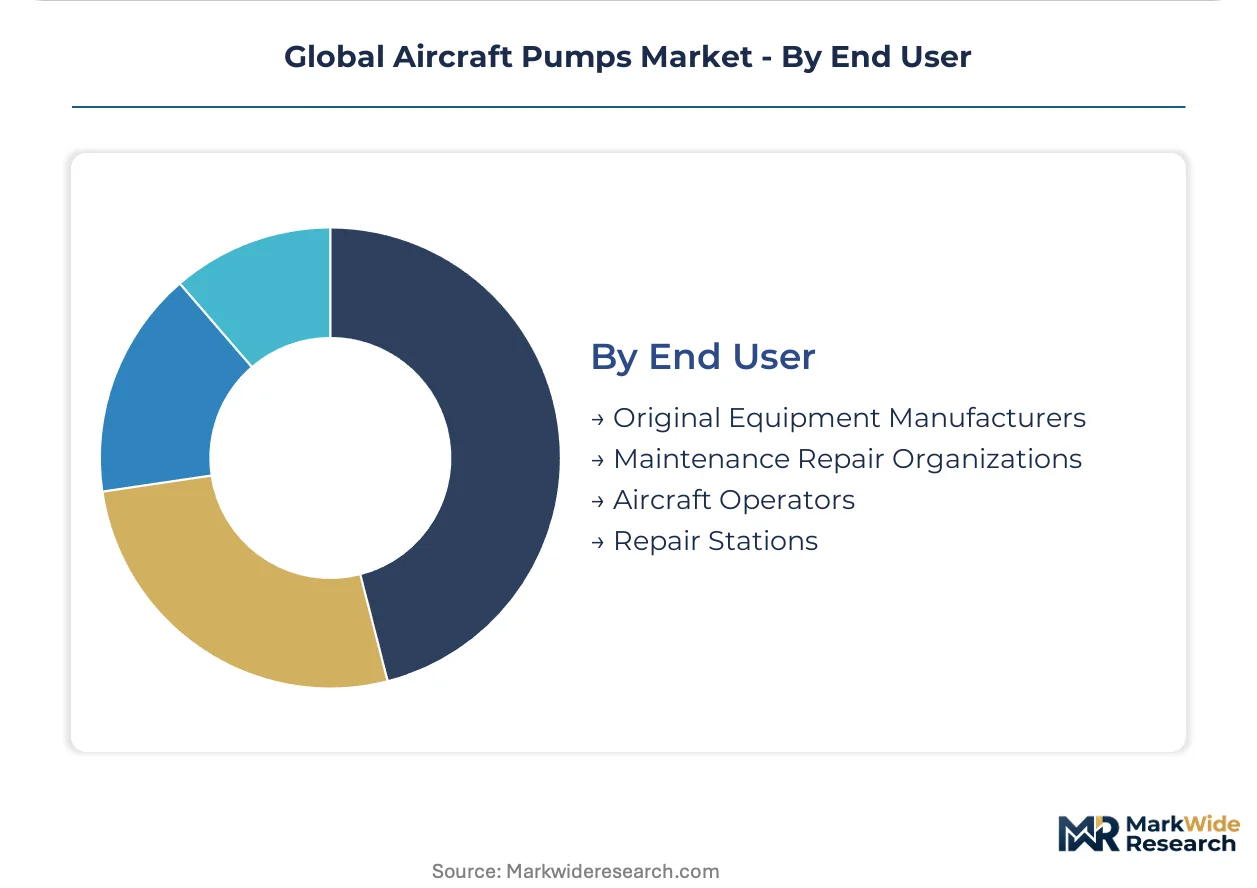
- Original Equipment Manufacturers:OEMs like Boeing and Airbus integrate pumps into new aircraft designs and production lines, driving initial procurement volumes. New-build commercial aircraft in China represent a significant locus for OEM pump procurement.
- Maintenance Repair Organizations:MROs provide aftermarket services for pump overhaul, repair, and replacement, leveraging long-term service agreements. The expanding global fleet creates substantial MRO channel expansion opportunities.
- Aircraft Operators:Airlines and cargo carriers procure pumps for line maintenance and operational spares, prioritizing component reliability and total lifecycle costs to maximize aircraft availability.
- Repair Stations:Independent and airline-affiliated facilities perform specialized repairs on aircraft pumps, ensuring airworthiness and extending the operational lifespan of critical components.
Demand for new pumps primarily originates from Original Equipment Manufacturers, while aftermarket services are dominated by Maintenance Repair Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's expanding aerospace manufacturing sector anchors global demand for new aircraft pumps, driven by domestic commercial aircraft programs. This growth creates substantial procurement opportunities for specialized components worldwide. The country's industrial policies support the localization of advanced aviation technologies.
United States
United States demand for aircraft pumps stems from military aircraft modernization programs and the expanding Unmanned Aerial Vehicles sector. FAA certification processes significantly influence product development and market entry for new pump technologies. Major aerospace clusters in Southern California drive innovation and production for defense and commercial aviation applications.
France
French aerospace manufacturers, particularly Airbus, drive significant pump procurement for commercial aircraft production lines. EASA airworthiness standards mandate rigorous testing and compliance for all flight-critical components, including pumps. The Toulouse region serves as a central hub for aerospace manufacturing and component integration, supporting extensive supply chains.
Germany
German aerospace engineering focuses on advanced materials and precision manufacturing for aircraft pumps, supporting both commercial and military platforms. EASA regulations and the EU Green Deal influence the development of more efficient and environmentally compliant pump systems. Hamburg's aerospace cluster, with its strong ties to Airbus, remains a key center for component development and integration.
Japan
Japanese aerospace companies contribute to regional jet programs and maintain a substantial MRO market for existing fleets, creating consistent demand for aircraft pumps. METI policies encourage domestic aerospace industry development and adherence to stringent JIS standards. The Nagoya area anchors a significant portion of Japan's aerospace manufacturing, including component suppliers for various aircraft types.
China
China's ramp-up of commercial aircraft manufacturing, notably the COMAC C919, generates substantial new-build pump procurement volume. The MEE's environmental standards and national GB standards influence material selection and manufacturing processes for aviation components. Shanghai's aerospace industrial base is a primary locus for aircraft assembly and related component supply chain activities.
Global Aircraft Pumps Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches like electric propulsion system components. The market exhibits a tiered structure, with major integrators and specialized component suppliers. Strategic archetypes include diversified aerospace conglomerates, precision control system specialists, and advanced material innovators. Companies are engaging in portfolio diversification and strategic partnerships to expand their market reach and technological capabilities.
Within the diversified aerospace conglomerate archetype, French-based Safran exemplifies integration across complex engine and landing gear systems, often incorporating its own advanced hydraulic and fuel pumps. US-based Parker-Hannifin Corporation represents a major integrator, leveraging its extensive product portfolios to serve both OEM and MRO channels globally. Woodward, Inc., another US-based entity, anchors the precision control systems segment, particularly for fuel and actuation applications requiring high reliability. These companies collectively demonstrate distinct strategies for market penetration and value capture within the aircraft pumps sector.
| Leading Market Players |
|---|
| Safran |
| Eaton Corporation plc |
| Parker-Hannifin Corporation |
| Woodward, Inc. |
| Crane Co. |
| Collins Aerospace |
| Honeywell International, Inc. |
| AeroControlex |
| Zodiac Aerospace |
| Others |
Cost & Logistics Intelligence
The EU's REACH regulation, influencing material selection, gates qualified supply for compliant components and drives premium-tier pricing for certified alternatives. This regulatory pressure forces manufacturers to invest in research and development for new alloys and coatings. Such mandates reshape both component availability and cost structures across the value chain.
Pricing Analysis
Long-term service agreements that bundle repairs, spares, and reliability guarantees are increasingly prioritized over initial unit price. Price differentiation stems from airworthiness certification levels and the integration of advanced materials like titanium alloys. Pricing softness affects standard components due to competitive pressures, while specialized, flight-critical pumps command a premium. Commercial aircraft OEMs purchasing new-build components exhibit lower price sensitivity for high-reliability systems compared to general aviation operators.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns manage the flow of specialized pump components to global assembly lines and MRO facilities. Supply concentration is evident in the United States, France, and China for key manufacturing and new-build procurement. The supply chain relies heavily on specialized materials, including titanium and aerospace-grade aluminum alloys. Tier-2 supplier consolidation creates single-source vulnerability, posing a structural risk for major integrators. Downstream distribution runs through direct OEM sales and aftermarket MRO channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play, as stringent certification cycles and extreme operating requirements force smaller, less capitalized players out. Strategic acquisitions and partnerships will define future competitive landscapes.
For Market Incumbents:
Anchor existing market share by deepening vertical integration into critical component manufacturing and certification processes. Invest heavily in R&D for compliant materials and integrated power electronics to meet evolving regulatory and architectural demands. Expand MRO channel capabilities globally, leveraging extensive product portfolios to capture high-margin aftermarket revenue. This strategy mitigates threats from new technology entrants and divergent certification pathways.
For New Entrants and Emerging Players:
Capture white-space opportunities within the rapidly expanding Unmanned Aerial Vehicles (UAV) sector, focusing on miniaturized, high-efficiency fuel and hydraulic pumps. Target the emerging hybrid-electric propulsion systems segment by developing novel cooling solutions for power electronics and batteries. A go-to-market angle emphasizing superior power-to-weight ratios and advanced thermal management will differentiate offerings in these high-growth niches.
For Investors and Strategic Acquirers:
The first commercial deployment of hybrid-electric aircraft is the leading indicator that validates advanced electric pump technologies and opens new investment avenues. The aircraft pumps market offers long-term viability, driven by new aircraft architectures and fleet expansion. Target acquisition archetypes include precision control system specialists and firms with strong multidisciplinary engineering expertise in mechatronics and fluid dynamics. Focus on entities possessing robust certification capabilities for novel components.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced material R&D | Ensures compliance with environmental regulations like REACH and maintains market access. |
| Expand MRO service capabilities | Captures high-margin aftermarket revenue from a growing global aircraft fleet. |
| Develop integrated pump electronics | Enables predictive maintenance and offers higher-value, smarter system solutions. |
| Form partnerships for hybrid-electric systems | Accelerates entry into novel applications for cooling power electronics and batteries. |
| Upskill engineering teams in mechatronics | Addresses multidisciplinary skill gaps required for next-generation electric pump design. |
Research Approach
Independent corroboration across primary interviews, industry reports, and regulatory filings underwrites the qualitative findings of this analysis. The methodology combines insights from OEM procurement leads, MRO technical directors, aerospace engineers, and regulatory compliance officers. Secondary validation draws from FAA certification documents, EASA airworthiness directives, and aerospace industry association publications. A rigorous bottom-up and top-down triangulation approach ensures data accuracy.
The forecast framework anchors the projection horizon to historical performance and market trends. Quantitative modeling segments the market by product type, technology, application, end-user, and regional demand. Compound Annual Growth Rates (CAGRs) are derived from historical data and projected growth drivers, including commercial aircraft production forecasts and UAV adoption rates. This approach provides a comprehensive view of market evolution throughout the forecast period.
The model holds under current geopolitical stability and technological development trajectories; deviation in material cost volatility or unforeseen regulatory shifts would alter projections. Forecasts reflect assumptions documented through extensive primary and secondary research. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market