
 Global Aircraft Fuel Tanks Market | 2026-2036
Global Aircraft Fuel Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Fuel Tanks Market Foresight
Polymer-matrix composites are recalibrating aircraft fuel tank economics as aluminum-intensive designs face weight and corrosion penalties. Safran leverages its vertical integration across thermoset manufacturing to control composite fuel cell supply chains. Parker Hannifin Corporation anchors the aftermarket segment through its global distribution network for bladder tank replacements. RTX Corporation specializes in military conformal tank systems, sustaining program relationships with prime contractors across multiple fighter platforms.
Aircraft fuel tanks are sealed containment vessels engineered to store and deliver aviation fuel under pressurized, dynamic-load, and crash-impact conditions, typically constructed with multi-layer barrier systems, lightning strike protection meshes, and venting architectures that prevent vapor ignition. Integral tanks dominate commercial platforms where wing box structures double as fuel cavities, while bladder tanks command premium positioning in military rotorcraft and tactical aircraft due to their self-sealing, crash-resistant properties. Composite materials represent the fastest-growing technology segment as manufacturers substitute carbon fiber reinforced polymers for legacy aluminum alloy fabrications to achieve double-digit weight reductions.
FAA airworthiness standards under 14 CFR Part 25.963 and EASA CS-25 fuel tank safety regulations mandate ignition source prevention programs that directly shape material selection and system architecture decisions. The EPA's National Emission Standards for Hazardous Air Pollutants constrain volatile organic compound emissions during manufacturing processes, pushing suppliers toward closed-mold resin transfer techniques. Stakeholders must monitor evolving MIL-STD-889 requirements for fuel system compatibility with sustainable aviation fuel blends as defense and commercial fleets accelerate alternative fuel qualification timelines.
Market Dynamics
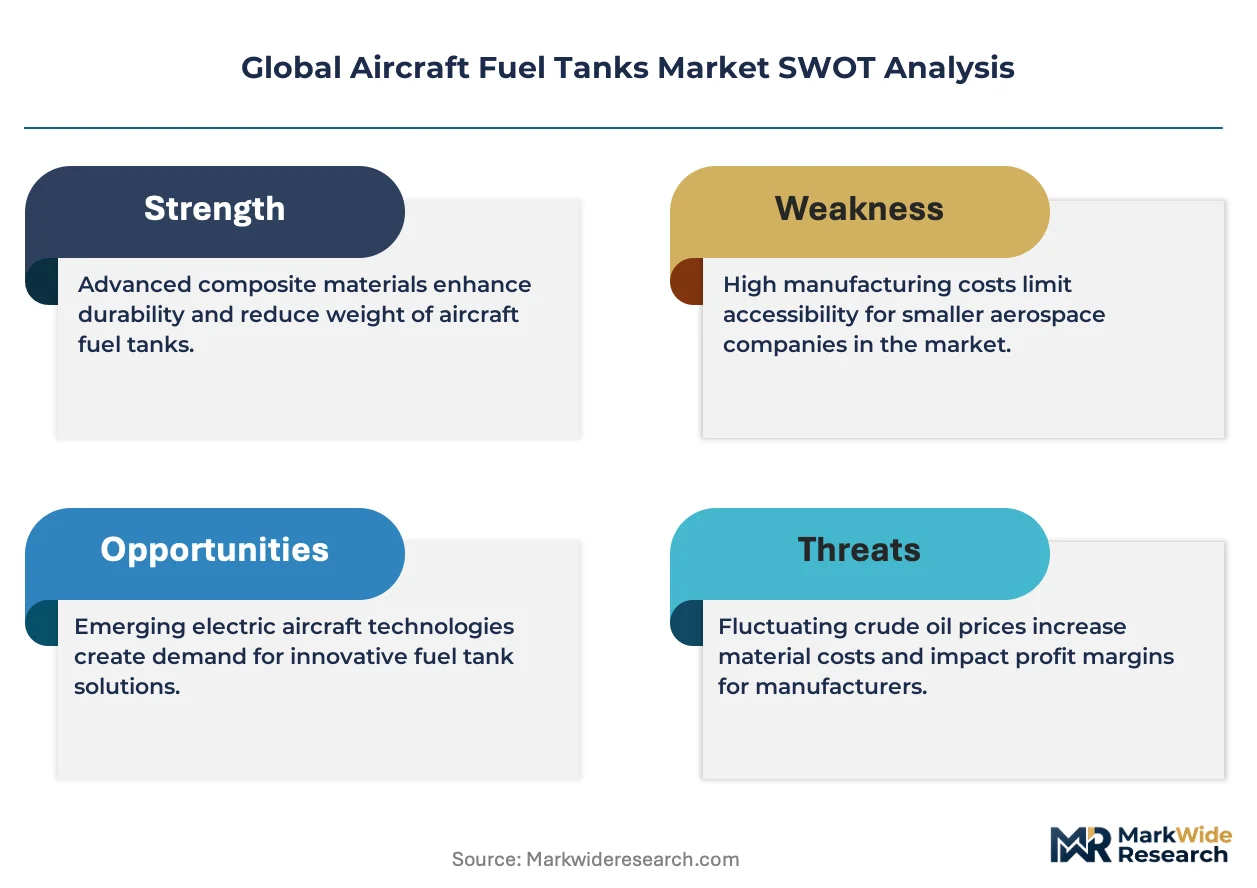
Composite material substitution is compressing aluminum's dominance in fuel tank fabrication as weight-reduction mandates from airframers cascade through tier-one supply chains. Military crashworthiness specifications and commercial ignition-source prevention rules are jointly accelerating multi-layer barrier architectures.
Growth Catalysts
- Sustainable Aviation Fuel Compatibility Mandates:MIL-STD-889 revisions and FAA certification pathways for SAF blends are forcing fuel system redesigns across defense and commercial fleets. Tank lining materials and seal architectures require reformulation.
- Lightweighting Imperatives in Wing Box Integration:Carbon fiber reinforced polymers are capturing share from 2000-series aluminum alloys in integral tank applications. OEMs specify double-digit weight reductions for next-generation narrowbody programs.
- NATO Military Procurement Expansion:Crash-resistant bladder systems are seeing concentrated demand from fighter and rotorcraft replacement programs across member states. Self-sealing technologies command premium positioning in tactical aircraft specifications.
Market Restraints
- Raw Material Supply Concentration:Aerospace-grade carbon fiber prepregs depend on a limited supplier base concentrated in Japan and the United States. Toray and Hexcel capacity allocations constrain tier-two fabricator expansion.
- Certification Timeline Friction:FAA 14 CFR Part 25.963 compliance for novel composite tank architectures extends development cycles by 18-36 months. Flight test validation for lightning strike protection adds program risk.
- Aluminum Price Volatility:7075-T6 and 2024-T3 alloy sheet costs fluctuate with LME pricing and aerospace mill premiums. Legacy platform sustainment programs face unpredictable material cost exposure.
Strategic Opportunities
- Urban Air Mobility Fuel Cell Integration:eVTOL platforms require conformal tank geometries that depart from conventional wing box architectures. Distributed electric propulsion layouts favor segmented fuel containment systems.
- Closed-Mold Manufacturing Techniques:EPA National Emission Standards for Hazardous Air Pollutants are pushing suppliers toward resin transfer molding. Out-of-autoclave processing reduces volatile organic compound emissions and energy intensity.
- Aftermarket Bladder Replacement Cycles:Military fleet aging is compressing replacement intervals for self-sealing fuel cells. Battle damage repair and preventive maintenance programs create recurring revenue streams independent of new aircraft deliveries.
Industry Challenges
- Multimaterial Joining Expertise Scarcity:Composite-to-titanium and composite-to-aluminum interface engineering requires specialized welding and fastening knowledge. Workforce development lags behind process qualification demands.
- Legacy Platform Integration Complexity:Retrofitting crash-resistant bladder systems into existing airframes demands structural modification and center-of-gravity recalculation. Engineering change orders proliferate through sustainment supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Fuel Tanks Market |
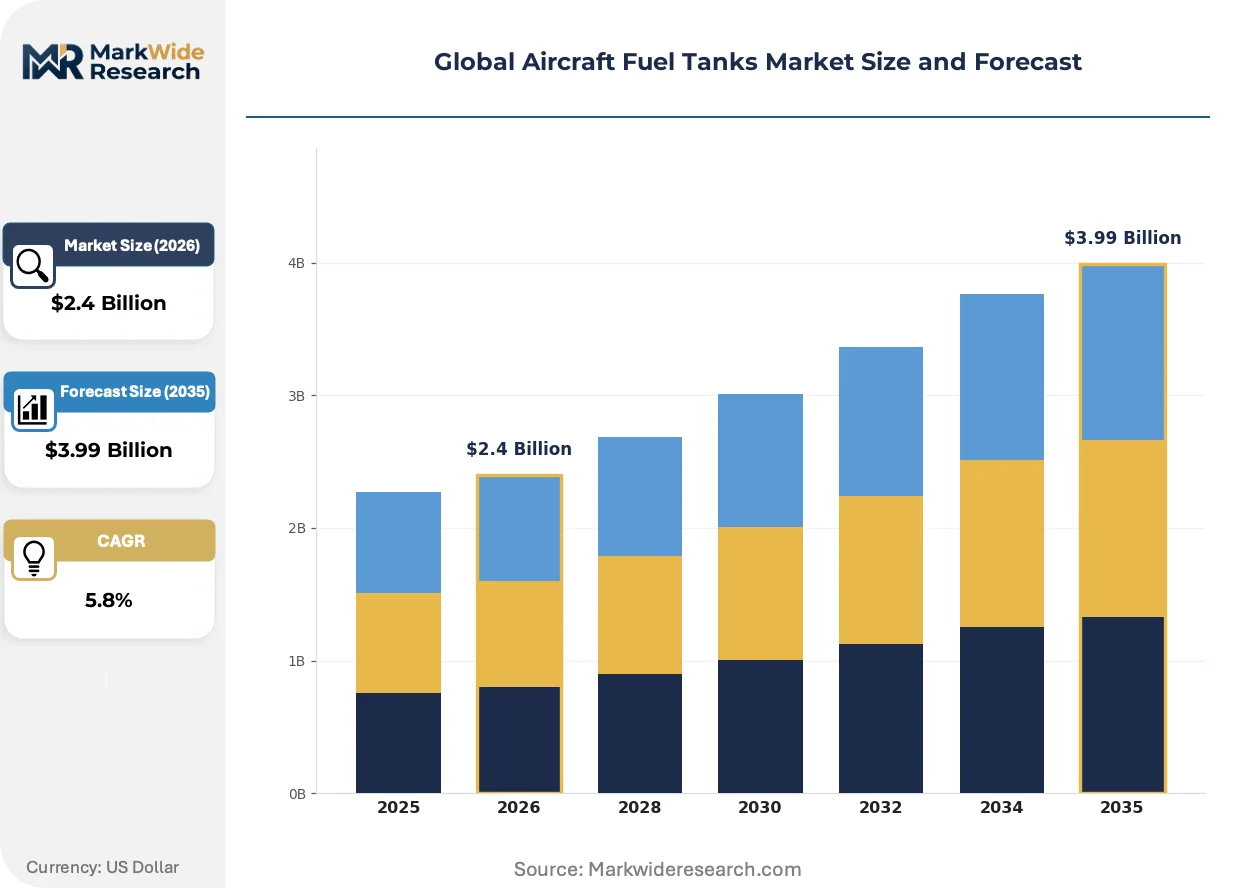
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integral Tank, Bladder Tank, Tip Tank, External Tank, Conformal Tank, Auxiliary Tank Technology: Composite Materials, Aluminum Alloy, Titanium Alloy, Fuel Bladder, Foam Fill, Insulation Coatings Application: Commercial Aircraft, Military Aircraft, Business Jets, Unmanned Aerial Vehicles, Helicopters, Special Mission Aircraft End User: Aircraft Manufacturers, Maintenance Providers, Defense Contractors, Aerospace Suppliers, Charter Operators, Flight Schools |
| Companies Covered | Safran, RTX Corporation, Parker Hannifin Corporation, Eaton Corporation, GKN Aerospace, Collins Aerospace, Meggitt PLC, Honeywell International Inc., Woodward Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Fuel Tanks Market Shifts & Advancements
Additive manufacturing is penetrating fuel tank component fabrication as topology-optimized brackets, baffles, and venting hardware displace conventional machined assemblies. Process qualification for flight-critical applications is advancing through focused energy deposition and powder bed fusion pathways.
Out-of-autoclave thermoset processing is decentralizing composite fuel cell production from centralized autoclave facilities to distributed manufacturing cells. Tier-two suppliers in Italy and Japan are adopting resin transfer molding for medium-volume military programs. This technology is decentralizing supply chain geography and compressing lead times for crash-resistant bladder systems.
EASA CS-25 fuel tank safety regulations are tightening ignition source prevention requirements for electrical wiring interconnection systems in proximity to fuel vapors. Manufacturers must demonstrate arc fault containment and segregation from tank boundaries. European narrowbody programs are responding with hardened conduit architectures and revised zoning protocols.
Defense procurement patterns are consolidating vendor relationships around long-term performance-based logistics contracts. Original equipment manufacturers are unbundling fuel system sustainment from platform-wide support agreements. The United States defense industrial base exhibits the most pronounced shift toward availability-based contracting for bladder tank replacements.
Global Aircraft Fuel Tanks Market Segmentation
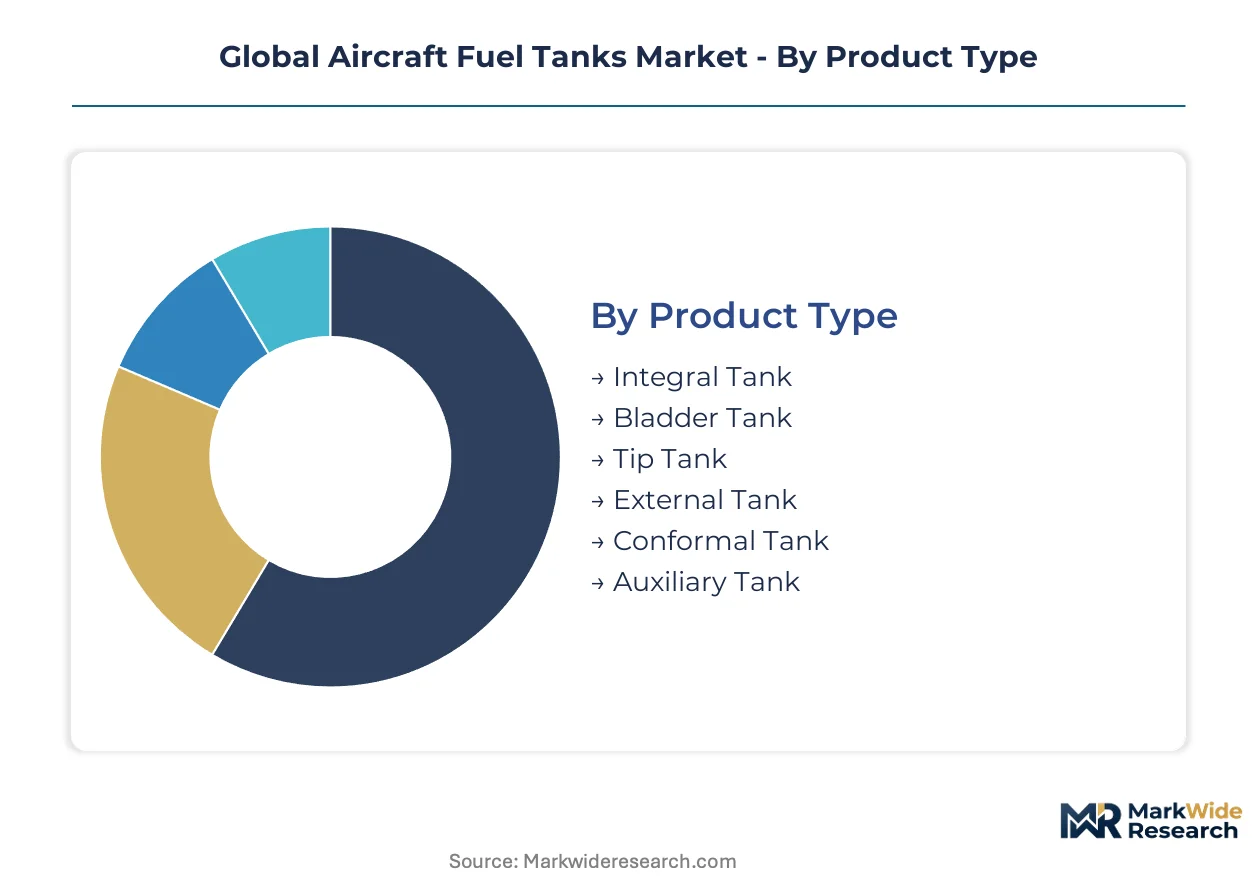
Aircraft fuel tank segmentation reflects divergent engineering requirements across platform types, with structural integration depth determining whether tanks function as standalone replaceable units or as embedded airframe elements. Material selection and certification pathways vary substantially across these boundaries, creating distinct competitive arenas with specialized supplier capabilities.
Product Type:
Integration depth separates segments into embedded structural systems versus removable auxiliary configurations, with crashworthiness mandates and weight targets driving divergent design philosophies.
- Integral Tank:Wing box cavities sealed with fuel-tight coatings and lightning protection meshes constitute the dominant commercial aviation architecture. Boeing 737 MAX and Airbus A320neo families specify these designs for center-of-gravity optimization and maximum fuel volume density.
- Bladder Tank:Multi-layer elastomeric cells with self-sealing capabilities absorb ballistic impact and crash deformation without catastrophic fuel release. NATO fighter programs and military rotorcraft procurement concentrate demand for these systems around crash-resistant specifications.
- Tip Tank:Wingtip-mounted auxiliary containers extend range for long-haul ferry flights and special mission profiles. These removable units minimize structural modification to host airframes.
- External Tank:Pylon-carried drop tanks provide mission-configurable range extension for tactical aircraft. Combat aircraft operators prioritize rapid jettison mechanisms and aerodynamic profiling.
- Conformal Tank:Fuselage-hugging geometries preserve radar cross-section and aerodynamic efficiency for low-observable platforms. RTX Corporation and prime contractors co-develop these for fifth-generation fighter programs.
- Auxiliary Tank:Supplementary internal or cargo bay installations address range deficits without permanent airframe modification. Business jet and special mission operators favor these for operational flexibility.
Integral tanks lead volumes today; conformal tanks are gaining share fastest through stealth platform proliferation.
Technology:
Cost tier stratification separates legacy metallic fabrication from advanced composite processing, with certification burden and raw material pricing creating distinct margin structures.
- Composite Materials:Carbon fiber reinforced polymers achieve double-digit weight reduction versus aluminum equivalents through resin transfer molding and out-of-autoclave processing. Narrowbody OEMs specify these for next-generation wing box fuel cavities.
- Aluminum Alloy:2000-series and 7000-series alloys remain prevalent in legacy platform sustainment and cost-sensitive applications. LME price volatility and aerospace mill premiums constrain supplier margins.
- Titanium Alloy:Corrosion-resistant sheet and extrusions dominate high-temperature zones and fastener interfaces. Military programs specify these for carrier-based aircraft exposure to salt environments.
- Fuel Bladder:Elastomeric multi-ply constructions with ballistic protection layers serve rotorcraft and tactical aircraft crashworthiness requirements. Self-sealing mechanisms activate upon puncture.
- Foam Fill:Reticulated polyurethane matrices suppress slosh dynamics and vapor ignition risk in military applications. These add parasitic weight traded against survivability gains.
- Insulation Coatings:Thermal barrier systems protect fuel properties during supersonic flight and high-altitude cold soak. Specialized formulations address sustainable aviation fuel compatibility.
Aluminum alloy retains installed base dominance; composite materials are expanding most quickly through new program adoption.
Application:
Customer type fragmentation separates defense procurement cycles from commercial aftermarket patterns, with platform life expectancy and utilization intensity shaping replacement economics.
- Commercial Aircraft:Narrowbody and widebody fleets drive integral tank volume through OEM production rates and heavy maintenance intervals. Wing box inspections trigger liner replacement programs.
- Military Aircraft:Fighter, tanker, and transport programs specify crash-resistant bladder and conformal configurations. Performance-based logistics contracts unbundle fuel system sustainment from platform support.
- Business Jets:Long-range platforms integrate auxiliary and tip tank options for transoceanic capability. Fractional ownership fleets compress utilization cycles.
- Unmanned Aerial Vehicles:Endurance-optimized designs prioritize weight reduction and conformal packaging. Surveillance platforms demand extended loiter configurations.
- Helicopters:Crash-resistant bladder systems are mandatory for civil and military rotorcraft certification. Self-sealing technology commands premium positioning.
- Special Mission Aircraft:Intelligence, surveillance, and reconnaissance platforms require modified tank architectures for sensor payload accommodation and extended duration.
Commercial aircraft dominates absolute volume; unmanned aerial vehicles show steepest expansion trajectory through defense and commercial dual-use proliferation.
End User:
Supply concentration varies across manufacturing versus aftermarket channels, with defense contractor consolidation contrasting fragmented maintenance provider networks.
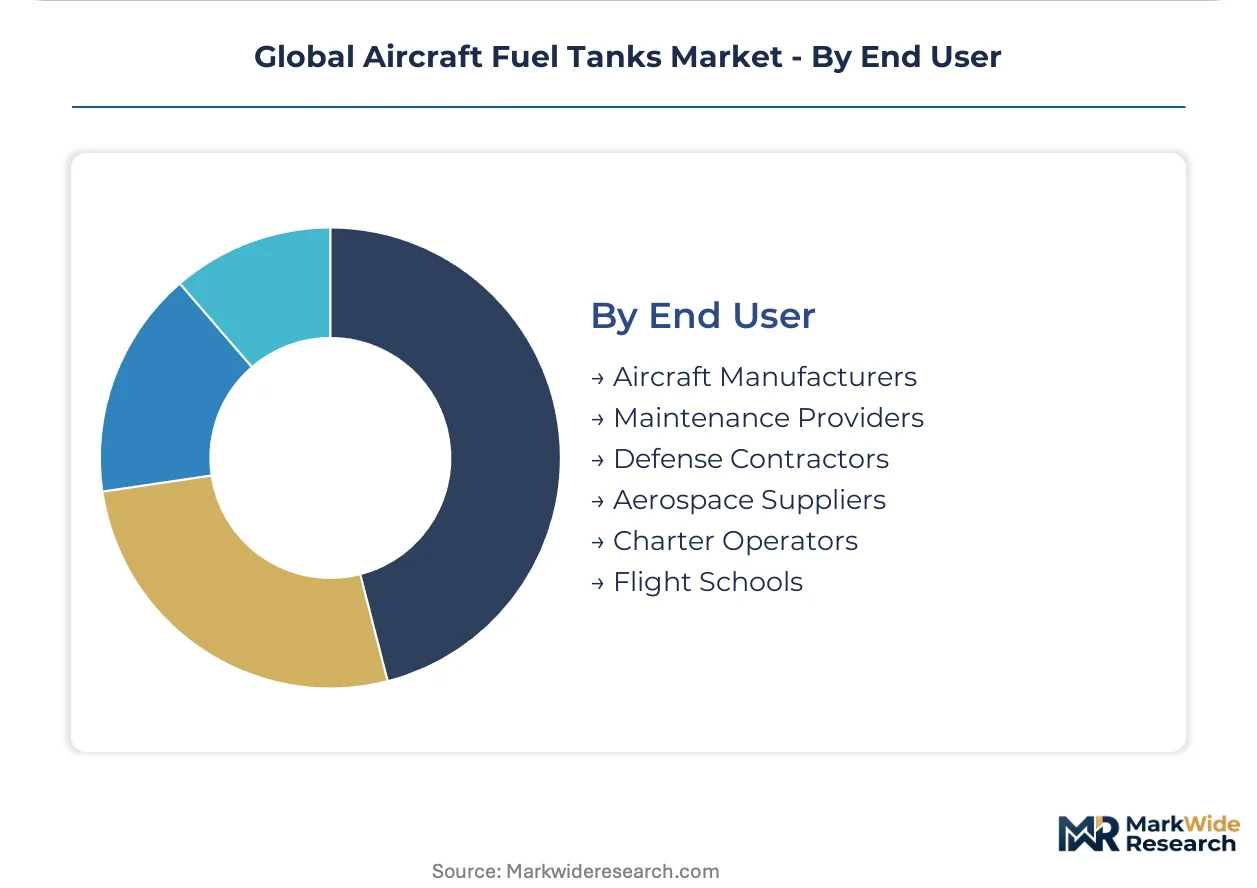
- Aircraft Manufacturers:Boeing, Airbus, and Embraer specify tier-one fuel system architectures during platform development. These OEMs control design authority and qualification protocols.
- Maintenance Providers:MRO facilities execute airworthiness directive compliance and preventive tank inspections. Heavy check intervals drive recurring bladder and liner replacement demand.
- Defense Contractors:Lockheed Martin, Boeing Defense, and Northrop Grumman integrate fuel systems into weapon system deliveries. Long-term availability contracts structure supplier relationships.
- Aerospace Suppliers:Tier-two and tier-three fabricators produce detail parts and subassemblies under OEM technical direction. Process qualification constraints limit new entrant penetration.
- Charter Operators:High-utilization fleets accelerate wear-related replacement cycles. Operational tempo exceeds scheduled airline patterns.
- Flight Schools:Training aircraft accumulate high cycle counts with minimal tank technology complexity. Cost minimization dominates procurement criteria.
Aircraft manufacturers command design-influence today; maintenance providers are capturing share fastest through fleet aging and aftermarket consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States defense industrial base concentrates the highest density of aircraft fuel tank manufacturing, with Wichita, Kansas and Fort Worth, Texas anchoring tier-one supplier ecosystems around Boeing and Lockheed Martin final assembly lines.
United States
FAA 14 CFR Part 25.963 certification mandates and Pentagon procurement programs drive demand for crash-resistant bladder systems. Military aircraft modernization programs at Wright-Patterson Air Force Base accelerate fuel cell testing protocols. Wichita, Kansas hosts concentrated composite fuel tank fabrication serving Boeing's narrowbody programs.
France
Airbus A320neo and A350 production rates sustain integral tank demand from Toulouse and Hamburg final assembly lines. EASA CS-25 fuel tank safety regulations tighten ignition source prevention requirements for European narrowbody platforms. Safran's vertical integration across thermoset manufacturing controls supply chains from Le Havre facilities.
United Kingdom
BAE Systems' participation in F-35 and Tempest programs sustains conformal tank engineering expertise. UK Ministry of Defence performance-based logistics contracts restructure supplier relationships toward availability-based sustainment. GKN Aerospace's Bristol and Cowes facilities specialize in wing box fuel cavity integration for commercial platforms.
Germany
Airbus Defence and Space military transport programs in Manching drive auxiliary tank requirements for A400M fleets. Germany's KBA enforces aviation equipment certification alignment with EASA standards. Premium AEROTEC's Augsburg and Nordenham plants supply structural fuel tank components to Airbus commercial programs.
Japan
Mitsubishi Heavy Industries' F-X fighter development program creates demand for indigenous conformal fuel cell capabilities. METI's aerospace industry support policies fund composite manufacturing process qualification. Nagoya's aerospace cluster concentrates Toray carbon fiber prepreg supply to regional tier-two fabricators.
Global Aircraft Fuel Tanks Market Competitive Landscape
Global majors compete with regional champions across certification authority and defense program access. The market structures around tier-one integrators with OEM design authority, tier-two specialists with process qualifications, and tier-three component suppliers. Three archetypes dominate: vertically integrated aerostructures divisions, independent fuel system specialists, and diversified industrial conglomerates. Competitive moves concentrate on strategic partnerships for platform design-in and geographic expansion toward Asian narrowbody final assembly lines.
Within the defense-specialist tier, RTX Corporation and Safran exemplify contrasting integration models. Parker Hannifin Corporation anchors aftermarket positioning through distribution network density. These three occupy distinct competitive spaces: RTX represents prime contractor-aligned system development, Safran exemplifies materials-to-systems vertical control, and Parker Hannifin sits within the recurring-revenue aftermarket segment.
| Leading Market Players |
|---|
| Safran |
| RTX Corporation |
| Parker Hannifin Corporation |
| Eaton Corporation |
| GKN Aerospace |
| Collins Aerospace |
| Meggitt PLC |
| Honeywell International Inc. |
| Woodward Inc. |
| Others |
Supply & Pricing Matrix
Tier-one OEM procurement offices at Boeing Wichita and Lockheed Martin Fort Worth anchor contract-based long-term offtake agreements that compress spot-market exposure for composite fuel cell suppliers. Pricing power concentrates with qualified fabricators holding FAA 14 CFR Part 25.963 and EASA CS-25 certifications, while raw material pass-through clauses in aluminum-intensive legacy contracts expose tier-two suppliers to LME volatility.
Pricing Analysis
Input-cost pass-through mechanisms dominate as Toray and Hexcel carbon fiber prepreg allocations flow through to tier-two fabricator quotes. Three-tier pricing structure across crash-resistant military bladder systems, commercial composite integral tanks, and legacy aluminum sustainment parts reflects certification burden and volume scale. Pricing pressure stems from OEM lightweighting mandates squeezing margins on aluminum alloy fabrications. Military procurement offices show least price sensitivity due to survivability specifications, while commercial aftermarket distributors face acute cost compression from charter operator procurement consolidation.
Supply Chain Analysis
Certification gating through FAA 14 CFR Part 25.963 and MIL-STD-889 qualification protocols restricts tier-two entry and concentrates supply among incumbent fabricators. Aerospace-grade carbon fiber prepregs draw from Japan and the United States, with Toray's Nagoya facilities and Hexcel's Salt Lake City operations anchoring regional supply. Aluminum 7075-T6 sheet and titanium fastener interfaces rest on mill capacity in Germany and France. Single-source vulnerability runs through Japanese carbon fiber concentration. Distribution runs through prime contractor-directed supply chains with performance-based logistics contracts unbundling sustainment from new production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as SAF compatibility mandates and crashworthiness specifications shift procurement criteria toward premium-certified architectures. Demand is migrating from commodity aluminum sustainment toward multi-layer barrier systems with self-sealing and lightning protection qualifications.
For Market Incumbents: Lock in long-term performance-based logistics contracts with Pentagon procurement offices before RTX Corporation and Safran consolidate vendor relationships. Deepen backward integration into thermoset resin formulation to offset Toray prepreg allocation constraints. Prioritize out-of-autoclave process qualification to capture EPA National Emission Standards compliance premiums from European narrowbody programs. For New Entrants and Emerging Players: Capture aftermarket bladder replacement demand from aging NATO fighter fleets where incumbent capacity is absorbed by new platform development. Target eVTOL conformal fuel cell geometries as the most penetrable white space, given departure from conventional wing box architectures. Pursue joint qualification pathways with urban air mobility platform developers seeking segmented distributed propulsion tank systems. For Investors and Strategic Acquirers: Aerostructures divisions of diversified industrial conglomerates are the most active acquirer in this space, seeking fuel system capabilities to complement wing box integration franchises. The five-to-ten year viability window favors targets with MIL-STD-889 qualification and SAF compatibility testing infrastructure. Monitor EASA CS-25 ignition source prevention rulemaking as the signal to watch for accelerated composite substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Mold Manufacturing Transition | Resin transfer molding adoption at Italian and Japanese tier-two facilities compresses lead times for crash-resistant bladder systems. |
| SAF Compatibility Qualification | MIL-STD-889 revision pathways force reformulation of tank lining materials and seal architectures across defense fleets. |
| Performance-Based Logistics Contracting | Availability-based sustainment agreements with United States defense contractors unbundle fuel system support from platform-wide programs. |
| Conformal Tank Co-Development | RTX Corporation's prime contractor relationships on fifth-generation fighter programs preserve radar cross-section and aerodynamic efficiency. |
| Aftermarket Distribution Network Expansion | Parker Hannifin Corporation's global bladder replacement infrastructure captures recurring revenue from military fleet aging cycles. |
Research Methodology
Bottom-up platform-level modeling reconciled against top-down supplier capacity tracking forms the analytical core of this study. Primary interviews with fuel system engineering directors, military procurement officers at Wright-Patterson Air Force Base, MRO maintenance planners, and tier-two composite fabricators were validated against secondary sources including FAA airworthiness directive filings, EASA certification databases, Pentagon budget justification documents, and aerospace trade customs records. Triangulation across these channels ensures segmentation integrity across integral, bladder, and conformal tank architectures.
Input-output matrices linking carbon fiber prepreg supply from Toray and Hexcel to tier-two fabricator output capacity drive volume projections across the analysis window. Segmentation dimensions include tank type, material technology, application platform, and end-user channel, with CAGRs derived from production rate trajectories at Boeing Wichita and Airbus Toulouse. Industry-specific forecast inputs capture NATO fighter replacement cycles and eVTOL platform development timelines.
Underlying measurement precision varies by segment; military bladder tank procurement with disclosed program budgets carries tighter precision than emerging eVTOL conformal tank forecasts. Projections reflect assumptions regarding FAA and EASA certification timeline friction and raw material allocation constraints. A model refresh is warranted upon material change in MIL-STD-889 SAF compatibility requirements or Toray carbon fiber capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Military Jet Fuel Market