
 Asia-Pacific Aviation Fuel Market | 2026-2036
Asia-Pacific Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aviation Fuel Market Outlook
Low-cost carriers is bifurcating from full-service airlines as the dominant buyer archetype across the Asia-Pacific Aviation Fuel Market. Royal Dutch Shell Plc leverages its integrated supply chain to dominate bunkering at Singapore Changi and Hong Kong International Airport. Bharat Petroleum Corp Ltd anchors India's government-backed refinery expansion program, while Petronas Aviation Sdn Bhd specializes in Malaysian domestic route coverage with dedicated pipeline infrastructure.
Asia-Pacific aviation fuel comprises refined petroleum products—primarily Jet A-1 kerosene with freeze point below minus 47 degrees Celsius and flash point minimum of 38 degrees Celsius—manufactured through hydrocracking and hydrotreating of crude oil fractions for gas turbine propulsion in commercial and military aircraft. Jet A-1 maintains structural leadership across product types due to universal turbine compatibility and established airport infrastructure, while biofuels represent the fastest-growing segment as airlines commit to net-zero carbon targets. Commercial aviation commands the largest application share, though cargo transport segments attract premium pricing during peak e-commerce fulfillment cycles.
China's MIIT enforces GB standards for aviation fuel quality and blending ratios, while India's CEA coordinates refinery output allocation under national energy security frameworks. Singapore's national regulator mandates strict storage and handling protocols that shape regional logistics investment patterns. Stakeholders must monitor SAF certification timelines and bilateral sustainable fuel agreements between ASEAN member states to secure offtake positions before infrastructure bottlenecks emerge.
Market Dynamics
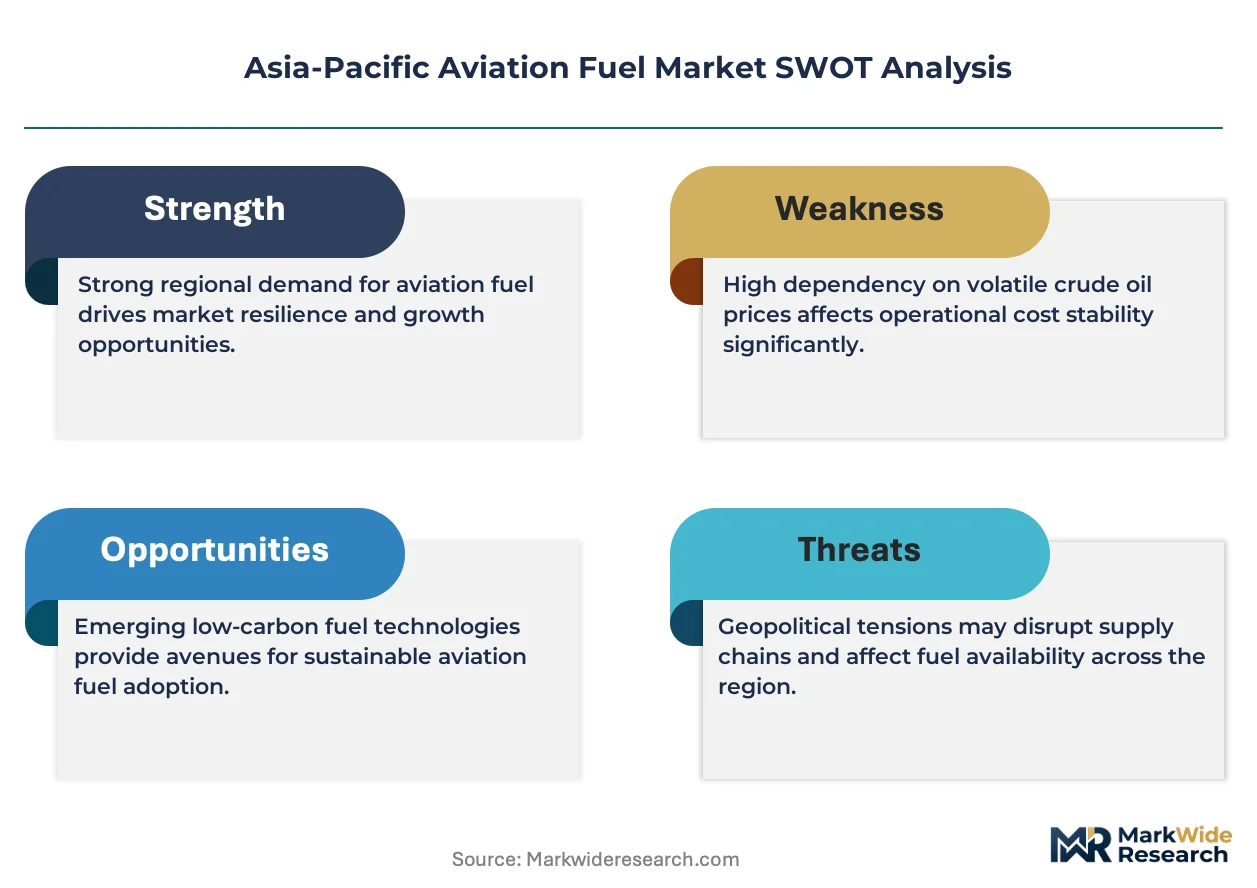
China's dual carbon goals and India's PLI scheme for alternative fuels are forcing a structural pivot across the Asia-Pacific Aviation Fuel Market, as SAF blending mandates reconfigure refinery investment priorities and airline procurement contracts.
Growth Catalysts
- SAF Blending Mandates:China's MIIT enforces escalating biofuel content requirements under national carbon neutrality targets, compelling state-owned refiners to retool hydrocracking units for sustainable feedstock processing.
- Fleet Expansion:Low-cost carriers across Indonesia, Vietnam, and the Philippines are doubling narrow-body aircraft orders, creating concentrated demand spikes at regional hub airports.
- Pipeline Infrastructure:Dedicated aviation fuel pipelines at Kuala Lumpur International Airport and Singapore Changi eliminate trucking bottlenecks and reduce contamination risk for Jet A-1 deliveries.
Market Restraints
- Crude Price Volatility:Jet kerosene crack spreads track Dubai crude benchmarks with minimal hedge protection for Asian refiners, compressing margin visibility for independent fuel suppliers.
- Refinery Concentration:Pertamina's Cilacap complex and Shell's Singapore refinery account for disproportionate regional Jet A-1 output, creating single-point vulnerability during unplanned maintenance cycles.
- Feedstock Competition:Used cooking oil and agricultural residues face competing offtake from road transport biodiesel programs, limiting SAF scale-up velocity.
Strategic Opportunities
- Vietnam Market Entry:Van Don International Airport and Long Thanh International Airport lack dedicated aviation fuel storage, creating first-mover advantage for infrastructure investors.
- Power-to-Liquid Pathways:Electrofuel synthesis combining green hydrogen and captured CO2 offers zero-carbon Jet A-1 alternatives for airlines with science-based net-zero commitments.
- ASEAN SAF Certification Harmonization:Bilateral sustainable fuel agreements between member states under the ASEAN Energy Cooperation Action Plan streamline cross-border offtake contracting.
Industry Challenges
- ASTM D7566 Certification Timelines:Novel SAF production pathways face multi-year approval processes, delaying commercial deployment of alcohol-to-jet and gasification technologies.
- Legacy Fuel System Compatibility:Existing airport hydrant infrastructure requires material compatibility testing for high-blend SAF concentrations, constraining rapid rollout at secondary airports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aviation Fuel Market |
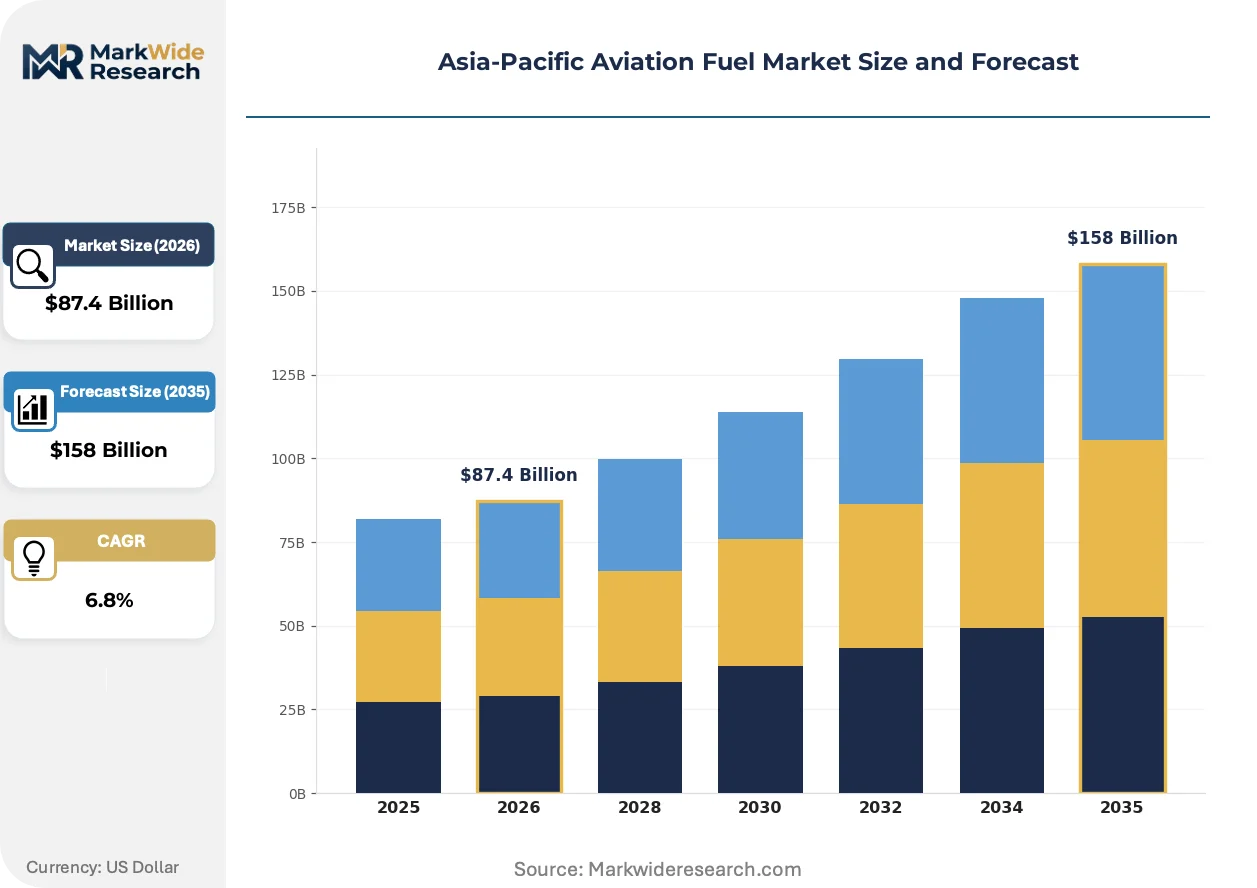
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aviation Gasoline, Jet A-1, Jet B, Biofuels Application: Commercial Aviation, Military Aviation, Cargo Transport, General Aviation Distribution Channel: Direct Sales, Retail Outlets, Online Sales, B2B Sales End User: Airlines, Charter Operators, Cargo Freighters, Private Owners |
| Companies Covered | Pertamina Persero PT, Chevron Corporation, Bharat Petroleum Corp Ltd, BP plc, Royal Dutch Shell Plc, China Aviation Oil Corporation Ltd, Indian Oil Corporation Limited, Exxon Mobil Corporation, Petronas Aviation Sdn Bhd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aviation Fuel Market Strategic Shifts
Digital fuel management platforms and molecular tagging technologies are compressing quality assurance cycles while SAF co-processing retrofits reshape refinery capital allocation across the region.
Hydroprocessed esters and fatty acids (HEFA) technology converts waste oils and animal fats into drop-in Jet A-1 substitutes with identical performance specifications. Full-service carriers including Singapore Airlines and Cathay Pacific have committed to 10% SAF blends by 2030, though supply constraints limit actual uptake. The technology stack is bifurcating between HEFA dominance through 2028 and emerging power-to-liquid alternatives for post-2030 carbon neutrality pathways.
India's CEA coordinates mandatory refinery output allocation under national energy security frameworks, prioritizing aviation fuel stockpiles over export-oriented products during supply disruptions. This intervention compresses spot market liquidity and forces airlines into longer-term offtake contracts with Bharat Petroleum and Indian Oil Corporation. Domestic route operators face the tightest procurement constraints, while international carriers maintain flexibility through Singapore bunkering alternatives.
Airlines are consolidating fuel procurement through joint purchasing consortiums rather than individual carrier negotiations with refiners. The Airlines for Australia and New Zealand (A4ANZ) fuel buying group aggregates demand from Qantas, Virgin Australia, Air New Zealand and regional affiliates, extracting volume discounts and standardizing sustainability certification requirements. This concentration is most visible in Australia, where the consortium handles over half of total aviation fuel purchases and has begun mandating SAF disclosure in supplier RFPs.
Asia-Pacific Aviation Fuel Market Segmentation
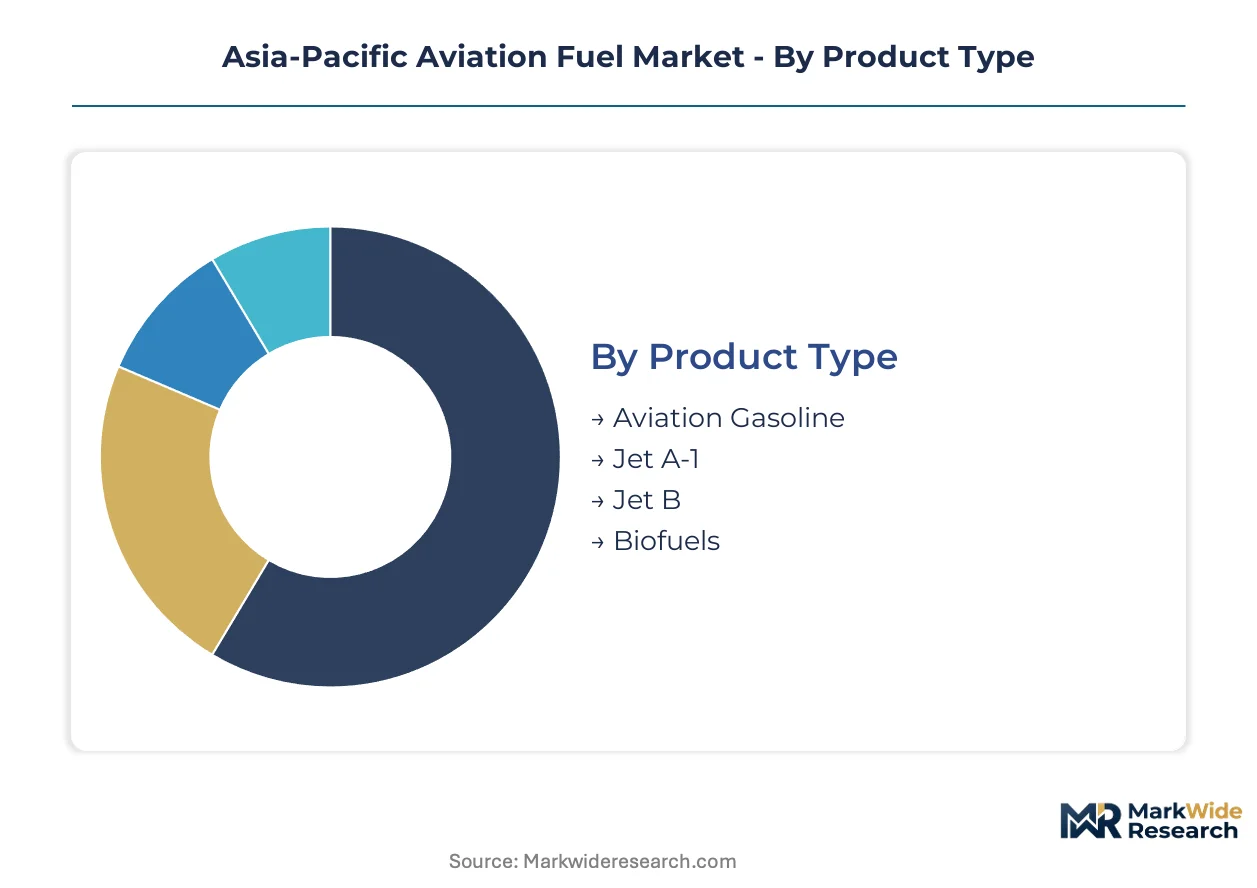
Asia-Pacific aviation fuel segmentation reflects divergent regulatory pressures across MIIT-mandated SAF pathways and CEA-coordinated stockpile priorities. Refinery investment and airline procurement contracts align with specific product specifications and end-use certification requirements rather than uniform commodity trading.
Product Type:
China's MIIT enforces GB standards that differentiate kerosene grades by freeze point and flash point thresholds, while India's CEA coordinates refinery allocation prioritizing military-grade specifications during supply disruptions.
- Jet A-1:Refined kerosene with freeze point below minus 47 degrees Celsius and flash point minimum of 38 degrees Celsius, manufactured through hydrocracking and hydrotreating of crude oil fractions. Demand concentrates at Singapore Changi and Hong Kong International Airport where Shell's integrated supply chain dominates bunkering operations for full-service and low-cost carriers alike.
- Biofuels:Hydroprocessed esters and fatty acids (HEFA) technology converts waste oils and animal fats into drop-in substitutes with identical performance specifications to conventional Jet A-1. Adoption accelerates fastest in China under dual carbon goals and India's PLI scheme for alternative fuels, though feedstock competition from road transport biodiesel constrains scale-up velocity.
- Aviation Gasoline:High-octane fuel for piston-engine aircraft with lower volume throughput than turbine fuels.
- Jet B:Wide-cut naphtha-kerosene blend for cold climate operations with higher volatility specifications.
Established volume favors Jet A-1; emerging adoption favors Biofuels.
Application:
Cost tier differentiation separates scheduled services with long-term offtake contracts from ad-hoc procurement for non-scheduled operations.
- Commercial Aviation:Scheduled passenger services by full-service and low-cost carriers consuming the majority of regional Jet A-1 throughput. Fleet expansion across Indonesia, Vietnam, and the Philippines generates concentrated demand spikes at hub airports where pipeline infrastructure eliminates trucking bottlenecks.
- Cargo Transport:Dedicated freighter operations and belly-hold cargo attracting premium pricing during peak e-commerce fulfillment cycles. Operators at Kuala Lumpur International Airport leverage dedicated aviation fuel pipelines to reduce contamination risk for time-sensitive pharmaceutical and electronics shipments.
- Military Aviation:Defense procurement with specialized quality assurance protocols and strategic stockpile requirements.
- General Aviation:Private and business aviation with fragmented demand across secondary airports lacking hydrant infrastructure.
Commercial Aviation commands procurement scale; Cargo Transport captures margin expansion during peak cycles.
Distribution Channel:
Supply concentration shapes channel selection, with direct refinery relationships favored by volume buyers and retail outlets serving fragmented demand.
- B2B Sales:Consolidated procurement through joint purchasing consortiums such as Airlines for Australia and New Zealand aggregating demand from Qantas, Virgin Australia, and Air New Zealand. This concentration handles over half of Australian aviation fuel purchases and mandates SAF disclosure in supplier RFPs.
- Direct Sales:Long-term offtake contracts between airlines and state-owned refiners including Bharat Petroleum and Indian Oil Corporation under CEA-coordinated allocation frameworks.
- Retail Outlets:Fixed-base operators and smaller airports without dedicated pipeline connections.
- Online Sales:Digital fuel management platforms for general aviation and charter operators with variable scheduling patterns.
B2B Sales consolidates procurement power; Direct Sales locks in supply security.
End User:
Customer type determines contract structure, with flag carriers negotiating multi-year offtake agreements and private owners purchasing on spot terms.
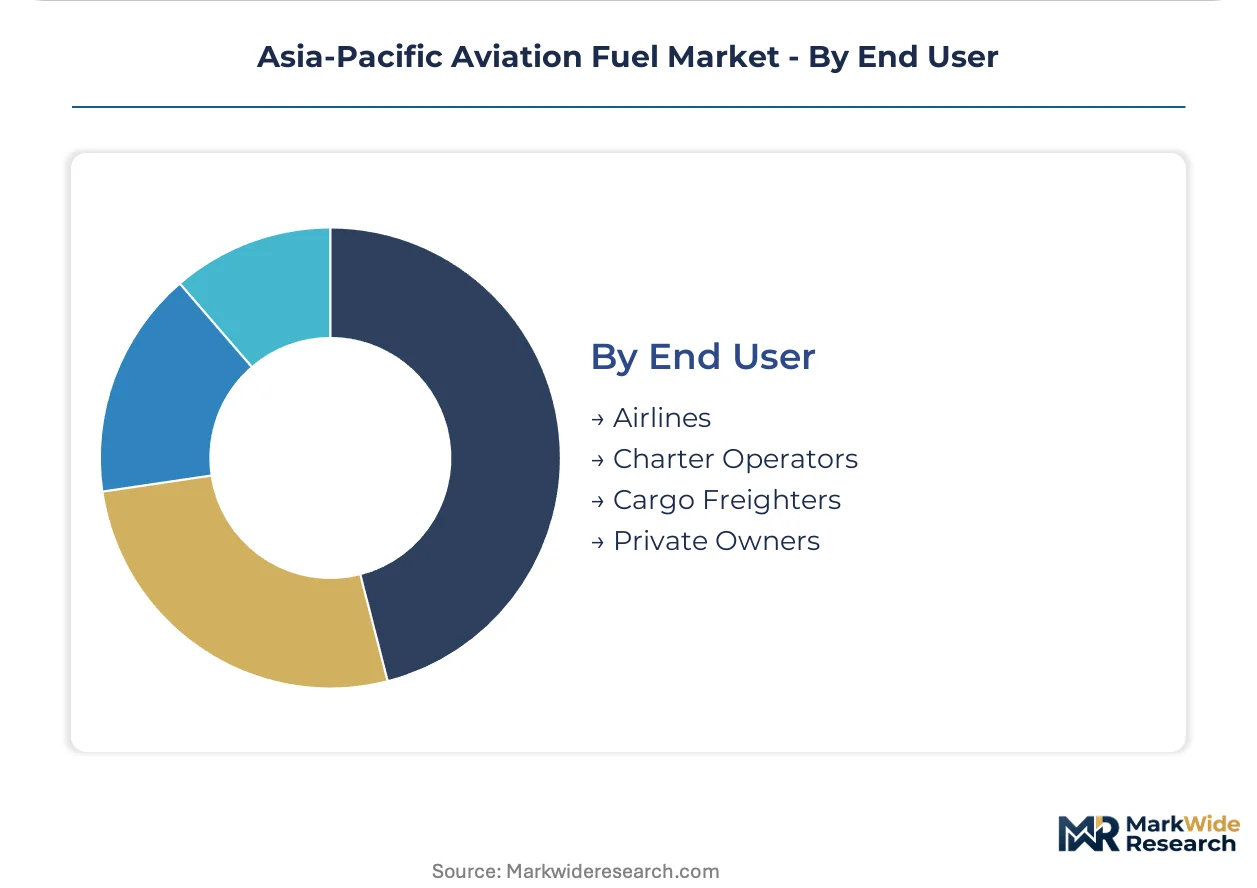
- Airlines:Full-service carriers including Singapore Airlines and Cathay Pacific committing to 10% SAF blends, constrained by ASTM D7566 certification timelines for novel production pathways. Low-cost carriers across Southeast Asia expand narrow-body orders, forcing longer-term contracting to secure volume.
- Cargo Freighters:Dedicated operators with premium pricing tolerance and specialized storage requirements at major hubs.
- Charter Operators:Non-scheduled services with variable demand patterns and limited bargaining power.
- Private Owners:General aviation with small-batch procurement and highest per-unit logistics costs.
Airlines anchor volume contracting; Cargo Freighters extract priority service premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore exports refined Jet A-1 to airlines across Southeast Asia, with Shell's Singapore refinery feeding bunkering operations at Changi Airport for carriers operating intra-regional routes.
China
MIIT enforces escalating SAF blending mandates under dual carbon goals, forcing Sinopec and PetroChina to retool hydrocracking units for sustainable feedstock processing. GB standards differentiate kerosene grades by freeze point and flash point thresholds. Yangtze River Delta refineries supply Shanghai Pudong and Beijing Capital airports where state-owned carriers anchor procurement volumes.
India
CEA coordinates mandatory refinery output allocation prioritizing aviation fuel stockpiles over export-oriented products during supply disruptions. PLI scheme for alternative fuels accelerates HEFA pathway investments. Mumbai and Delhi-NCR concentrate demand where Bharat Petroleum and Indian Oil Corporation lock airlines into longer-term offtake contracts.
Indonesia
Pertamina's Cilacap complex accounts for disproportionate regional Jet A-1 output, creating single-point vulnerability during unplanned maintenance cycles. Lion Air and Garuda Indonesia expand narrow-body orders, forcing concentrated demand spikes at Soekarno-Hatta International Airport. Jakarta anchors procurement scale for low-cost carrier fleet expansion.
Singapore
The national regulator mandates strict storage and handling protocols that shape regional logistics investment patterns. Shell dominates bunkering operations at Changi Airport through integrated supply chain control. Singapore Changi and Seletar Airport infrastructure eliminates trucking bottlenecks for Jet A-1 deliveries to full-service and low-cost carriers alike.
Vietnam
VietJet and Bamboo Airways double aircraft orders without matching aviation fuel storage infrastructure at Van Don International Airport or Long Thanh International Airport. This gap creates first-mover advantage for infrastructure investors. Ho Chi Minh City and Hanoi concentrate demand where pipeline absence forces continued trucking dependence.
Asia-Pacific Aviation Fuel Market Competitive Environment
Player mix skews toward state-owned refiners with integrated pipeline infrastructure. Concentration is pronounced at the refining tier, where national oil companies control disproportionate regional Jet A-1 output. Two strategic archetypes dominate: integrated energy majors with airport bunkering networks, and state-backed refiners with government-mandated allocation authority. Competitive moves center on SAF co-processing retrofits and strategic pipeline investments at greenfield airport developments.
Within the integrated energy major tier, Royal Dutch Shell Plc and BP plc exemplify players with airport-specific supply chain control. Among state-backed refiners, Pertamina Persero PT and Bharat Petroleum Corp Ltd occupy positions shaped by government allocation frameworks and domestic route coverage mandates. Petronas Aviation Sdn Bhd sits within the specialized aviation subsidiary archetype, with dedicated pipeline infrastructure at Kuala Lumpur International Airport representing a distinct competitive position.
| Leading Market Players |
|---|
| Pertamina Persero PT |
| Chevron Corporation |
| Bharat Petroleum Corp Ltd |
| BP plc |
| Royal Dutch Shell Plc |
| China Aviation Oil Corporation Ltd |
| Indian Oil Corporation Limited |
| Exxon Mobil Corporation |
| Petronas Aviation Sdn Bhd |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty days of forward inventory coverage at Singapore Changi and Hong Kong International Airport anchors pricing power for integrated suppliers, compressing spot market liquidity for independent buyers while amplifying contract premiums during supply disruptions. This lead-time band concentrates procurement leverage with Shell and state-backed refiners who control dedicated pipeline infrastructure.
Pricing Analysis
Conventional Jet A-1 versus HEFA biofuel versus power-to-liquid electrofuels stratifies pricing across three technology generations. Contract-based long-term offtake dominates commercial aviation, with price differentiation driven by SAF certification tier and volume scale commitments. Pricing pressure stems from crude volatility tracking Dubai benchmarks, compressing margins for non-integrated suppliers. Low-cost carriers exhibit highest price sensitivity through consolidated consortium buying, while cargo freighters tolerate premium tiers for priority delivery guarantees.
Supply Chain Analysis
Singapore, Indonesia, and India anchor regional Jet A-1 production through Shell's Pulau Bukom refinery, Pertamina's Cilacap complex, and Bharat Petroleum's Mumbai facilities. Crude feedstock draws from Middle Eastern sour grades and Australian sweet crudes, with hydrocracking catalysts and specialized additives resting on limited supplier bases. Single-source vulnerability concentrates at Pertamina's Cilacap complex, where unplanned maintenance triggers regional allocation constraints. Distribution runs through dedicated aviation fuel pipelines at Kuala Lumpur International Airport and Singapore Changi, eliminating trucking contamination risks for hub airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SAF co-processing expertise and ASTM D7566 certification velocity represent the binding capability gaps, with incumbents hoarding technical talent and new entrants struggling to secure feedstock offtake positions before infrastructure bottlenecks harden.
For Market Incumbents: Shield market position by accelerating HEFA retrofit investments at Cilacap and Pulau Bukom ahead of MIIT-mandated blending escalations. Deepen backward integration into used cooking oil collection networks across Indonesia and Malaysia to secure feedstock priority over road transport biodiesel competitors. Lock cargo freighters into premium-tier contracts before Vietnam's greenfield airports attract alternative suppliers.
For New Entrants and Emerging Players: Secondary airport fuel storage gaps at Van Don International Airport and Long Thanh International Airport offer first-mover infrastructure plays outside incumbent pipeline networks. Target Vietnam's unmet demand through mobile storage and trucking solutions while permanent hydrant systems remain unbuilt. Pursue joint venture structures with VietJet and Bamboo Airways to anchor volume commitments during fleet expansion cycles.
For Investors and Strategic Acquirers: Long-term, this sits as a regulated utility play because SAF mandates convert refining capacity into contracted revenue streams with airline offtake guarantees. Acquisition candidates center on mid-scale HEFA technology holders with pending ASTM D7566 approvals. Watch SAF certification timeline accelerations as the inflection signal for valuation step-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Co-Processing Retrofit | MIIT blending mandates force Sinopec and PetroChina to reconfigure hydrocracking units for sustainable feedstock. |
| Pipeline Infrastructure Expansion | Dedicated aviation fuel lines at Kuala Lumpur International Airport eliminate contamination risk for pharmaceutical cargo. |
| Feedstock Backward Integration | Used cooking oil collection networks in Indonesia secure priority over road transport biodiesel competitors. |
| Joint Purchasing Consortium | Airlines for Australia and New Zealand aggregates Qantas and Virgin Australia demand for volume discounts. |
| Greenfield Storage Investment | Van Don International Airport lacks dedicated aviation fuel infrastructure, creating first-mover advantage. |
Study Parameters
A spread of perspectives from refinery operations managers, airline procurement directors, airport fuel services coordinators, and CEA allocation officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through MIIT GB standard filings, CEA output allocation directives, Pertamina operational disclosures, and Shell Singapore refinery throughput data. Bottom-up volume estimates from individual airport throughput statistics triangulated against top-down refinery production allocations across the analysis window.
Segmentation dimensions modeled include fuel product type, application tier, distribution channel structure, and end-user contract archetype across the projection horizon. CAGRs derived from historical throughput growth rates adjusted for fleet expansion schedules and SAF mandate implementation curves. Forecast inputs incorporated narrow-body aircraft delivery timelines, hydrocracking unit retrofit capex cycles, and bilateral SAF certification agreements under ASEAN Energy Cooperation frameworks.
Forecasts assume regulatory continuity in China's MIIT enforcement patterns and India's CEA allocation frameworks; material policy shifts would require re-modeling. Recalibration cycles align with material shifts in ASTM D7566 certification approvals, greenfield airport commissioning schedules, and feedstock competition from road transport biodiesel programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aviation Fluid Market