
 Military Jet Fuel Market | 2026-2036
Military Jet Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Military Jet Fuel Market Foresight
Synthetic paraffinic kerosene is rebalancing cost structures as militaries blend renewable feedstocks into conventional JP-8 and Jet A-1 specifications. BP PLC leverages its integrated refining network to sustain long-term defense supply agreements across multiple NATO airbases. Chevron Corporation anchors its position through proprietary hydroprocessing technology that meets stringent military flash-point requirements. Exxon Mobil Corporation dominates bulk procurement contracts via direct pipeline access to strategic petroleum reserves.
Military jet fuel denotes kerosene-based aviation turbine fuel formulated to military specifications, with JP-8 containing corrosion inhibitors, icing inhibitors, and static dissipater additives to ensure operational reliability from minus 47 degrees Celsius upward; its primary purpose is to power high-performance turbine engines across tactical and strategic airframes under extreme operational conditions. Fuel type segmentation shows JP-8 retaining the largest volume share due to its NATO standardization, while synthetic and alternative fuel variants represent the fastest-growing subcategory as defense ministries impose carbon intensity benchmarks. Application segmentation reveals unmanned aerial systems as the emerging demand vector, with drone fleets consuming specialized high-density fuels that differ from manned aircraft requirements.
The U.S. Defense Logistics Agency Energy, NATO's Single Fuel Concept, and the EU Green Deal's sustainable aviation fuel mandates collectively shape product formulation, procurement eligibility, and cross-border logistics protocols for military suppliers. ASTM D7566 and DEF STAN 91-91 certification requirements force refiners to maintain dual production lines for conventional and synthetic grades. Stakeholders must monitor how evolving carbon accounting rules and alternative fuel certification pathways alter contract qualification criteria and long-term offtake agreements.
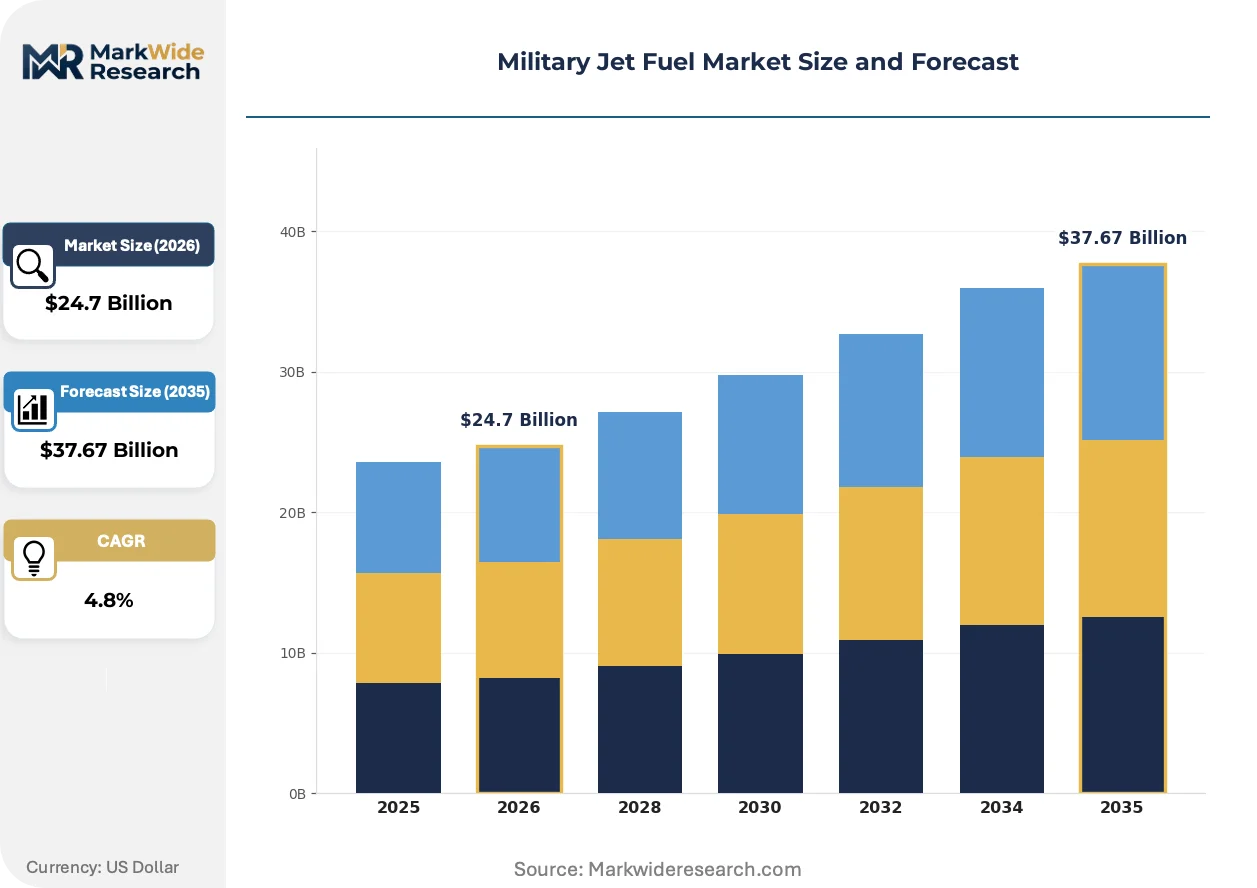
Market Dynamics
The U.S. Department of Defense's sustainable aviation fuel mandates under the Energy Independence and Security Act are compressing supplier qualification timelines while NATO's Single Fuel Concept locks in JP-8 standardization across allied airforces, creating simultaneous pull toward alternative feedstocks and resistance to specification divergence.
Growth Catalysts
- NATO Single Fuel Concept:Standardization around JP-8 specifications eliminates cross-border logistics friction and enables pooled procurement across member airforces, reducing unit costs for bulk offtake agreements.
- Unmanned aerial systems expansion:Defense procurement agencies are fielding drone fleets requiring high-density specialized fuels, opening new formulation contracts distinct from manned aircraft supply.
- EU Green Deal sustainable aviation fuel mandates:Carbon intensity benchmarks for military applications are accelerating synthetic paraffinic kerosene blending trials and alternative certification pathways.
Market Restraints
- Crude-linked feedstock volatility:Conventional jet fuel production remains tethered to petroleum price swings, compressing margin predictability for refiners maintaining dual conventional and synthetic production lines.
- Strategic petroleum reserve access concentration:Bulk procurement advantages cluster with suppliers holding direct pipeline infrastructure to U.S. federal reserves, limiting new entrant scale.
- ASTM D7566 certification complexity:Synthetic fuel approval pathways require extensive testing protocols that extend qualification timelines and elevate R&D fixed costs for alternative feedstock developers.
Strategic Opportunities
- Aerial refueling fleet modernization:Tanker aircraft procurement programs across NATO member states are expanding demand for high-reliability fuel with extended storage stability requirements.
- Biomass-to-liquid technology convergence:Integration of Fischer-Tropsch synthesis with agricultural waste processing is opening domestic feedstock security advantages for national defense fuel strategies.
- Defense logistics agency energy contracting reform:Long-term offtake agreement structures are shifting toward performance-based specifications that reward carbon intensity reductions alongside traditional operational metrics.
Industry Challenges
- DEF STAN 91-91 compliance timeline compression:Dual certification maintenance for conventional and synthetic grades strains quality assurance staffing and laboratory throughput at mid-scale refiners.
- Legacy additive package integration:Corrosion inhibitors, icing inhibitors, and static dissipater additives formulated for petroleum-derived JP-8 require reformulation validation when blended with synthetic paraffinic kerosene, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Jet Fuel Market |
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $37.67 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: JP-5, JP-8, Jet A-1, TS-1 Application: Combat Vehicles, Aircraft, Drones, Naval Operations End User: Military Branches, Government Contractors, Defense Manufacturers, Aerospace Agencies Distribution Channel: Direct Supply, Retail, B2B Distribution, Logistics Providers |
| Companies Covered | BP PLC, Chevron Corporation, Exxon Mobil Corporation, Royal Dutch Shell PLC, TotalEnergies, Honeywell International Inc, GS Caltex Corporation, Repsol SA, Hess Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Jet Fuel Market Shifts & Advancements
Synthetic paraffinic kerosene production pathways are compressing the cost gap with conventional refining while defense ministries impose operational carbon accounting. Three developments are restructuring supplier positioning and procurement specifications.
Hydroprocessed esters and fatty acids (HEFA) technology is consolidating as the dominant renewable pathway for military jet fuel applications. The U.S. Air Force Material Command has accelerated HEFA-SPK blending trials from laboratory validation to operational fleet testing. This consolidation is compressing competing thermochemical and biological conversion routes into niche demonstration status rather than scaled supply.
The EU Green Deal's sustainable aviation fuel mandates are forcing defense procurement agencies to embed carbon intensity thresholds into contract eligibility criteria. Refiners serving NATO airbases must now document lifecycle emissions across feedstock cultivation through combustion. European suppliers are responding by securing certified sustainable biomass chains and investing in mass-balance tracking infrastructure.
Defense buyers are unbundling fuel procurement from integrated logistics support contracts, creating discrete commodity markets for jet fuel separate from storage, handling, and quality assurance services. The U.S. Defense Logistics Agency Energy has piloted this separation in continental U.S. supply regions. This shift is most visible in Germany and the United Kingdom, where NATO airbases are negotiating standalone fuel supply agreements with multiple qualified refiners.
Military Jet Fuel Market Segmentation
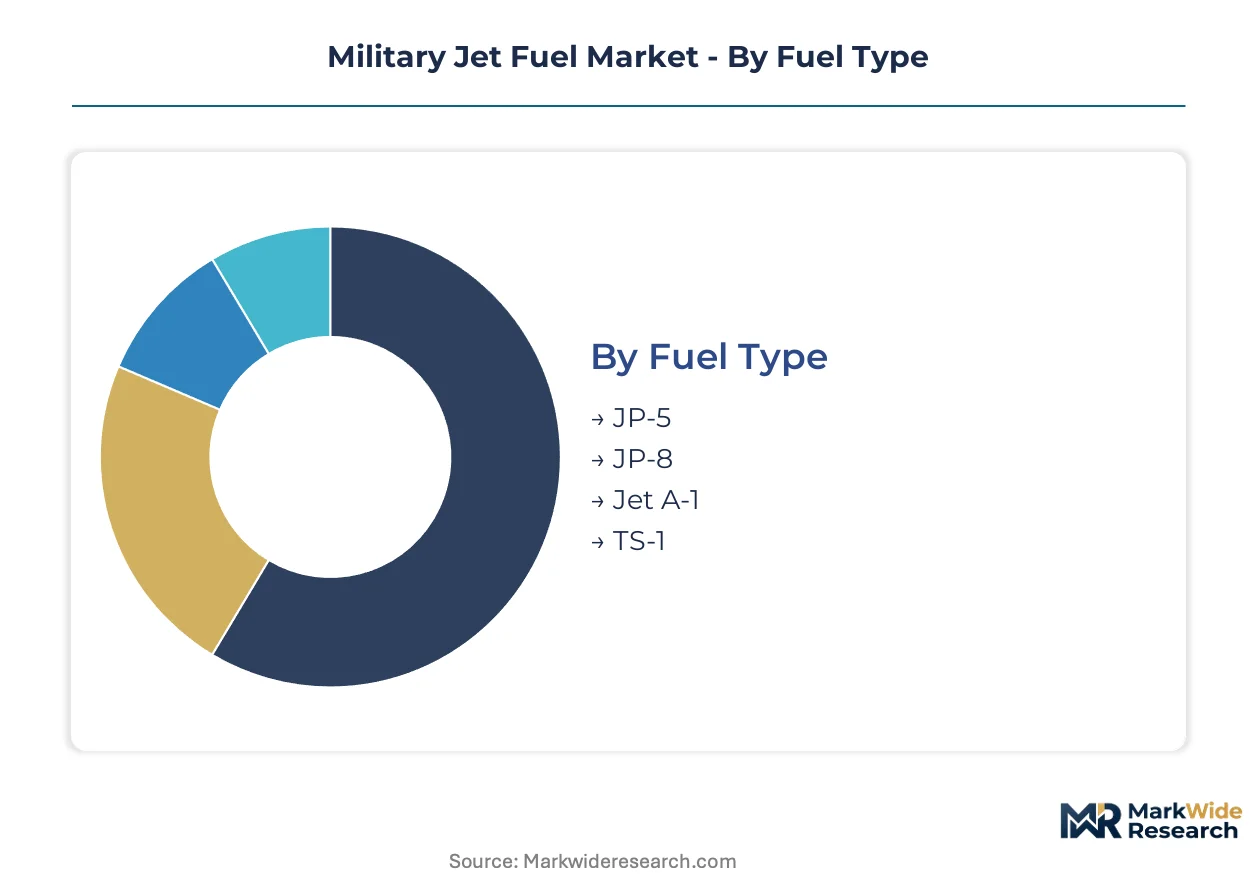
Military jet fuel procurement operates through rigid specification hierarchies where fuel chemistry determines operational compatibility across diverse airframe and engine combinations. Segmentation reveals how defense buyers balance NATO standardization mandates against emerging unmanned platform requirements and sustainability transitions.
Fuel Type:
Supply concentration clusters around NATO-aligned specifications with established additive packages and certified production infrastructure.
- JP-8:Kerosene-based formulation containing corrosion inhibitors, icing inhibitors, and static dissipater additives for operational reliability from minus 47 degrees Celsius upward. The U.S. Air Force Material Command manages the single largest procurement program globally, locking in volume commitments across continental U.S. and European NATO airbases. NATO's Single Fuel Concept cements JP-8 as the alliance-wide standard, eliminating cross-border logistics friction for pooled procurement.
- Jet A-1:Civil aviation-grade kerosene meeting DEF STAN 91-91 and ASTM D1655 specifications, increasingly blended with synthetic paraffinic kerosene under EU Green Deal mandates. Demand concentrates in European defense ministries embedding carbon intensity benchmarks into contract eligibility, with refiners maintaining dual conventional and synthetic production lines to maintain qualification.
- JP-5:High-flash-point formulation specified for naval carrier operations where fire safety requirements exceed land-based thresholds.
- TS-1:Russian-origin specification retained in former Soviet-aligned defense forces with distinct freezing point and sulfur content parameters.
Today's leader: JP-8. Tomorrow's challenger: Jet A-1.
Application:
Cost tier differentiation separates high-volume manned aircraft supply from specialized drone fuel formulations commanding premium qualification overhead.
- Aircraft:Manned tactical and strategic airframes consuming bulk volumes under long-term offtake agreements with direct pipeline access to strategic petroleum reserves. The U.S. Defense Logistics Agency Energy anchors demand through centralized procurement, while NATO aerial refueling fleet modernization expands high-reliability fuel requirements with extended storage stability specifications.
- Drones:Unmanned aerial systems requiring high-density specialized fuels distinct from manned aircraft formulations, with defense procurement agencies fielding drone fleets under discrete commodity contracts unbundled from integrated logistics support. EU Green Deal carbon accounting rules accelerate synthetic paraffinic kerosene blending trials for unmanned platforms.
- Combat Vehicles:Ground-based turbine powerplants in armored formations utilizing JP-8 interchangeability with aviation assets under single-fuel logistics doctrines.
- Naval Operations:Maritime turbine propulsion systems specifying JP-5 for carrier-based aviation and surface combatant compatibility.
Aircraft dominate procurement volumes. Drones are gaining share fastest.
End User:
Customer type determines contract structure complexity, from sovereign military procurement to subcontractor tiering under prime defense manufacturer agreements.
- Military Branches:Sovereign air forces, navies, and armies operating centralized fuel depots with direct government-to-refiner contracting authority under national defense fuel strategies.
- Government Contractors:Private sector logistics specialists managing storage, handling, and quality assurance services as discrete markets separate from fuel commodity supply.
- Defense Manufacturers:Original equipment producers requiring test fuel volumes for engine certification and airframe integration programs.
- Aerospace Agencies:Research and development establishments conducting alternative fuel certification pathways under ASTM D7566 protocols.
Military branches control volume. Government contractors are capturing service-layer margin.
Distribution Channel:
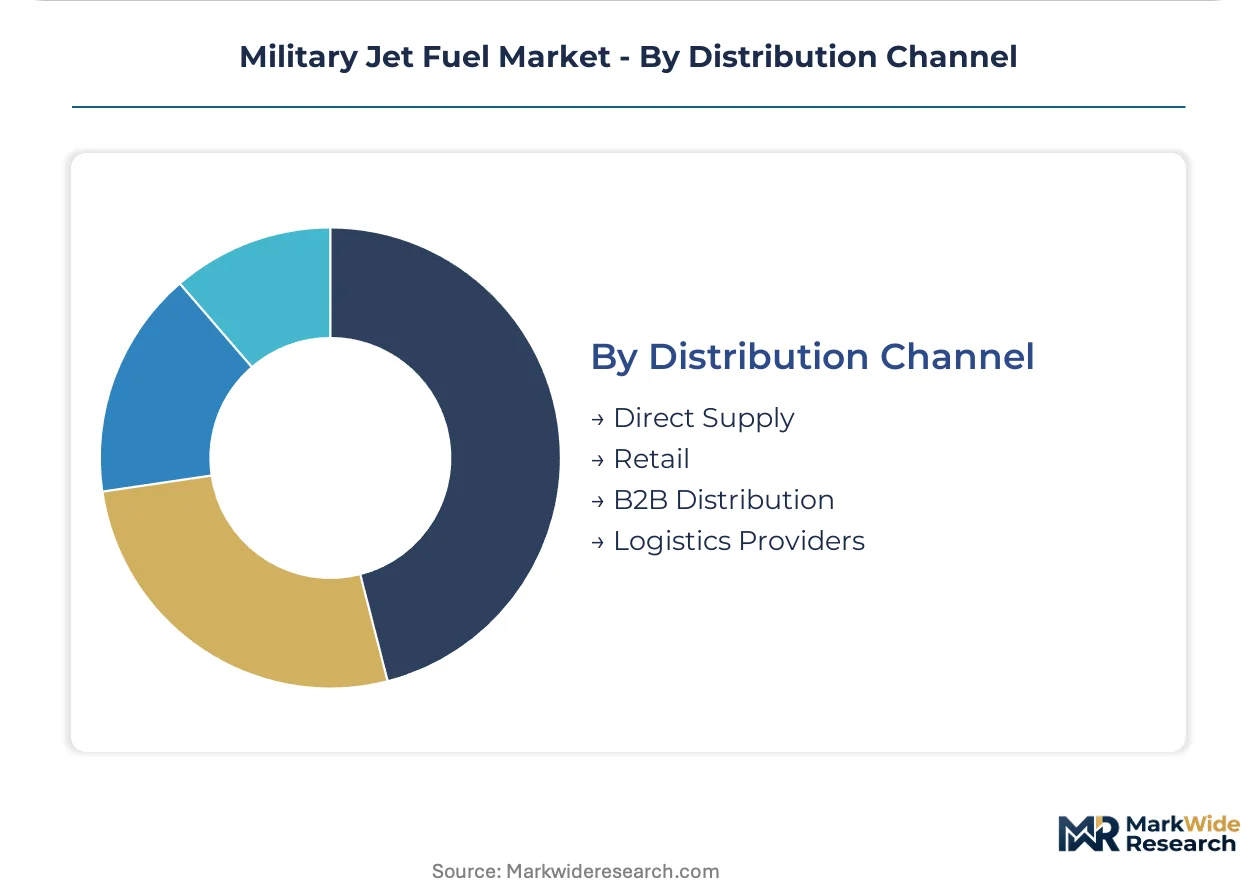
Margin structure varies by channel depth, with direct supply capturing value through infrastructure ownership and B2B distribution layering qualification overhead.
- Direct Supply:Refiner-to-military depot relationships leveraging proprietary pipeline access to strategic petroleum reserves, compressing intermediary costs for bulk offtake agreements.
- Logistics Providers:Specialized handlers managing NATO cross-border movements with mass-balance tracking infrastructure for sustainable aviation fuel documentation.
- B2B Distribution:Midstream aggregators serving defense manufacturers and aerospace agencies with smaller batch requirements and extended qualification timelines.
- Retail:Limited commercial access points for reserve and training operations outside sovereign procurement frameworks.
Direct supply holds volume concentration. Logistics providers are expanding with sustainability tracking mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Air Force Material Command manages the single largest military jet fuel procurement program worldwide, anchoring demand concentration in North America while NATO standardization drives procurement patterns across European allied airbases.
United States
The U.S. Department of Defense's sustainable aviation fuel mandates under the Energy Independence and Security Act are compressing supplier qualification timelines for conventional and synthetic blend stocks. Defense Logistics Agency Energy contracting reform is shifting long-term offtake agreements toward performance-based specifications that reward carbon intensity reductions. Refineries along the Gulf Coast maintain direct pipeline access to strategic petroleum reserves, securing bulk procurement advantages for JP-8 supply to continental airbases.
Germany
NATO's Single Fuel Concept locks in JP-8 standardization across Luftwaffe operations while EU Green Deal mandates accelerate synthetic paraffinic kerosene blending trials. The country's national defense fuel strategy prioritizes domestic feedstock security through biomass-to-liquid technology convergence. Refining clusters in North Rhine-Westphalia are investing in mass-balance tracking infrastructure to document lifecycle emissions for military contract eligibility.
United Kingdom
Royal Air Force aerial refueling fleet modernization is expanding demand for high-reliability fuel with extended storage stability requirements under DEF STAN 91-91 certification. Ministry of Defence procurement is unbundling fuel supply from integrated logistics support contracts, creating discrete commodity markets separate from handling services. Industrial concentrations around Grangemouth and Fawley are maintaining dual production lines for conventional and synthetic Jet A-1 grades.
France
Direction Générale de l'Armement is embedding carbon intensity benchmarks into jet fuel contract eligibility criteria alongside traditional operational metrics. The EU Green Deal's sustainable aviation fuel mandates are forcing defense procurement agencies to secure certified sustainable biomass chains for military applications. Refining infrastructure near Le Havre and Fos-sur-Mer is consolidating hydroprocessed esters and fatty acids capacity for NATO airbase supply.
Japan
Ministry of Defense unmanned aerial systems expansion is opening formulation contracts for high-density specialized fuels distinct from manned aircraft requirements. METI is coordinating with the U.S. Air Force Material Command on alternative fuel certification pathways under ASTM D7566 protocols. Industrial clusters in Chiba and Yokkaichi are developing Fischer-Tropsch synthesis integration with domestic agricultural waste processing for defense fuel security.
Military Jet Fuel Market Competitive Landscape
Global majors compete with regional champions across refinery scale and strategic petroleum reserve access, producing a tiered structure where integrated oil corporations hold bulk procurement advantages and mid-scale refiners specialize in dual-certification maintenance. The vendor base clusters around three archetypes: pipeline-connected integrated refiners capturing direct supply contracts, technology licensors monetizing proprietary hydroprocessing capabilities, and regional blenders serving unbundled logistics markets. Dominant competitive moves include backward integration into biomass feedstock cultivation and capacity expansion for synthetic paraffinic kerosene production lines.
Within the integrated refiner tier, BP PLC and Exxon Mobil Corporation exemplify archetypes differentiated by infrastructure ownership and geographic positioning. BP PLC leverages its integrated refining network to sustain long-term defense supply agreements across multiple NATO airbases. Exxon Mobil Corporation anchors its competitive position through direct pipeline access to U.S. strategic petroleum reserves, securing volume concentration in the world's largest military jet fuel procurement program. Chevron Corporation occupies a technology-differentiated position through proprietary hydroprocessing capabilities that meet stringent military flash-point requirements.
| Leading Market Players |
|---|
| BP PLC |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Royal Dutch Shell PLC |
| TotalEnergies |
| Honeywell International Inc |
| GS Caltex Corporation |
| Repsol SA |
| Hess Corporation |
| Others |
Supply & Pricing Matrix
Hydroprocessed esters and fatty acids technology diffusion is compressing production cost differentials between conventional petroleum refining and synthetic paraffinic kerosene pathways, simultaneously redistributing margin capture toward feedstock controllers and concentrating supply influence among refiners with dual-certification infrastructure.
Pricing Analysis
Crude-linked feedstock volatility passes through to JP-8 contract rates with 3-6 month lag structures, while synthetic blend stocks command premium-mid-economy pricing differentiation based on carbon intensity certification tiers. ASTM D7566 qualification overhead elevates R&D fixed costs for alternative pathway developers, compressing their margin buffers against petroleum price swings. Government contractors exhibit highest price sensitivity due to unbundled logistics procurement, whereas sovereign military branches absorb cost premiums for strategic petroleum reserve access security.
Supply Chain Analysis
Regional distribution centers cluster around NATO airbase networks in Germany, the United Kingdom, and the United States, with hub-and-spoke patterns radiating from Gulf Coast refining corridors and North Rhine-Westphalia industrial zones. Feedstock supply draws from conventional crude pipelines, agricultural waste biomass clusters, and certified sustainable palm oil derivatives. Single-source vulnerability concentrates in strategic petroleum reserve access rights held by integrated majors. Distribution runs through direct refiner-to-depot pipelines for bulk volumes, supplemented by specialized NATO cross-border logistics handlers for sustainable aviation fuel mass-balance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Military jet fuel functions as a stable compounder anchored by NATO's Single Fuel Concept standardization, which locks in recurring procurement volumes across allied defense ministries regardless of crude price cycles.
For Market Incumbents: Anticipate synthetic paraffinic kerosene qualification timeline compression by pre-investing in ASTM D7566 dual-certification laboratory throughput before EU Green Deal carbon intensity mandates harden contract eligibility. Secure backward integration into certified sustainable biomass chains to defend margin position against feedstock cost pass-through volatility. Prioritize aerial refueling fleet modernization contracts with extended storage stability specifications as the highest-margin demand vector. For New Entrants and Emerging Players: Begin with unmanned aerial systems fuel formulations as the most penetrable white-space segment, where defense procurement agencies field discrete commodity contracts unbundled from integrated logistics support. Target government contractor service layers in Germany and the United Kingdom where NATO airbases negotiate standalone fuel supply agreements. Pursue Fischer-Tropsch synthesis technology licensing as the go-to-market angle for national defense fuel security positioning in Japan and Pacific allied states. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale refiners maintaining dual conventional and synthetic production lines with existing DEF STAN 91-91 infrastructure but lacking direct strategic petroleum reserve pipeline access. Long-term viability across the analysis window hinges on carbon intensity reduction capabilities embedded in contract performance metrics. Watch for Defense Logistics Agency Energy contracting reform signals shifting toward performance-based specifications as the inflection indicator for synthetic fuel offtake acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | ASTM D7566 and DEF STAN 91-91 parallel qualification secures NATO contract eligibility across conventional and synthetic fuel procurement cycles. |
| Biomass Feedstock Backward Integration | Captive agricultural waste processing under EU Green Deal mandates locks in carbon intensity documentation for military contract performance tiers. |
| Aerial Refueling Fleet Supply Agreement | High-reliability fuel contracts with extended storage stability specifications capture premium margins from NATO tanker modernization programs. |
| Unmanned Systems Fuel Formulation Development | Specialized high-density fuel R&D opens discrete commodity markets separate from manned aircraft bulk procurement. |
| Mass-Balance Tracking Infrastructure Investment | Lifecycle emissions documentation systems satisfy EU Green Deal sustainable aviation fuel mandates for NATO cross-border logistics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with refinery operations directors, Defense Logistics Agency Energy contracting officers, NATO fuel logistics coordinators, and sustainable aviation fuel certification specialists with secondary validation from EIA petroleum supply data, NATO standardization directives, EU Green Deal implementation documents, and ASTM D7566 certification pathway records. Bottom-up fuel type demand modeling triangulated against top-down defense budget allocation analysis.
Segment-weighting approaches distributed volume and value projections across fuel type categories, application segments, end-user contracting structures, and distribution channel tiers throughout the forecast period. CAGRs derived from historical procurement volume trajectories, aerial refueling fleet modernization schedules, unmanned aerial systems deployment timelines, and synthetic paraffinic kerosene blending mandate phase-ins. Industry-specific inputs included NATO Single Fuel Concept compliance rates, strategic petroleum reserve drawdown patterns, and HEFA-SPK production cost convergence curves.
Several conditions sit outside the modeled scope, including geopolitical supply disruptions affecting strategic petroleum reserve access, breakthrough thermochemical conversion technologies displacing Fischer-Tropsch pathways, and unilateral NATO member state withdrawals from collective procurement frameworks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aircraft Exhaust System Market