
 Aviation Refueling Market | 2026-2036
Aviation Refueling Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Refueling Market Outlook
ReFuelEU Aviation is rebalancing the cost-of-entry calculus for European suppliers by mandating progressive sustainable aviation fuel blending quotas. Shell plc leverages its integrated refining and biofuel production network to secure early compliance positioning. TotalEnergies SE anchors its strategy through dedicated SAF manufacturing partnerships across France and the Netherlands. Neste Corporation specializes in renewable diesel and SAF pathways, giving it differentiated feedstock access that competitors struggle to replicate.
Aviation refueling encompasses the storage, distribution, and transfer of aviation turbine fuels to aircraft, operating through hydrant systems or mobile dispensers with flow rates typically exceeding 3,000 liters per minute for wide-body jets. The process demands strict adherence to cleanliness standards such as ASTM D1655 and DEF STAN 91-091 to prevent fuel contamination that could disable jet engines during flight. Jet A-1 dominates commercial applications due to its freeze point of minus 47 degrees Celsius, while biofuels represent the fastest-growing fuel type as airlines face mounting pressure to reduce lifecycle carbon emissions. Commercial aviation absorbs the largest volume share among applications, though cargo operations are gaining structural importance from e-commerce-driven freighter fleet expansion.
The US Environmental Protection Agency and Federal Aviation Administration jointly enforce emissions standards and operational safety protocols that shape refueling infrastructure investments at American airports. Europes REACH regulation and F-Gas Regulation compound compliance burdens by restricting certain chemical additives and pressurized transfer equipment. Stakeholders must monitor how divergent national SAF mandates across the United States, European Union, and India reshape procurement patterns and supplier qualification requirements without assuming harmonized timelines.
Market Dynamics
The EU Green Deal's ReFuelEU Aviation mandate is forcing fuel suppliers to reconfigure blending infrastructure ahead of progressively tightening sustainable aviation fuel quotas, compressing the timeline for capital deployment across European airport networks.
Growth Catalysts
- Post-pandemic fleet renewal:Commercial airlines across Southeast Asia are accelerating aircraft deliveries to capture recovering passenger volumes, directly expanding hydrant system and mobile dispenser requirements at major hubs.
- ReFuelEU Aviation blending mandates:The regulation's progressive SAF quotas are compelling fuel suppliers to invest in co-processing and standalone renewable fuel production capacity.
- Military modernization programs:India's defense infrastructure expansion is driving dedicated refueling capacity buildouts at strategic airfields and forward operating bases.
Market Restraints
- Feedstock cost volatility:Used cooking oil and agricultural residue prices fluctuate with food commodity markets, squeezing SAF production economics independent of crude oil benchmarks.
- European supply concentration:Neste Corporation controls disproportionate renewable diesel and SAF pathway capacity, creating single-source dependency for blenders seeking compliance.
- ASTM D1655 cleanliness standards:The specification's particulate and water content limits impose filtration and testing infrastructure costs that smaller regional airports struggle to absorb.
Strategic Opportunities
- Indian airport infrastructure expansion:Greenfield developments at Navi Mumbai and Jewar are specifying hydrant systems with future SAF compatibility during initial construction.
- Co-processing technology convergence:Petroleum refiners are retrofitting fluid catalytic crackers and hydrocrackers to handle lipid feedstocks alongside conventional crude fractions.
- US Inflation Reduction Act credits:The IRA's clean fuel production tax credits are incentivizing domestic SAF manufacturing investments independent of state-level mandates.
Industry Challenges
- Hydrant system integration complexity:Retrofitting existing underground fueling networks for SAF compatibility requires extended downtime at capacity-constrained airports.
- DEF STAN 91-091 certification timelines:Military fuel specifications demand extensive qualification testing that delays new biofuel pathway approvals by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Refueling Market |
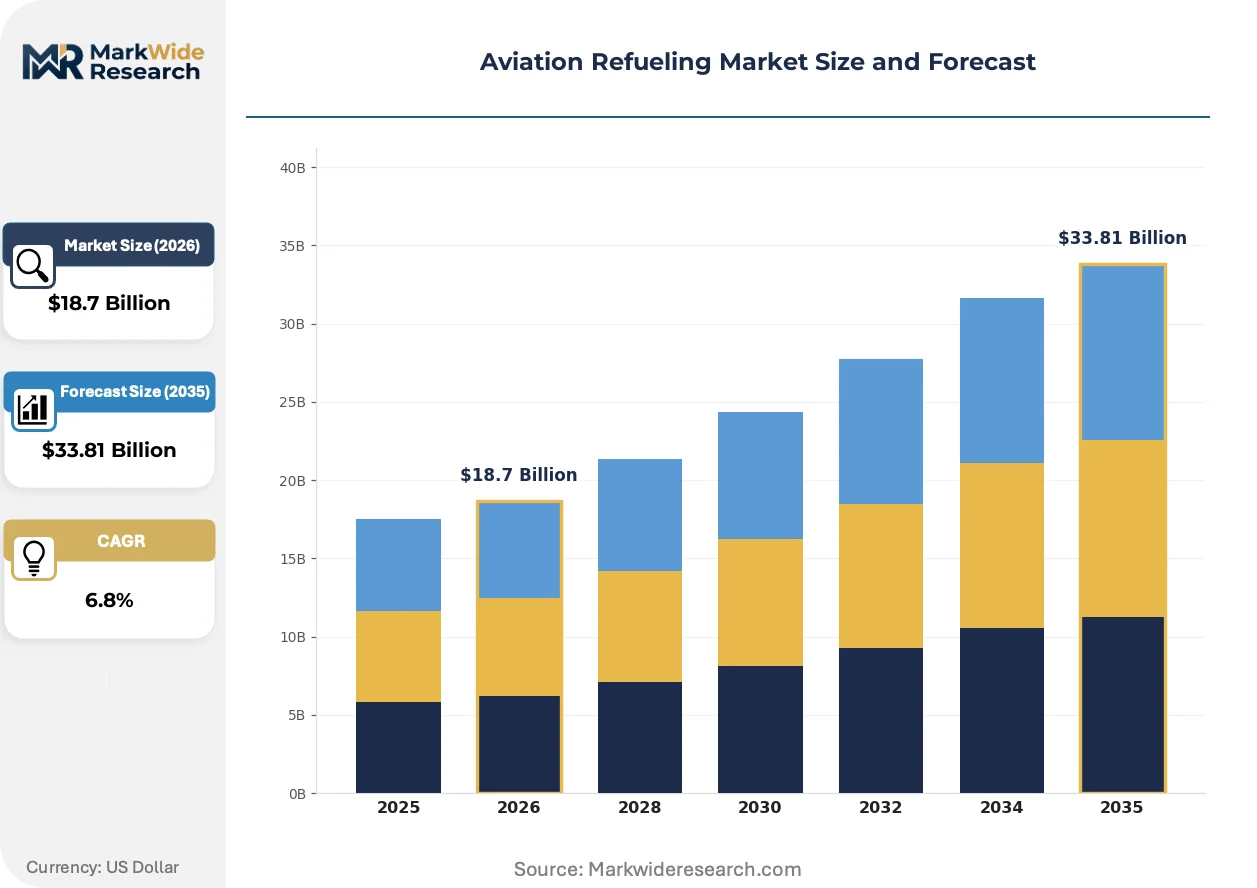
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Avgas, Biofuels Application: Commercial Aviation, Military Aviation, General Aviation, Cargo Distribution Channel: Direct Supply, Pipeline, On-Route Delivery, Fuel Tanks End User: Airlines, Private Operators, Government Agencies, Airport Authorities |
| Companies Covered | TotalEnergies SE, Phillips 66, ExxonMobil Corporation, Marathon Petroleum Corporation, Valero Energy Corporation, Shell plc, Chevron Corporation, Neste Corporation, BP plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Refueling Market Strategic Shifts
Digital fuel management systems and alternative feedstock pathways are converging to reshape how aviation turbine fuel is tracked, blended, and delivered across airport ecosystems.
Automated hydrant dispensers equipped with real-time density measurement and electronic fuel ticketing are rewriting ground handling economics. Major hub airports in Germany and the Netherlands are deploying these systems to compress turnaround times for wide-body fleets. The technology is enabling precision blending of conventional Jet A-1 with SAF batches while maintaining custody transfer accuracy.
The EU F-Gas Regulation is pressuring suppliers to eliminate hydrofluorocarbon-based leak detection systems from refueling equipment. European airports must transition to infrared or ultrasonic alternatives by specified phase-out dates. This regulatory friction is accelerating capital replacement cycles for aging hydrant infrastructure ahead of technical obsolescence.
Cargo carriers are unbundling fuel procurement from ground handling contracts to negotiate direct offtake agreements with SAF producers. This disintermediation is visible at Luxembourg and Anchorage hubs where dedicated freighter operators seek supply security independent of passenger airline fuel pools. The model is compressing traditional supplier-aggregator relationships in air freight corridors.
Aviation Refueling Market Segmentation
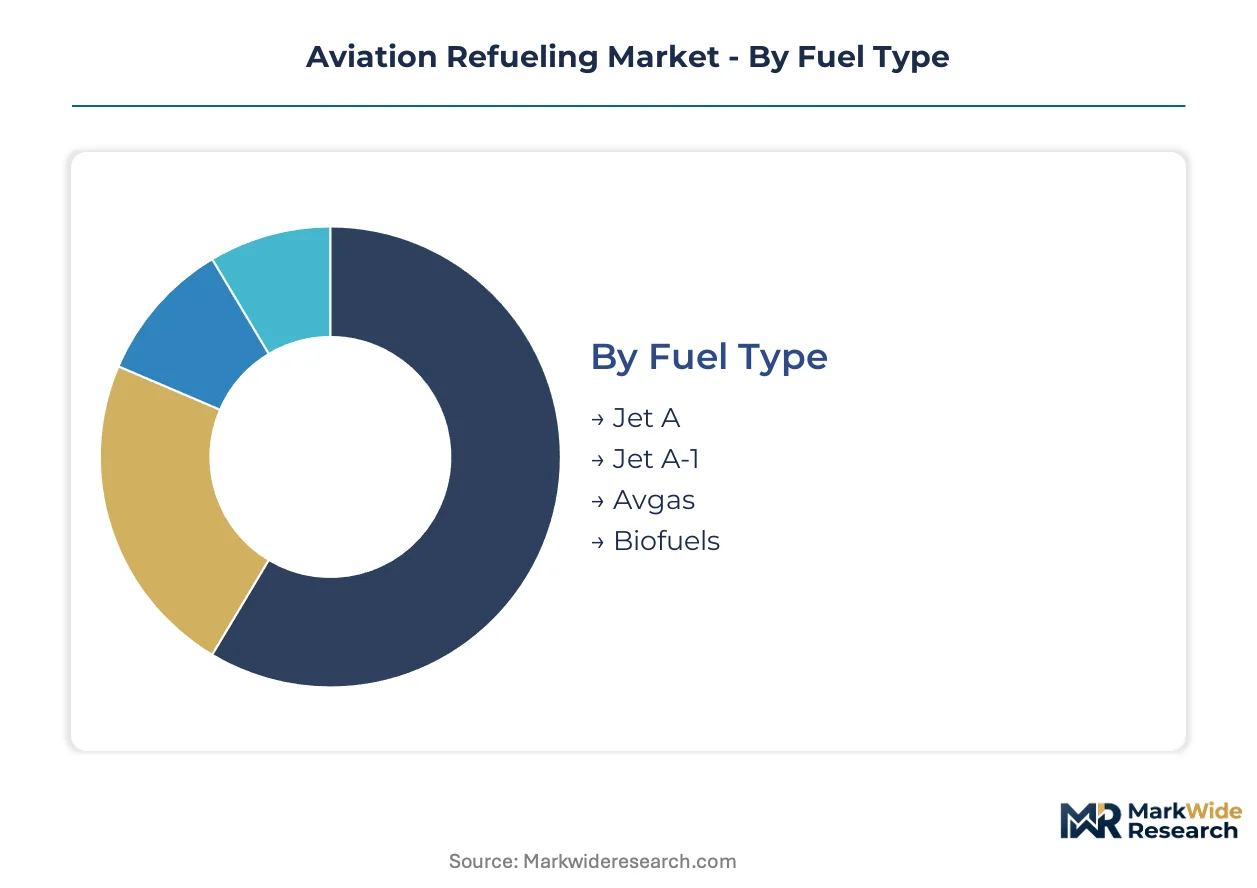
Segmentation in aviation refueling reveals how fuel specifications, operational requirements, and procurement channels create distinct commercial territories. Each category maps to different infrastructure investments, regulatory compliance burdens, and margin structures across airport ecosystems.
Fuel Type:
Supply concentration in conventional jet fuel refining creates pricing leverage for integrated petroleum majors, while biofuel pathways remain fragmented across renewable diesel specialists and agricultural processors.
- Jet A:Formulated with a freeze point of minus 40 degrees Celsius, this kerosene-grade fuel serves primarily domestic US commercial routes where extreme cold weather performance is less critical. Demand concentrates at Dallas-Fort Worth and Atlanta hubs where Delta Air Lines and American Airlines maintain massive connecting operations dependent on high-volume, rapid-turn fueling infrastructure.
- Jet A-1:The international standard specification with a minus 47 degrees Celsius freeze point dominates long-haul operations crossing polar and high-altitude corridors. European and Asian carriers at Frankfurt, Singapore Changi, and Dubai International specify this grade exclusively for intercontinental fleet compatibility, driving hydrant system standardization across major hubs.
- Avgas:High-octane aviation gasoline for piston-engine aircraft contains tetraethyl lead additives that ECHA's REACH regulation is progressively restricting across EU member states.
- Biofuels:Hydrotreated esters and fatty acids (HEFA) pathways from Neste and World Energy supply the bulk of certified sustainable aviation fuel to airlines meeting ReFuelEU Aviation blending mandates.
Jet A-1 absorbs the bulk of installed capacity; biofuels are expanding most quickly.
Application:
Operational tempo and fleet scale determine infrastructure requirements, with wide-body commercial operations demanding entirely different fueling architectures than dispersed general aviation movements.
- Commercial Aviation:Scheduled passenger carriers operating narrow-body and wide-body fleets require continuous hydrant system access at gates with flow rates exceeding 3,000 liters per minute. India's airport infrastructure expansion at Navi Mumbai and Jewar specifies these systems with future SAF compatibility during initial construction.
- Cargo:Dedicated freighter operators at Luxembourg Findel and Ted Stevens Anchorage International are unbundling fuel procurement from ground handling contracts to negotiate direct offtake agreements with SAF producers, compressing traditional supplier-aggregator relationships in air freight corridors.
- Military Aviation:India's defense infrastructure expansion is driving dedicated refueling capacity buildouts at strategic airfields and forward operating bases under military modernization programs.
- General Aviation:Business jets and private piston aircraft rely on mobile dispensers and fixed-base operator fuel farms rather than underground hydrant networks.
Commercial aviation commands the largest volume flows; cargo is climbing the fastest as e-commerce reshapes freighter fleet planning.
Distribution Channel:
Capital intensity and custody transfer requirements segment suppliers by their ability to own and operate physical fuel infrastructure versus broker third-party access.
- Pipeline:Dedicated aviation fuel pipelines from refineries to airport storage terminals offer lowest unit logistics costs but require decades-long offtake commitments that only major hub airports can underwrite.
- Direct Supply:Integrated oil majors leverage backward integration into refining to deliver Jet A-1 and SAF blends directly to airline fuel farms, capturing margin across the value chain.
- On-Route Delivery:Into-plane agents coordinate last-mile dispensing through hydrant carts or refueler trucks, handling custody transfer documentation and quality testing.
- Fuel Tanks:Airport-owned or third-party leased storage tanks provide buffer inventory against supply disruptions, with EPA and FAA jointly enforcing emissions standards and operational safety protocols that shape infrastructure investments at American airports.
Pipeline networks anchor high-volume hub economics; on-route delivery is gaining share fastest among mid-tier airports avoiding capital-intensive infrastructure.
End User:
Procurement scale and counterparty creditworthiness determine contract structures, with sovereign-backed entities accessing fundamentally different terms than privately held operators.
- Airlines:Network carriers negotiate multi-year fuel supply agreements indexed to Platts jet fuel benchmarks, with SAF offtake clauses increasingly mandatory under EU Green Deal compliance frameworks.
- Government Agencies:Military and state aviation departments procure through defense fuel supply centers with DEF STAN 91-091 certification requirements that delay new biofuel pathway approvals by 18-24 months.
- Airport Authorities:Infrastructure owners specify hydrant system technical standards and grant into-plane concessions to competing fuel suppliers.
- Private Operators:Corporate flight departments and fractional ownership programs purchase through fixed-base operators at list-plus pricing without volume discounts.
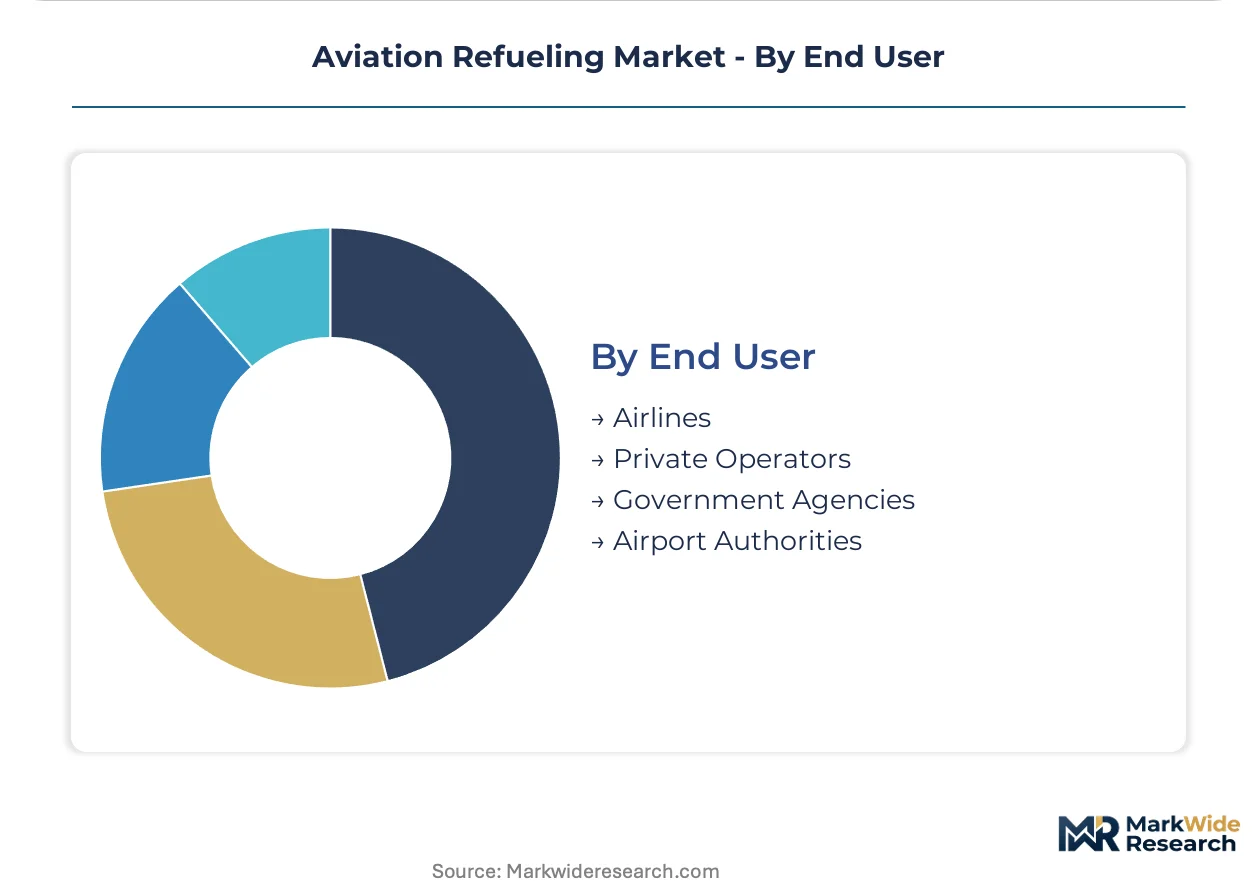
Airlines absorb the bulk of jet fuel procurement volume; government agencies are expanding fastest as defense modernization accelerates across India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's clean fuel production tax credits are concentrating SAF manufacturing investments in Louisiana and Texas corridor refineries, pulling capital toward Gulf Coast hydrogen hubs and carbon capture infrastructure.
United States
Domestic carriers at Dallas-Fort Worth and Atlanta hubs are expanding hydrant capacity to accommodate post-pandemic fleet renewals. The EPA and FAA jointly enforce emissions standards that shape refueling infrastructure investments at American airports. Houston's refining corridor anchors Jet A-1 supply security for transcontinental operations.
Germany
Frankfurt and Munich airports are deploying automated hydrant dispensers with real-time density measurement to compress wide-body turnaround times. The EU F-Gas Regulation is pressuring elimination of hydrofluorocarbon-based leak detection systems from refueling equipment. The Rhine-Main industrial cluster hosts co-processing retrofit investments at petroleum refineries handling lipid feedstocks.
India
Commercial airlines are accelerating aircraft deliveries to capture recovering passenger volumes across Delhi and Mumbai hubs. Military modernization programs are driving dedicated refueling capacity buildouts at strategic airfields under defense infrastructure expansion. Greenfield developments at Navi Mumbai and Jewar specify hydrant systems with future SAF compatibility during initial construction.
Singapore
Changi Airport's cargo operations are gaining structural importance from e-commerce-driven freighter fleet expansion across Southeast Asian trade lanes. The country's national aviation regulator enforces strict adherence to ASTM D1655 cleanliness standards for fuel contamination prevention. The Jurong Island petrochemical cluster supplies Jet A-1 to regional carriers operating polar and high-altitude corridors.
Netherlands
Amsterdam Schiphol is unbundling fuel procurement from ground handling contracts as cargo carriers negotiate direct SAF offtake agreements. The ReFuelEU Aviation mandate is compelling fuel suppliers to invest in co-processing and standalone renewable fuel production capacity. The Rotterdam port-industrial complex anchors pipeline distribution networks delivering aviation turbine fuel to Northwest European hubs.
Aviation Refueling Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across aviation refueling, creating a tiered structure where integrated oil majors capture margin across the value chain while renewable diesel specialists dominate SAF pathway supply. The market exhibits supply concentration in conventional jet fuel refining alongside fragmentation in biofuel feedstock processing. Three archetypes prevail: backward-integrated petroleum majors with captive refining, renewable fuel specialists with differentiated feedstock access, and regional into-plane agents coordinating last-mile dispensing. Competitive intensity centers on co-processing technology licensing and strategic partnerships for SAF manufacturing capacity.
Within the integrated petroleum major tier, Shell plc and TotalEnergies SE exemplify backward-integrated positioning through refining and biofuel production networks, while Neste Corporation occupies a distinct position as a renewable diesel and SAF pathway specialist with feedstock advantages that competitors struggle to replicate.
| Leading Market Players |
|---|
| TotalEnergies SE |
| Phillips 66 |
| ExxonMobil Corporation |
| Marathon Petroleum Corporation |
| Valero Energy Corporation |
| Shell plc |
| Chevron Corporation |
| Neste Corporation |
| BP plc |
| Others |
Value Chain & Pricing Dynamics
Network carriers negotiating multi-year fuel supply agreements indexed to Platts jet fuel benchmarks dominate procurement volume, anchoring contract-based long-term offtake as the prevailing pricing structure across airport ecosystems. Their counterparty creditworthiness and scale concentrate pricing power with integrated petroleum majors capable of underwriting decades-long infrastructure commitments.
Pricing Analysis
Short lead-time premiums for spot SAF batches command substantial markups over scheduled contract deliveries as airlines scramble to meet ReFuelEU Aviation blending mandates ahead of compliance deadlines. Price differentiation hinges on certification grade under ASTM D7566 and volume scale, with major hub carriers locking in fixed-price clauses while regional operators absorb volatile spot premiums. Cost compression in conventional Jet A-1 is intensifying because petroleum refiners are sacrificing margin to retain airline offtake commitments against SAF substitution. Cargo carriers unbundling fuel procurement from ground handling contracts prove least price-sensitive, absorbing premium SAF costs to secure supply security independent of passenger airline fuel pools.
Supply Chain Analysis
Maritime freight costs from Singapore and Rotterdam refining corridors to Asian and European hub airports constitute a material component of delivered fuel economics, compressing margins for into-plane agents without backward integration into terminal storage. Geographic supply concentrates in the United States, Singapore, and the Netherlands, with the Gulf Coast hydrogen hub corridor and Jurong Island petrochemical cluster anchoring global Jet A-1 production. Raw material dependencies draw from crude oil benchmarks, used cooking oil feedstocks, and agricultural residues whose prices fluctuate with food commodity markets. Single-source vulnerability in HEFA pathway supply from Neste Corporation creates compliance risk for European blenders seeking renewable fuel quotas. Distribution runs through dedicated aviation fuel pipelines, direct supply from integrated majors, and on-route delivery via hydrant carts and refueler trucks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation refueling is becoming a vertical-integration race as petroleum majors retrofit fluid catalytic crackers for lipid co-processing and renewable specialists build captive SAF manufacturing capacity to bypass feedstock bottlenecks.
For Market Incumbents: Deepen backward integration into biofuel feedstock sourcing through dedicated agricultural residue partnerships and used cooking oil collection networks to defend against Neste Corporation's pathway dominance. Secure long-term offtake agreements with Indian military fuel supply centers before DEF STAN 91-091 certification timelines delay competitor approvals by 18-24 months. For New Entrants and Emerging Players: The price-point gap between premium certified-SAF blends and economy-tier conventional Jet A-1 offers entry latitude for mid-tier refiners deploying co-processing retrofits at stranded petroleum assets. Target India's greenfield airport developments at Navi Mumbai and Jewar where hydrant system specifications remain uncommitted and SAF compatibility clauses are being written during initial construction. Lead with modular skid-mounted blending units that minimize capital deployment against integrated majors' infrastructure lock-in. For Investors and Strategic Acquirers: The window for entry favors renewable diesel specialists with differentiated feedstock access and ASTM D7566 certification pathways already secured. Over a five-to-ten-year horizon, acquisition targets should demonstrate secured lipid supply contracts and co-processing technology licenses rather than standalone refinery exposure. Watch for Indian defense infrastructure expansion announcements as the inflection signal indicating accelerated military refueling capacity buildouts at strategic airfields.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Processing Retrofit Investment | Petroleum refiners in the Rhine-Main cluster are retrofitting fluid catalytic crackers to handle lipid feedstocks alongside conventional crude fractions. |
| SAF Manufacturing Partnership | TotalEnergies SE anchors its European compliance positioning through dedicated renewable fuel production capacity across France and the Netherlands. |
| Hydrant System Automation Deployment | Frankfurt and Munich airports deploy automated dispensers with real-time density measurement to compress wide-body turnaround times. |
| Direct Offtake Agreement Negotiation | Cargo carriers at Luxembourg Findel unbundle fuel procurement from ground handling contracts to secure SAF supply independent of passenger airline pools. |
| Feedstock Supply Chain Integration | Shell plc leverages its integrated refining and biofuel production network to secure early ReFuelEU Aviation compliance positioning. |
Study Parameters
Multi-period observation of Platts jet fuel benchmark movements, ReFuelEU Aviation mandate implementation timelines, and Indian defense procurement announcements anchored the trend analysis, supplemented by interviews with fuel supply specialists, airport infrastructure planners, airline procurement directors, and petroleum refinery operations managers. Secondary validation drew from EPA and FAA joint enforcement disclosures, ECHA REACH regulation filings, EU F-Gas Regulation phase-out schedules, and customs data on aviation turbine fuel trade flows. Bottom-up capacity modeling across airport hydrant systems and top-down demand triangulation from airline fleet renewal schedules were cross-referenced for convergence.
Input-output matrices mapped fuel type segmentation against application channels and distribution infrastructure across the projection horizon. Segmentation dimensions modeled included fuel specification grade, operational application, procurement channel structure, and end-user credit tier. CAGRs were derived from elasticity-adjusted demand projections and capacity deployment schedules reported by airport authorities and defense infrastructure agencies. Industry-specific forecast inputs incorporated SAF blending mandate trajectories and military modernization program expenditure patterns.
Inputs from refinery operations disclosures and airport concession agreements were available through the study window; gaps in forward-looking SAF production capacity announcements introduce uncertainty bands around supply-side assumptions. Stakeholders should weight assumptions against their own operating context and monitor regulatory implementation delays that could compress or extend infrastructure investment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aircraft Fuel System Market