
 All-Electric Propulsion Satellites Market | 2026-2036
All-Electric Propulsion Satellites Market Size, Share, and Industry Trends Forecast 2026-2036
All-Electric Propulsion Satellites Market Insights
The EU Green Deal is decoupling satellite procurement from conventional chemical propulsion baselines. Airbus Defence and Space leverages its Toulouse manufacturing base to dominate European electric propulsion integration. Boeing Defense, Space & Security anchors North American demand through classified government programs. Thales Alenia Space competes on dual-use platforms that straddle civilian telecommunications and military resilience mandates.
All-electric propulsion satellites replace chemical thrusters with ionized propellant acceleration systems, typically employing xenon or krypton fed through Hall effect or gridded ion thrusters to achieve specific impulses exceeding 1500 seconds for station-keeping and orbit-raising maneuvers. Small satellites and CubeSats now drive volume demand as constellation operators prioritize mass efficiency over raw thrust, while large satellites sustain premium margins where extended operational lifespans justify higher upfront propulsion costs. Hall effect thrusters lead technology adoption due to proven heritage, though ionic thrusters capture growing share in precision orbit-insertion applications.
EMA's space medicine standards, REACH chemical restrictions on propellant handling, and CE marking for ground support equipment collectively elevate compliance costs for non-European suppliers seeking European commercial access. The US FAA's evolving commercial space launch regulations and FCC orbital debris mitigation rules impose parallel certification burdens on operators serving American government and commercial end users. Stakeholders must monitor how dual-use export control harmonization between European and American frameworks reshapes supply chain geography.
Market Dynamics
The EU Green Deal's emissions-linked procurement criteria are forcing satellite operators to abandon chemical propulsion baselines entirely. This regulatory pressure concentrates manufacturing investment in European electric propulsion hubs while reshaping competitive positioning across the supply chain.
Growth Catalysts
- Xenon-to-krypton thruster transition:Constellation operators are switching propellant chemistry to reduce supply chain exposure to South African xenon concentration. Krypton abundance cuts long-term operating costs for high-count fleets.
- France's Toulouse cluster:Airbus Defence and Space anchors a concentrated supplier ecosystem that accelerates Hall effect thruster integration timelines for European commercial and military platforms.
- FCC orbital debris mitigation rules:US operators face mandatory deorbit timelines that electric propulsion satisfies more efficiently than chemical alternatives, driving platform replacement cycles.
Market Restraints
- Xenon supply concentration:South Africa controls the majority of global xenon extraction, exposing operators to geopolitical supply interruptions and price volatility.
- REACH chemical handling compliance:European propellant ground processing facilities face elevated certification costs that disadvantage non-European suppliers seeking commercial access.
- Extended orbit-raising timelines:Electric propulsion requires months versus days for chemical thrusters, compressing revenue realization windows for time-sensitive missions.
Strategic Opportunities
- Indian constellation deployment:ISRO's commercial arm and private operators represent underpenetrated demand for small electric-propulsion platforms in regional navigation and earth observation networks.
- Dual-use platform standardization:Thales Alenia Space is converging civilian telecommunications architectures with military resilience specifications, opening single-platform procurement across defense and commercial budgets.
- CE marking for ground support equipment:European certification requirements create captive demand for specialized handling infrastructure that integrated manufacturers can capture.
Industry Challenges
- Hall effect thruster plasma physics expertise:The specialized workforce for ionized propellant acceleration system design remains concentrated in Toulouse and Moscow, constraining supplier expansion.
- Multi-year qualification timelines:EMA space medicine standards and FAA commercial launch regulations impose parallel certification tracks that delay new entrant market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | All-Electric Propulsion Satellites Market |
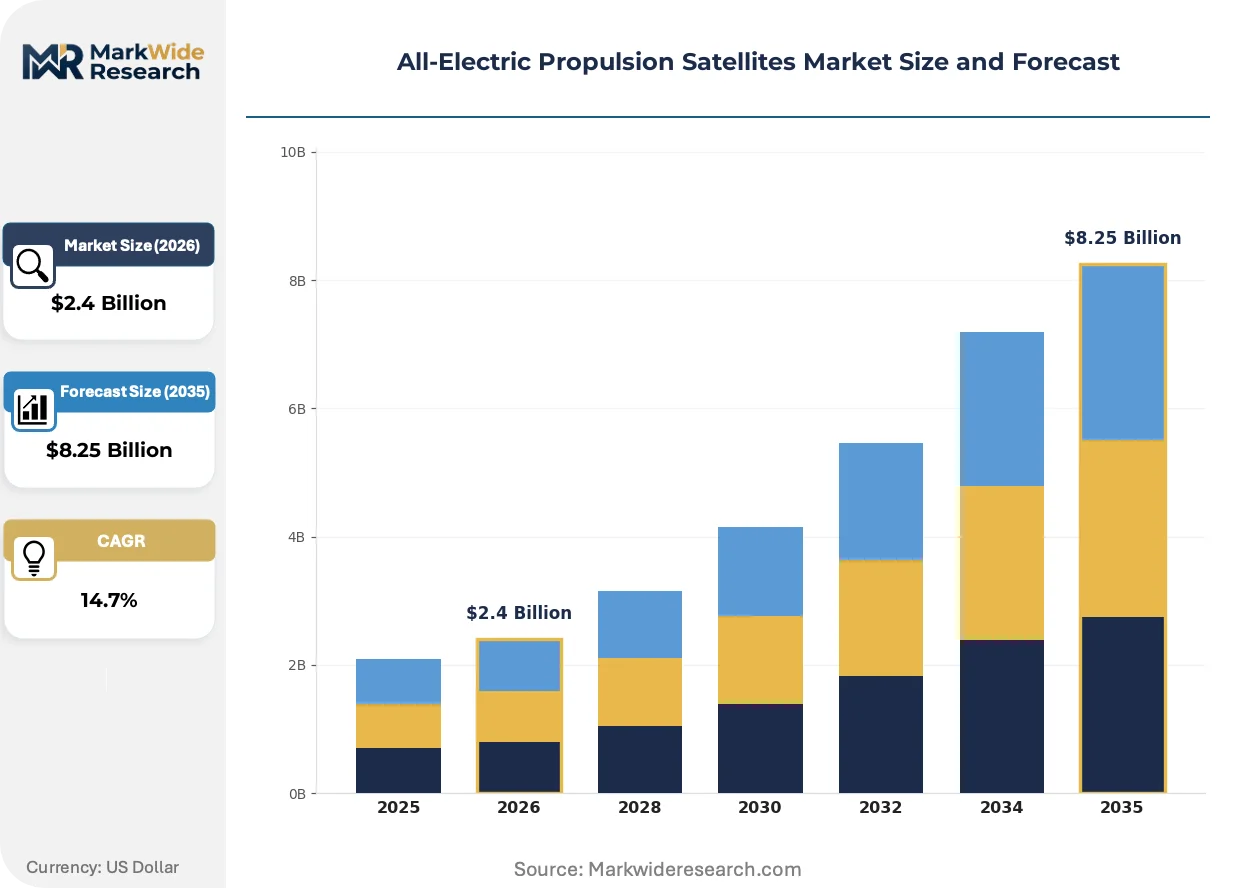
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Satellites, Medium Satellites, Large Satellites, CubeSats Application: Telecommunications, Earth Observation, Scientific Research, Navigation End User: Government, Commercial, Non-Profit, Military Technology: Ionic Thrusters, Hall Effect Thrusters, Pulsed Plasma Thrusters, Others |
| Companies Covered | Airbus Defence and Space, Boeing Defense, Space & Security, Lockheed Martin Corporation, Northrop Grumman Corporation, Thales Alenia Space, Safran Group, ArianeGroup, L3Harris Technologies, Aerojet Rocketdyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
All-Electric Propulsion Satellites Market Trends and Innovations
Krypton-fed Hall effect thrusters are overtaking xenon systems as the dominant electric propulsion architecture. This chemistry shift responds to supply security concerns while enabling higher specific impulse performance for constellation operators.
Gridded ion thruster technology is overtaking conventional Hall effect systems in precision orbit-insertion applications. Earth observation constellations requiring exact phasing are adopting these systems despite higher complexity. The technology is compressing station-keeping fuel budgets for missions demanding sub-meter positioning accuracy.
REACH chemical restrictions on propellant handling are forcing ground infrastructure redesign across European launch sites. Industrial consequence includes mandatory closed-loop processing systems for xenon and krypton. Small satellite operators serving EU government contracts face compliance costs that favor integrated European suppliers over component importers.
Buyer concentration among mega-constellation operators is compressing supplier negotiation leverage. SpaceX and Amazon's Project Kuiper now dictate platform specifications that flow down to subsystem vendors. This pattern concentrates procurement power in US-based prime contractors while fragmenting European supplier margins.
All-Electric Propulsion Satellites Market Segmentation
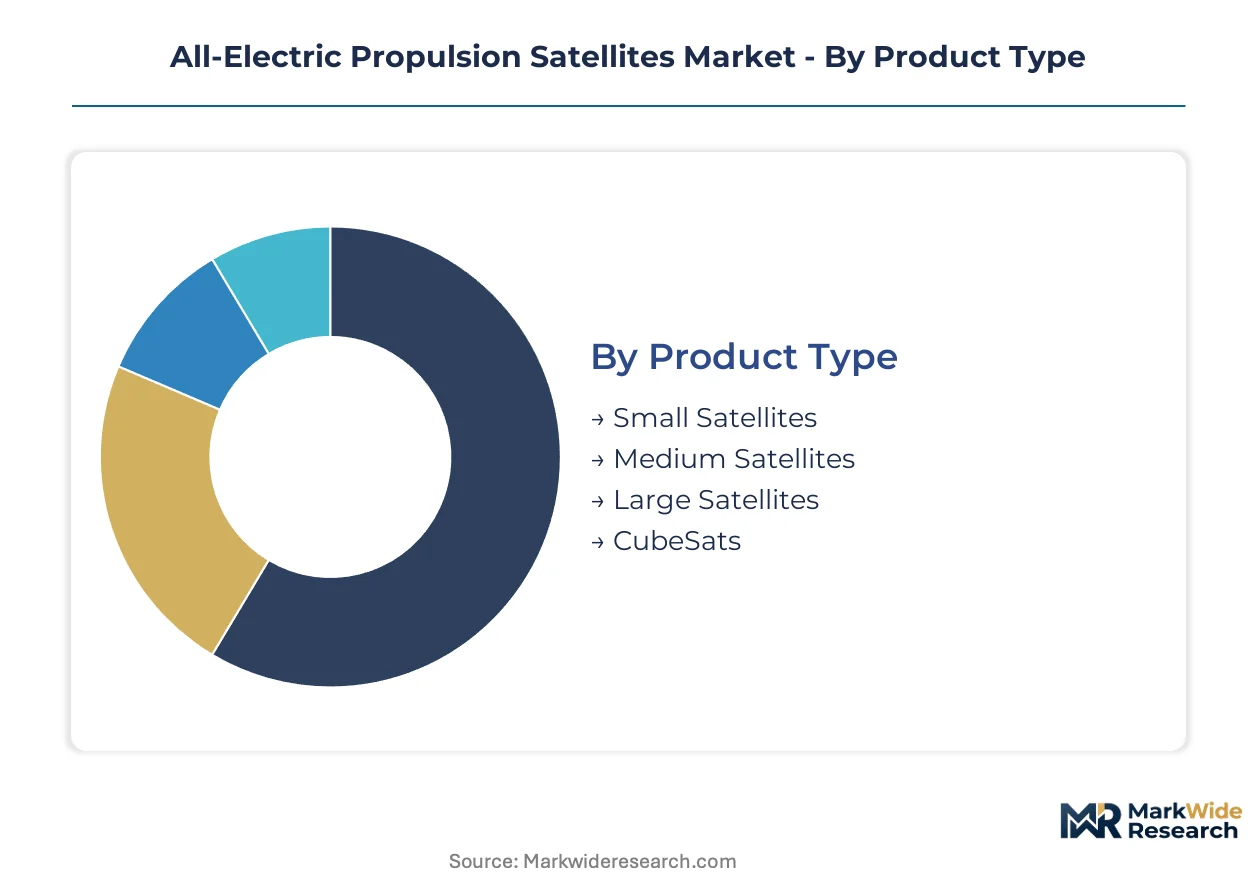
Electric propulsion platform selection hinges on mission duration, payload mass, and orbit-raising timeline trade-offs. Capital deployment varies dramatically across satellite classes and thruster technologies, with constellation scale economies reshaping procurement patterns.
Product Type:
Capital intensity peaks with large satellite platforms requiring redundant propulsion strings and extended qualification cycles, while small satellite categories demand volume manufacturing discipline over unit engineering investment.
- Small Satellites:Mass-produced electric-propulsion units prioritize krypton-fed Hall effect thrusters for station-keeping in 100-500 kg platforms. Demand clusters with commercial constellation operators seeking rapid deployment timelines and standardized bus architectures.
- Large Satellites:Premium platforms integrate gridded ion thruster arrays delivering precise orbit insertion for geostationary telecommunications payloads. Extended operational lifespans justify upfront propulsion costs through reduced replacement frequency.
- Medium Satellites:Hybrid architectures balance chemical backup with electric primary propulsion for government earth observation missions.
- CubeSats:Miniaturized pulsed plasma thrusters enable limited maneuverability for academic and technology demonstration payloads.
Large satellites absorb the bulk of installed capacity; small satellites are expanding most quickly.
Application:
Revenue stability differs sharply across mission types, with telecommunications offering predictable cash flows against scientific research's grant-dependent volatility.
- Telecommunications:Geostationary and low-earth-orbit constellations deploy electric propulsion for both orbit-raising and station-keeping, with FCC debris mitigation rules mandating efficient deorbit capability. Operators prioritize krypton chemistry to reduce South African xenon supply exposure.
- Earth Observation:Precision orbit phasing requirements drive gridded ion thruster adoption for sub-meter positioning accuracy. Dual-use platforms serving military resilience mandates command premium pricing.
- Scientific Research:Deep-space missions leverage high-specific-impulse electric propulsion for interplanetary trajectory optimization.
- Navigation:Regional systems require electric thrusters for constellation replenishment and orbital plane maintenance.
Telecommunications dominates current procurement volumes; earth observation is gaining share fastest.
End User:
Procurement authority concentration shapes contract structures, with military buyers imposing stringent qualification requirements that commercial operators circumvent.
- Commercial:Mega-constellation operators dictate platform specifications to subsystem vendors, compressing supplier margins while accelerating technology refresh cycles. SpaceX and Amazon's Project Kuiper anchor North American demand.
- Military:Classified programs through Boeing Defense, Space & Security require radiation-hardened components and secure supply chains. Dual-use platform standardization is converging civilian and military specifications.
- Government:Civil space agencies prioritize technology demonstration missions with extended development timelines.
- Non-Profit:Educational and humanitarian satellite initiatives rely on rideshare launch economics and simplified propulsion systems.
Commercial buyers command the largest order books; military procurement is climbing the fastest.
Technology:
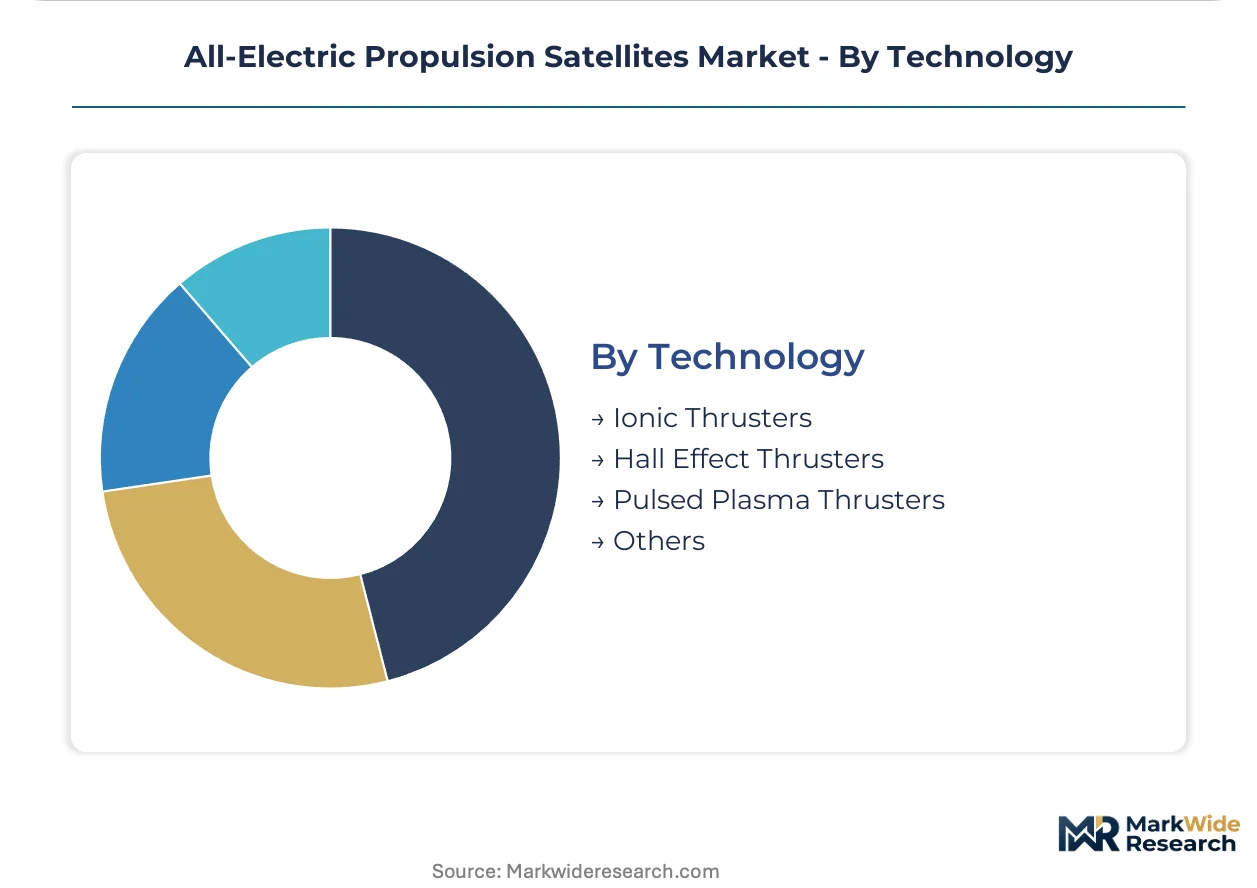
Technical maturity and supply chain readiness determine thruster selection, with heritage systems facing displacement from next-generation architectures.
- Hall Effect Thrusters:Proven heritage systems from Toulouse manufacturing clusters dominate European integration timelines. Krypton chemistry transition is displacing xenon-dependent legacy platforms.
- Ionic Thrusters:Gridded ion systems capture precision applications requiring exact phasing control for earth observation constellations.
- Pulsed Plasma Thrusters:Ablative and vacuum arc systems serve CubeSat attitude control with minimal propellant infrastructure.
- Others:Electrospray and helicon thruster concepts remain in technology readiness level advancement.
Hall effect thrusters retain the majority of flight heritage; ionic thrusters are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Toulouse anchors European electric propulsion manufacturing, with Airbus Defence and Space driving Hall effect thruster integration for commercial and military platforms across the continent.
France
Airbus Defence and Space commands European electric propulsion integration from its Toulouse manufacturing base, serving both commercial constellation operators and military resilience programs. The EU Green Deal's emissions-linked procurement criteria accelerate abandonment of chemical propulsion baselines entirely. Thales Alenia Space competes from Cannes and Cannes-la-Bocca facilities on dual-use platforms converging civilian telecommunications with defense specifications.
United States
Boeing Defense, Space & Security anchors North American demand through classified government programs requiring radiation-hardened electric propulsion systems. FCC orbital debris mitigation rules mandate efficient deorbit timelines that electric thrusters satisfy more cost-effectively than chemical alternatives. SpaceX and Amazon's Project Kuiper concentrate mega-constellation procurement power in California and Washington state facilities.
Italy
Thales Alenia Space operates from Rome and Turin facilities, specializing in dual-use electric propulsion platforms that straddle civilian telecommunications and military mandates. REACH chemical restrictions on propellant handling elevate certification costs for non-European suppliers seeking Italian commercial access. The country's space manufacturing corridor links Turin engineering centers with Rome-based government procurement.
Japan
Mitsubishi Electric and IHI Aerospace develop gridded ion thruster systems for precision orbit-insertion applications in earth observation constellations. METI funding programs support domestic electric propulsion qualification timelines for commercial and scientific missions. Tsukuba Space Center concentration enables rapid technology transfer from JAXA research to industrial production.
India
ISRO's commercial arm and emerging private operators represent underpenetrated demand for small electric-propulsion platforms in regional navigation and earth observation networks. BIS certification requirements and PLI scheme incentives favor domestic manufacturing partnerships over direct imports. Bengaluru's aerospace cluster concentrates propulsion engineering talent for constellation-scale production.
All-Electric Propulsion Satellites Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification heritage and dual-use certification depth. The vendor base stratifies between integrated prime contractors controlling full platform integration and specialized thruster manufacturers supplying subsystems. Three archetypes dominate: European state-affiliated aerospace conglomerates with captive electric propulsion capabilities, US defense primes anchoring classified procurement, and emerging commercial constellation operators backward-integrating into proprietary thruster design. Competitive moves concentrate on strategic partnerships for krypton supply security and technology licensing to compress multi-year qualification timelines.
Among European state-affiliated conglomerates, Airbus Defence and Space and Thales Alenia Space exemplify the integrated prime archetype, combining Toulouse and Cannes manufacturing concentration with EU regulatory compliance infrastructure. Boeing Defense, Space & Security occupies a position within the US defense prime tier, leveraging classified program relationships to sustain premium positioning against commercial price pressure. These three entities represent distinct geographic anchors for procurement authority concentration across NATO-aligned electric propulsion demand.
| Leading Market Players |
|---|
| Airbus Defence and Space |
| Boeing Defense, Space & Security |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Thales Alenia Space |
| Safran Group |
| ArianeGroup |
| L3Harris Technologies |
| Aerojet Rocketdyne |
| Others |
Pricing and Supply Chain Analysis
Krypton-fed Hall effect thruster adoption is simultaneously compressing propellant procurement costs and redistributing manufacturing gravity toward European integration hubs. This chemistry transition weakens South African xenon dependency while amplifying Toulouse-based suppliers' negotiating leverage over constellation operators.
Pricing Analysis
Operational lifespan guarantees anchor value-based pricing for electric propulsion platforms, with premium tiers commanding multiples over standard configurations based on qualification heritage and dual-use certification depth. Price differentiation separates radiation-hardened military-grade systems from commercial constellation units, with volume scale and REACH compliance status as secondary drivers. Pricing pressure stems from mega-constellation operators backward-integrating into proprietary thruster design, compressing subsystem vendor margins. Commercial buyers exhibit highest price sensitivity, while classified military programs absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Toulouse, Cannes-la-Bocca, and Bengaluru coordinate hub-and-spoke patterns for Hall effect thruster components and ground support equipment. Manufacturing concentrates in France, Italy, and the United States, with propellant processing drawing from Ukrainian and Russian krypton extraction prior to current disruptions. Raw material dependencies include high-purity krypton gas, ceramic discharge channel substrates, and magnetic circuit alloys. Single-source vulnerability in specialized plasma physics workforce pools constrains capacity expansion. Distribution runs through prime contractor integration facilities rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated prime contractors as multi-year EMA and FAA qualification timelines extinguish venture-funded new entrant viability. REACH compliance infrastructure and dual-use certification depth now function as exclusionary moats.
For Market Incumbents: Extend qualification heritage advantages by capturing CE-marked ground support equipment revenue streams adjacent to thruster sales. Deepen backward integration into krypton purification and closed-loop propellant processing to neutralize supply security threats from South African xenon concentration. Lock in exclusive supplier status with emerging Indian constellation operators before domestic BIS-certified competitors mature.
For New Entrants and Emerging Players: Enter via specialized gridded ion thruster subsystems for precision earth observation phasing applications where heritage players underinvest. Target academic and technology demonstration missions as qualification pathways toward commercial viability. Pursue licensing arrangements with Toulouse-based engineering talent pools to compress EMA space medicine certification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime acquisition of dual-use platform specialists with captive European regulatory compliance infrastructure. Long-term viability favors integrated manufacturers over component suppliers as buyer concentration intensifies. Monitor FCC orbital debris rule enforcement stringency as inflection indicator for platform replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Krypton Supply Security Partnership | Long-term offtake agreements with Ukrainian and Qatari gas processors reduce South African xenon exposure. |
| Dual-Use Platform Standardization | |
| CE Marking for Ground Infrastructure | European certification requirements create captive demand for specialized xenon handling systems. |
| Indian Manufacturing Partnership | PLI scheme incentives and BIS certification favor domestic production alliances over direct imports. |
| Gridded Ion Thruster R&D Investment | Precision orbit-insertion applications for earth observation constellations command premium positioning. |
Research Methodology
Independent corroboration across satellite operator procurement executives, Hall effect thruster engineering leads, and EMA regulatory affairs specialists underwrites the qualitative findings in this study. Secondary validation draws from FCC orbital debris filings, EU Green Deal implementation directives, and REACH chemical handling compliance databases. Bottom-up platform deployment forecasts triangulate against top-down constellation operator capex disclosures.
Rate-of-change decomposition across the analysis window separates volume growth in small satellite constellations from value concentration in large geostationary platforms. Segmentation dimensions include thruster technology type, satellite mass class, application mission profile, and end-user procurement authority. CAGRs derive from installed base replacement cycles and new constellation deployment schedules, with krypton price trajectory and REACH compliance cost inflation as specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control harmonization disruptions or xenon supply emergency allocations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Canada Satellite-Based Earth Observation Market
Satellite
Russia Satellite Communications Market
Satellite
India Satellite Connectivity Market
Satellite
Vehicle Mounted Satellite Communication Station Market
Satellite
Airborne UHF-Band SATCOM Market
Satellite
Saudi Arabia Satellite Imagery Services Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Flat Panel Satellite Antenna Market
Satellite
India Satellite Communication Market
Satellite
Russia Satellite-Based Earth Observation Market
Satellite
North America Military Satellite Market
Satellite
Satellite Communication Equipment Market
Satellite
Canada Satellite Connectivity Market
Satellite
Europe Satellite Attitude and Orbit Control System Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
China Satellite-Based Earth Observation Market