
 Electric Aircraft Market | 2026-2036
Electric Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Aircraft Market Intelligence
The architectural shift toward distributed electric propulsion systems is rewriting the fundamentals of aircraft design and performance. Joby Aviation leverages its early progress in certification processes with the FAA to establish a strong market position. Archer Aviation specializes in developing eVTOL aircraft for urban air mobility networks. Beta Technologies differentiates with a focus on both cargo and passenger aircraft, targeting diverse logistics and transport applications.
Electric aircraft utilize electric motors for propulsion, powered by batteries, fuel cells, or hybrid systems. Their design targets zero in-flight emissions for applications ranging from personal air vehicles to regional transport. Battery electric propulsion technology dominates development for smaller aircraft, while hybrid electric systems are pursued for larger regional jets. Short-haul commuting and cargo transport are the initial commercial focus for airlines and cargo operators.
Regulatory frameworks from the FAA in the United States and the EASA in Europe are establishing the certification pathways for novel aircraft designs. These standards, along with directives from China's civil aviation authority, govern airworthiness, operational safety, and pilot training requirements. Stakeholder success will depend on navigating these evolving and complex regulatory landscapes to achieve type certification and begin commercial operations.
Market Dynamics
The architectural shift toward distributed electric propulsion is the central force shaping the electric aircraft market. This technological change, enabled by advances in high-power electric motors and sophisticated flight control software, allows for fundamentally new aircraft designs previously considered impractical.
Growth Catalysts
- Regulatory Frameworks:Clear certification pathways being established by the FAA in the United States and EASA in Europe provide manufacturers with defined targets for airworthiness and operational safety, reducing development uncertainty for urban air mobility applications.
- Battery Technology Advances:Continuous improvements in battery energy density and thermal management systems are extending the viable range and payload capacity of electric aircraft, making short-haul commuting and regional cargo transport commercially feasible.
- Urban Congestion:Severe ground traffic in major metropolitan areas globally creates strong demand for alternative transportation modes, positioning urban air mobility as a time-saving solution for commuters and logistics operators.
Market Restraints
- Battery Performance Limitations:Current battery technology, despite improvements, imposes significant constraints on aircraft range, endurance, and payload, limiting initial applications to short-duration flights and restricting entry into longer regional routes.
- Material Supply Chain Bottlenecks:The supply of critical materials, including high-purity cobalt and lithium for batteries and aerospace-grade carbon composites for airframes, is concentrated in a few regions, creating price volatility and supply risks.
- High Certification Costs:The immense capital investment and long timelines required to achieve type certification for novel aircraft designs under stringent FAA and EASA regulations represent a substantial structural barrier for new entrants.
Strategic Opportunities
- Cargo and Logistics Niches:The middle-mile and last-mile logistics sectors present a significant opportunity for specialized electric cargo drones and aircraft, particularly for high-value or time-sensitive deliveries like medical supplies.
- Autonomous Flight Systems:Integrating advanced AI-driven autonomous flight controls with electric propulsion can reduce operational complexity and long-term pilot dependency, opening pathways for more scalable and efficient air mobility networks.
- Government Decarbonization Mandates:Policy initiatives like the EU Green Deal and national carbon reduction targets create powerful incentives for airlines and logistics companies to invest in zero-emission aircraft to meet future environmental compliance goals.
Industry Challenges
- Ground Infrastructure Deficit:The widespread lack of vertiports and high-speed charging infrastructure in urban and regional areas presents a critical operational bottleneck, limiting the scalability and practical deployment of electric aircraft services.
- Certification Process Complexity:Navigating the multi-year, technically intensive process to achieve type certification from aviation authorities like the FAA and EASA for entirely new aircraft classes remains a primary execution challenge for all developers.
- Specialized Talent Shortages:A scarcity of engineers with cross-disciplinary expertise in aerospace engineering, high-voltage power electronics, and battery chemistry constrains the pace of design, testing, and manufacturing across the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Aircraft Market |
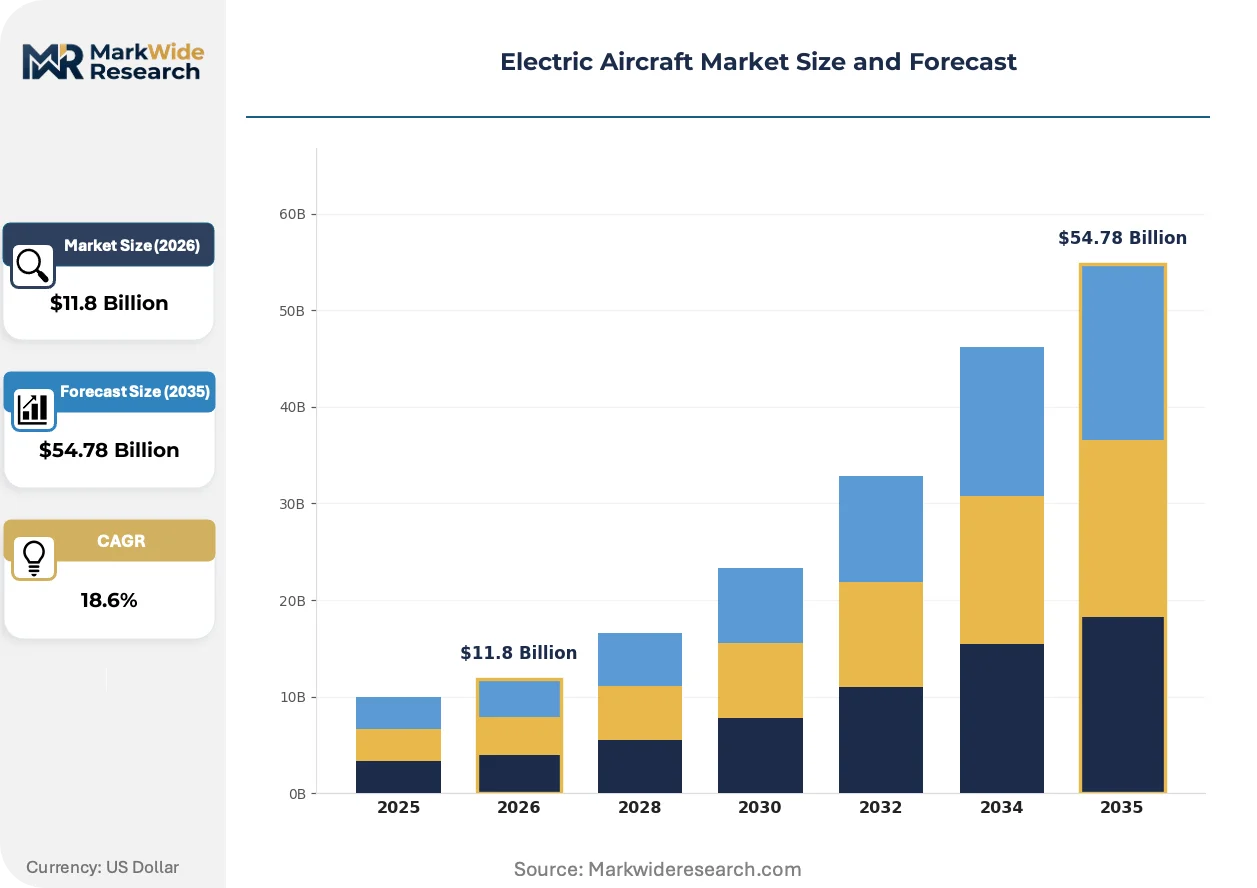
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $54.78 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Regional Jets, Light Sport Aircraft, Commuter Planes, Cargo Drones, Personal Air Vehicles Propulsion Technology: Battery Electric, Hybrid Electric, Fuel Cell Electric, Solar Electric, Turboelectric Application: Short-Haul Commuting, Cargo Transport, Aerial Surveying, Emergency Services, Flight Training End User: Airlines, Cargo Operators, Flight Schools, Government Agencies, Charter Services |
| Companies Covered | Eve, Embraer, Joby Aviation, Elektra, Vertical Aerospace, Archer Aviation, Boeing Wisk Aero, Honda, Beta Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Aircraft Market Strategic Shifts & Innovations
The architectural shift from conventional, centralized engines to distributed electric propulsion systems is rewriting the fundamentals of aerodynamic design and performance. This enables novel airframe configurations, such as eVTOL aircraft, that are optimized for efficiency in specific flight phases.
Distributed electric propulsion (DEP) uses multiple, smaller electric motors placed strategically across an airframe to provide lift and thrust. Urban air mobility developers are rapidly adopting DEP for its redundancy, quiet operation, and precise flight control capabilities. This technology is rendering obsolete traditional aircraft design philosophies reliant on a few large engines and complex mechanical control surfaces.
In the United States, the FAA's creation of specific certification pathways for powered-lift aircraft provides a structured, though rigorous, route to market. These new rules address the unique characteristics of eVTOL designs that blend elements of helicopters and fixed-wing airplanes. The urban air mobility segment is most affected, with manufacturers tailoring their entire development and flight-testing programs to these evolving airworthiness standards.
A demand-side shift is occurring toward on-demand air mobility, bypassing traditional scheduled transport for direct, app-based booking of short-haul flights. This model disrupts conventional transport for time-sensitive travel, especially for inter-city and airport-to-downtown routes. This purchasing behavior is most pronounced in dense metropolitan regions in North America and Asia where severe ground congestion justifies a premium for air-based transit.
Electric Aircraft Market Segmentation
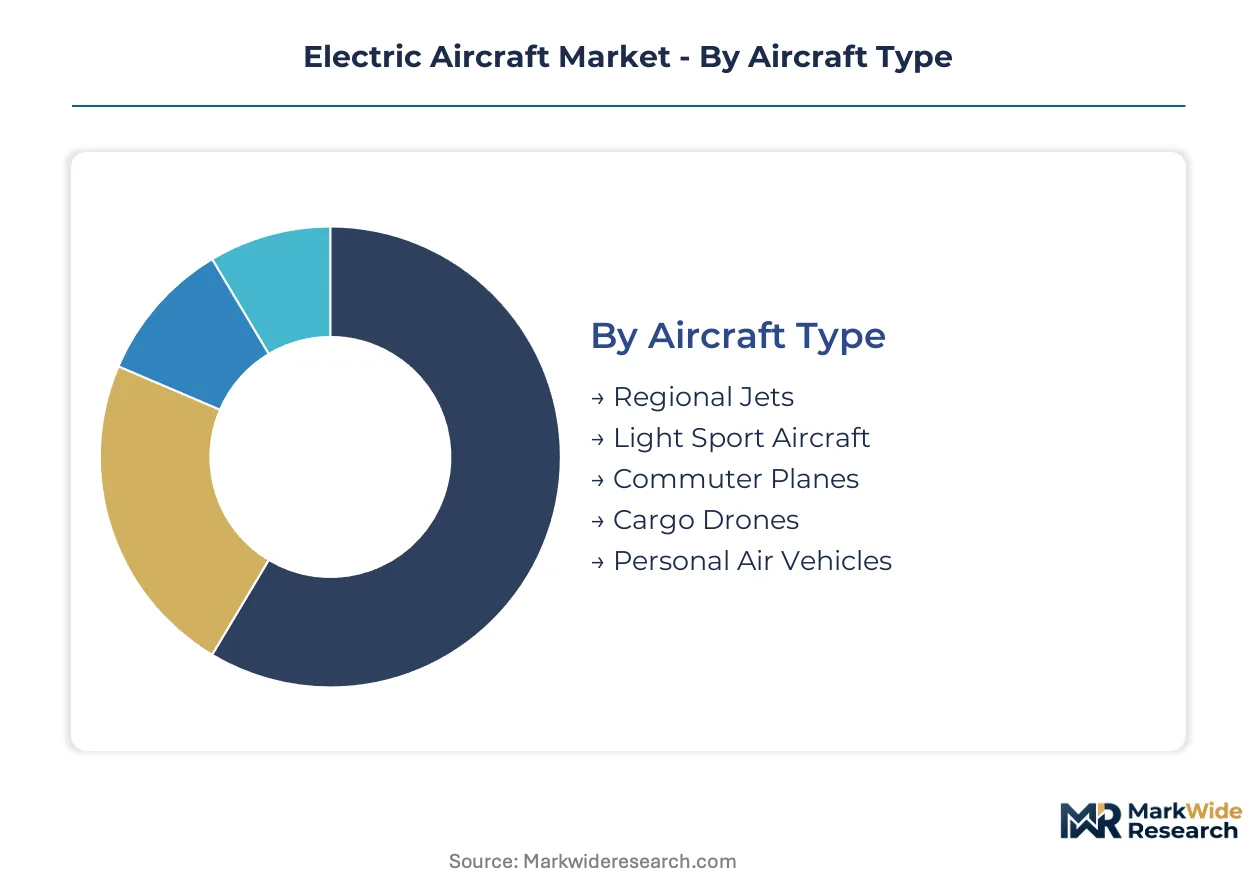
Understanding the Electric Aircraft Market through detailed segmentation reveals the specific technological advancements and end-use cases driving its expansion. This granular view highlights the varying adoption rates and strategic priorities across different aircraft designs, propulsion systems, applications, and end-user groups. Market segmentation provides a framework for assessing the commercial viability of novel aviation solutions.
Aircraft Type:
The range of aircraft types in the electric aircraft market addresses diverse operational needs, from individual transport to regional logistics.
- Regional Jets:These larger electric aircraft are designed for inter-city travel, often leveraging hybrid-electric propulsion to extend range and payload capacity. Demand concentrates in regions like Europe and North America, where airlines are seeking decarbonization pathways for existing short-to-medium haul routes.
- Personal Air Vehicles:Compact, often eVTOL designs, these aircraft are tailored for individual or small-group urban air mobility, emphasizing convenience and efficiency for short distances. Demand is particularly strong in dense metropolitan areas of the United States and China, driven by severe ground congestion and the promise of rapid point-to-point travel.
- Light Sport Aircraft:Smaller, simpler electric aircraft primarily used for recreational flying or flight training, benefiting from reduced operating costs and lower noise profiles.
- Commuter Planes:Designed for shorter routes connecting smaller towns to larger hubs, these electric models aim to replace conventional turboprops with more sustainable options.
- Cargo Drones:Autonomous or remotely piloted electric aircraft specialized in package delivery and logistics, particularly for middle-mile and last-mile operations in urban and rural settings.
Regional Jets holds installed capacity. Cargo Drones is rotating up the share rankings.
Propulsion Technology:
Propulsion technology differentiation underpins performance envelopes and operational feasibility across the electric aircraft spectrum.
- Battery Electric:These systems rely solely on stored electrical energy in batteries to power electric motors, offering zero in-flight emissions and quiet operation for short-range flights. Development is concentrated in smaller urban air mobility aircraft due to current battery energy density limitations.
- Hybrid Electric:Combining electric motors with a conventional combustion engine or turbine, these systems extend range and payload capacity by generating electricity onboard. Larger regional jets and cargo aircraft are exploring hybrid solutions to bridge the gap to full battery-electric long-haul flight.
- Fuel Cell Electric:Utilizing hydrogen fuel cells to generate electricity, this technology offers longer range than pure battery systems with zero emissions, suitable for medium-sized aircraft.
- Solar Electric:Aircraft integrating solar panels to generate power, primarily for extended endurance or high-altitude long-endurance applications, often in uncrewed aerial vehicles.
- Turboelectric:A system where a turbine drives an electric generator, which in turn powers distributed electric motors, offering high power output and flexibility in aircraft design.
Battery Electric systems demonstrate the steepest expansion trajectory. Turboelectric configurations are gaining share most quickly.
Application:
Specific operational applications define the commercial viability and deployment scenarios for electric aircraft technologies.
- Short-Haul Commuting:This application focuses on inter-city or airport-to-downtown routes, offering a time-saving alternative to ground transport in congested urban centers. Demand is pronounced in North America and Asia, where intense ground traffic creates a premium for rapid air transit.
- Cargo Transport:Electric aircraft are deployed for middle-mile and last-mile logistics, specializing in rapid, efficient delivery of goods, including high-value or time-sensitive items like medical supplies. E-commerce expansion and demand for faster delivery drive this segment in the United States and Europe.
- Aerial Surveying:Electric drones and light aircraft are used for environmental monitoring, infrastructure inspection, and precision agriculture due to their quiet operation and lower costs.
- Emergency Services:Electric aircraft provide rapid response capabilities for medical emergencies, search and rescue, and disaster relief, benefiting from quick deployment and reduced noise.
- Flight Training:Electric light sport aircraft offer lower operating costs and reduced environmental impact for pilot training programs, making aviation education more accessible.
Short-Haul Commuting applications are expanding fastest. Emergency Services are climbing the share rankings.
End User:
The ultimate end-users for electric aircraft drive demand based on their specific business models and operational requirements.
- Airlines:Commercial carriers are investing in electric aircraft to meet decarbonization mandates like the EU Green Deal and to reduce operational costs on regional routes. Major airlines in Europe and the United States are exploring partnerships for eVTOL services and regional electric jets.
- Cargo Operators:Logistics companies are integrating electric cargo drones and aircraft into their networks to enhance delivery speed, reduce emissions, and optimize last-mile operations. Companies like Amazon and UPS are piloting electric drone delivery in select markets.
- Flight Schools:These institutions adopt electric aircraft for pilot training, capitalizing on lower fuel and maintenance costs while preparing pilots for future electric fleets.
- Government Agencies:Entities such as national defense, border patrol, and environmental protection agencies utilize electric aircraft for surveillance, transport, and monitoring missions.
- Charter Services:Private aviation companies offer on-demand electric air travel for business and leisure, providing flexible and premium transportation options.
Airlines represent the largest current demand base. Government Agencies are exhibiting the strongest growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a primary innovator in electric aircraft technology, significantly influences global market development through its regulatory advancements. European countries also contribute substantially to novel aircraft designs and certification pathways. Demand for electric aviation solutions is expanding across key metropolitan areas worldwide.
United States
United States demand centers on urban air mobility and short-haul commuting applications, backed by significant venture investment. The FAA's clear regulatory pathways for powered-lift aircraft are accelerating development and certification processes. California's Silicon Valley and aerospace hubs in Washington state are driving innovation in eVTOL design and advanced propulsion systems.
Germany
Germany's market expansion aligns with European decarbonization mandates and a strong focus on regional air transport. EASA's comprehensive certification frameworks provide a structured route to market for electric aircraft manufacturers. Bavaria, with its strong automotive and aerospace engineering base, is a hub for hybrid-electric and battery-electric propulsion system development.
China
China exhibits strong demand for personal air vehicles and urban air mobility solutions, driven by severe metropolitan congestion. Directives from China's civil aviation authority are establishing airworthiness and operational safety standards for novel aircraft designs. The Pearl River Delta region is seeing rapid investment in eVTOL manufacturing and integrated air mobility networks.
Japan
Japan's interest in electric aircraft stems from its dense urban environments and the need for efficient on-demand air mobility and logistics. The Ministry of Economy, Trade and Industry (METI) supports research and development for urban air mobility solutions. The Tokyo metropolitan area is exploring vertiport infrastructure development to integrate eVTOL services into its transport ecosystem.
The United Kingdom
The United Kingdom focuses on electric aircraft for short-haul commuting and enhancing regional connectivity, particularly for airport-to-downtown routes. EASA's influence on certification standards continues to shape local regulatory approaches for novel aircraft. Aerospace clusters around Bristol and Cranfield are actively involved in developing advanced materials and propulsion systems for next-generation electric aircraft.
Electric Aircraft Market Key Industry Players
On the supply side, the industry is highly fragmented, with numerous startups and established aerospace firms competing for market share. This landscape features a tiered structure, encompassing pure-play eVTOL developers, traditional aerospace giants diversifying into electric propulsion, and specialized component suppliers. Companies are primarily engaging in strategic partnerships for technology co-development and aggressive capital raises to fund extensive certification processes.
Within the pure-play eVTOL developer archetype, Joby Aviation, Inc. and Archer Aviation, Inc. exemplify the focus on urban air mobility applications. Joby Aviation, a California-based company, occupies a position centered on early certification progress with the FAA. Archer Aviation, also based in California, anchors its strategy on developing eVTOL aircraft for urban networks. Beta Technologies, a Vermont-based firm, sits within the archetype of developers targeting both cargo and passenger aircraft for diverse logistics and transport applications.
| Leading Market Players |
|---|
| Eve |
| Embraer |
| Joby Aviation |
| Elektra |
| Vertical Aerospace |
| Archer Aviation |
| Boeing Wisk Aero |
| Honda |
| Beta Technologies |
| Others |
Cost & Logistics Intelligence
Urban air mobility routes face high initial operating costs driven by concentrated battery material supply chains, influencing downstream price differentiation for rapid, time-sensitive air transit services. This cost structure impacts commercial viability and market access.
Pricing Analysis
The initial technology-generation pricing gap between early-stage electric aircraft prototypes and future mass-produced models remains substantial. Contract-based long-term offtake agreements dominate for fleet operators, alongside per-flight transactional pricing for individual consumers. Pricing differentiation stems from FAA Type Certification status and the level of after-sales service and support. Pricing pressure stems from increasing competition and anticipated production scale. Emergency services and high-value cargo operators demonstrate lower price sensitivity compared to short-haul commuters.
Supply Chain Analysis
Specialized component manufacturers for high-power electric motors and advanced composite airframes hold significant contract-manufacturing concentration. Geographic supply concentration for critical materials like lithium and cobalt centers in China, while advanced aerospace manufacturing hubs exist in the United States and Europe. The supply chain relies heavily on carbon composites and high-energy-density battery cells. Commodity price volatility for these raw materials presents a structural supply chain risk. Downstream distribution runs through direct sales to airlines and cargo operators, alongside dedicated vertiport networks for urban air mobility services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric aircraft market is an early-cycle expansion story, buoyed by increasing regulatory clarity from authorities like the FAA and EASA, which is accelerating adoption pathways. Stakeholders must strategically position themselves to capture emerging value pools.
For Market Incumbents: Insulate existing market share by accelerating investment in proprietary battery technology and advanced thermal management systems. Acquire specialized component suppliers to mitigate material supply chain risks and control intellectual property. This strategy counters the threat from disruptive startups offering lower operational cost structures. Incumbents should also prioritize certification investment to establish early operational advantages.
For New Entrants and Emerging Players: Establish a beachhead in underserved cargo and logistics niches, particularly for middle-mile and last-mile operations in regional areas. The cargo drone segment in rural settings presents the most penetrable application due to less stringent infrastructure requirements. A focused go-to-market angle emphasizing rapid, efficient delivery of high-value or time-sensitive goods will differentiate offerings. Partnerships with existing logistics providers can accelerate market entry and scaling.
For Investors and Strategic Acquirers: FAA Type Certification of early eVTOL models reshapes the acquisition landscape, signaling readiness for scaled commercial operations. This market offers significant long-term viability and growth potential over the next decade. Investors should target companies demonstrating clear progress in regulatory compliance or possessing unique, high-energy-density propulsion intellectual property. The widespread deployment of vertiport infrastructure across major metropolitan areas is the critical signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure long-term battery material contracts | Ensures stable supply and mitigates commodity price volatility for critical components. |
| Invest in vertiport infrastructure development | Unlocks scalability and operational viability for urban air mobility services. |
| Accelerate FAA/EASA type certification | Establishes market leadership and enables commercial operations ahead of competitors. |
| Develop AI-driven autonomous flight systems | Reduces operational complexity and addresses future pilot dependency challenges. |
| Form strategic partnerships with airlines | Guarantees initial demand and integrates electric aircraft into existing networks. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. The analysis involved discussions with aerospace engineers, regulatory affairs specialists, airline procurement managers, and battery chemists. Secondary data sources included FAA and EASA certification documents, academic research papers on propulsion systems, trade association reports, and corporate financial filings. This approach ensured robust bottom-up and top-down triangulation of market insights.
A multi-factor calibration model integrated supply-side capacity expansions with demand-side adoption curves over the projection horizon. This framework segmented the market by aircraft type, propulsion technology, application, end-user, and regional regulatory compliance. Compound annual growth rates were derived from historical trends and projected future growth drivers. Key industry-specific forecast inputs included anticipated battery energy density improvements and the projected rates of vertiport infrastructure deployment.
Stress conditions across regulatory timelines, material supply chain stability, and technological breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding current market dynamics and expected industry evolution. Unforeseen certification delays or sudden commodity price spikes represent specific risk factors that could revise projections. Quarterly review of regulatory updates and battery technology advancements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Ailerons Market
Aircraft
Small Evtol Aircraft Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Flight Management Systems Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Tanker Aircraft Market
Aircraft
Aircraft Control Surface Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Light Electric Aircraft Market
Aircraft
Maritime Patrol Aircraft Market
Aircraft
Air Starter Market
Aircraft
Europe Aircraft Manufacturing Market