
 Aircraft Valves Market | 2026-2036
Aircraft Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Valves Market Analytics
North American aerospace manufacturing is reshaping competitive dynamics across the aircraft valves supply chain. Eaton Corporation leverages vertical integration across hydraulic and fuel system architectures to sustain program awards on major platforms. Parker Hannifin Corporation anchors its position through R&D intensity in electromechanical valve actuation, while Safran competes on European regulatory alignment and carbon brake integration expertise.
Aircraft valves are precision-engineered flow control devices manufactured from titanium alloys, nickel-based superalloys, and advanced polymer composites, designed to regulate fuel, hydraulic fluid, and pneumatic pressure across operating envelopes from -65°F to 450°F. Their primary purpose is to ensure fail-safe fluid management in flight-critical systems under extreme vibration, thermal cycling, and pressure differentials. Butterfly valves dominate fuel system applications due to weight advantages and quarter-turn actuation speed, while solenoid technology is displacing legacy pneumatic architectures in next-generation electric aircraft platforms. Commercial aviation OEM procurement concentrates margin pools in original equipment channels, though MRO providers are extending aftermarket capture through predictive maintenance contracts.
FAA airworthiness standards under 14 CFR Part 25, EASA CS-25 certification requirements, and ISO 9001/AS9100 quality frameworks collectively govern material selection, fire resistance testing, and traceability protocols for aircraft valve suppliers. These regulatory layers shape demand by mandating redundant sealing technologies and deterministic failure modes that extend engineering cycles and qualification costs. Stakeholders must monitor the divergence between FAA and EASA electrification timelines to align product roadmaps with divergent certification pathways.
Market Dynamics
Electrification of flight control architectures is compressing pneumatic valve demand while expanding electromechanical actuator procurement across Boeing and Airbus narrow-body programs. FAA 14 CFR Part 25 fire-resistance mandates and EASA CS-25 certification timelines are extending qualification cycles, concentrating engineering resources on deterministic failure-mode designs.
Growth Catalysts
- Narrow-body production ramp:Boeing 737 MAX and Airbus A320neo output rates are accelerating fuel system valve procurement from tier-one hydraulic suppliers.
- FAA airworthiness directives:Enhanced fire-resistance testing under 14 CFR Part 25.863 is mandating redundant sealing architectures that extend contract values for qualified vendors.
- Superalloy forging capacity:Titanium and Inconel supply expansion in the United States is reducing lead times for precision valve housings in next-generation platforms.
Market Restraints
- Titanium price volatility:Sponge input costs from Russian and Ukrainian supply corridors are creating margin compression for forged valve component manufacturers.
- Single-source forging concentration:Critical superalloy castings for high-pressure fuel valves depend on captive facilities in the United States and France, creating geographic concentration risk.
- Pneumatic-to-electric substitution:Electromechanical actuation is rendering legacy pneumatic valve architectures obsolete in urban air mobility prototypes.
Strategic Opportunities
- Urban air mobility electrification:eVTOL developers in Germany and the United States are specifying solid-state valve arrays for distributed propulsion systems.
- India defense procurement:Indigenous combat aircraft programs under the country's defense offset policies are creating local assembly mandates for hydraulic system suppliers.
- Predictive maintenance contracts:Sensor-integrated valve assemblies enabling condition-based monitoring are capturing aftermarket revenue streams from commercial fleet operators.
Industry Challenges
- Electromechanical systems engineering:Scarce talent pools for high-reliability motor control and position feedback integration are constraining R&D throughput at mid-tier suppliers.
- Dual certification timelines:Divergent FAA and EASA electrification roadmaps are forcing parallel qualification tracks that duplicate test article costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Valves Market |
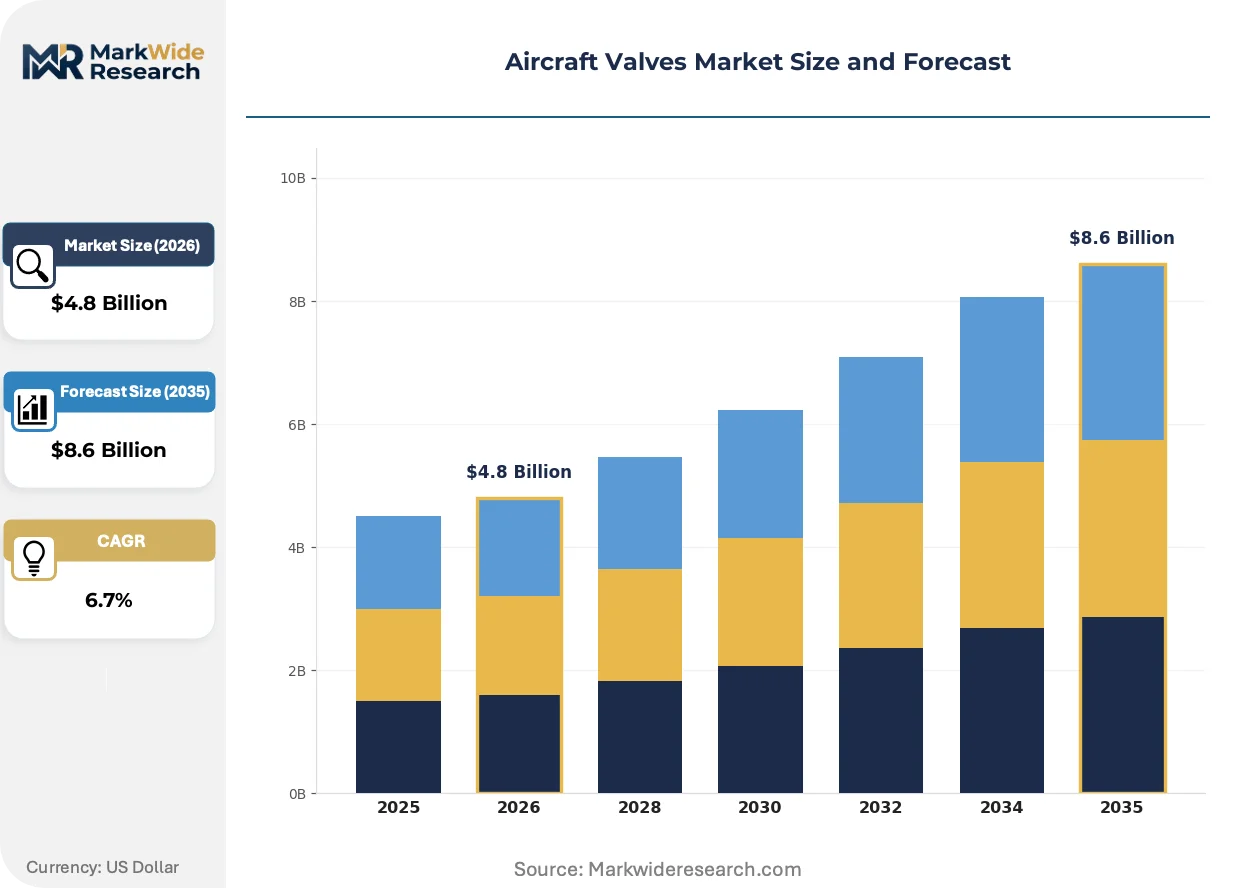
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Check Valves, Butterfly Valves Application: Fuel Systems, Hydraulic Systems, Pneumatic Systems, Air Management Technology: Electric Valves, Pneumatic Valves, Manual Valves, Solenoid Valves End User: OEMs, MRO Providers, Military Aircraft, Commercial Aviation |
| Companies Covered | Eaton Corporation, Parker Hannifin Corporation, Safran, Woodward Inc., Honeywell International Inc., Triumph Group, Liebherr Group, Moog Inc., Raytheon Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Valves Market Evolving Landscape
Digital twin integration and additive manufacturing are compressing prototype-to-qualification timelines while enabling topology-optimized valve geometries that were previously unmachinable. These shifts are redistributing competitive advantage toward suppliers with captive simulation and powder-bed fusion capabilities.
Model-based systems engineering is virtualizing valve design validation workflows, replacing physical test iterations with finite-element and computational fluid dynamics correlation. Tier-one aerospace suppliers are adopting these platforms to compress FAA certification timelines from thirty-six to eighteen months. The approach is virtualizing traditional hardware-in-the-loop verification, reducing qualification costs for electromechanical fuel valve architectures.
EASA CS-25 Amendment 25-147 introduced enhanced flammability requirements for thermal/acoustic insulation materials adjacent to fuel system components. European OEM procurement specifications now mandate fire-resistant polymer composites in valve housing assemblies that previously used standard thermoplastics. German and French suppliers are retrofitting production lines to meet these material specifications ahead of 2027 fleet retrofit deadlines.
Airline technical procurement teams are consolidating valve sourcing under long-term availability agreements that bundle original equipment and overhaul services. Maintenance, repair, and overhaul providers are responding with dedicated valve repair stations in Singapore and the United Arab Emirates. This consolidation is most visible among Middle Eastern flag carriers seeking to internalize component life-cycle costs across wide-body fleets.
Aircraft Valves Market Segmentation
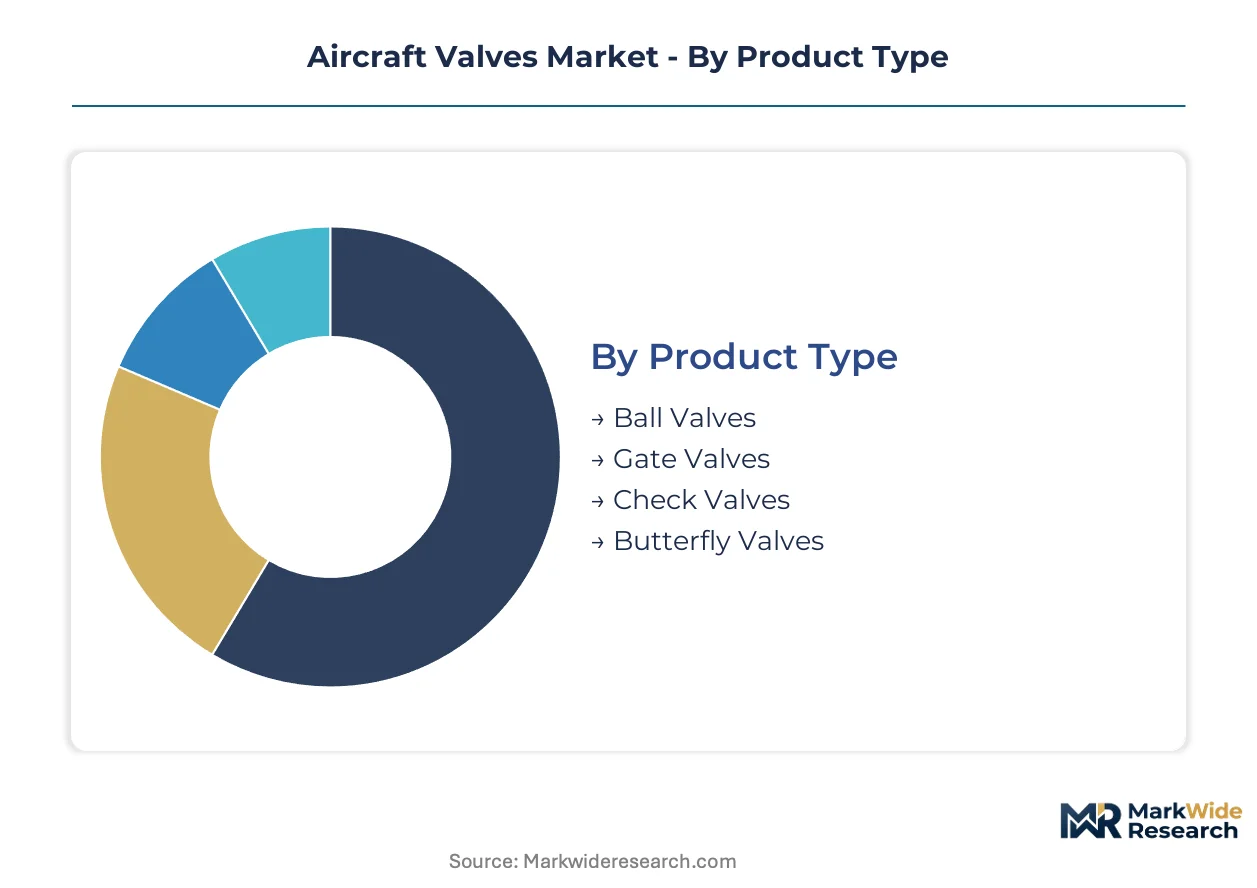
Aircraft valve procurement cycles vary dramatically by system criticality and platform generation. Fuel system components turn over fastest on narrow-body production lines, while hydraulic architectures in legacy fleets extend replacement intervals. Understanding these velocity differentials shapes inventory positioning and engineering resource allocation.
Product Type:
Replacement velocity splits sharply between fuel system quick-turn items and structural hydraulic components with decade-long service lives.
- Butterfly Valves:Titanium and nickel-alloy constructions dominate fuel tank isolation and engine feed applications. Boeing 737 MAX and Airbus A320neo procurement concentrates in Wichita, Kansas and Toulouse, France forging corridors, driven by weight-minimization mandates and quarter-turn actuation speed requirements.
- Ball Valves:Spherical closure mechanisms with PTFE or metal seats handle high-pressure hydraulic circuits in landing gear and flight control systems. Demand clusters around Parker Hannifin and Eaton Corporation supply agreements for next-generation electric aircraft platforms, constrained by superalloy forging lead times.
- Gate Valves:Linear-motion designs seal fuel manifolds in wide-body auxiliary power units.
- Check Valves:Spring-loaded or swing-type configurations prevent backflow in pneumatic distribution networks.
Butterfly valves dominate installed base. Ball valves are where expansion concentrates.
Application:
System architecture electrification is redistributing procurement volumes across traditional pneumatic domains.
- Fuel Systems:Fire-resistant sealing technologies under FAA 14 CFR Part 25.863 and EASA CS-25 Amendment 25-147 govern pump isolation, tank venting, and engine feed regulation. Redundant sealing architectures from German and French suppliers are climbing the fastest as European retrofit deadlines approach.
- Hydraulic Systems:5,000 PSI operating pressures in flight control actuation demand Inconel 718 housings and deterministic failure-mode designs. Airbus A350 and Boeing 787 procurement channels concentrate margin in original equipment, though Singapore and UAE MRO stations are capturing aftermarket overhaul contracts.
- Pneumatic Systems:Bleed air management valves face substitution pressure from electromechanical alternatives in urban air mobility prototypes.
- Air Management:Environmental control system valves regulate cabin pressure and temperature across commercial and military platforms.
Hydraulic systems anchor current revenue. Fuel systems are where technology refresh concentrates.
Technology:
Actuation mechanism selection determines qualification timeline length and certification pathway complexity.
- Electric Valves:Brushless DC motor drives with position feedback sensors enable deterministic control in fly-by-wire architectures. FAA and EASA divergent electrification roadmaps are forcing parallel qualification tracks, extending engineering cycles for mid-tier suppliers lacking captive simulation capabilities.
- Solenoid Valves:Electromagnetic actuation provides rapid response for fuel injector and bleed air applications. eVTOL developers in Germany and the United States are specifying solid-state arrays for distributed propulsion, displacing legacy pneumatic alternatives.
- Pneumatic Valves:Compressed air actuation retains installed base in legacy Boeing 737NG and Airbus A320ceo fleets.
- Manual Valves:Mechanical override mechanisms provide fail-safe redundancy in emergency systems.
Pneumatic valves retain installed base dominance. Electric valves are where R&D investment concentrates.
End User:
Customer type dictates contract structure, pricing discipline, and life-cycle revenue capture mechanics.
- OEMs:Boeing and Airbus narrow-body programs bundle multi-year availability agreements with technical procurement teams, consolidating sourcing under long-term contracts that span original equipment and initial provisioning. Margin pools concentrate here for tier-one hydraulic suppliers with vertical integration across fuel and actuation architectures.
- MRO Providers:Predictive maintenance contracts with sensor-integrated valve assemblies enable condition-based monitoring revenue streams. Singapore and United Arab Emirates repair stations are expanding dedicated valve capabilities to serve Middle Eastern flag carrier wide-body fleets.
- Military Aircraft:India's indigenous combat aircraft programs under defense offset policies mandate local assembly for hydraulic system suppliers.
- Commercial Aviation:Airline technical procurement consolidation drives bundled sourcing across original equipment and overhaul services.
OEMs dominate contract value. MRO providers are where aftermarket capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Superalloy forging corridors in the United States and France anchor precision valve production for commercial aviation programs. Wichita, Kansas and Toulouse, France concentrate titanium and Inconel capacity for narrow-body fuel system architectures. Certification divergence between FAA and EASA timelines is fragmenting supplier qualification pathways across Atlantic production bases.
United States
Boeing 737 MAX production rates in Renton, Washington drive fuel system valve procurement from tier-one hydraulic suppliers. FAA 14 CFR Part 25.863 fire-resistance mandates enforce redundant sealing architectures that extend engineering cycles for qualified vendors. Wichita, Kansas hosts concentrated titanium forging capacity for precision valve housings, with suppliers reducing lead times through captive superalloy supply expansion.
France
Airbus A320neo output in Toulouse accelerates demand for butterfly valve assemblies with quarter-turn actuation specifications. EASA CS-25 Amendment 25-147 flammability requirements mandate fire-resistant polymer composites in valve housing assemblies ahead of 2027 retrofit deadlines. French suppliers in the Toulouse forging corridor are retrofitting production lines to meet enhanced material specifications for European fleet compliance.
Germany
eVTOL developers in Munich and Stuttgart specify solid-state valve arrays for distributed propulsion system architectures. EASA electrification roadmaps for urban air mobility compress pneumatic valve demand while expanding electromechanical actuator procurement. Bavarian engineering clusters concentrate R&D talent for high-reliability motor control and position feedback integration in next-generation electric platforms.
India
Indigenous combat aircraft programs under defense offset policies mandate local assembly for hydraulic system suppliers. DGFT procurement frameworks require foreign OEMs to establish domestic manufacturing partnerships for avionics and flight control components. Bangalore and Hyderabad defense corridors are attracting valve fabricators seeking compliance with indigenization mandates for military aerospace programs.
Singapore
Middle Eastern flag carriers are consolidating valve sourcing under long-term availability agreements that bundle original equipment and overhaul services. Singapore repair stations are expanding dedicated valve capabilities to capture aftermarket revenue from wide-body fleet operators. Changi aerospace clusters concentrate predictive maintenance contracts with sensor-integrated valve assemblies enabling condition-based monitoring.
Aircraft Valves Market Competitive Landscape
Vertically integrated conglomerates and specialized electromechanical specialists split the market between fuel system architectures and flight control actuation. The supplier base concentrates around forging-integrated fabricators with captive titanium capacity and R&D-intensive actuator developers with simulation capabilities. Two archetypes dominate: superalloy-forging-integrated suppliers controlling upstream material flows, and electromechanical specialists capturing electrification-driven procurement. Competitive moves center on backward integration into titanium sponge processing and strategic partnerships with eVTOL platform developers.
Among North American conglomerates, Eaton Corporation and Parker Hannifin Corporation occupy positions spanning hydraulic and fuel system architectures. Safran anchors European regulatory alignment expertise with carbon brake integration capabilities. These three exemplify the forging-integrated archetype, with captive supply chains reducing lead times for precision valve housings in next-generation narrow-body programs.
| Leading Market Players |
|---|
| Eaton Corporation |
| Parker Hannifin Corporation |
| Safran |
| Woodward Inc. |
| Honeywell International Inc. |
| Triumph Group |
| Liebherr Group |
| Moog Inc. |
| Raytheon Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Wichita, Kansas titanium forging corridors concentrate superalloy capacity for precision valve housings, translating captive material flows into pricing leverage for qualified suppliers serving Boeing narrow-body programs. FAA 14 CFR Part 25.863 fire-resistance mandates extend engineering qualification cycles, concentrating margin in vendors with redundant sealing architectures already certified.
Pricing Analysis
FAA 14 CFR Part 25.863 and EASA CS-25 Amendment 25-147 dictate the pricing tier structure across aircraft valve procurement, separating fire-resistant polymer composite assemblies from standard thermoplastic configurations. Certification grade and volume scale differentiate pricing bands, with long-term availability agreements bundling original equipment and overhaul services commanding premium positioning. Cost compression in legacy pneumatic architectures is intensifying because electromechanical substitution renders older designs obsolete. Commercial airline technical procurement teams exhibit highest price sensitivity through consolidated sourcing mandates, while defense offset programs in India demonstrate lowest sensitivity due to indigenization requirements.
Supply Chain Analysis
Export controls on superalloy forging technology limit technology transfer to non-allied production bases, concentrating precision valve housing manufacture in the United States, France, and Germany. Titanium sponge and Inconel 718 castings draw from Russian and Ukrainian supply corridors disrupted by geopolitical conflict. Single-source forging vulnerability in Wichita and Toulouse corridors creates geographic concentration risk for narrow-body fuel system architectures. Distribution runs through tier-one hydraulic suppliers with backward integration into superalloy processing, feeding OEM procurement channels and Singapore-UAE MRO repair stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated airline technical procurement teams bundling multi-year valve sourcing agreements, fragmenting supplier margin pools across original equipment and aftermarket overhaul obligations.
For Market Incumbents: Entrench certification advantage by accelerating EASA CS-25 Amendment 25-147 compliance ahead of 2027 European retrofit deadlines, while capturing titanium forging capacity expansion in Wichita to offset sponge input cost volatility. Pneumatic-to-electric substitution from eVTOL developers threatens legacy installed base; respond through R&D intensity in brushless DC motor control and position feedback integration. For New Entrants and Emerging Players: Build out solid-state valve array capabilities for German and American urban air mobility platforms, where distributed propulsion architectures lack incumbent supplier relationships. India's defense offset procurement frameworks under DGFT mandates represent the most penetrable geography, requiring domestic manufacturing partnerships in Bangalore and Hyderabad defense corridors. Target predictive maintenance contracts with sensor-integrated assemblies as the go-to-market angle, capturing aftermarket revenue from Middle Eastern flag carrier wide-body fleets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical specialists with captive simulation capabilities over forging-integrated conglomerates facing pneumatic substitution headwinds. Five-to-ten year viability hinges on electrification roadmap alignment with divergent FAA and EASA certification timelines. Acquisition targets should demonstrate powder-bed fusion additive manufacturing and digital twin integration competencies. The signal to watch is consolidation velocity among Singapore and UAE MRO providers establishing dedicated valve repair capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Fire-Resistant Material Certification | EASA CS-25 Amendment 25-147 compliance unlocks European narrow-body retrofit procurement ahead of 2027 deadlines. |
| Additive Manufacturing Scale-Up | Powder-bed fusion capabilities compress FAA qualification timelines from thirty-six to eighteen months for electromechanical architectures. |
| Predictive Maintenance Platform Launch | Sensor-integrated valve assemblies enable condition-based monitoring revenue from Singapore and UAE repair stations. |
| Domestic Forging Partnership | India DGFT offset mandates require local assembly partnerships for indigenous combat aircraft hydraulic systems. |
| Solid-State Valve Array Development | German and American eVTOL developers specify distributed propulsion components displacing legacy pneumatic alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directive filings, EASA certification databases, and SEC 10-K disclosures from tier-one hydraulic suppliers. Primary interviews engaged aircraft valve procurement managers at Boeing and Airbus, MRO operations directors in Singapore and UAE, and superalloy forging executives in Wichita and Toulouse. Bottom-up segmentation modeling triangulates against top-down aerospace production forecasts from narrow-body program output rates.
Forecast inputs span fuel system, hydraulic, pneumatic, and air management applications across butterfly, ball, gate, and check valve product types. Electric, solenoid, pneumatic, and manual actuation technologies are modeled against OEM, MRO, military, and commercial end-user channels. CAGRs derive from correlated narrow-body production ramp rates and regulatory-driven replacement cycles. Superalloy forging capacity expansion and titanium sponge supply corridor stability inform input cost trajectories.
Stress conditions across titanium price volatility, EASA-FAA certification timeline divergence, and eVTOL electrification adoption curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on Boeing 737 MAX and Airbus A320neo output sustainability. Material shifts in export control regimes affecting superalloy forging technology transfer would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market