
 Canada Space Electronics Market | 2026-2036
Canada Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Space Electronics Market Insights
The capability gap between vertically integrated prime contractors and specialized component suppliers is reorganizing competitive dynamics across Canadian space electronics. MDA Space leverages its end-to-end satellite manufacturing footprint to dominate domestic procurement chains. Honeywell Aerospace Canada sustains long-term positioning through radiation-hardened avionics specialization. Kepler Communications competes via software-defined radio architectures for constellation-scale deployments.
Space electronics encompasses radiation-tolerant and radiation-hardened components, subsystems, and integrated assemblies engineered to operate across temperature extremes from -55°C to +125°C while surviving cumulative ionizing dose exposures exceeding 100 krad(Si). These systems enable reliable command, control, communication, and power management for spacecraft operating in low Earth orbit through deep space trajectories. Satellite Components leads product-type revenue generation due to recurring demand for bus and payload electronics across government and commercial programs. FPGA technology within the technology dimension captures expanding share as reprogrammable logic reduces mission-specific ASIC development cycles and qualification costs.
Health Canada and the Canadian Space Agency coordinate component qualification frameworks aligned with NASA-STD-8739 and ECSS-Q-ST-60-02C standards, creating dual-certification requirements that filter market access. The Department of National Defence's space procurement directives under the Defence Procurement Strategy further constrain supplier eligibility to domestically cleared entities. Stakeholders must monitor evolving export control harmonization between Canada's Controlled Goods Program and U.S. International Traffic in Arms Regulations, as reclassification of space-qualified electronics could abruptly reshape cross-border supply relationships and domestic manufacturing obligations.
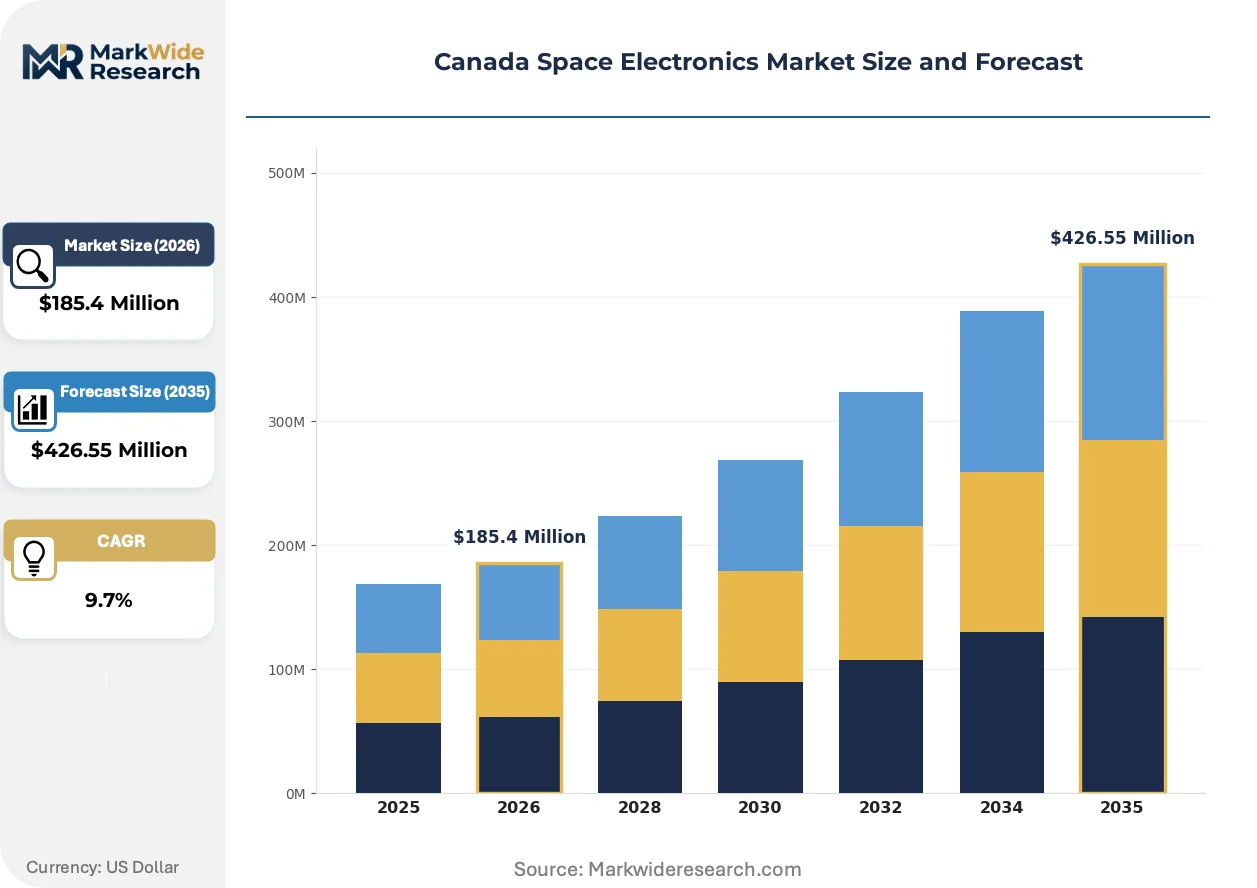
Market Dynamics
The Canadian Space Electronics Market is restructuring around satellite constellation deployment cycles, as operators demand radiation-hardened components with compressed qualification timelines that challenge traditional aerospace supply chains.
Growth Catalysts
- LEO Constellation Deployment:Satellite operators in Ontario's Greater Toronto Area corridor are scaling procurement of bus electronics for broadband and Earth observation networks. This concentrates demand within a single manufacturing cluster.
- NASA-STD-8739 Alignment:Health Canada's adoption of this soldering and workmanship standard streamlines dual-certification pathways for domestic suppliers seeking U.S. government contracts.
- FPGA Technology Maturation:Reprogrammable logic devices are reducing mission-specific ASIC development cycles, enabling faster payload customization for government science missions.
Market Restraints
- Rare Earth Element Concentration:Gallium nitride and silicon carbide substrates depend on concentrated overseas refining capacity, exposing Canadian fabricators to input volatility and export restriction risk.
- Domestic Clearance Requirements:The Department of National Defence's Defence Procurement Strategy restricts supplier eligibility to Controlled Goods Program-registered entities, filtering market access for foreign component vendors.
- Qualification Cost Barriers:Total ionizing dose testing to 100 krad(Si) thresholds requires specialized facilities at the Canadian Space Agency's David Florida Laboratory, creating bottleneck capacity for small suppliers.
Strategic Opportunities
- Arctic Surveillance Applications:The Department of National Defence's polar communications and weather monitoring mandates create dedicated demand for cold-tolerant electronics operating below -55°C.
- Software-Defined Radio Convergence:Integration of reconfigurable RF front-ends with radiation-tolerant digital backends enables multi-band payload architectures without hardware swaps.
- Provincial Manufacturing Incentives:Ontario's advanced manufacturing tax credits for space-related production equipment reduce capital intensity for domestic PCB fabrication and assembly expansion.
Industry Challenges
- Radiation Effects Engineering Talent:Canadian universities produce limited graduates with combined expertise in semiconductor physics and space environment modeling, constraining design team scaling.
- ITAR Harmonization Uncertainty:Pending reclassification of space-qualified electronics under U.S. export control reforms threatens to disrupt cross-border component flows and force domestic sourcing mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Space Electronics Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $426.55 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Components, Communication Systems, Power Systems, Avionics Application: Earth Observation, Telecommunications, Scientific Research, Navigation End User: Aerospace Manufacturers, Government Agencies, Research Institutions, Private Enterprises Technology: Microelectronics, FPGA, Analog, Digital |
| Companies Covered | MDA Space, Honeywell Aerospace Canada, ABB Canada, NGC Aérospatiale, Space Flight Laboratory, Canadensys Aerospace, Mission Control Space Services, Calian Group, Kepler Communications, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Space Electronics Market Trends and Innovations
Modular payload architectures are displacing monolithic satellite electronics, enabling constellation operators to refresh capabilities without full platform replacement. This shift compresses technology refresh cycles and reconfigures supplier relationships.
Software-defined radio platforms are decomposing traditional hardware-bound communication subsystems into reconfigurable digital layers. Constellation operators are adopting these architectures for frequency agility across LEO deployments. This decomposition is collapsing the distinction between payload and bus electronics, forcing subsystem suppliers to compete on firmware integration rather than discrete component performance.
Health Canada's regulatory alignment with ECSS-Q-ST-60-02C component qualification standards is creating dual-certification obligations for domestic suppliers. This harmonization expands addressable market access to European Space Agency programs. Small and mid-sized Canadian electronics vendors are responding by consolidating testing documentation to satisfy both NASA-STD-8739 and ECSS requirements within single qualification campaigns.
Consolidated procurement through prime contractor satellite manufacturing platforms is displacing direct component purchasing by government agencies. The Canadian Space Agency and Department of National Defence are channeling electronics acquisition through MDA Space and other domestic primes with end-to-end integration capabilities. This concentration is most visible in Ontario, where satellite manufacturing corridor density enables just-in-time component logistics that smaller suppliers struggle to match.
Canada Space Electronics Market Segmentation
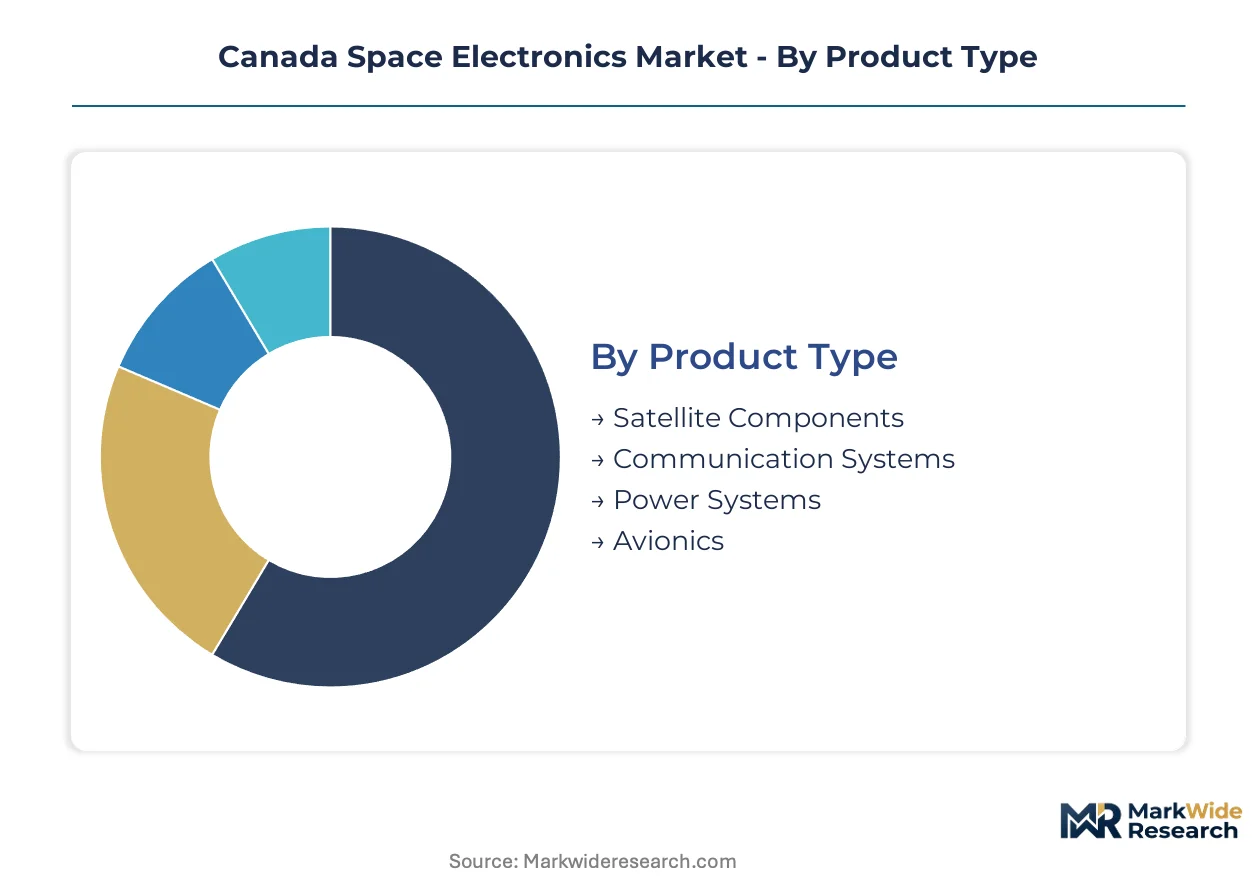
Segmentation in the Canadian Space Electronics Market reveals how procurement authority concentrates through prime contractors while technology choices reshape supplier relationships. Understanding these divisions exposes where qualification burdens fall heaviest and which component categories face displacement from reprogrammable alternatives.
Product Type:
FPGA maturation and software-defined architectures are exerting substitution pressure on discrete component categories, collapsing traditional distinctions between fixed-function and reconfigurable electronics.
- Satellite Components:Bus and payload electronics including command and data handling units, thermal control systems, and structural electronics. Ontario's Greater Toronto Area manufacturing corridor concentrates procurement for LEO constellation programs, with MDA Space channeling volume through vertically integrated supply chains.
- Communication Systems:Transponders, antennas, and RF subsystems enabling spacecraft-to-ground and inter-satellite links. Health Canada's NASA-STD-8739 alignment streamlines dual-certification for domestic suppliers targeting government science missions.
- Power Systems:Solar array drive electronics, battery management units, and power distribution modules.
- Avionics:Guidance, navigation, and control computers with radiation-hardened processing architectures.
Satellite Components retains volume leadership; FPGA-enabled Communication Systems holds the steepest expansion curve.
Application:
Application demand clusters around Defence Procurement Strategy mandates, with Department of National Defence polar surveillance requirements creating cold-tolerance specifications that filter supplier eligibility.
- Earth Observation:Payload electronics for optical, radar, and multispectral imaging satellites. The Canadian Space Agency's RADARSAT program and commercial operators in Ontario drive recurring bus electronics procurement with stringent radiation tolerance requirements.
- Telecommunications:Broadband constellation electronics for LEO data relay and direct-to-device services. Kepler Communications and other domestic operators are scaling software-defined radio deployments across polar orbital planes.
- Scientific Research:Instruments and subsystems for space astronomy, heliophysics, and planetary exploration missions.
- Navigation:Signal generation and timing electronics for positioning, navigation, and timing services.
Earth Observation commands the largest procurement footprint; Telecommunications is climbing the fastest as constellation deployment accelerates.
End User:
End user structure reflects the Defence Procurement Strategy's consolidation of electronics acquisition through prime contractors rather than direct agency purchasing.
- Aerospace Manufacturers:Prime contractors with end-to-end satellite integration capabilities. MDA Space dominates domestic procurement chains through its Brampton manufacturing campus, capturing Controlled Goods Program-cleared supplier relationships.
- Government Agencies:The Canadian Space Agency and Department of National Defence with mission-specific payload requirements. Health Canada's regulatory alignment with ECSS-Q-ST-60-02C creates dual-certification obligations for vendors seeking European Space Agency program access.
- Research Institutions:Universities and laboratories with CubeSat and small satellite development programs.
- Private Enterprises:Commercial operators and new entrants with constellation-scale electronics demand.
Aerospace Manufacturers anchor procurement volume; Private Enterprises are gaining share fastest as commercial constellation investment expands.
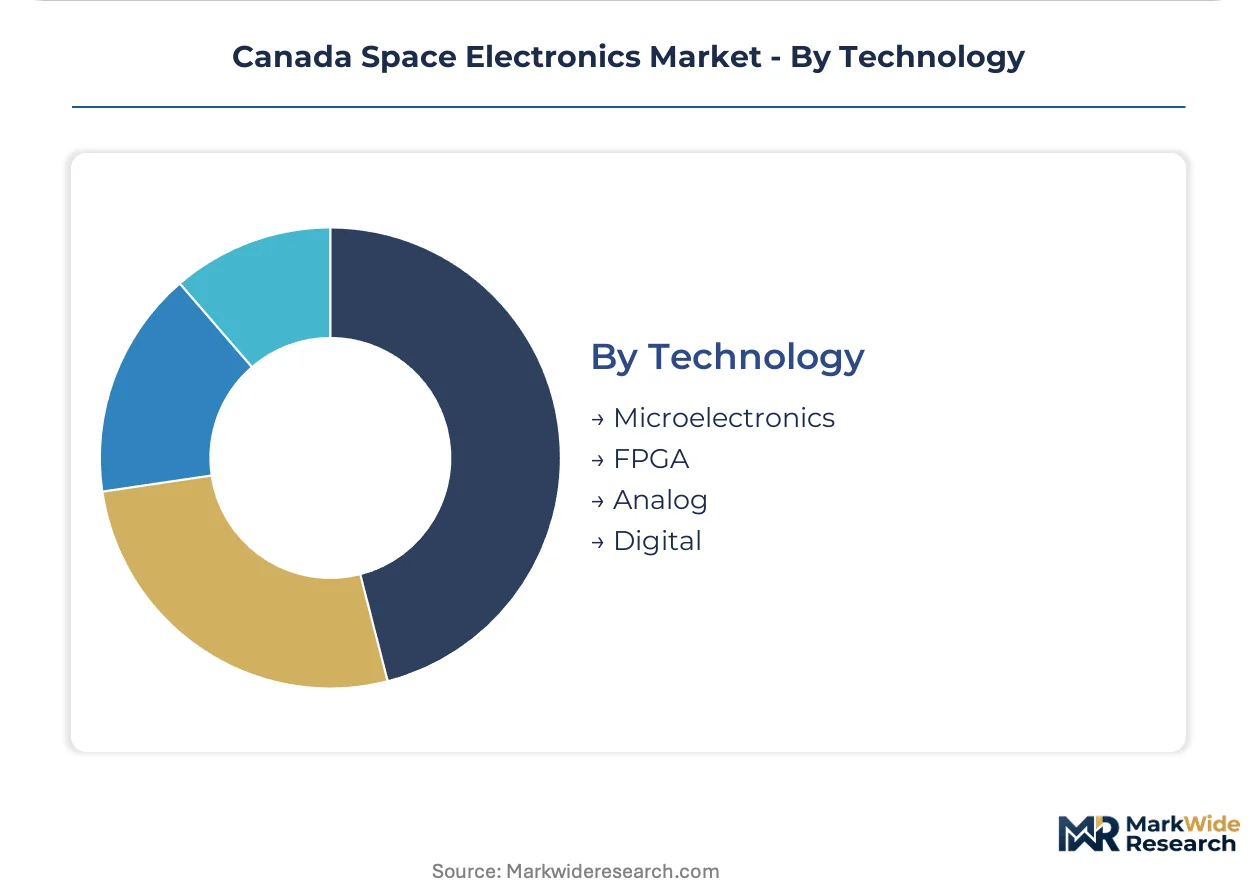
Technology:
Technology segmentation tracks the shift from fixed-function ASICs toward reprogrammable logic that compresses mission-specific development cycles.
- FPGA:Field-programmable gate arrays with radiation-tolerant and radiation-hardened variants. Reprogrammable logic reduces qualification costs and enables post-launch payload reconfiguration for government science missions.
- Microelectronics:Integrated circuits, processors, and memory devices with space-qualified packaging. David Florida Laboratory testing capacity creates bottleneck constraints for small suppliers seeking total ionizing dose certification to 100 krad(Si) thresholds.
- Analog:Sensors, amplifiers, and signal conditioning circuits with radiation-hardened performance.
- Digital:Discrete logic devices and interface circuits for command and data handling subsystems.
Microelectronics maintains installed base dominance; FPGA is expanding most quickly as reprogrammable architectures displace fixed-function alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario consumes space electronics differently than other Canadian provinces, channeling procurement through vertically integrated prime contractors rather than direct agency purchasing. Quebec and Western Canada operate more fragmented supplier networks with heavier reliance on foreign component sourcing.
Ontario
The Greater Toronto Area manufacturing corridor concentrates LEO constellation demand from MDA Space and Kepler Communications. Health Canada's NASA-STD-8739 alignment streamlines dual-certification for Brampton-area suppliers targeting U.S. government contracts. The David Florida Laboratory in Ottawa provides total ionizing dose testing capacity that bottlenecks qualification timelines for smaller vendors.
Quebec
Montreal's aerospace cluster sustains avionics and communication systems demand through NGC Aérospatiale and ABB Canada operations. The province's advanced manufacturing tax credits reduce capital intensity for PCB fabrication expansion. Controlled Goods Program registration requirements filter foreign supplier access to Department of National Defence polar surveillance programs.
British Columbia
Vancouver-area satellite operators and ground station developers drive demand for software-defined radio architectures. The province's proximity to Pacific Rim supply chains exposes fabricators to gallium nitride substrate volatility from concentrated overseas refining. Provincial clean technology incentives support cold-tolerant electronics development for Arctic applications.
Alberta
Calgary's energy sector spillover generates demand for ruggedized electronics applicable to space-qualified power systems. The province's limited domestic space manufacturing footprint forces reliance on Ontario-based prime contractor supply chains. Alberta Innovates funding programs target radiation effects engineering talent development to address national capability gaps.
Atlantic Canada
Halifax and St. John's harbor maritime surveillance applications creating demand for satellite communication downlink electronics. The region's distance from Ontario manufacturing clusters elevates logistics costs for radiation-hardened component procurement. Atlantic Canada Opportunities Agency programs support small satellite development at Memorial University and related research institutions.
Canada Space Electronics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Canadian space electronics procurement. MDA Space dominates domestic channels through captive satellite manufacturing capabilities, while Honeywell Aerospace Canada sustains positioning via radiation-hardened avionics specialization. The market organizes around three archetypes: vertically integrated primes with end-to-end capabilities, component specialists with qualification expertise, and constellation operators with software-defined architectures. Competitive moves concentrate on strategic partnerships for testing access and geographic expansion into provincial incentive zones.
Within the integrated prime tier, MDA Space and Honeywell Aerospace Canada exemplify contrasting positioning strategies. MDA Space anchors Ontario's manufacturing corridor through backward integration into satellite bus production. Honeywell Aerospace Canada occupies a specialist position leveraging long-standing radiation-hardening capabilities. Kepler Communications represents the constellation-operator archetype, competing through software-defined radio architectures rather than component manufacturing depth. These three players collectively illustrate how procurement authority concentrates through prime contractor platforms while technology choices reshape supplier relationships across the domestic market.
| Leading Market Players |
|---|
| MDA Space |
| Honeywell Aerospace Canada |
| ABB Canada |
| NGC Aérospatiale |
| Space Flight Laboratory |
| Canadensys Aerospace |
| Mission Control Space Services |
| Calian Group |
| Kepler Communications |
| Others |
Pricing and Supply Chain Analysis
FPGA substitution for mission-specific ASICs simultaneously shifts procurement geography toward reprogrammable logic suppliers and compresses pricing premiums previously commanded by custom silicon development cycles. Health Canada's dual-certification alignment with NASA-STD-8739 and ECSS-Q-ST-60-02C standards layers qualification cost burdens that stratify supplier tiers by certification depth.
Pricing Analysis
After-market service contracts and extended qualification support drive lifetime value for radiation-hardened component vendors. Pricing stratifies across radiation-tolerance grades, with 100 krad(Si) certified components commanding substantial premiums over commercial-off-the-shelf alternatives. Cost compression in FPGA-based subsystems is intensifying as reprogrammable architectures displace fixed-function ASICs across LEO constellation programs. Commercial satellite operators exhibit highest price sensitivity, while Department of National Defence mandates prioritize performance assurance over unit economics.
Supply Chain Analysis
China and Japan anchor gallium nitride and silicon carbide substrate refining capacity that Canadian fabricators draw from for power electronics. Rare earth element concentration in concentrated overseas processing creates single-source vulnerability for radiation-hardened semiconductor inputs. Distribution runs through Ontario's Greater Toronto Area manufacturing corridor, where MDA Space and Kepler Communications channel component procurement through vertically integrated prime contractor platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating through prime contractor consolidation, with MDA Space's captive satellite manufacturing capabilities shifting buyer power toward integrated platforms and away from direct government agency purchasing.
For Market Incumbents: Shield qualification expertise at the David Florida Laboratory by securing exclusive testing access agreements before capacity constraints worsen. Deepen backward integration into FPGA firmware development to capture value migrating from hardware to software layers. The threat of software-defined radio architectures collapsing payload-bus electronics distinctions demands defensive positioning in reconfigurable logic integration. For New Entrants and Emerging Players: Differentiate on cold-tolerance specifications below -55°C for Arctic surveillance applications where Department of National Defence mandates create dedicated demand. Target Alberta and Atlantic Canada regions where distance from Ontario manufacturing clusters elevates logistics costs and opens white-space for regional fabrication services. A go-to-market angle anchored in provincial manufacturing tax credit optimization reduces customer capital intensity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed component specialists holding Controlled Goods Program registration and ECSS dual-certification capabilities. Long-term viability hinges on qualification facility access rather than manufacturing scale alone. The signal to watch is Health Canada export control reclassification harmonization with U.S. ITAR reforms, which would abruptly reshape domestic sourcing mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Facility Expansion | David Florida Laboratory capacity additions reduce bottleneck constraints for small suppliers seeking 100 krad(Si) certification. |
| FPGA Firmware Platform Development | Reprogrammable logic integration captures value migrating from discrete components to software-defined architectures. |
| Dual-Certification Consolidation | Single-campaign qualification for NASA-STD-8739 and ECSS-Q-ST-60-02C expands addressable market to European Space Agency programs. |
| Arctic Cold-Tolerance Specialization | Electronics operating below -55°C align with Department of National Defence polar surveillance mandates. |
| Provincial Incentive Zone Expansion | Ontario advanced manufacturing tax credits reduce capital intensity for PCB fabrication and assembly operations. |
Research Methodology
A standing panel of satellite program managers, radiation effects engineers, procurement officers at prime contractors, and Canadian Space Agency qualification specialists provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation against CSA procurement databases, Department of National Defence contract disclosures, Health Canada regulatory filings, and ECSS standards documentation. Bottom-up component demand modeling and top-down program budget analysis were triangulated to cross-verify market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, end user, and technology choice, with particular attention to FPGA substitution dynamics and software-defined radio adoption curves. CAGRs were derived from year-over-year growth rate progression analysis applied to qualification-cleared supplier revenue trajectories and constellation deployment schedules.
Material uncertainties — ITAR reclassification timing, rare earth export restriction episodes, and radiation effects engineering talent pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and qualification pathway continuity that rapid policy shifts could invalidate. Recalibration cycles align with material shifts in Defence Procurement Strategy directives and Health Canada standards alignment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space on Board Computing Platform Market
Space
Space Rover Market
Space
Space Ground Station Equipment Market
Space
Asteroid Mining Market
Space
Europe Space Logistics Market
Space
Mexico Space Electronics Market
Space
Germany Space Electronics Market
Space
Suborbital Space Tourism Market
Space
Italy Space Electronics Market
Space
Space Mobile Service Market
Space
Space Launch Services Market
Space
Space-Based Solar Power Market
Space
Space in Orbit Refueling Market
Space
India Space Electronics Market
Space
Asia-Pacific Space Electronics Market