
 Jet Fuel Market | 2026-2036
Jet Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Jet Fuel Market Analysis
Middle Eastern refining capacity is narrowing the Atlantic Basin's historical supply surplus. Saudi Arabian Oil Company leverages integrated upstream-downstream assets to sustain export volumes across Asian markets. Exxon Mobil Corporation anchors North American supply through Gulf Coast refining complexes. BP plc competes on SAF co-processing capabilities at its Rotterdam and Whiting facilities.
Jet fuel comprises refined kerosene meeting strict flash point and freeze point specifications, typically produced through hydrocracking and hydrotreating of crude oil fractions to power gas turbine engines. Jet A-1 dominates transatlantic and intercontinental routes due to its lower freeze point, while military operations sustain demand for JP-8 and specialized variants with enhanced thermal stability. Commercial airlines generate the largest revenue pool, though cargo carriers represent the fastest-expanding end user segment as e-commerce logistics networks multiply dedicated freighter fleets.
EPA renewable fuel standards and ICAO Carbon Offsetting and Reduction Scheme for International Aviation compel US carriers to source certified sustainable aviation fuel, while EU ETS and ReFuelEU Aviation mandates hard-code blending percentages into European jet fuel specifications. China's GB standards and MIIT energy intensity targets shape domestic refinery output decisions. Stakeholders must monitor SAF certificate-of-sustainability traceability systems and offtake contract structures to secure feedstock access.
Market Dynamics
The EU Green Deal's SAF blending mandates are forcing a fundamental restructuring of refinery output decisions, as European carriers must secure certified sustainable feedstocks or face exclusion from continental airspace.
Growth Catalysts
- ReFuelEU Aviation mandates:Hard-coded blending percentages create guaranteed offtake volumes for SAF producers across EU member states.
- China's domestic aviation network expansion:MIIT energy intensity targets drive refinery capacity additions serving Beijing, Shanghai, and Guangzhou hub traffic.
- Hydroprocessed esters and fatty acids (HEFA):This pathway dominates near-term SAF supply as co-processing infrastructure scales at existing hydrotreating facilities.
Market Restraints
- Crude oil price volatility:Jet fuel crack spreads compress when upstream costs spike without corresponding ticket price pass-through.
- Middle Eastern supply concentration:Saudi Arabian Oil Company and ADNOC control marginal export barrels to Asian buyers.
- SAF feedstock scarcity:Used cooking oil and animal fat supplies face competition from biodiesel and oleochemical sectors.
Strategic Opportunities
- India's underserved tier-2 airport network:IndiGo and Air India Express expansion creates demand for imported Jet A-1 at non-metro terminals.
- Power-to-liquid Fischer-Tropsch synthesis:Renewable hydrogen and captured carbon convergence enables e-kerosene production at industrial clusters.
- Book-and-claim certificate trading:This channel innovation allows cargo carriers to meet sustainability targets without physical fuel lifting at every origin.
Industry Challenges
- ASTM D7566 annex qualification timelines:New alcohol-to-jet and gasification pathways face multi-year certification delays before commercial deployment.
- Jet fuel pipeline segregation:Common carrier systems cannot guarantee SAF molecule traceability from refinery to wing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jet Fuel Market |
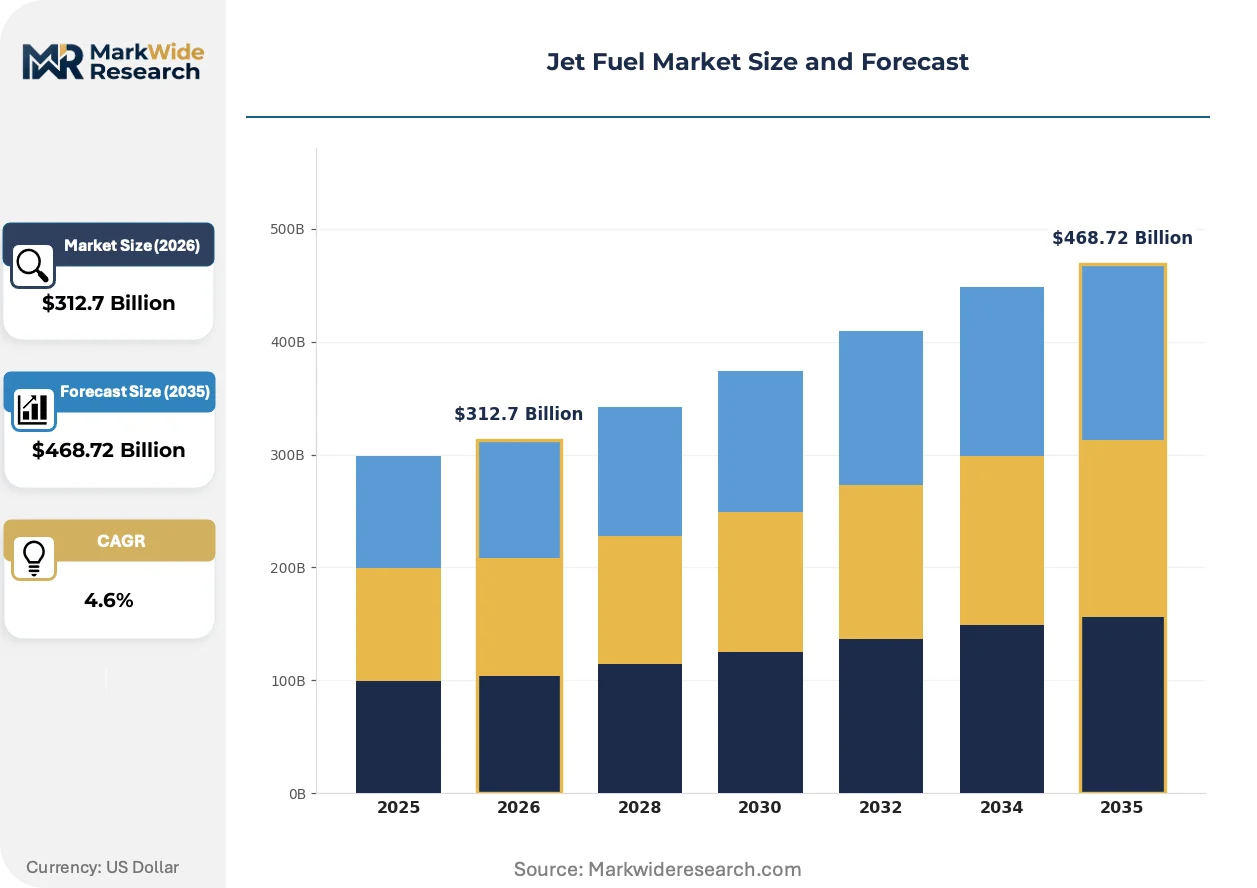
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $468.72 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, TS-1 End User: Commercial Airlines, Cargo Carriers, Military, Private Jets Distribution Channel: Direct Sales, Online Retail, Fuel Stations, Distributors Application: Aviation, Military Operations, Emergency Services, Recreational Flying |
| Companies Covered | BP plc, Neste Corporation, Exxon Mobil Corporation, Saudi Arabian Oil Company, China National Petroleum Corporation, Chevron Corporation, TotalEnergies, Petrobras, Royal Dutch Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jet Fuel Market Emerging Trajectories
Digital fuel management platforms are virtualizing physical supply chain coordination, compressing procurement cycles from monthly tenders to real-time spot optimization. This shift enables carriers to arbitrage regional price differentials while maintaining strict quality custody.
HEFA-SPK production is virtualizing traditional refinery economics by allowing hydrotreaters to swing between diesel and jet yields based on margin signals. European majors have reconfigured Rotterdam and Whiting units for this flexibility. The technology is virtualizing fixed asset utilization rates across the Atlantic Basin.
EU ETS carbon price integration into jet fuel contracts is reshaping European carrier hedging strategies. Airlines now face dual exposure: traditional crack spreads plus emissions allowance volatility. Lufthansa Group and Air France-KLM have established dedicated carbon trading desks to manage this layered risk.
Cargo carriers are consolidating procurement through dedicated freighter alliances, displacing fragmented airline-by-airline fuel purchasing. Amazon Air and DHL Express have negotiated direct refinery offtake agreements bypassing traditional into-plane agents. This concentration is most visible at Cincinnati, Leipzig, and Hong Kong cargo hubs where dedicated terminals anchor volume commitments.
Jet Fuel Market Segmentation
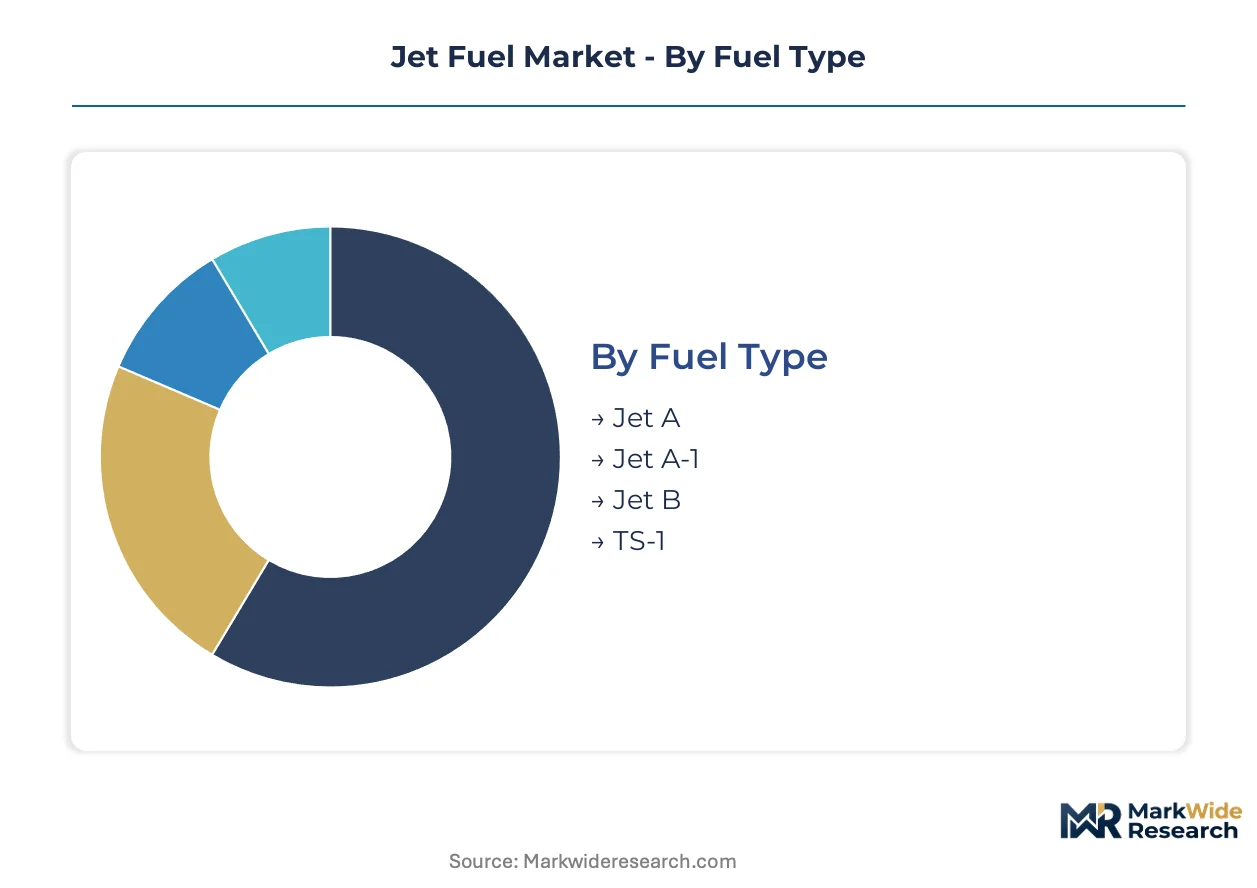
Jet fuel procurement decisions diverge sharply across fuel specifications, operator scale, and delivery infrastructure. Each segmentation dimension carries distinct margin structures and regulatory exposure that reshape competitive positioning for refiners and carriers alike.
Fuel Type:
Cost tier differentiation separates commodity kerosene from specialized formulations with freeze-point and thermal-stability premiums.
- Jet A-1:Refined kerosene meeting DEF STAN 91-91 and ASTM D1655 specifications with a -47°C freeze point. Transatlantic and intercontinental routes concentrate demand as carriers optimize for cold-weather performance over polar corridors.
- Jet A:Slightly higher freeze point specification (-40°C) dominates North American domestic trunk routes. US carriers favor this grade for cost efficiency on temperate-zone operations where extreme cold exposure remains limited.
- Jet B:Wide-cut gasoline-kerosene blend serving cold-climate airports in Canada and Alaska. Military forward operating locations sustain niche demand for this lower-flash-point variant.
- TS-1:Russian-origin specification with enhanced thermal stability requirements. Former Soviet bloc states and certain Chinese domestic routes maintain offtake for this legacy grade.
Jet A-1 commands the established base. The steepest expansion runs through Jet A as US domestic network density climbs.
End User:
Customer type segmentation reveals diverging procurement sophistication and sustainability compliance burdens.
- Cargo Carriers:Dedicated freighter operators from Amazon Air to DHL Express negotiate direct refinery offtake agreements. E-commerce logistics multiplication drives fleet expansion and consolidated fuel purchasing power at Cincinnati, Leipzig, and Hong Kong hubs.
- Commercial Airlines:Full-service and low-cost carriers generate the largest absolute volume pool. Lufthansa Group and Air France-KLM have established dedicated carbon trading desks to manage EU ETS exposure layered atop traditional crack spread hedging.
- Military:Defense ministries sustain demand for JP-8 and specialized variants with enhanced thermal stability and lubricity additives. NATO standardization efforts are gradually displacing national specifications.
- Private Jets:Fractional ownership fleets and high-net-worth operators purchase through fixed-base operators with into-plane service contracts. Sustainability certificate purchasing outpaces physical SAF lifting in this segment.
Commercial Airlines anchor volume concentration. Cargo Carriers are climbing the fastest as dedicated freighter deliveries accelerate.
Distribution Channel:
Supply concentration varies dramatically by channel structure and custody transfer points.
- Direct Sales:Major carriers negotiate term contracts with integrated oil companies bypassing intermediaries. Saudi Arabian Oil Company and Exxon Mobil Corporation anchor these relationships through captive refining capacity.
- Distributors:Independent marketers aggregate fragmented demand from regional carriers and general aviation. This channel carries highest price volatility exposure due to inventory timing risk.
- Fuel Stations:Fixed-base operators at general aviation airports serve private jet and recreational demand. Into-plane fees and storage charges compound landed costs significantly.
- Online Retail:Digital platforms for spot market access and contract management are virtualizing procurement cycles. Real-time optimization now compresses tender periods from monthly to intraday.
Direct Sales captures the premium relationship tier. Distributors are gaining share fastest as tier-2 airport networks expand in India and Southeast Asia.
Application:
Volume and maturity separate established aviation operations from emerging use cases with specialized fuel requirements.
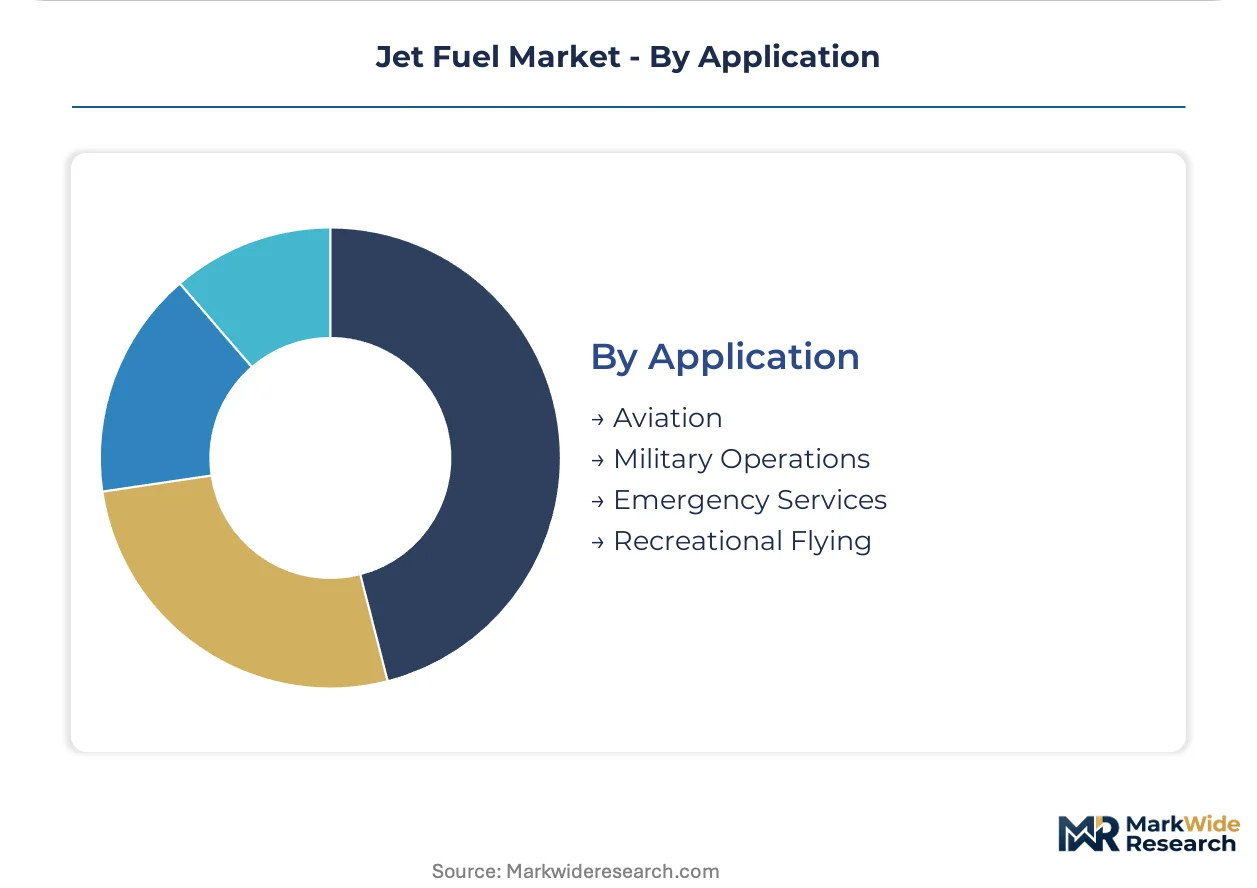
- Aviation:Scheduled passenger and cargo services constitute the core demand base. Refinery output decisions swing between diesel and jet yields based on margin signals from HEFA co-processing flexibility.
- Military Operations:Tactical and strategic airlift requirements sustain demand for specialized formulations with enhanced thermal stability. Single-fuel policies are consolidating JP-8 adoption across ground and air platforms.
- Emergency Services:Air ambulance and search-and-rescue operators require guaranteed supply access with minimal notice. This segment pays significant premiums for supply security and rapid response.
- Recreational Flying:Flight training and private pilot activity generates scattered demand through small-volume purchases. AVGAS-Jet A substitution debates continue for piston-engine applications.
Aviation dominates the volume base. Emergency Services are expanding most quickly as healthcare network coverage requirements tighten response time standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT energy intensity targets anchor Chinese refinery output decisions as domestic aviation network density climbs. The EU Green Deal's SAF blending mandates force European carriers to restructure procurement. Refinery capacity additions concentrate around Beijing, Shanghai, and Guangzhou hub traffic.
United States
EPA renewable fuel standards compel carriers to source certified sustainable aviation fuel. The FAA coordinates ASTM D7566 pathway qualification timelines for alcohol-to-jet technologies. Gulf Coast refining complexes anchor North American supply through integrated hydrocracking and hydrotreating infrastructure.
China
GB standards and MIIT energy intensity targets shape domestic refinery output decisions. The country's national aviation regulator mandates fuel quality specifications for expanding hub operations. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate new capacity serving international route growth.
Germany
EU ETS carbon price integration reshapes carrier hedging strategies alongside traditional crack spread exposure. ReFuelEU Aviation mandates hard-code blending percentages into jet fuel specifications. Frankfurt and Munich airports anchor SAF certificate-of-sustainability traceability system deployment.
India
IndiGo and Air India Express expansion creates demand for imported Jet A-1 at tier-2 terminals. The country's petroleum regulator oversees fuel quality standards for non-metro airport network growth. Maharashtra and Gujarat refining corridors scale hydrotreater flexibility between diesel and jet yields.
United Arab Emirates
ADNOC controls marginal export barrels to Asian buyers through integrated upstream-downstream assets. The country's civil aviation authority coordinates fuel supply security for Dubai and Abu Dhabi hub operations. Jebel Ali refining complex sustains export volumes across Indian Ocean markets.
Jet Fuel Market Vendor Landscape
Integrated majors and national oil companies split the market through contrasting asset configurations. Consolidation concentrates around upstream-downstream integration depth rather than geographic coverage breadth. Strategic archetypes divide between Gulf-based export refiners and European SAF co-processing specialists. Capacity expansion and strategic partnerships dominate competitive moves as players secure feedstock access.
Within the integrated major tier, BP plc and Exxon Mobil Corporation exemplify divergent regional anchoring strategies. Saudi Arabian Oil Company represents the Gulf-based export refiner archetype with captive crude supply. These three entities occupy positions spanning Atlantic Basin and Asian market access through differentiated infrastructure footprints.
| Leading Market Players |
|---|
| BP plc |
| Neste Corporation |
| Exxon Mobil Corporation |
| Saudi Arabian Oil Company |
| China National Petroleum Corporation |
| Chevron Corporation |
| TotalEnergies |
| Petrobras |
| Royal Dutch Shell plc |
| Others |
Supply Flow & Price Mechanics
The Singapore-Rotterdam freight corridor compresses procurement economics as Middle Eastern export barrels compete with Atlantic Basin refining output for Asian carrier offtake. This logistics tension concentrates pricing power with integrated upstream-downstream majors while forcing downstream buyers into long-term contract structures that lock in volume security against spot volatility.
Pricing Analysis
Atlantic Basin and Asian spot markets diverge by four to six dollars per barrel depending on arbitrage window timing and inventory positioning at Singapore and Fujairah storage hubs. Jet fuel pricing stratifies across SAF-certified, Jet A-1 specification, and Jet A domestic grades with freeze point and sustainability certification driving tier separation. Cost compression in conventional kerosene runs through crude price volatility without corresponding ticket price pass-through elasticity. Cargo carriers at Cincinnati and Leipzig hubs demonstrate lowest price sensitivity due to consolidated direct refinery contracts, while regional distributors at India's tier-2 airports face highest margin pressure from inventory timing risk.
Supply Chain Analysis
Export control regimes on hydrocracking catalyst technology limit refinery capacity expansion in certain markets, concentrating marginal supply growth with holders of licensed process designs. Saudi Arabia, the United Arab Emirates, and the United States anchor global supply through integrated refining complexes with captive crude access. Feedstock dependencies center on medium and heavy sour crude slate availability, hydrogen supply for hydrotreating, and HEFA pathway feedstocks including used cooking oil and animal fat. Single-source vulnerability concentrates in Middle Eastern export barrels controlled by Saudi Arabian Oil Company and ADNOC. Distribution runs through common carrier pipeline systems with into-plane agents at major hubs and direct refinery offtake for consolidated cargo carrier demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified SAF production capability sits as the binding constraint across European and North American markets, with ASTM D7566 pathway qualification timelines extending three to five years and feedstock access contested by biodiesel and oleochemical competitors. This capability gap separates integrated majors with co-processing infrastructure from aspirants lacking hydrotreater flexibility or certified supply chain traceability systems.
For Market Incumbents: Harden refinery asset utilization through HEFA-SPK co-processing flexibility at Rotterdam, Whiting, and Gulf Coast facilities, swinging yields between diesel and jet based on real-time margin signals. Deepen backward integration into used cooking oil and animal fat collection networks to secure feedstock access against biodiesel sector competition. Prioritize ASTM D7566 annex qualification investment for alcohol-to-jet and gasification pathways ahead of regulatory mandate acceleration.
For New Entrants and Emerging Players: Pursue power-to-liquid Fischer-Tropsch synthesis at industrial clusters with converging renewable hydrogen and captured carbon supply, targeting e-kerosene production ahead of ReFuelEU Aviation mandate escalation. India's tier-2 airport network expansion offers the most penetrable geography as IndiGo and Air India Express scale non-metro operations with imported Jet A-1 demand. Establish book-and-claim certificate trading platforms to capture cargo carrier sustainability compliance spend without physical fuel lifting infrastructure.
For Investors and Strategic Acquirers: Mid-scale SAF technology licensors with qualified ASTM D7566 pathways and locked feedstock offtake agreements represent the priority acquisition archetype for portfolio exposure to mandated blending volume growth. Long-term viability hinges on securing certificate-of-sustainability traceability systems and co-processing infrastructure ahead of 2030 regulatory inflection. Monitor EU ETS carbon price integration into jet fuel contract structures as the signal indicating carrier hedging strategy maturation and SAF premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| HEFA Co-Processing Retrofit | Enables hydrotreater yield flexibility between diesel and jet at Rotterdam and Whiting facilities. |
| Feedstock Supply Agreement | Locks used cooking oil and animal fat access against biodiesel sector competition for SAF production. |
| ASTM D7566 Pathway Qualification | Accelerates alcohol-to-jet and gasification technology commercial deployment timelines. |
| Book-and-Claim Platform Launch | Virtualizes SAF molecule traceability for cargo carrier compliance without physical lifting. |
| Carbon Trading Desk Establishment | Manages layered EU ETS exposure atop traditional crack spread hedging for European carriers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EIA data, IEA reports, customs and trade flow databases, and SEC filings from integrated oil companies, validated through structured interviews with refinery operations managers, airline fuel procurement directors, sustainable aviation fuel technology licensors, and into-plane service providers at major hub airports. Bottom-up segmentation modeling triangulates against top-down macro demand projections across fuel type, end user category, distribution channel, and application dimensions.
Forecast inputs incorporate hydrocracking and hydrotreating capacity utilization rates, crude slate availability and quality shifts, regulatory mandate implementation timelines including ReFuelEU Aviation and EPA renewable fuel standards, and aviation traffic recovery trajectories across passenger and cargo segments. CAGRs derive from regression analysis against historical jet fuel crack spreads and forward curve structures. Modeled dimensions span fuel specification tier, operator scale, delivery infrastructure type, and regional regulatory framework cluster.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, carbon credit market liquidity, or aviation demand cyclicality would shift the trajectory. Forecasts reflect documented assumptions regarding ASTM D7566 pathway qualification timelines, SAF feedstock supply elasticity, and refinery capacity addition schedules. Material shifts in EU ETS carbon price levels, Middle Eastern export policy, or breakthrough power-to-liquid cost reduction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market