
 Fuel Tank Inerting Systems Market | 2026-2036
Fuel Tank Inerting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Fuel Tank Inerting Systems Market Analytics
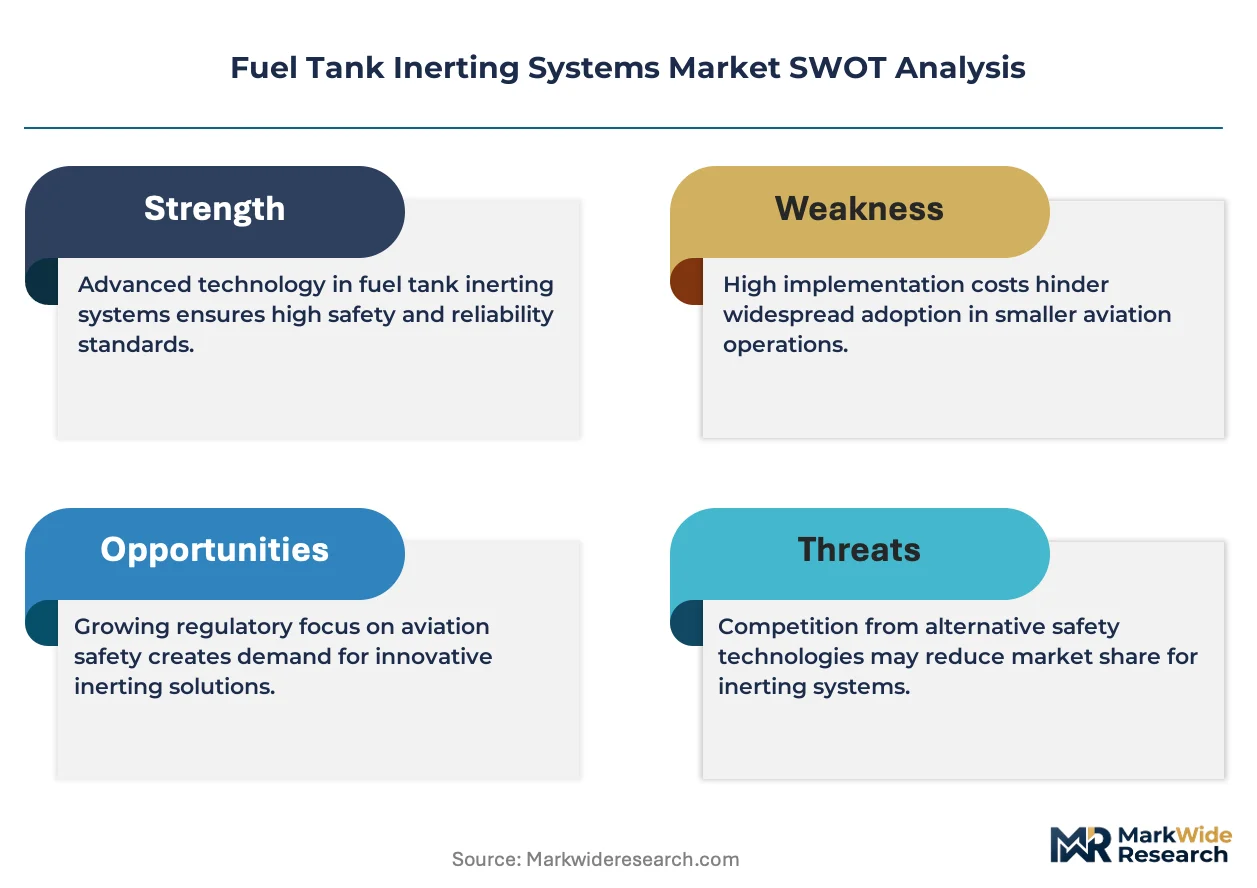
Buyer concentration among aerospace OEMs and military contractors is hardening as fleet modernization programs consolidate procurement decisions around fewer platform integrators. Honeywell International leverages its integrated avionics footprint to bundle inerting systems with broader fuel management suites. Eaton Corporation anchors its position through specialized control system architectures that govern nitrogen generation rates across variable flight profiles. Parker Hannifin Corporation competes on fluid distribution expertise, extending its legacy hose and fitting dominance into gas distribution unit design for tank ullage inerting.
Fuel tank inerting systems generate nitrogen-enriched air through membrane separation or pressure swing adsorption, then distribute this inert gas into aircraft fuel tank ullage spaces to suppress explosive vapor ignition. Membrane separation technology dominates commercial aerospace installations due to lower weight and maintenance burden compared with cryogenic alternatives. Control systems capture the highest margin pool within the component stack, as software-governed nitrogen concentration monitoring commands premium pricing against commodity hardware. Aerospace OEMs represent the most concentrated end user segment, though shipping companies are emerging as a secondary demand vector driven by updated International Maritime Organization safety protocols for tanker vapor management.
FAA airworthiness directives mandate fuel tank system safety assessments that directly compel retrofit investments across aging commercial fleets. EASA and the FAA coordinate harmonized certification standards for nitrogen generation system performance, reducing regulatory fragmentation for dual-certified platform suppliers. Military contractors face supplemental MIL-STD-882 system safety requirements that layer additional testing protocols onto baseline commercial designs. Stakeholders must monitor the divergence between civilian and military certification timelines, as defense program delays risk stranding engineering resources committed to dual-use platform development.
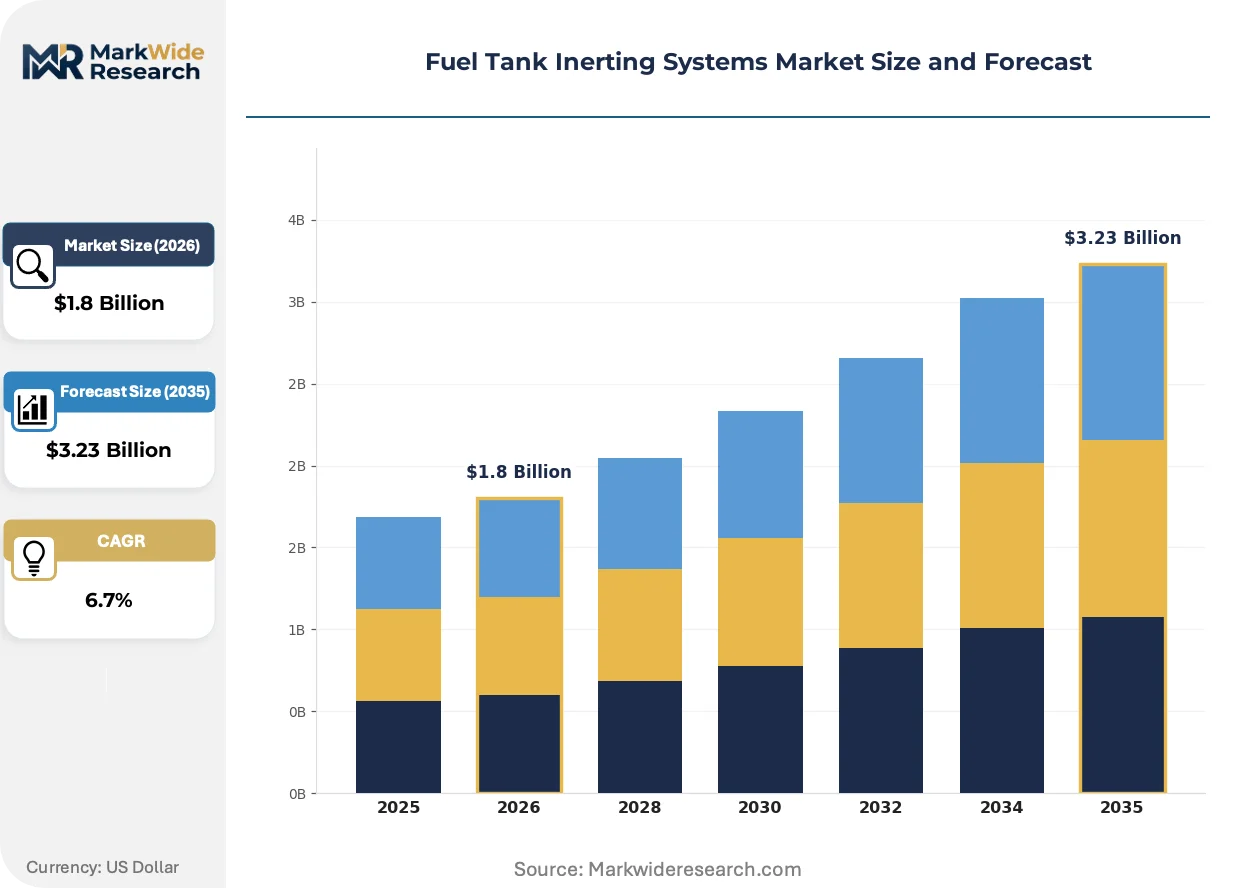
Market Dynamics
Fleet modernization mandates from the FAA are compressing retrofit timelines across aging narrow-body aircraft, forcing nitrogen generation system suppliers to accelerate certification cycles while managing membrane material lead times.
Growth Catalysts
- FAA Airworthiness Directives:Mandates for fuel tank flammability reduction compel commercial carriers to install nitrogen-enriched air systems on in-service aircraft.
- Membrane Separation Technology:Hollow-fiber membrane modules deliver weight savings over pressure swing adsorption, driving adoption in single-aisle platforms.
- United States Fleet Density:The largest installed base of commercial and military aircraft sustains concentrated demand for retrofit and line-fit inerting hardware.
Market Restraints
- Specialized Polymer Supply Concentration:Hollow-fiber membrane production depends on a limited supplier base in Germany and Japan, creating input vulnerability.
- MIL-STD-882 Testing Burden:Military certification requirements layer additional validation protocols onto commercial designs, extending program timelines.
- Cryogenic Nitrogen Infrastructure:Ground-based liquid nitrogen systems remain viable for certain cargo and maintenance applications, limiting addressable market expansion.
Strategic Opportunities
- Maritime Tanker Applications:International Maritime Organization safety protocols for vapor management are opening secondary demand from shipping operators.
- Control System Software Convergence:Integration of nitrogen concentration monitoring with predictive maintenance platforms creates aftermarket service attach rates.
- India Fleet Expansion:Low-cost carrier growth and indigenous regional jet programs present greenfield installation opportunities outside saturated Western markets.
Industry Challenges
- Dual-Use Certification Coordination:Divergence between FAA commercial timelines and defense program delays risks stranding engineering resources committed to dual-certified platforms.
- Legacy Aircraft Integration Complexity:Retrofit installations on aging Boeing 737 NG and Airbus A320ceo families require custom structural modifications and wiring harness adaptations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuel Tank Inerting Systems Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Separation, Pressure Swing Adsorption, Cryogenic Distillation, Chemical Absorption Component: Inert Gas Generators, Control Systems, Sensors, Gas Distribution Units Application: Aerospace, Marine, Transportation, Storage Solutions End User: Aerospace OEMs, Shipping Companies, Fuel Storage Facilities, Military Contractors |
| Companies Covered | Honeywell International, Eaton Corporation, Parker Hannifin Corporation, Collins Aerospace, Safran, Woodward, Liebherr-International, Air Liquide, Crane Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuel Tank Inerting Systems Market Evolving Landscape
Active sensor networks and machine-learning diagnostics are transforming inerting system architectures from passive hardware installations into intelligent, condition-monitored assets that reduce unscheduled maintenance.
Machine-learning-based predictive maintenance software is automating nitrogen generation rate adjustments based on real-time fuel load, altitude, and temperature data. Commercial airlines with high-utilization narrow-body fleets are deploying these systems fastest. This capability is automating the transition from scheduled component replacement to condition-based maintenance, compressing aftermarket service intervals.
The FAA and EASA harmonization initiative on nitrogen generation system performance standards is reducing regulatory fragmentation for dual-certified suppliers. Manufacturers now submit single certification packages covering both jurisdictions. Wide-body OEMs with transatlantic operational profiles are capturing the greatest compliance efficiency gains from this coordination.
Airline procurement departments are consolidating inerting system purchases into multi-year airframe maintenance contracts rather than standalone component acquisitions. Lessors and asset managers are driving this bundling to simplify lease return conditions. This pattern is most pronounced among United States-based fleet operators with standardized narrow-body configurations.
Fuel Tank Inerting Systems Market Segmentation
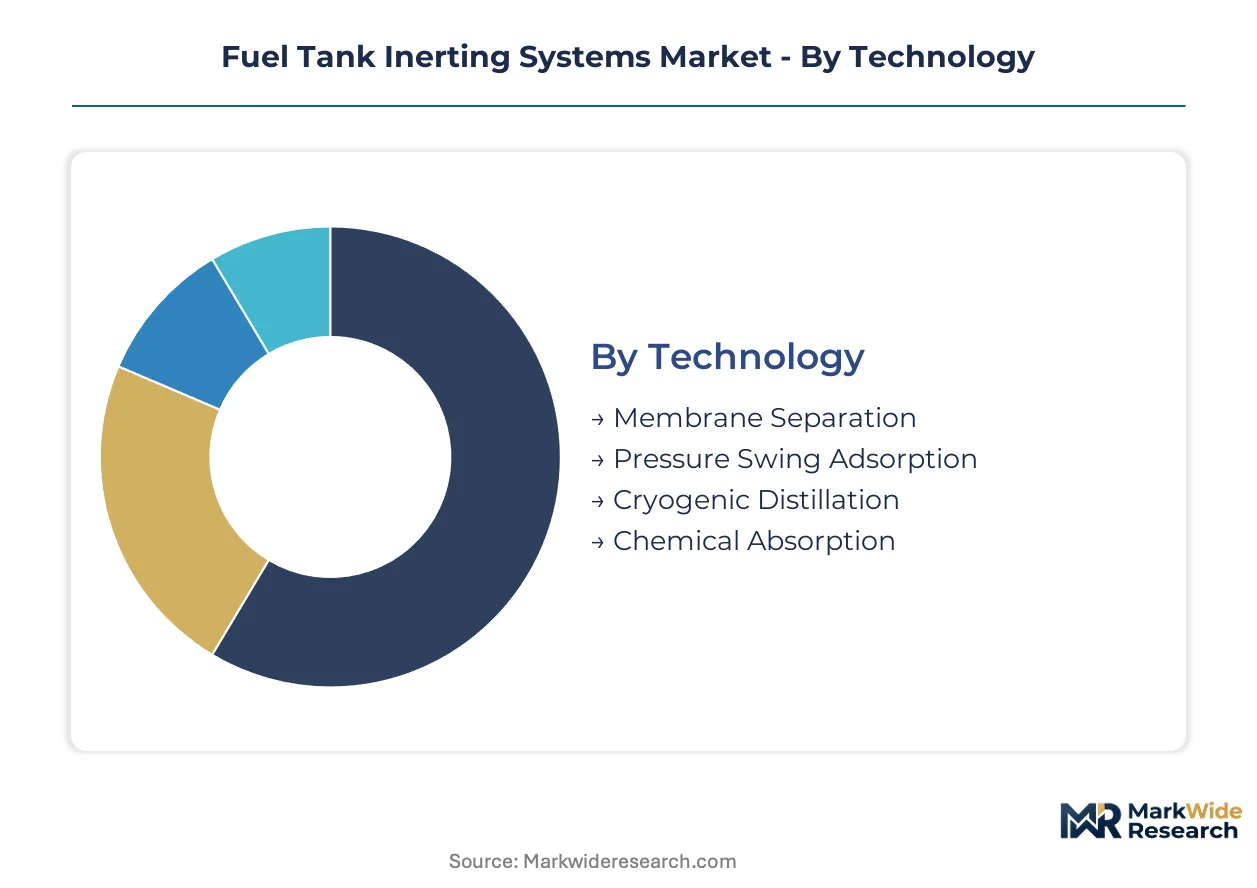
Segmentation in fuel tank inerting systems reveals how nitrogen generation technology, control architectures, and end-use requirements diverge across aerospace, maritime, and defense applications. Procurement patterns vary sharply between line-fit OEM programs and aftermarket retrofit installations.
Technology:
Standardization dominates membrane-based platforms while cryogenic and chemical methods serve niche performance thresholds.
- Membrane Separation:Hollow-fiber polymer membranes extract nitrogen from engine bleed air through selective permeation, producing 95-98% nitrogen purity. Commercial narrow-body fleets in the United States specify this technology for weight and reliability advantages. FAA airworthiness directives on fuel tank flammability reduction mandate retrofits that favor this lower-maintenance approach.
- Pressure Swing Adsorption:Zeolite molecular sieves cycle between pressurization and depressurization to separate nitrogen from ambient air, achieving higher purity levels than membrane systems. Military tanker aircraft and specialized cargo platforms require this technology for mission-critical vapor suppression where nitrogen concentration must exceed 99%.
- Cryogenic Distillation:Liquid nitrogen generation through fractional distillation serves ground-based fuel storage facilities with continuous high-volume requirements.
- Chemical Absorption:Amine-based scrubbing systems remove oxygen through chemical reaction, deployed in legacy maritime installations with established maintenance protocols.
Most installed capacity flows through Membrane Separation. Expansion is steepest in Pressure Swing Adsorption.
Component:
Margin concentration shifts upstream toward software-governed control architectures and away from commodity hardware.
- Control Systems:Programmable logic controllers govern nitrogen generation rates, tank ullage pressure, and system fault isolation through integrated sensor feedback. These units capture premium pricing in aftermarket service contracts. Predictive maintenance software integration is compressing scheduled replacement intervals for United States-based fleet operators.
- Inert Gas Generators:Engine bleed air processing modules combine filtration, temperature conditioning, and membrane separation in compact line-replaceable units. Single-aisle commercial aircraft specify standardized generator configurations that simplify logistics across high-utilization fleets.
- Sensors:Oxygen concentration and pressure transducers provide real-time ullage monitoring for closed-loop control.
- Gas Distribution Units:Manifold and valve assemblies route nitrogen-enriched air to multiple fuel tank compartments.
Control Systems command the highest margin pool. Inert Gas Generators ship the greatest unit volume.
Application:
Certification intensity separates aerospace from adjacent sectors with lighter regulatory burdens.
- Aerospace:Commercial and military aircraft fuel tank protection drives the largest addressable demand, spanning line-fit production and mandated retrofit programs. FAA-EASA harmonization on nitrogen generation standards reduces dual-certification overhead for platform suppliers serving transatlantic operators.
- Marine:Tanker cargo vapor management and bunker fuel storage protection are expanding under International Maritime Organization safety protocols. Shipping operators in Singapore and Rotterdam are retrofitting inert gas systems to meet updated vapor emission controls.
- Transportation:Rail and heavy-duty vehicle fuel cell hydrogen storage requires specialized inerting for cryogenic tank integrity.
- Storage Solutions:Above-ground and underground fuel depot vapor suppression serves military logistics and strategic petroleum reserve facilities.
Aerospace absorbs the majority of engineering resources. Marine applications are climbing the fastest.
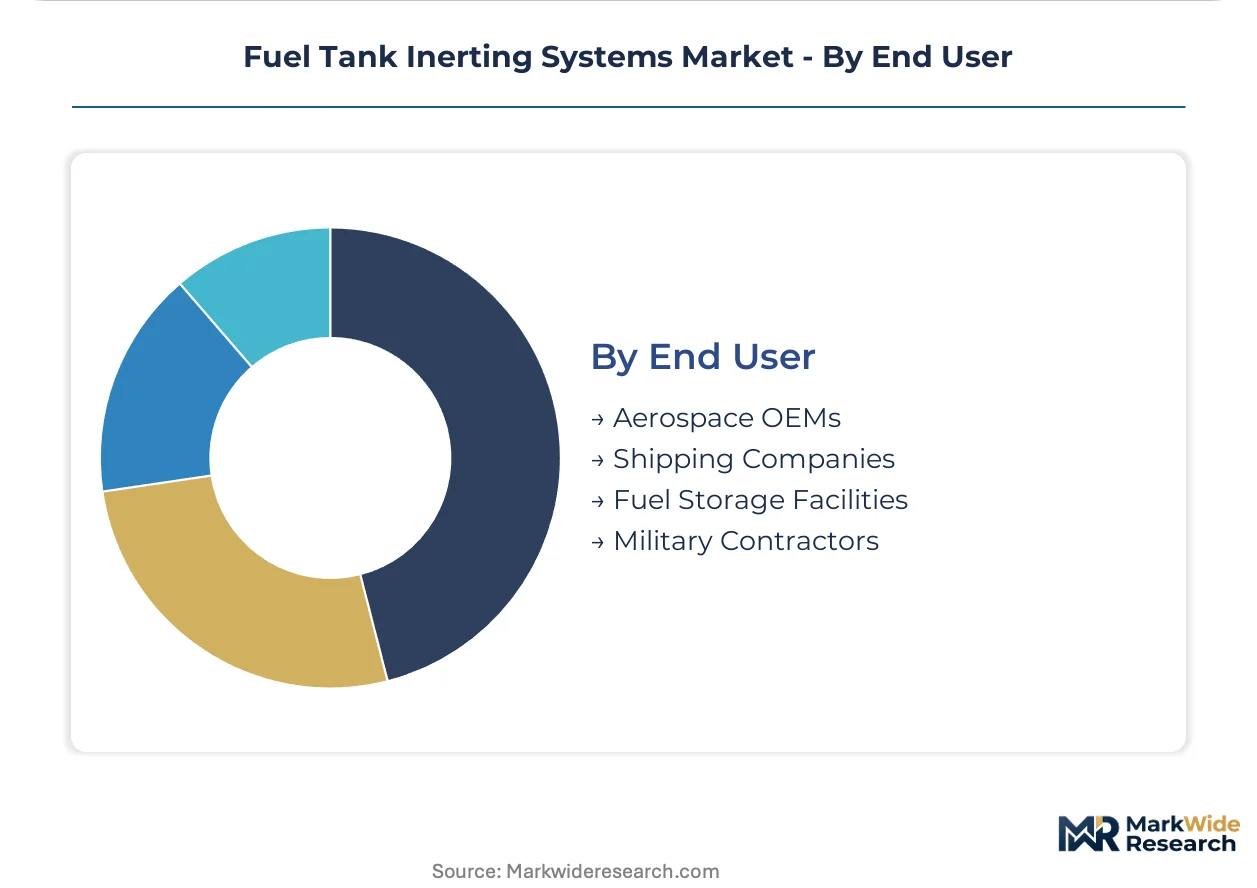
End User:
Procurement consolidation among fleet operators is compressing supplier margins while expanding contract durations.
- Aerospace OEMs:Boeing and Airbus specify inerting systems during airframe design, integrating nitrogen generation with centralized fuel management architectures. Line-fit procurement concentrates decisions among fewer platform integrators as fleet modernization programs consolidate.
- Military Contractors:Defense primes layer MIL-STD-882 system safety requirements onto baseline commercial designs, extending validation timelines. Program delays risk stranding engineering resources committed to dual-use platform development.
- Shipping Companies:Tanker operators and container lines are emerging as secondary demand vectors driven by maritime safety regulations.
- Fuel Storage Facilities:Strategic depot operators specify ground-based nitrogen generation for large-scale vapor management.
Aerospace OEMs concentrate the largest procurement volume. Shipping Companies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace engineering talent clusters in the United States, Germany, and France anchor the industry's geographic footprint. FAA mandates and EASA harmonization protocols concentrate procurement decisions within these jurisdictions.
United States
Boeing's commercial and defense platforms sustain the largest installed base of retrofit programs. FAA airworthiness directives on fuel tank flammability reduction compel nitrogen generation system installations across aging narrow-body fleets. Wichita, Kansas and Seattle, Washington host concentrated supplier engineering operations serving these mandates.
Germany
Specialized polymer supply for hollow-fiber membrane production concentrates in German chemical manufacturing clusters. EASA certification standards coordinate with FAA protocols, reducing dual-certification overhead for platform suppliers. Munich and Hamburg anchor aerospace supplier development for nitrogen generation control architectures.
France
Airbus line-fit programs drive specification authority for integrated fuel management suites. ANSM and EASA regulatory coordination shapes nitrogen purity standards for commercial aviation applications. Toulouse and Nantes sustain engineering centers governing membrane separation module integration.
Japan
Advanced materials suppliers in Osaka and Nagoya produce high-performance polymers for membrane separation technology. METI industrial policy supports aerospace component manufacturing for export markets. Japanese suppliers serve as secondary sources for hollow-fiber membrane inputs to Western system integrators.
Singapore
Maritime tanker retrofit demand is accelerating under International Maritime Organization vapor management protocols. The Port of Singapore and Jurong shipyard cluster host installation capacity for inert gas systems on LNG carriers and product tankers. Singapore-based shipping operators are consolidating procurement for regional fleet compliance.
Fuel Tank Inerting Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across membrane technology, control systems, and gas distribution hardware. The supplier base organizes into three tiers: integrated avionics providers bundling inerting with fuel management suites; specialized fluid control engineers governing nitrogen generation rates; and component suppliers extending legacy hose and fitting expertise into gas distribution design. Consolidation pressures intensify as fleet operators bundle procurement into multi-year airframe maintenance contracts. Strategic partnerships between membrane material suppliers and system integrators are displacing standalone component sourcing.
Among diversified industrial conglomerates, Honeywell International, Eaton Corporation, and Parker Hannifin Corporation exemplify contrasting competitive positions. Honeywell occupies a position representing integrated avionics bundling. Eaton exemplifies specialized control system architecture development. Parker Hannifin anchors the fluid distribution tier, extending legacy expertise into gas distribution unit design. These three structures illustrate how procurement consolidation favors players with adjacent fuel management capabilities over standalone inerting specialists.
| Leading Market Players |
|---|
| Honeywell International |
| Eaton Corporation |
| Parker Hannifin Corporation |
| Collins Aerospace |
| Safran |
| Woodward |
| Liebherr-International |
| Air Liquide |
| Crane Co. |
| Others |
Value Network & Pricing Analysis
FAA airworthiness directive compliance deadlines are compressing procurement timelines for nitrogen generation systems, forcing membrane material suppliers to prioritize certified production lines and elevating pricing power for qualified vendors over commodity competitors.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for hollow-fiber membrane modules, yet three-tier pricing structure across premium, standard, and economy levels persists due to FAA-EASA certification tier differentiation. Price differentiation stems from nitrogen purity thresholds and predictive maintenance software bundling. Cost compression in standard-tier hardware is intensifying because airline procurement departments are consolidating purchases into multi-year airframe maintenance contracts. Regional jet operators in India exhibit highest price sensitivity, while United States-based narrow-body fleet operators with standardized configurations demonstrate lowest sensitivity due to lease-return condition simplification priorities.
Supply Chain Analysis
FAA-EASA harmonized certification standards function as the primary qualification gate, constraining supplier entry and anchoring production in Germany, Japan, and the United States. Hollow-fiber membrane production draws from specialized polymer feedstocks, precision fiber extrusion equipment, and nitrogen purity testing apparatus. Single-source vulnerability concentrates in German chemical manufacturing clusters for membrane substrate materials. Distribution runs through aerospace OEM line-fit procurement channels and authorized aftermarket service networks serving retrofit mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in fuel tank inerting systems center on software-governed control system premiums and predictive maintenance service attach rates, with membrane material cost curves flattening as Japanese suppliers expand qualified production capacity.
For Market Incumbents: Cement market position through backward integration into hollow-fiber membrane substrate production and captive supply of specialized polymers from Japanese material partners. Pressure swing adsorption technology from emerging defense contractors threatens premium positioning in military tanker segments. Certification investment in dual-use FAA-MIL-STD-882 platforms secures engineering resource allocation against program delay risks. For New Entrants and Emerging Players: Digital-channel route through predictive maintenance software platforms offers lowest barrier to incumbent customer relationships. Maritime tanker retrofit demand in Singapore and Rotterdam presents most penetrable white-space, with International Maritime Organization vapor management protocols creating regulatory pull. Target aftermarket service contracts for aging Boeing 737 NG and Airbus A320ceo fleets requiring custom structural modifications. For Investors and Strategic Acquirers: Asymmetric upside sits with control system software specialists integrating machine-learning diagnostics with nitrogen concentration monitoring. Long-term viability favors acquisition targets with established FAA-EASA dual-certification pathways and embedded positions in narrow-body fleet operator maintenance contracts. Watch for divergence between commercial FAA certification timelines and defense program delays as inflection indicator for dual-use platform engineering resource strain.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrates | Captive supply of German and Japanese polymer feedstocks insulates against single-source vulnerability. |
| Predictive Maintenance Software Launch | Machine-learning diagnostics integration with Honeywell and Eaton control architectures compresses service intervals. |
| Maritime Tanker Retrofit Partnership | Singapore-based shipping operators consolidate procurement for International Maritime Organization compliance. |
| Dual-Use Certification Investment | FAA-EASA-MIL-STD-882 harmonization reduces engineering resource stranding risk across defense delays. |
| India Fleet Expansion Joint Venture | Low-cost carrier growth and indigenous regional jet programs open greenfield installation opportunities. |
Research Methodology
Coverage spans the United States, Germany, France, Japan, and Singapore, with primary inputs from each jurisdiction combining structured interviews with aerospace OEM procurement directors, nitrogen generation system engineering leads, airline fleet managers, maritime tanker operators, and defense prime contract officers with secondary validation through FAA airworthiness directive filings, EASA certification databases, International Maritime Organization protocol updates, and SEC 10-K disclosures from diversified industrial conglomerates. Bottom-up unit demand modeling triangulates against top-down market value reconstruction.
Granularity-level framing applies technology-specific nitrogen purity thresholds, component-level margin pool differentiation, and end-user procurement consolidation patterns across the projection horizon. Segmentation dimensions include membrane separation versus pressure swing adsorption technology tiers, control system versus hardware component margin structures, aerospace versus marine application certification intensity, and OEM line-fit versus aftermarket retrofit demand channels. CAGRs derive from fleet modernization mandate timing, membrane material supply expansion curves, and predictive maintenance software penetration assumptions.
Defense program delays, hollow-fiber membrane supply disruptions, and maritime regulatory enforcement variance are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on FAA-EASA harmonization stability and airline procurement bundling velocity. A model refresh is warranted upon material change in military tanker platform development timelines or International Maritime Organization protocol adoption rates in Asian shipping hubs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aircraft Refueler Market