
 Aircraft Exhaust System Market | 2026-2036
Aircraft Exhaust System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Exhaust System Market Intelligence
FAA airworthiness certification, particularly under Part 34 for emissions, is redrawing the competitive landscape for exhaust system suppliers. Safran leverages its extensive engine integration expertise for complete propulsion solutions. GKN Aerospace specializes in advanced metallic and composite structures for nacelles and exhaust components. Triumph Group competes on its broad portfolio of aerostructures and system components for both OEM and MRO channels.
An aircraft exhaust system is a set of engineered components designed to safely duct hot gases from an engine. These systems utilize high-temperature alloys like Inconel to withstand extreme thermal stress while managing noise and emissions. The commercial jets segment constitutes the largest portion of the market, driven by new aircraft deliveries and fleet modernization. Within materials, titanium and Inconel alloys command premium pricing due to their superior performance characteristics compared to stainless steel.
The market operates under stringent oversight from aviation authorities including the U.S. FAA and the European Union Aviation Safety Agency (EASA). These bodies mandate specific noise and emission levels, directly influencing exhaust system design and material selection. Regulations from bodies like the CAAC in China are also critical for market access. Component manufacturers must therefore balance material innovation with the complex and evolving certification requirements for next-generation aircraft platforms.
Market Dynamics
The aircraft exhaust system market is shaped by the intense pressure to meet stricter emissions and noise standards from regulators like the FAA and EASA, while simultaneously advancing material science to reduce weight and improve fuel efficiency on new aircraft platforms.
Growth Catalysts
- Commercial Fleet Growth:The expansion of the global commercial aircraft fleet, particularly for long-haul travel, creates baseline demand for new exhaust systems.
- Advanced Material Adoption:The shift to Inconel and titanium alloys reduces weight and improves heat resistance, enabling more fuel-efficient aircraft designs.
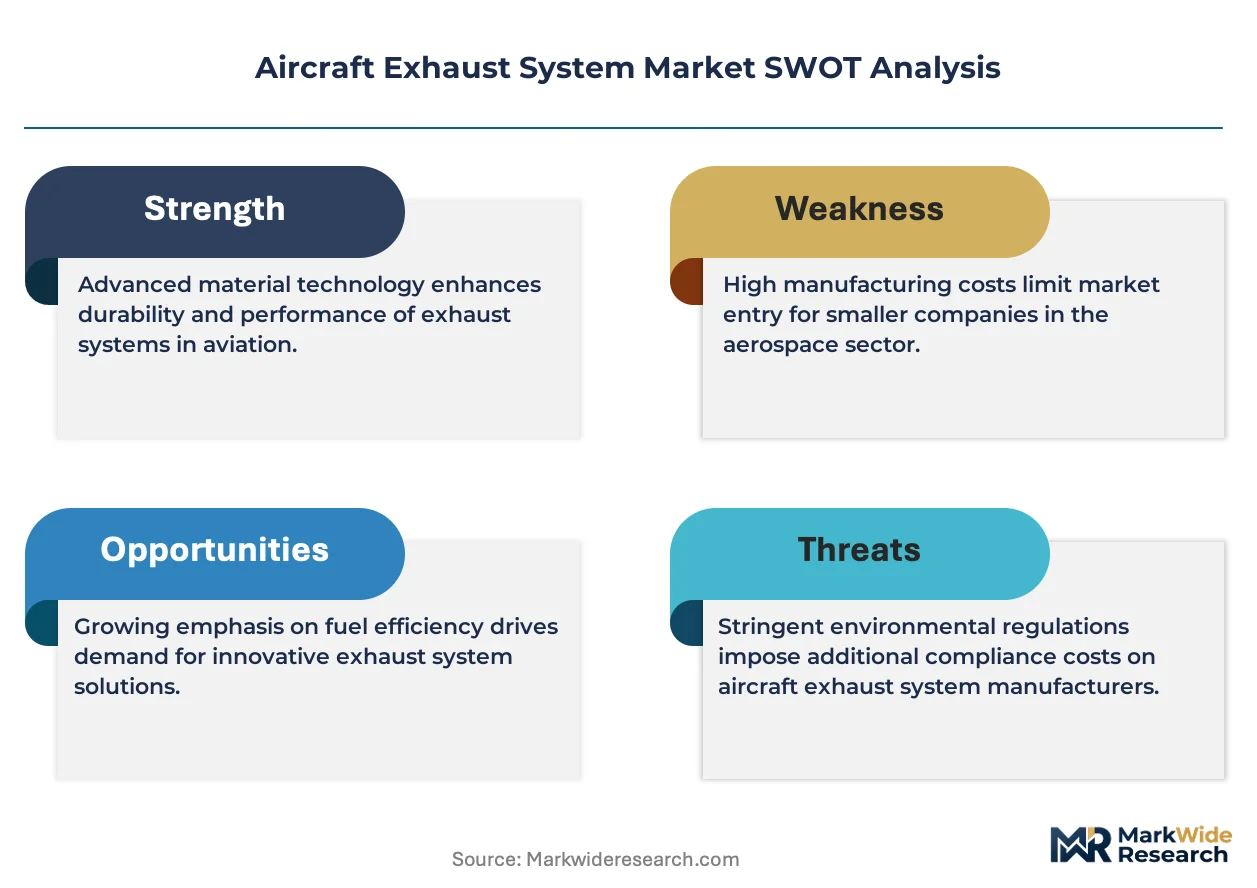
- Environmental Regulation:Stringent noise and emissions standards from the FAA and EASA mandate the use of technologically sophisticated exhaust systems for certification.
Market Restraints
- High Material Costs:Dependence on expensive alloys like titanium and Inconel creates high input costs and exposes manufacturers to price volatility.
- Lengthy Certification Cycles:Rigorous airworthiness certification processes with the FAA and EASA are time-consuming and costly, slowing down innovation and market entry.
- Manufacturing Complexity:Fabrication of high-temperature alloy components requires specialized equipment and expertise, concentrating production among a limited number of suppliers.
Strategic Opportunities
- Additive Manufacturing:Using 3D printing allows for the production of lighter, more complex exhaust components, optimizing acoustic performance and reducing part count.
- New Aviation Segments:The emerging Urban Air Mobility (UAM) sector requires novel, lightweight thermal management solutions, creating a new market for specialized suppliers.
- Digital Aftermarket Services:Offering sensor-based predictive maintenance for exhaust systems opens high-margin, recurring revenue opportunities with airlines and MRO providers.
Industry Challenges
- Skilled Labor Scarcity:A shortage of certified welders and technicians with expertise in forming and joining high-temperature alloys like Inconel creates production bottlenecks and drives up labor costs.
- Propulsion System Integration:Ensuring seamless integration of the exhaust system with next-generation engine architectures and advanced nacelle structures presents a significant engineering and coordination challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Exhaust System Market |
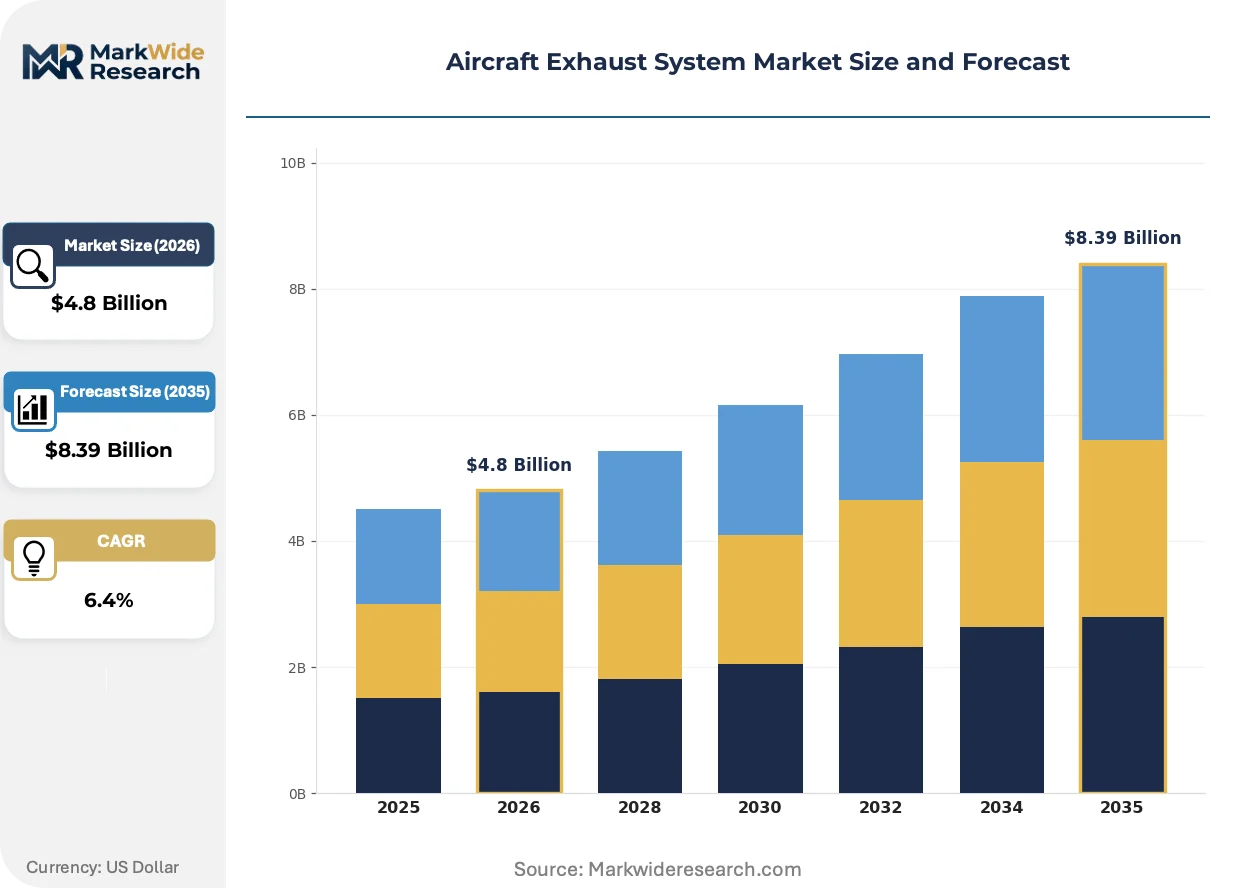
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turbocharger, Silencer, Exhaust Pipe, Muffler Material: Stainless Steel, Titanium, Aluminum, Inconel Aircraft Type: Commercial Jets, Military Aircraft, Helicopters, General Aviation Application: Power Generation, Noise Reduction, Emission Control, Thermal Management |
| Companies Covered | Triumph Group Inc., Magellan Aerospace Corporation, Rolls-Royce plc, Melrose Industries PLC, TransDigm Group Incorporated, GKN Aerospace, Ducommun Incorporated, Safran, Senior plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Exhaust System Market Strategic Shifts & Innovations
A convergence of material science and digital engineering tools is defining the next generation of aircraft exhaust systems. These innovations are a direct response to regulatory demands for quieter, cleaner, and more efficient aircraft propulsion.
Advanced acoustic liner technology uses micro-perforated panels and engineered cellular structures for noise attenuation. Airframe manufacturers are adopting these systems to meet stringent airport noise regulations. This drive for efficiency is miniaturizing the acoustic treatment, forcing engineers to achieve more noise reduction within a smaller, lighter physical envelope.
European Union sustainability directives like the CSRD are expanding compliance beyond operational emissions. This shift compels manufacturers to document the environmental footprint of their value chain, from material sourcing to recyclability. The commercial aerospace segment, especially suppliers to European airframers, is now investing in circular economy principles for component design.
Airline and airframer procurement is shifting from sourcing discrete components to acquiring integrated propulsion systems. This trend favors large Tier 1 integrators who can deliver a complete nacelle, thrust reverser, and exhaust module. This shift is most pronounced in the large commercial jet sector, where system integration is critical for optimizing overall performance.
Aircraft Exhaust System Market Segmentation
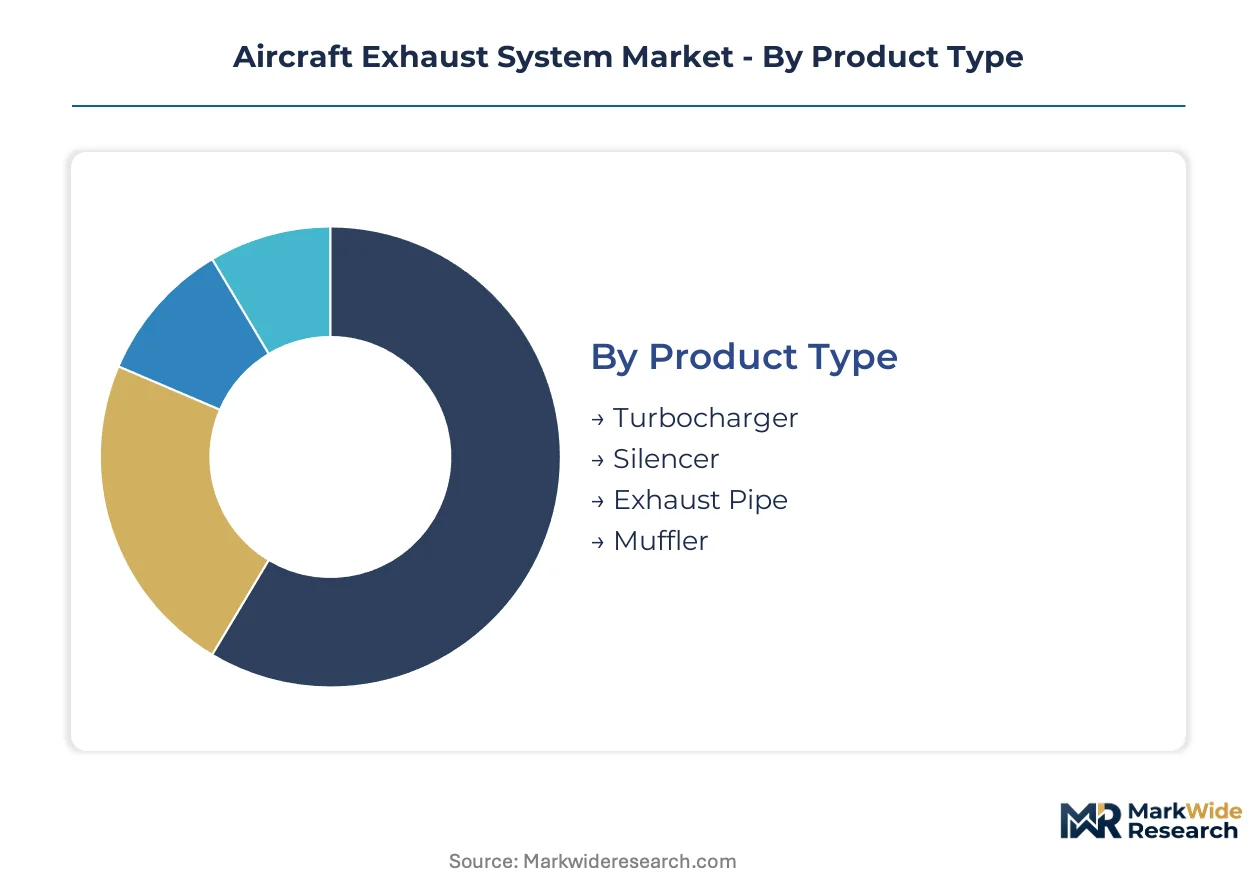
Segmentation analysis for the aircraft exhaust system market reveals critical differentiators in product functionality, material science, aircraft integration, and operational objectives. These distinctions directly influence technological investment, supply chain strategies, and market growth trajectories across various aviation sectors. Understanding these segments helps manufacturers align their offerings with specific performance and regulatory demands.
Product Type:
The product type segmentation highlights areas where traditional components face substitution pressure from integrated solutions or advanced designs.
- Exhaust Pipe:These components are engineered to safely duct hot gases away from the engine, managing high temperatures and pressures. Demand concentrates in the commercial jets segment for long-haul aircraft, driven by the need for durable and efficient gas flow.
- Silencer:Silencer systems incorporate advanced acoustic liner technology to attenuate engine noise, crucial for meeting stringent airport noise regulations. New aircraft platforms, including emerging urban air mobility (UAM) vehicles, increasingly demand these sophisticated noise reduction solutions.
- Turbocharger:Turbochargers utilize exhaust gas energy to increase engine power and efficiency, primarily found in piston-powered aircraft engines.
- Muffler:Mufflers reduce noise output from smaller aircraft engines, often found in general aviation and some helicopter applications.
Exhaust Pipe components anchor the volume base while Silencer systems gain share at the steepest rate.
Material:
Material selection for aircraft exhaust systems is often dictated by a cost-performance hierarchy, influencing procurement decisions across different aircraft types.
- Inconel:This nickel-chromium superalloy offers exceptional strength and corrosion resistance at extreme temperatures, making it ideal for high-performance exhaust sections. Demand is high in commercial jets and military aircraft due to the requirement for superior heat resistance and durability.
- Titanium:Titanium alloys provide an excellent strength-to-weight ratio and superior corrosion resistance, critical for reducing overall aircraft mass and improving fuel efficiency. Advanced new aircraft platforms increasingly specify titanium for exhaust components to meet strict weight targets.
- Stainless Steel:Stainless steel provides a cost-effective solution for exhaust components in less demanding applications, offering good corrosion resistance and mechanical properties.
- Aluminum:Aluminum alloys are used in specific, lower-temperature sections of exhaust systems where weight reduction is paramount and thermal loads are moderate.
Performance demands from next-generation aircraft platforms increasingly drive material innovation towards lighter, more durable alloys.
Aircraft Type:
The aircraft type segmentation reveals varying demand volumes and performance requirements for exhaust systems across different aviation sectors.
- Commercial Jets:This segment includes large passenger aircraft used for scheduled air travel, representing the largest portion of the market. Demand is driven by new aircraft deliveries and fleet modernization initiatives across global airlines, particularly for long-haul routes.
- Military Aircraft:Encompassing fighter jets, transport planes, and surveillance aircraft, this segment requires exhaust systems optimized for extreme conditions and mission-specific performance. Demand is tied to defense procurement cycles and the operational readiness of global air forces.
- Helicopters:Helicopters utilize specialized exhaust systems designed to manage unique aerodynamic and thermal challenges associated with rotary-wing flight.
- General Aviation:This category covers smaller private and recreational aircraft, where exhaust systems often prioritize cost-effectiveness and simpler designs.
Global commercial fleet expansion underpins the largest segment demand, influencing exhaust system design and manufacturing scale.
Application:
Application segmentation highlights how regulatory pressures and operational efficiency mandates shape the functional priorities of exhaust system design.
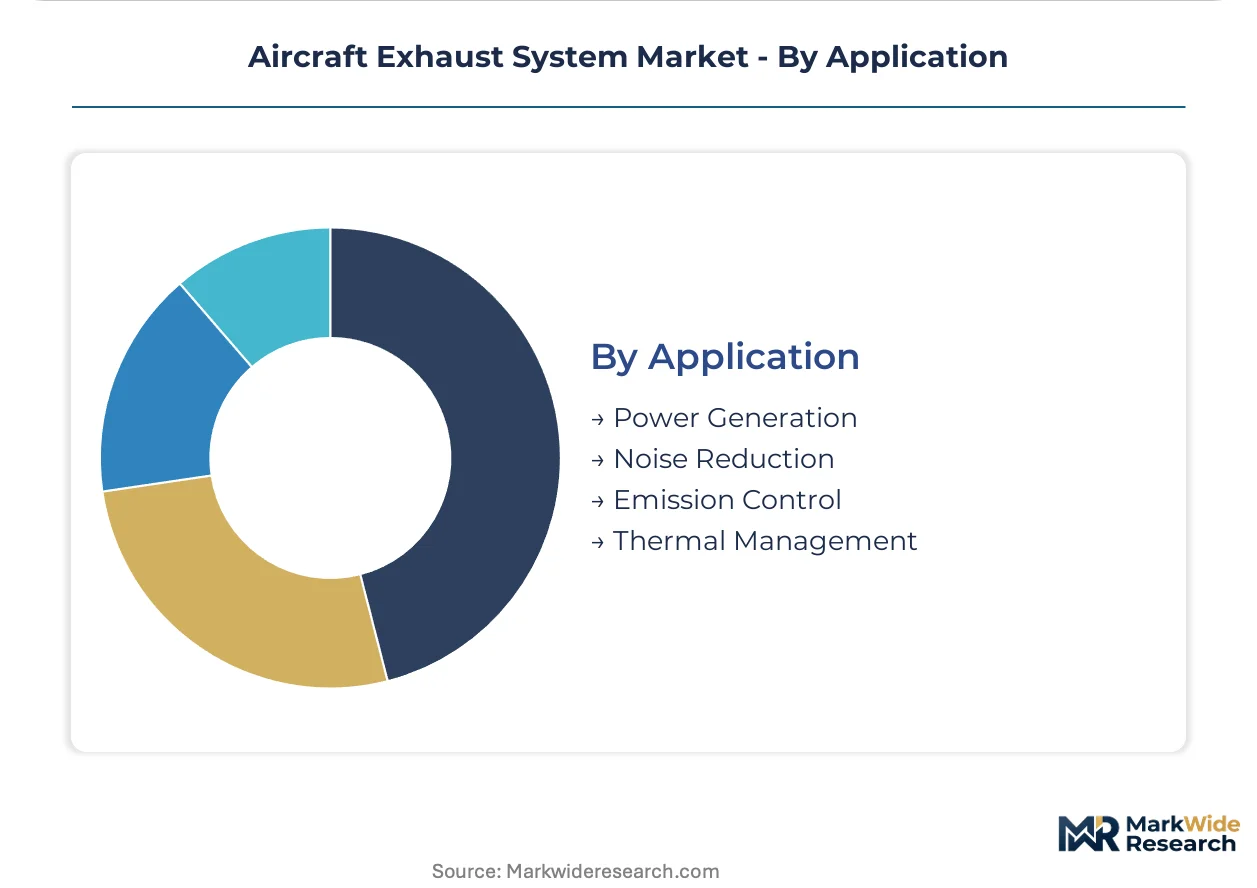
- Noise Reduction:This application focuses on minimizing acoustic emissions from aircraft engines, employing advanced acoustic liner technology and exhaust nozzle designs. Demand is growing in urban air mobility (UAM) and commercial aircraft sectors due to stringent airport noise regulations and community concerns.
- Emission Control:Exhaust systems designed for emission control integrate technologies like catalytic converters and advanced combustion management to reduce harmful pollutants. New engine architectures are incorporating these solutions to meet FAA Part 34 and EASA environmental standards.
- Power Generation:Exhaust systems support power generation by efficiently channeling hot gases to drive turbines or other auxiliary power units.
- Thermal Management:This application involves controlling and dissipating heat generated by the exhaust gases, crucial for protecting surrounding aircraft structures and components.
Environmental performance requirements dictate significant innovation in exhaust system design, particularly for noise and emission reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global demand for aircraft exhaust systems concentrates in regions with established aerospace manufacturing capabilities and significant commercial airline operations. These areas drive procurement for both new aircraft deliveries and fleet modernization programs. Rigorous airworthiness certification processes also shape regional market dynamics.
United States
Demand for advanced exhaust systems stems from new commercial aircraft builds and military procurement cycles. The FAA's stringent Part 34 emissions standards influence design and material selection for new platforms. Major aerospace clusters in Seattle and Wichita spearhead innovation in exhaust component manufacturing.
France
French aerospace manufacturers drive procurement for exhaust systems, particularly for large commercial jets like Airbus. EASA regulations, along with EU sustainability directives like CSRD, mandate environmentally compliant designs. Toulouse, a major aerospace hub, sees significant activity in integrated propulsion system development.
United Kingdom
UK-based engine and airframe manufacturers generate substantial demand for high-performance exhaust components. The Civil Aviation Authority (CAA) enforces strict noise and emission standards for UK-registered aircraft. Derby and Bristol, known for engine design and manufacturing, foster specialized exhaust system development.
Germany
German aerospace industry contributes to exhaust system demand through its strong presence in aircraft interiors and component manufacturing. EASA certification requirements for noise and emissions directly impact design specifications. Hamburg and Munich serve as key centers for aerospace engineering and advanced material research.
Japan
Japanese aircraft component suppliers contribute to global exhaust system supply chains, driven by domestic defense needs and international partnerships. METI initiatives support advanced material research for lighter, more durable aerospace components. Nagoya's aerospace cluster focuses on precision manufacturing for critical engine parts.
Aircraft Exhaust System Market Key Industry Players
Player mix skews toward large Tier 1 integrators capable of delivering complete propulsion solutions. The market also includes specialized component manufacturers focusing on advanced materials and complex geometries. A third segment comprises MRO providers offering aftermarket services for exhaust systems. Strategic partnerships are common for technology development, while M&A activity consolidates specialized capabilities.
Specialists in integrated propulsion systems and advanced component manufacturing include Safran, known for its engine integration expertise across complete propulsion solutions. GKN Aerospace exemplifies a focus on advanced metallic and composite structures for nacelles and exhaust components. Triumph Group occupies a position providing a broad portfolio of aerostructures and system components for both OEM and MRO channels. These companies represent the diverse capabilities and strategic approaches required to meet evolving market demands and stringent regulatory standards.
| Leading Market Players |
|---|
| Triumph Group Inc. |
| Magellan Aerospace Corporation |
| Rolls-Royce plc |
| Melrose Industries PLC |
| TransDigm Group Incorporated |
| GKN Aerospace |
| Ducommun Incorporated |
| Safran |
| Senior plc |
| Others |
Cost & Logistics Intelligence
The increasing substitution of stainless steel with Inconel and titanium alloys is reshaping aircraft exhaust system supply geography and pricing economics. This material transition elevates input costs and concentrates manufacturing expertise in specific regions.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material costs like Inconel and titanium, govern pricing for aircraft exhaust systems. Price differentiation stems from the stringent FAA/EASA certification levels and the high degree of customization required for specific aircraft platforms. Upward pricing pressure arises from the escalating costs of advanced alloys and the extensive R&D investment in noise and emissions reduction. General aviation represents the most price-sensitive segment, while military and commercial jet operators prioritize performance and compliance over cost.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized high-temperature alloys, influence the global aircraft exhaust system supply chain. Supply concentrations for critical components and advanced materials are found in the United States, France, and the United Kingdom. Dependence on Inconel and titanium alloys creates single-source vulnerability for specialized processing, alongside a scarcity of certified welders. Distribution primarily runs through direct channels to major OEMs and MRO providers, often facilitated by large Tier 1 integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft exhaust system market presents a defensive moat, anchored by significant regulatory entrenchment through FAA and EASA certification. High switching costs for aerospace integrators further solidify market positions.
For Market Incumbents:Fortify existing OEM relationships by deepening integration with engine architectures and nacelle designs. Invest heavily in advanced material science and additive manufacturing capabilities to counter emerging material science startups. Leverage extensive certification investment with FAA and EASA to create barriers to entry for new players. Expand specialized manufacturing capacity for high-temperature alloys in strategic aerospace hubs.
For New Entrants and Emerging Players:Differentiate on niche material innovation or specialized acoustic performance for emerging segments. Target the nascent Urban Air Mobility (UAM) sector with novel, lightweight thermal management solutions. Develop sensor-based predictive maintenance offerings for aftermarket services, providing high-margin recurring revenue. Focus on specific component-level advancements rather than full system integration to gain initial market traction.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with private equity-backed component manufacturers specializing in aerostructures or advanced materials. This market offers long-term viability due to its critical infrastructure role and high regulatory barriers to entry. Identify mid-cap specialists with proprietary acoustic liner technology or additive manufacturing expertise for strategic acquisition. The signal to watch is the increasing consolidation of Tier 2 suppliers by larger system integrators.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Additive Manufacturing | This enables production of lighter, more complex exhaust components, optimizing acoustic performance for new aircraft platforms. |
| Expand Digital Aftermarket Services | Offering sensor-based predictive maintenance creates high-margin, recurring revenue opportunities with airline and MRO customers. |
| Deepen OEM Co-development Partnerships | Ensuring seamless integration with next-generation engine architectures facilitates certification and market access for new systems. |
| Acquire Acoustic Technology Specialists | This secures proprietary noise attenuation solutions, addressing stringent airport noise regulations and UAM vehicle needs. |
| Develop Circular Economy Initiatives | Documenting value chain environmental footprints meets EU sustainability directives and enhances material recyclability for components. |
Research Approach
Two parallel data streams informed the analysis: primary interviews and extensive secondary validation. Primary data involved conversations with aerospace engineers, procurement leads, MRO technicians, and regulatory compliance officers. Secondary research drew from FAA and EASA reports, aerospace industry association publications, and financial filings of public companies. This approach ensured robust bottom-up and top-down triangulation of market insights.
The forecast framework established a clear modeling period across the analysis window, integrating historical performance with future projections. Segmentation dimensions included product type, material, aircraft type, application, and regional regulatory environment. Compound Annual Growth Rates were derived from an assessment of historical trends and anticipated technological shifts. Key inputs included new aircraft delivery schedules and advanced material science adoption rates.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or unforeseen supply chain disruptions would require recalibration. Forecasts reflect core assumptions regarding aircraft production rates and regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market