
 Refueling Aircraft Market | 2026-2036
Refueling Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Refueling Aircraft Market Analytics
Saudi Arabia is fragmenting its refueling aircraft supplier base as defense localization accelerates under Vision 2030. Boeing anchors the wide-body tanker segment with KC-46A production sustained by Pentagon multi-year procurement. Airbus competes through A330 MRTT deliveries to European and Middle Eastern operators. Lockheed Martin specializes in probe-drogue systems that extend platform interoperability across allied fleets.
Refueling aircraft are purpose-built aerial platforms and ground support systems designed to transfer aviation fuel to receiver aircraft during flight or at airfields, typically operating at flow rates exceeding 1,000 gallons per minute through boom or hose-drogue architectures. Their primary purpose is to extend operational range for military strike missions and reduce turnaround times for commercial aviation networks. Military end users dominate capital deployment for tanker fleets, while commercial airlines concentrate spending on hydrant systems and refueling trucks at hub airports. Jet A fuel type retains the largest volume share, though biofuel blending requirements are altering storage and handling infrastructure specifications across both segments.
FAA regulations govern ground fueling safety and fire suppression standards at US commercial airports, while EASA enforces equivalent hydrant system certification across European Union member states. Military procurement falls under national defense acquisition frameworks, with NATO standardization agreements driving interoperability requirements for aerial refueling interfaces. Stakeholders must monitor sustainable aviation fuel mandates from regulators and assess how fuel property changes affect seal compatibility and filtration specifications in existing equipment.
Market Dynamics
The refueling aircraft market pivots on military fleet modernization cycles intersecting with commercial airport infrastructure mandates. Defense procurement offices are accelerating tanker replacements while FAA hydrant system upgrades force simultaneous capital deployment across dual customer bases.
Growth Catalysts
- NATO Standardization Agreements:Allied interoperability requirements for boom and probe-drogue interfaces are driving cross-border procurement coordination. Member states must certify new tankers against STANAG 3447 protocols.
- Sustainable Aviation Fuel Mandates:The EU Green Deal's blending targets are forcing storage and handling infrastructure retrofits at major European hubs. Hydrant system operators face seal compatibility and filtration specification overhauls.
- Hub Airport Expansion:Commercial carriers at Dubai International and Singapore Changi are commissioning next-generation refueling trucks and underground fuel farms to accommodate wide-body fleet growth.
Market Restraints
- Titanium Alloy Supply Concentration:Boom and wing pod fabrication depends on Russian and Chinese sponge titanium sources. Western defense contractors face input cost volatility and sanctions compliance complexity.
- EASA Certification Timelines:Hydrant system approvals for new fuel types average 18-24 months. This regulatory friction delays sustainable aviation fuel infrastructure rollouts at EU member airports.
- Autonomous Ground Vehicle Substitution:Self-driving refueling trucks from aviation ground support specialists are displacing conventional manned platforms in trial deployments at Amsterdam Schiphol.
Strategic Opportunities
- India Defense Modernization:The Indian Air Force's pending tanker tender under the Ministry of Defence's capital acquisition plan represents a white space for probe-drogue system suppliers. Indigenous offset requirements favor joint venture structures.
- Hydrogen Handling Infrastructure:Convergence of cryogenic storage technology and aviation fuel cell propulsion is creating demand for dual-capable ground support equipment. Early movers in liquid hydrogen couplings will capture specification-setting power.
- Performance-Based Logistics Contracts:US Air Force Materiel Command is piloting availability-based sustainment models for tanker fleets. This channel innovation shifts revenue from spare parts to flight-hour guarantees.
Industry Challenges
- Flight Test Engineer Scarcity:Aerial refueling certification requires specialized crews for boom envelope expansion and receiver qualification. Military and commercial programs compete for the same limited talent pool.
- Legacy System Integration:New tanker deliveries must maintain interoperability with 1960s-era receiver aircraft. Software and hardware interface complexity extends development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refueling Aircraft Market |
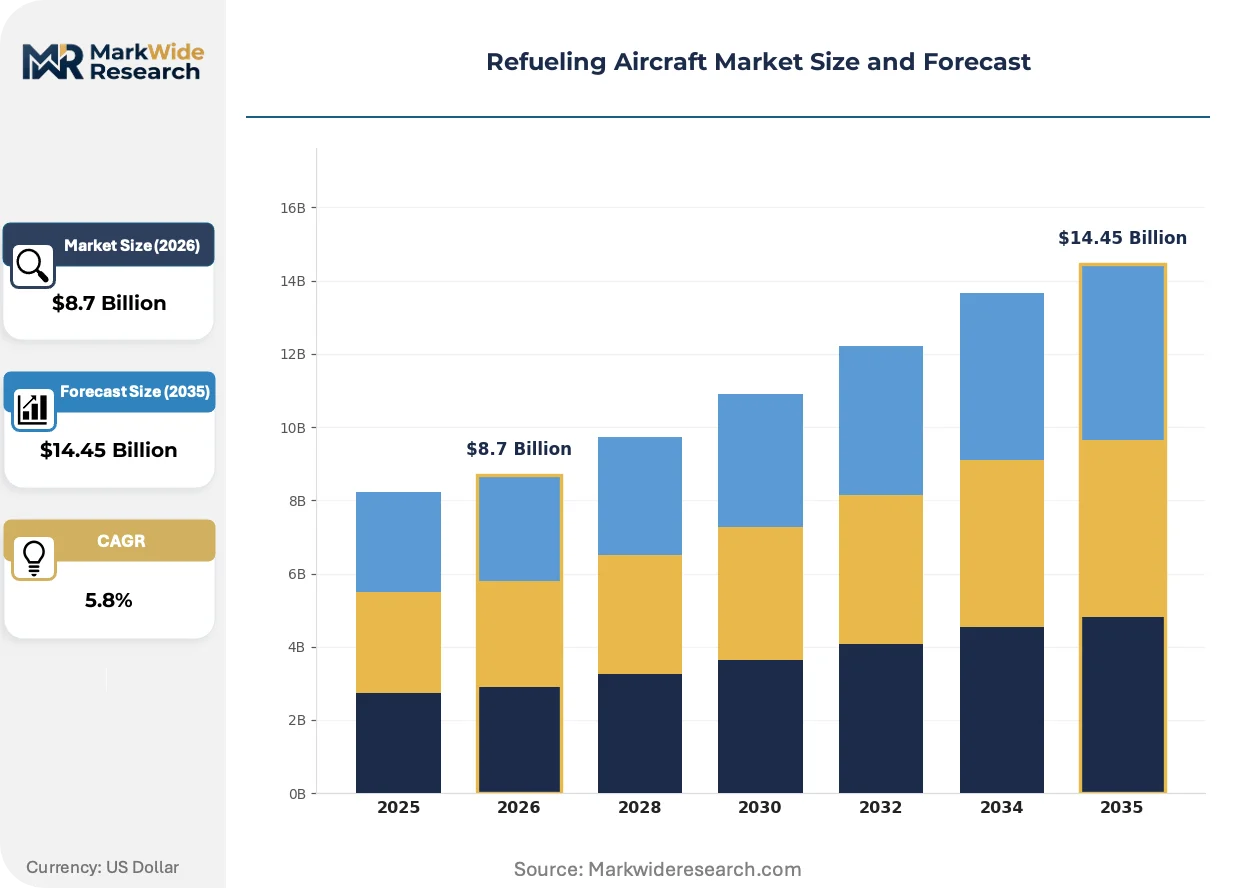
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refueling Trucks, Fuel Tanks, Hydrant Systems, Modular Systems End User: Military, Commercial Airlines, General Aviation, Cargo Operators Installation Type: Fixed, Mobile, Prefabricated, Onsite Fuel Type: Jet A, Avgas, Biofuel, Others |
| Companies Covered | Boeing, Airbus, Lockheed Martin, Northrop Grumman, Cobham, Eaton, GE Aviation, Safran, Embraer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refueling Aircraft Market Evolving Landscape
Autonomous systems and alternative fuel compatibility are restructuring capital allocation across the refueling aircraft value chain. Equipment specifications now anticipate propulsion technology transitions that remain a decade from operational deployment.
Fly-by-wire boom control systems are migrating from hydraulic actuation architectures to electro-mechanical configurations. The US Air Force is mandating this transition for all new tanker platforms to reduce maintenance hours and improve precision in contact operations. This technology compression is eliminating specialist hydraulic component suppliers from the tier-two vendor base.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in fire suppression systems installed at airport fuel farms. Hydrant operators must retrofit foam-based alternatives or face operating restrictions at major EU hubs. German and French airport authorities are accelerating compliance timelines ahead of statutory deadlines to secure insurance coverage.
Consolidated procurement consortia are displacing individual airline fuel purchasing agreements at hub airports. Ground handling providers at London Heathrow and Frankfurt Main now negotiate multi-carrier volume contracts with integrated into-plane service guarantees. This buyer concentration is compressing margins for independent refueling truck operators across Northern European markets.
Refueling Aircraft Market Segmentation
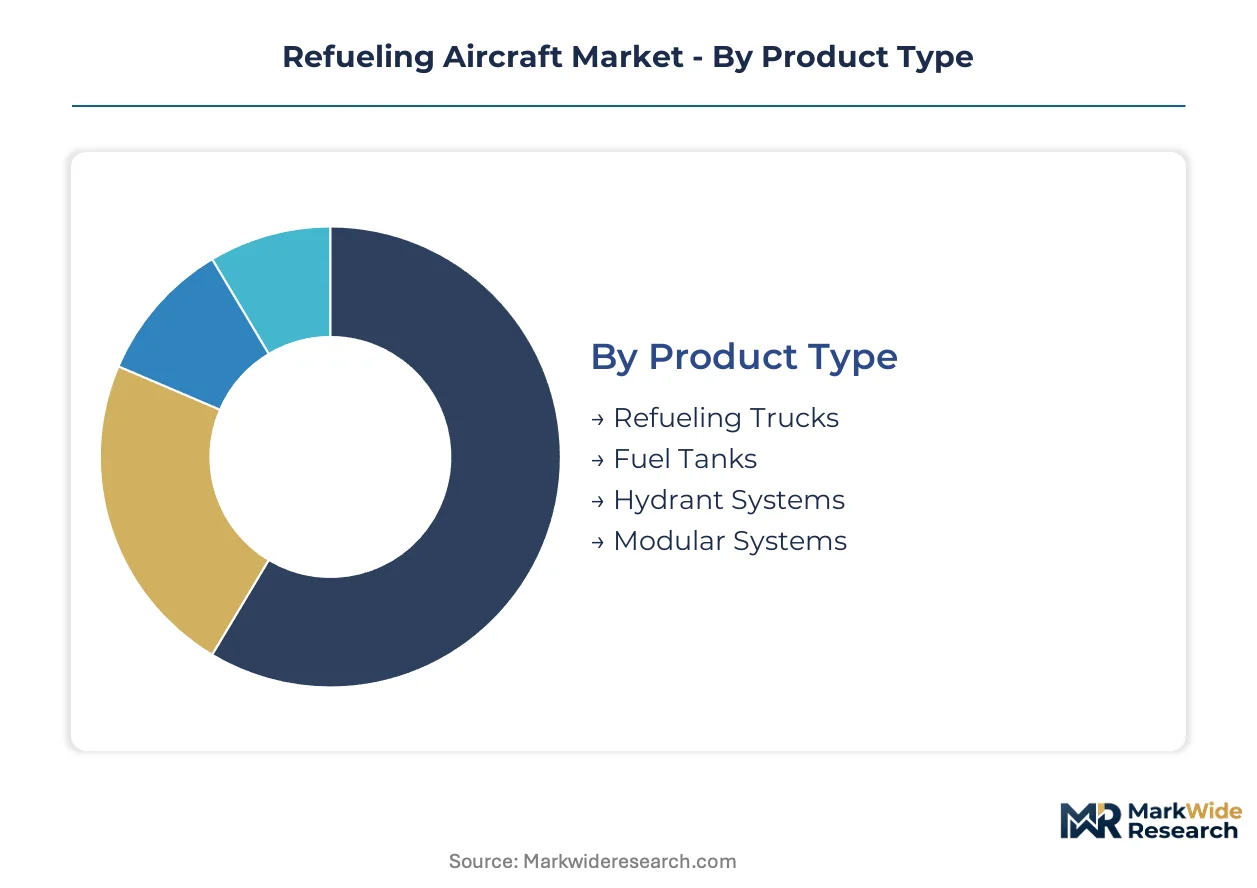
Segmentation in the refueling aircraft market reveals divergent equipment specifications between military tanker platforms and commercial ground support infrastructure. Procurement cycles, regulatory compliance requirements, and fuel handling protocols vary sharply across customer categories, forcing suppliers to maintain distinct product architectures.
Product Type:
Mature platforms dominate installed base volumes while emerging configurations capture modernization budgets.
- Refueling Trucks:Self-propelled or towed vehicles equipped with pumps, meters, and filtration systems for apron-based aircraft fueling. Demand concentrates at Dubai International and Singapore Changi where wide-body fleet expansion is forcing truck replacement cycles. FAA fire suppression standards are accelerating fleet turnover for aging carbon steel tank configurations.
- Hydrant Systems:Underground pipeline networks delivering fuel directly to aircraft parking positions via hydrant pits and dispensing carts. European hub airports under EU Green Deal mandates are retrofitting seal materials and filtration stages to accommodate biofuel blending requirements. EASA certification timelines for modified systems average 18-24 months.
- Fuel Tanks:Above-ground and underground storage vessels ranging from 10,000 to 500,000 gallon capacities for airport fuel farms.
- Modular Systems:Containerized refueling units designed for rapid deployment in expeditionary military operations or remote commercial airfields.
Hydrant Systems handle the majority of throughput at major commercial hubs; Modular Systems are expanding most quickly on share driven by expeditionary military requirements.
End User:
Cost tier segmentation separates capital-intensive military tanker programs from efficiency-driven commercial ground handling contracts.
- Military:National defense forces operating dedicated aerial refueling tankers and tactical ground support equipment. The US Air Force's KC-46A multi-year procurement sustains Boeing's wide-body tanker production line. NATO STANAG 3447 protocols mandate boom and probe-drogue interface standardization across allied fleets.
- Commercial Airlines:Scheduled carriers contracting ground handling services or operating captive fuel farms at hub airports. Consolidated procurement consortia at London Heathrow and Frankfurt Main are displacing individual airline purchasing agreements and compressing margins for independent truck operators.
- General Aviation:Private aircraft operators and fixed-base operators requiring smaller-scale refueling infrastructure at regional airports.
- Cargo Operators:Dedicated freight carriers with high-frequency turnaround requirements at logistics hubs.
Military end users deploy the largest capital per installation; Commercial Airlines are gaining share fastest as hub airport expansion accelerates across the Middle East and Asia-Pacific.
Installation Type:
Application requirements dictate permanence trade-offs between integrated infrastructure and operational flexibility.
- Fixed:Permanent concrete-anchored installations including underground hydrant networks and above-ground storage farms. Major European hubs are accelerating F-Gas Regulation compliance for foam-based fire suppression retrofits ahead of statutory deadlines.
- Mobile:Relocatable equipment including refueling trucks and trailer-mounted pumps for apron flexibility. Autonomous ground vehicle trials at Amsterdam Schiphol are testing self-driving configurations that may displace conventional manned platforms.
- Prefabricated:Factory-assembled modular units minimizing field construction time for capacity expansion projects.
- Onsite:Built-to-specification installations tailored to unique airfield geometries or operational constraints.
Fixed installations anchor throughput at established hubs; Mobile configurations are climbing the fastest as airports prioritize operational reconfiguration capabilities.
Fuel Type:
Supply concentration and regulatory mandates are restructuring storage and handling specifications across the installed base.
- Jet A:Kerosene-based turbine fuel standard for commercial aviation and military jet aircraft. The installed base of seal materials, filtration systems, and hydrant infrastructure was engineered for Jet A specifications, creating retrofit requirements as fuel properties evolve.
- Biofuel:Sustainable aviation fuel blends subject to EU Green Deal blending mandates and emerging FAA approval pathways. Seal compatibility and filtration specification overhauls are forcing infrastructure investment at major European hubs ahead of volume ramp.
- Avgas:High-octane gasoline formulation for piston-engine aircraft in general aviation operations.
- Others:Specialized fuels including JP-8 military formulations and emerging hydrogen carriers for future propulsion systems.
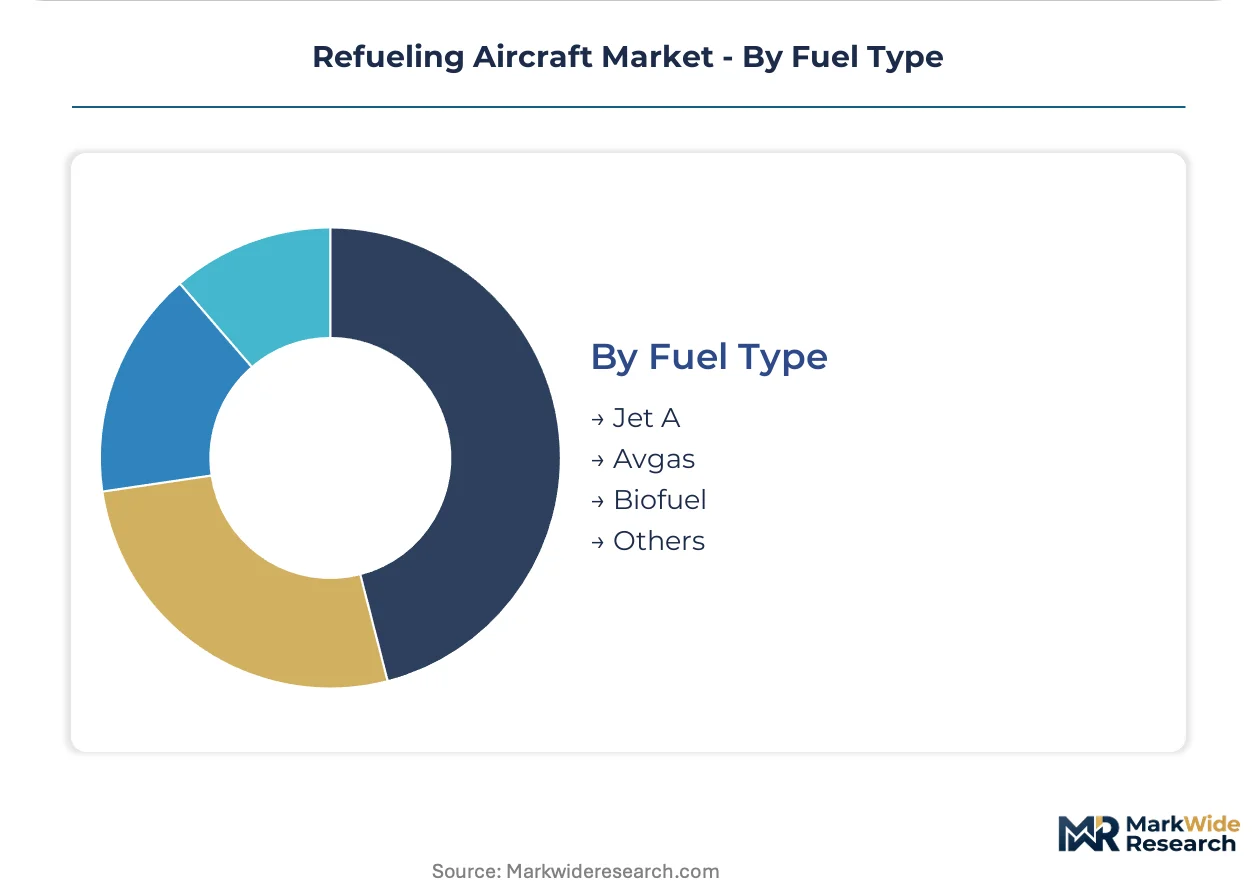
Jet A retains dominant volume through the forecast window; Biofuel is gaining share fastest as regulatory mandates harden across European Union member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA governs the United States market through hydrant system safety standards and fire suppression mandates that reshape ground support equipment specifications. Military tanker replacement programs and commercial hub expansion drive capital deployment across multiple geographies.
United States
The US Air Force's KC-46A multi-year procurement sustains wide-body tanker production while FAA fuel handling standards force hydrant system upgrades at major commercial hubs. The Pentagon's defense acquisition framework prioritizes boom and probe-drogue interoperability across allied fleets. Dallas-Fort Worth International anchors ground support equipment demand as American Airlines expands wide-body operations.
Germany
EASA hydrant system certification timelines averaging 18-24 months create regulatory friction for sustainable aviation fuel infrastructure rollouts at Frankfurt Main and Munich. The EU F-Gas Regulation accelerates foam-based fire suppression retrofits ahead of statutory deadlines. German airport authorities secure insurance coverage through early compliance, compressing deployment schedules for equipment suppliers.
France
Airbus A330 MRTT deliveries to European and Middle Eastern operators concentrate final assembly and systems integration in Toulouse. The EU Green Deal's blending targets force seal compatibility and filtration specification overhauls at Paris Charles de Gaulle. French defense procurement under NATO STANAG 3447 protocols mandates standardized aerial refueling interfaces for allied interoperability.
Saudi Arabia
Vision 2030 defense localization accelerates supplier base fragmentation as the Kingdom diversifies beyond traditional procurement relationships. The General Authority for Military Industries enforces indigenous offset requirements favoring joint venture structures for tanker and ground support programs. King Abdulaziz International in Jeddah commissions next-generation refueling infrastructure to accommodate pilgrimage traffic volume spikes.
India
The Indian Air Force's pending tanker tender under the Ministry of Defence's capital acquisition plan represents procurement white space for probe-drogue system specialists. BIS certification requirements for imported ground support equipment create compliance complexity for foreign suppliers. Bengaluru's aerospace cluster hosts maintenance, repair and overhaul facilities that support regional tanker fleet sustainment requirements.
Refueling Aircraft Market Competitive Landscape
Platform integrators and subsystem specialists split the market through divergent capital intensity requirements and certification barriers. The vendor base concentrates around defense primes with multi-decade military procurement relationships and commercial ground support equipment manufacturers serving airport infrastructure cycles. Three archetypes dominate: full-system integrators delivering complete tanker platforms, component specialists supplying boom and hose-drogue architectures, and ground support fabricators focused on hydrant systems and refueling trucks. Competitive moves center on performance-based logistics contracts that shift revenue from spare parts to flight-hour guarantees, plus geographic expansion through offset-driven joint ventures in emerging defense markets.
Among full-system integrators, Boeing and Airbus anchor the wide-body tanker segment through sustained military procurement and commercial derivative platforms. Lockheed Martin occupies a position within the subsystem specialist tier, representing probe-drogue architecture expertise that extends platform interoperability across allied fleets. These three companies exemplify how defense procurement concentration creates structural barriers for new entrants lacking established military certification pathways and NATO standardization agreement compliance histories.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Lockheed Martin |
| Northrop Grumman |
| Cobham |
| Eaton |
| GE Aviation |
| Safran |
| Embraer |
| Others |
Value Network & Pricing Analysis
Undercapacity in titanium alloy forging for boom and wing pod fabrication is concentrating supplier pricing power while forcing defense primes toward long-term offtake commitments. This utilization squeeze propagates through both aerial tanker production and ground support equipment manufacturing, compressing margins for tier-two fabricators unable to secure input allocations.
Pricing Analysis
Geographic price spreads between North American and European military procurement contracts reflect divergent offset requirements and certification cost burdens. Three-tier pricing structure across mission-certified, standard commercial, and expeditionary modular equipment segments dominates the market. Price differentiation rests on NATO STANAG 3447 compliance grade and after-sales service bundling. Cost compression in ground support equipment is intensifying as consolidated procurement consortia at major hubs extract volume discounts. Commercial airlines exhibit highest price sensitivity due to fuel pass-through economics, while defense procurement offices prioritize availability guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing concentration for refueling boom assemblies rests with specialized aerospace forging houses in the United States, France, and Japan. Raw material dependencies center on Russian and Chinese sponge titanium, aluminum-lithium alloys, and specialized hydraulic seal compounds. Single-source vulnerability in titanium supply creates exposure to sanctions compliance complexity and input cost volatility. Distribution runs through defense prime direct sales for military platforms and ground handling service provider procurement networks for commercial airport infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refueling aircraft market operates as a defensive-moat industry where regulatory entrenchment through FAA and EASA certification pathways creates structural barriers against new entrants. Decades-long military procurement relationships and NATO standardization agreement compliance histories compound this protection.
For Market Incumbents: Harden platform interoperability advantages by deepening backward integration into probe-drogue system production and securing exclusive supplier status for India's pending tanker tender. Autonomous ground vehicle substitution at Amsterdam Schiphol signals displacement risk for conventional refueling truck portfolios, necessitating pilot investments in self-driving configurations. Capacity addition in Saudi Arabia through Vision 2030 joint venture structures will preempt localization mandates before they harden.
For New Entrants and Emerging Players: Build out expeditionary modular system capabilities targeting expeditionary military requirements and remote commercial airfield deployments where incumbent presence remains thin. India's defense modernization white space offers the most penetrable geography given indigenous offset requirements that favor joint venture structures over direct foreign supply. A go-to-market angle anchored in hydrogen handling infrastructure for dual-capable ground support equipment will capture specification-setting power before propulsion technology transitions mature.
For Investors and Strategic Acquirers: Capital is best deployed toward subsystem specialists with probe-drogue architecture expertise and established NATO STANAG 3447 certification histories. Long-term viability over the next decade hinges on positioning for sustainable aviation fuel infrastructure retrofits and hydrogen handling capability convergence. The signal to watch is EASA certification timeline compression for biofuel-compatible hydrant systems, which would indicate regulatory friction easing and infrastructure rollout acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Logistics Contracting | US Air Force Materiel Command availability-based sustainment pilots shift revenue from spare parts to flight-hour guarantees. |
| Hydrogen Handling Infrastructure Development | Early movers in liquid hydrogen couplings will capture specification-setting power for dual-capable ground support equipment. |
| Vision 2030 Joint Venture Formation | Saudi localization mandates favor joint venture structures that preempt supplier base fragmentation in tanker and ground support programs. |
| F-Gas Regulation Compliance Acceleration | German and French airport authorities securing insurance through early foam-based fire suppression retrofits compress deployment schedules. |
| India Tanker Tender Positioning | Probe-drogue system specialists securing indigenous offset partnerships will capture Ministry of Defence capital acquisition plan awards. |
Research Methodology
Desk research of defense procurement databases, FAA and EASA regulatory filings, and NATO standardization agreement documentation preceded structured interviews with US Air Force Materiel Command program officers, European hub airport procurement directors, ground handling service operations executives, and aerospace tier-one supplier business development leads. Secondary validation drew from Pentagon budget justification materials, EU Green Deal implementation reports, and customs trade data for titanium alloy flows. Bottom-up equipment shipment analysis and top-down defense budget allocation triangulation anchored volume estimates.
Assumptions held fixed across the modeling period include NATO membership composition, existing FAA hydrant system safety standards, and Jet A fuel property specifications. Variables tested included sustainable aviation fuel blending mandate acceleration timelines, autonomous ground vehicle adoption rates, and titanium supply source diversification progress. Segmentation dimensions modeled encompass product type, end user category, installation permanence, and fuel handling protocol. CAGRs were derived from equipment replacement cycle analysis and procurement pipeline visibility. Industry-specific forecast inputs incorporated KC-46A multi-year procurement schedules and EU F-Gas Regulation compliance deadlines.
Practitioners should monitor titanium supply source diversification progress, EASA certification timeline compression signals, and autonomous ground vehicle trial expansion for early indicators of forecast revision necessity. Quarterly review of defense procurement pipeline announcements, sustainable aviation fuel infrastructure contract awards, and Vision 2030 joint venture formation activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market