
 Aerial Refueling Systems Market | 2026-2036
Aerial Refueling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aerial Refueling Systems Market Analysis
The capability gap between full-system integrators and component suppliers is reorganizing competitive hierarchies in aerial refueling. Boeing leverages its KC-46 Pegasus platform to dominate integrated boom system contracts for the U.S. Air Force. Airbus sustains European tanker dominance through its A330 MRTT Multi Role Tanker Transport program. Lockheed Martin Corporation competes in probe and drogue configurations for naval aviation and special mission requirements.
Aerial refueling systems encompass the mechanical, electrical, and fluid transfer equipment enabling fuel delivery from tanker to receiver aircraft during flight, typically operating at flow rates exceeding 1,200 gallons per minute through rigid boom or flexible hose architectures. These systems extend operational range for military strike packages, enable long-haul cargo routes, and sustain intelligence-surveillance-reconnaissance orbits without ground-based refueling infrastructure. Boom systems anchor the largest revenue pool due to their integration into strategic tanker platforms and higher unit values, while unmanned systems represent the fastest-expanding segment as autonomous docking algorithms mature for drone-to-drone refueling applications. Military aviation absorbs the dominant share of procurement budgets, though surveillance applications are gaining traction as persistent aerial coverage requirements intensify.
FAA airworthiness directives and EASA certification standards govern commercial tanker conversions, while MIL-STD-2525 and STANAG 3447 shape NATO interoperability for boom and drogue interfaces. The U.S. Air Force's KC-Y next-generation tanker program and European defense procurement directives will determine which platform architectures achieve scale production. Stakeholders must monitor autonomous refueling demonstrations and corresponding regulatory frameworks to anticipate which system types will transition from developmental to operational status.
Market Dynamics
Autonomous docking algorithms are compressing development timelines for unmanned aerial refueling, forcing legacy system integrators to reallocate R&D budgets toward machine-vision-based contact verification and real-time fuel transfer telemetry.
Growth Catalysts
- NATO STANAG 3447 Harmonization:Standardized boom and drogue interface specifications are enabling cross-border interoperability for allied tanker fleets, reducing fleet-specific engineering costs for defense procurement agencies.
- ISR Orbit Persistence:Intelligence-surveillance-reconnaissance missions require extended loiter times without ground infrastructure, driving demand for probe-equipped unmanned platforms capable of mid-mission fuel reception.
- Titanium Alloy Forging:Advanced metallurgy in receiver coupling mechanisms is extending component life cycles under high-cycle fatigue conditions, reducing maintenance intervals for operational tanker squadrons.
Market Restraints
- Aerospace-Grade Titanium Supply:Concentrated sourcing from Russian and Ukrainian feedstock processors creates input volatility for precision-forged refueling boom components.
- FAA Part 25 Certification Burden:Commercial tanker conversion approvals require extensive flight-test documentation, extending program timelines for civil cargo operators seeking multi-mission flexibility.
- Probe-Drogue Substitution Pressure:Naval aviation's preference for universal probe receptacles limits dedicated boom system procurement for carrier-compatible tanker platforms.
Strategic Opportunities
- US Air Force KC-Y Program:Next-generation tanker procurement will specify autonomous refueling capabilities, creating first-mover advantage for flight-control algorithm developers.
- Drone-to-Drone Architectures:Convergence of swarm coordination software with precision formation flight is enabling distributed tanking networks without manned tanker vulnerability.
- EASA CS-25 Conversion Pathways:Streamlined supplemental type certificate processes for used widebody aircraft are lowering entry barriers for European cargo operators establishing tanker capabilities.
Industry Challenges
- Flight-Test Engineer Scarcity:Specialized expertise in aerial contact dynamics and fuel transfer flutter analysis is concentrating at legacy defense primes, constraining startup participation in demonstration programs.
- Legacy Fleet Integration:Retrofitting digital fuel management systems onto analog-era tanker platforms requires custom wiring harness engineering that compresses program margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerial Refueling Systems Market |
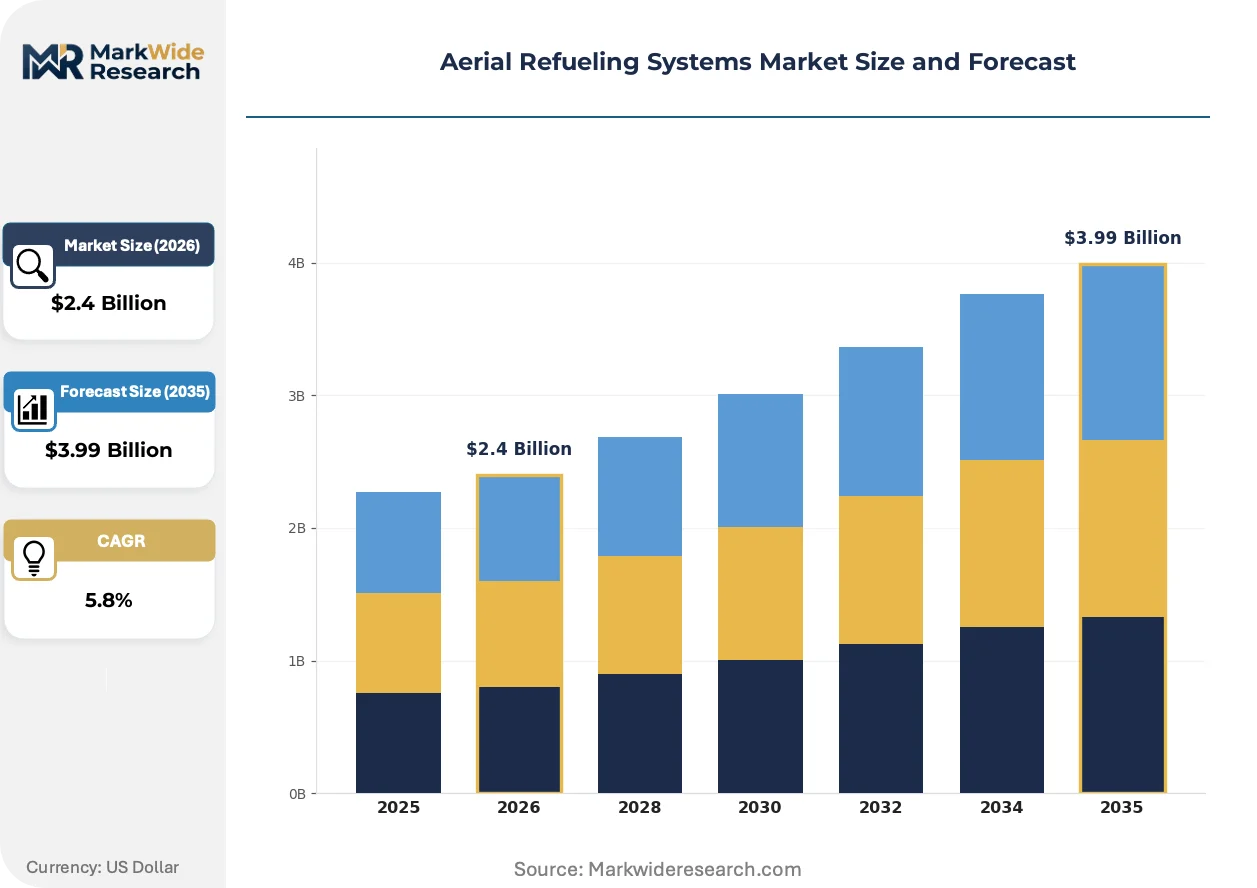
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Boom System, Probe & Drogue, Multi-Point, Unmanned System Application: Military Aviation, Commercial Aviation, Cargo Transport, Surveillance End User: Air Forces, Private Corporations, Government Agencies, Defense Contractors Platform: Aircraft, Helicopters, Drones, Transports |
| Companies Covered | Boeing, Airbus, Lockheed Martin Corporation, Eaton Corporation, Cobham Plc, GE Aviation, Safran, Israel Aerospace Industries, Marshall Aerospace & Defence Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerial Refueling Systems Market Emerging Trajectories
Machine vision and precision flight control are displacing human-operated boom and drogue contact, restructuring qualification requirements for aerial refueling system operators and maintenance personnel across military and emerging commercial applications.
Optical tracking arrays paired with LIDAR-based closure-rate sensing are bifurcating receiver approach procedures into autonomous and assisted-manual modes. The U.S. Navy's MQ-25 Stingray program is validating these sensor fusions for carrier-based unmanned tanking. This capability compression is enabling reduced-manning concepts for future tanker platforms while demanding new airworthiness certification frameworks for unmanned aerial systems.
EASA's emerging CS-UAS special condition for unmanned aircraft systems above 600 kg maximum takeoff weight is mandating fault-tolerant flight control architectures for autonomous refueling demonstrations. European defense procurement directives are incorporating these standards into multinational tanker development programs. A330 MRTT operators in NATO member states are adapting existing boom operator stations for supervisory oversight of autonomous docking sequences.
Defense procurement agencies are consolidating multi-year performance-based logistics contracts that unbundle hardware acquisition from flight-hour availability guarantees. The U.S. Air Force's KC-46 sustainment model replaces transactional spare parts purchasing with contractor-managed inventory at main operating bases. This contractual evolution is most visible in Pacific theater tanker operations, where dispersed basing patterns favor vendor-managed supply chain responsibility over organic depot maintenance capacity.
Aerial Refueling Systems Market Segmentation
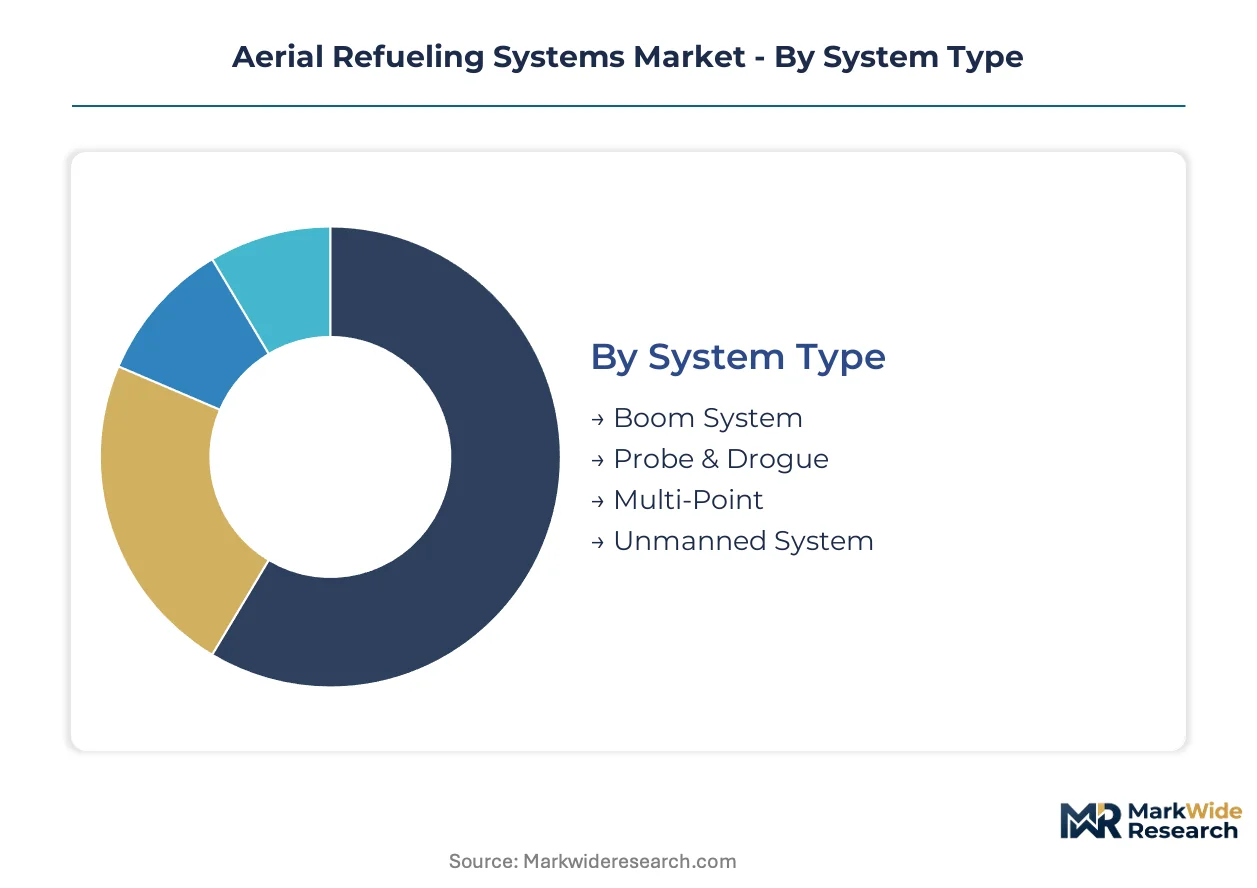
Aerial refueling systems fragment across mission profiles and platform architectures, with procurement patterns diverging sharply between sovereign defense budgets and commercial cargo operators. Segment boundaries are blurring as autonomous technologies enable unmanned tanking capabilities that cut across traditional military-civilian divides.
System Type:
Export-led demand concentrates in boom and probe-drogue systems for NATO-aligned air forces, while unmanned architectures remain domestically focused on U.S. Navy and Air Force development programs. Domestic procurement dominates multi-point configurations for specialized national tanker fleets.
- Boom System:Rigid telescoping booms with fly-by-wire control surfaces deliver fuel at rates exceeding 1,200 gallons per minute through receiver aircraft dorsal receptacles. U.S. Air Force KC-46 procurement anchors global demand, with STANAG 3447 standardization enabling cross-allied interoperability for European and Pacific theater operations.
- Unmanned System:Autonomous docking algorithms paired with machine-vision contact verification enable drone-to-drone fuel transfer without human operator intervention. U.S. Navy MQ-25 Stingray development contracts concentrate investment, with EASA CS-UAS special conditions shaping European regulatory pathways for future certification.
- Probe & Drogue:Flexible hose configurations with stabilized drogue baskets serve naval aviation and tactical fighter reception.
- Multi-Point:Hybrid architectures combining boom and hose stations on single tanker platforms maximize mission flexibility for mixed receiver fleets.
Boom System commands the established base. The steepest expansion runs through Unmanned System.
Application:
Cost tier stratification separates developmental autonomous programs from mature military sustainment contracts, with commercial aviation conversions occupying a narrow middle band constrained by certification burden.
- Military Aviation:Strike package range extension and persistent ISR orbit sustainment drive procurement for fighter, bomber, and reconnaissance platforms. NATO tanker fleet modernization programs across Germany, France, and the United Kingdom concentrate regional demand, with Indo-Pacific dispersal requirements accelerating Pacific theater investment.
- Surveillance:Intelligence-surveillance-reconnaissance missions demand extended loiter without ground infrastructure, creating specialized probe-equipped unmanned platforms. U.S. Customs and Border Protection and allied coast guard services anchor procurement, with maritime patrol requirements expanding sensor-fusion tanking integration.
- Cargo Transport:Long-haul freighter range extension enables hub bypass for time-critical logistics chains.
- Commercial Aviation:Passenger aircraft ferry and delivery operations represent limited civil application constrained by FAA Part 25 conversion costs.
Military Aviation absorbs the dominant procurement volume. Surveillance climbs fastest as persistent coverage mandates intensify.
End User:
Customer type determines contract structure, with air forces favoring performance-based logistics and defense contractors pursuing development funding for autonomous systems.
- Air Forces:Sovereign strategic tanker inventories require integrated fleet management with multi-decade sustainment horizons. U.S. Air Force KC-Y program specifications and European defense procurement directives shape platform requirements, with dispersed basing patterns favoring vendor-managed supply chain responsibility.
- Defense Contractors:Prime integrators and subsystem specialists compete for developmental autonomous refueling contracts. Boeing, Airbus, and Lockheed Martin sustain tier-one positions through platform-integrated offerings, while algorithm developers target flight-control software procurement.
- Government Agencies:Coast guard, border patrol, and scientific research services operate specialized tanker-converted platforms for mission-specific endurance.
- Private Corporations:Cargo operators and aerial firefighting services represent emerging commercial demand with limited current scale.
Air Forces command the established base. Defense Contractors see the steepest capability expansion through autonomous development.
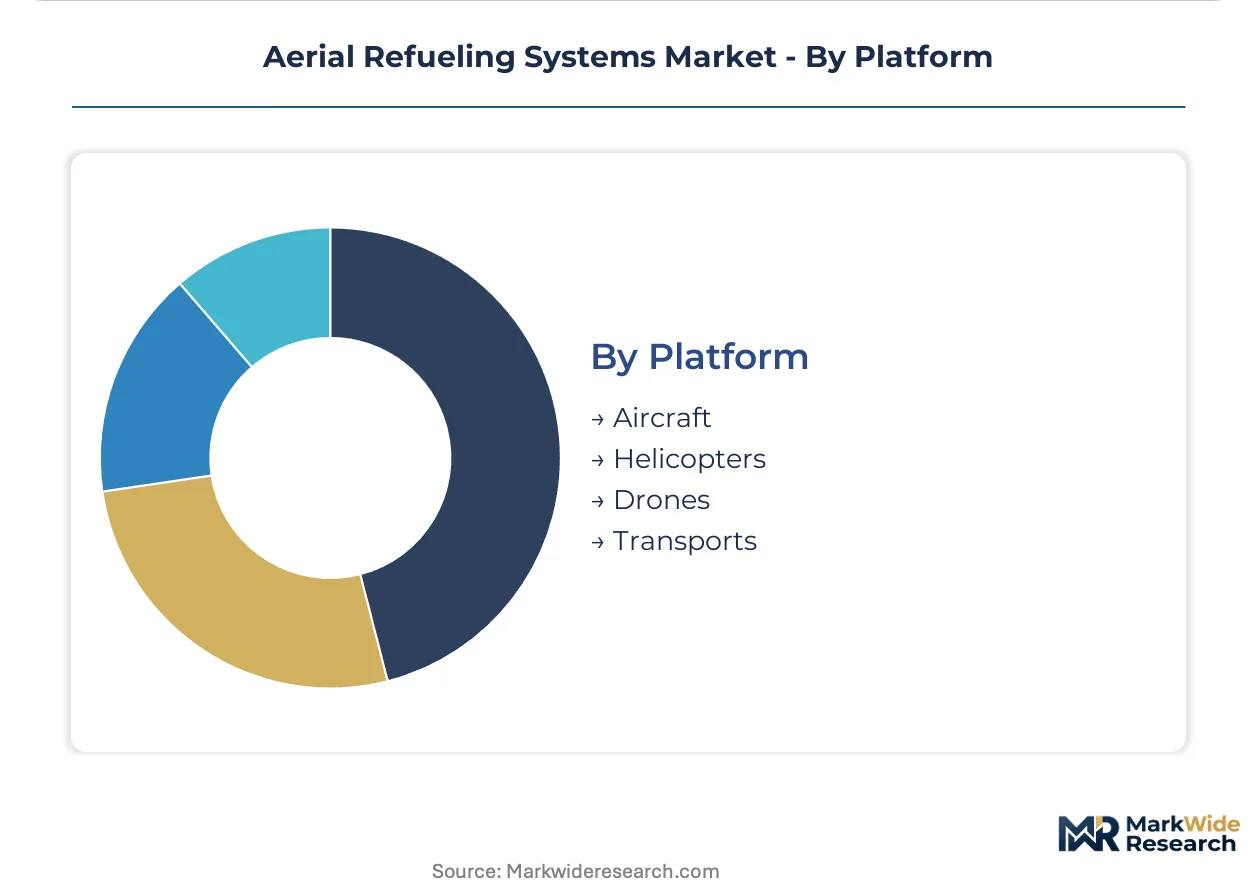
Platform:
Volume concentration follows military airframe procurement cycles, with transports and aircraft dominating unit production while drones capture disproportionate R&D investment.
- Aircraft:Widebody strategic tankers and narrowbody tactical platforms constitute the core installed base. Airbus A330 MRTT and Boeing KC-46 programs define the large-aircraft segment, with national tanker fleets in Australia, South Korea, and Singapore expanding Asia-Pacific presence.
- Drones:Unmanned platforms span loyal wingman tanking concepts through autonomous swarm coordination architectures. U.S. Air Force Skyborg and Navy MQ-25 programs concentrate investment, with European FCAS and Tempest initiatives incorporating drone-to-drone refueling into sixth-generation fighter ecosystems.
- Helicopters:Special operations and search-rescue missions employ probe-equipped rotorcraft for extended range.
- Transports:C-130 and A400M derivatives serve dual-role cargo-tanker configurations for tactical airlift units.
Aircraft commands the established base. Drones gain share fastest through autonomous capability maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with U.S.-based integrators commanding premium contract values, while European suppliers compete on interoperability certification and Asian procurement remains development-focused.
United States
The U.S. Air Force maintains the world's largest strategic tanker inventory through KC-46 and KC-Y program procurement. FAA Part 25 certification requirements govern commercial tanker conversions, while MIL-STD-2525 shapes military interoperability standards. Boeing's integrated production facilities in Washington State and Kansas anchor domestic boom system manufacturing, with dispersed basing across Pacific theater installations driving vendor-managed logistics demand.
France
Airbus Defence and Space sustains European tanker dominance through A330 MRTT production for NATO allies. EASA CS-25 standards and emerging CS-UAS special conditions for unmanned systems above 600 kg regulate certification pathways. The Toulouse aerospace cluster concentrates final assembly and flight-test capabilities, with French defense procurement directives influencing multinational tanker development specifications.
United Kingdom
Royal Air Force Voyager fleet modernization and NATO STANAG 3447 harmonization drive probe-drogue system demand. UK Ministry of Defence equipment plans prioritize multi-point refueling architectures for mixed receiver compatibility. Marshall Aerospace & Defence Group operations in Cambridge sustain legacy platform conversion expertise, with Farnborough-area engineering clusters supporting flight-test documentation for EASA compliance.
Israel
Israel Aerospace Industries specializes in special mission tanker conversions and probe-equipped unmanned platforms for persistent surveillance orbits. Israeli defense procurement emphasizes indigenous modification capabilities for tactical fighter range extension. Lod-based engineering centers develop autonomous docking algorithms, with Tel Aviv-area technology clusters contributing machine-vision sensor fusion for reduced-manning tanker concepts.
Japan
Japan Air Self-Defense Force KC-46 acquisitions and indigenous tanker development programs expand regional fleet capabilities. METI industrial policy supports aerospace supplier base strengthening for defense export competitiveness. Nagoya-area manufacturing clusters produce precision-forged titanium components for receiver coupling mechanisms, with Kawasaki Heavy Industries integration work concentrated in Gifu and Aichi prefectures.
Aerial Refueling Systems Market Vendor Landscape
Concentration sits with full-system integrators possessing platform-embedded refueling architectures. Tier-one positions consolidate around airframe manufacturers with captive tanker programs, while component specialists compete for subsystem procurement across multiple platforms. Two strategic archetypes dominate: integrated platform providers leveraging airframe-tanker bundling, and subsystem specialists targeting upgrade and sustainment contracts. Competitive moves center on performance-based logistics contracting and autonomous refueling algorithm development partnerships.
Among U.S.-based defense primes, Boeing and Lockheed Martin Corporation occupy positions spanning integrated boom and probe-drogue configurations. Airbus represents the European integrated platform archetype through its A330 MRTT program. These three exemplify the tier-one structure where airframe-tanker integration determines contract access, while specialists including Eaton Corporation and Safran sit within subsystem supply tiers for fuel transfer and flight control components.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Lockheed Martin Corporation |
| Eaton Corporation |
| Cobham Plc |
| GE Aviation |
| Safran |
| Israel Aerospace Industries |
| Marshall Aerospace & Defence Group |
| Others |
Supply Flow & Price Mechanics
Aircraft-scale forging capacity utilization above 85% in U.S. and Japanese titanium mills anchors supplier pricing power for precision-machined refueling boom components, compressing margins for subsystem integrators while elevating entry barriers for non-aerospace-qualified entrants. This scale concentration reinforces long-term contracting preferences among Air Force procurement officers seeking flight-hour availability guarantees over transactional spare parts purchasing.
Pricing Analysis
Configured-to-order boom systems command 40-60% premiums over standard probe-drogue configurations due to fly-by-wire integration complexity and STANAG 3447 certification requirements. The dominant contract structure runs through performance-based logistics with contractor-managed inventory, where pricing stratifies across flight-hour tiers, platform age brackets, and Pacific theater dispersal requirements. Cost compression in probe-drogue subsystems is intensifying because naval aviation's universal receptacle preference limits dedicated boom procurement volumes. Cargo operators and government agencies exhibit highest price sensitivity due to FAA Part 25 conversion cost exposure, while Air Forces accept premium positioning for integrated fleet management.
Supply Chain Analysis
Strait of Hormuz transit vulnerability and Russian feedstock exclusion are reshaping titanium sponge sourcing patterns for aerospace-grade receiver coupling mechanisms. Precision forging capacity concentrates in the United States, Japan, and France, with Nagoya-area mills and Toulouse clusters supplying critical boom actuator housings. The supply chain draws from Ukrainian titanium feedstock processors, Japanese vacuum arc remelters, and U.S. closed-die forgers, creating single-source vulnerability for high-cycle fatigue components. Distribution runs through prime-integrator vendor-managed inventory at main operating bases rather than organic depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerial refueling is crossing into platform-economics territory as autonomous docking algorithms and STANAG 3447 interoperability standards enable ecosystem lock-in effects previously absent from hardware-centric procurement.
For Market Incumbents: Consolidate algorithm development partnerships with flight-control software specialists before autonomous refueling specifications harden in KC-Y program requirements. Capture aftermarket telemetry data streams from installed boom systems to reinforce recurring-revenue positioning against probe-drogue substitution pressure from naval aviation procurement officers. Priority lever sits with backward integration into machine-vision sensor fusion for reduced-manning tanker concepts. For New Entrants and Emerging Players: Lead with EASA CS-UAS certification pathway specialization for unmanned systems above 600 kg, where regulatory complexity exceeds incumbent defense prime agility. White-space targets include European cargo operator tanker conversions through streamlined supplemental type certificate processes and drone-to-drone refueling software for FCAS and Tempest sixth-generation fighter ecosystems. Go-to-market angle centers on algorithm licensing rather than platform integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among flight-control algorithm developers with KC-Y program positioning and performance-based logistics contractors managing Pacific theater vendor-managed inventory. Long-term viability favors subsystem specialists with FAA/EASA dual-certification capabilities and titanium forging relationships outside Russian supply chains. Signal to watch is MQ-25 Stingray program transition from development to production-rate contracting as unmanned tanking validation milestone.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Docking Algorithm Development | Machine-vision contact verification enables reduced-manning tanker platforms for KC-Y program specifications. |
| Performance-Based Logistics Contracting | Flight-hour availability guarantees replace transactional spare parts purchasing across Pacific theater installations. |
| EASA CS-UAS Certification Pathway Investment | Special condition compliance for unmanned systems above 600 kg opens European defense procurement channels. |
| Titanium Supply Chain Reconfiguration | Non-Russian feedstock sourcing secures aerospace-grade forging capacity for precision boom components. |
| STANAG 3447 Interoperability Integration | Standardized boom and drogue interfaces enable cross-allied fleet flexibility for NATO procurement agencies. |
Methodological Framework
The analysis maps boom system, probe-drogue, unmanned system, and multi-point configurations, each validated through tanker fleet program managers, flight-test engineers, defense procurement officers, and subsystem manufacturing directors. Primary fieldwork combined structured interviews with sustainment contracting leads at U.S. Air Force Material Command and European defense procurement agencies with secondary validation against FAA airworthiness directives, EASA certification standards, MIL-STD-2525 specifications, and NATO STANAG documentation. Bottom-up platform delivery forecasts triangulated against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled system type, application mission profile, end-user contract structure, and platform architecture dimensions throughout the forecast period. CAGRs derived from platform procurement cycle analysis and autonomous capability maturation curves, with specific inputs including KC-46 delivery schedules, A330 MRTT export contracts, and MQ-25 development milestone progressions.
Forecasts assume regulatory continuity in FAA Part 25, EASA CS-25, and emerging CS-UAS special conditions; material policy shifts in unmanned aircraft certification or defense procurement directives would require re-modeling. Practitioners should keep alternative scenarios live as autonomous refueling demonstration outcomes and titanium supply chain reconfigurations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Hydrogen Aircraft Market