
 Aircraft Refueling Hose Market | 2026-2036
Aircraft Refueling Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Refueling Hose Market Analysis
Multi-source procurement is decoupling from legacy sole-supplier contracts across the aircraft refueling hose supply base. Eaton leverages captive manufacturing scale to anchor North American defense contracts. Trelleborg competes through advanced polymer compounding expertise for extreme-climate deployments. Parker Hannifin extends its position via integrated fluid systems that bundle hose, coupling, and monitoring hardware.
An aircraft refueling hose is a reinforced, fuel-resistant flexible conduit engineered to aviation-grade specifications, typically incorporating nitrile rubber inner tubes, textile or wire braid reinforcement layers, and synthetic rubber covers rated for jet fuel, gasoline, and wide-cut turbine fuels at operating pressures up to 300 psi. Flexible hose variants dominate installed base volume due to maneuverability requirements on congested aprons, while composite hose constructions represent the fastest-growing technology segment as operators seek reduced weight and improved static dissipation. Multi-point refueling systems anchor military procurement patterns, whereas single-point underwing configurations sustain commercial airline standardization.
FAA certification under Technical Standard Order C110a governs US-manufactured hose assemblies, while EASA CS-25 provisions shape European airworthiness acceptance. China's CAAC coordinates with GB aviation fuel equipment standards to condition domestic market access. India's BIS certification requirements and DGFT import classifications further fragment compliance pathways. Buyers must monitor evolving sustainable aviation fuel compatibility standards as aromatic content variations test existing elastomer formulations.
Market Dynamics
Fleet modernization programs across Asia-Pacific commercial aviation are accelerating hose replacement cycles, while sustainable aviation fuel compatibility requirements are forcing elastomer formulation changes throughout the supply base.
Growth Catalysts
- SAF Compatibility Mandates:EASA and FAA are tightening aromatic content specifications for fuel-handling equipment. Hose manufacturers must reformulate nitrile rubber compounds to withstand biofuel blends, creating replacement demand across installed bases.
- Airport Infrastructure Expansion:China, India, and Indonesia are constructing greenfield aviation fueling systems at 40+ new airports. Each installation requires certified hose assemblies for hydrant systems and mobile dispensers.
- Wire-Braid Reinforcement:Advanced wire-braid construction methods are improving pressure ratings and kink resistance. Military multi-point refueling systems are standardizing on these configurations for operational reliability.
Market Restraints
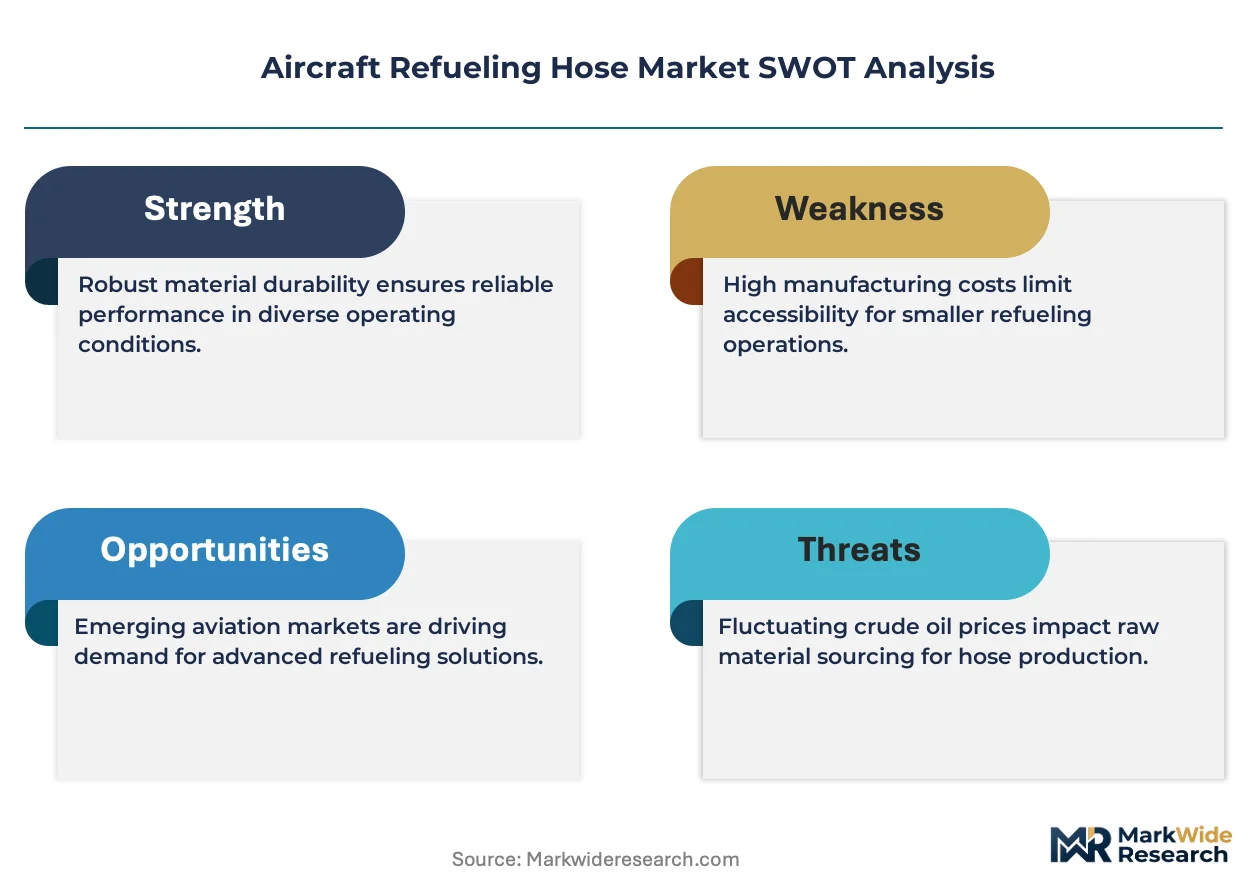
- Nitrile Rubber Price Volatility:Acrylonitrile feedstock costs fluctuate with petrochemical pricing. Compounders face margin compression when passing through raw material increases to aviation OEMs with long-term contracts.
- Supplier Concentration in Polymer Compounding:Three specialized compounders control 70% of aviation-grade nitrile rubber production. Any disruption at these facilities cascades through hose assembly lead times.
- Legacy Certification Lock-In:FAA TSO-C110a and EASA CS-25 grandfathering provisions slow adoption of novel materials. Thermoplastic barrier hoses face extended approval timelines despite performance advantages.
Strategic Opportunities
- Indonesia Fleet Expansion:Garuda Indonesia and Lion Air are adding 200+ narrow-body aircraft through 2030. Each aircraft requires underwing single-point refueling connections and associated ground support hose inventory.
- Integrated Monitoring Systems:Convergence of hose assemblies with pressure sensors and RFID tracking tags enables predictive maintenance. Ground handlers can monitor wear indicators and schedule replacements before failure.
- India PLI Scheme for Aviation Equipment:The Production Linked Incentive scheme offers 4-6% reimbursement on domestic manufacturing of certified fuel-handling equipment. Local assembly of hose couplings and fittings qualifies for these benefits.
Industry Challenges
- Polymer Chemist Shortage:Formulating elastomers for jet fuel, gasoline, and wide-cut turbine fuel compatibility requires specialized expertise. Aviation compounders compete with automotive and oilfield sectors for this talent pool.
- Dual Certification Burden:Manufacturers selling into both US and European markets must maintain parallel testing protocols for FAA TSO-C110a and EASA CS-25. Each certification cycle requires 18-24 months and substantial documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Refueling Hose Market |
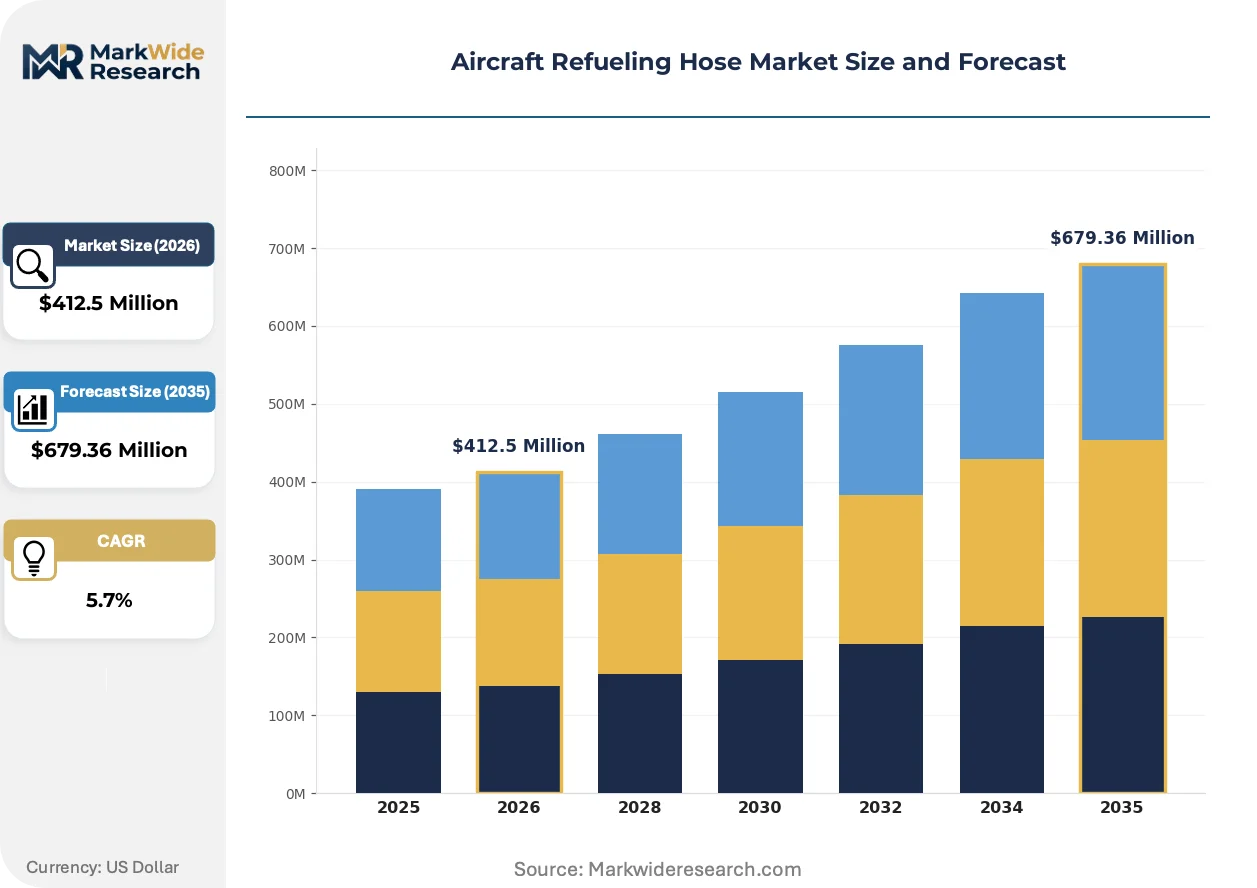
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $679.36 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Hose, Rigid Hose, Composite Hose, Stainless Steel Hose End User: Military Aircraft, Commercial Airlines, Cargo Carriers, General Aviation Technology: Single-Point Refueling, Multi-Point Refueling, Overwing Refueling, Underwing Refueling Diameter: 2 Inch, 3 Inch, 4 Inch, 5 Inch |
| Companies Covered | Parker Hannifin, Eaton, Goodyear, Aero Tec Laboratories, Hose Master, Trelleborg, Elaflex, Garsite, RYCO Hydraulics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Refueling Hose Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization efforts are compressing product development cycles while expanding performance boundaries for aviation fuel handling systems.
Thermoplastic barrier hose constructions are overtaking traditional all-rubber designs in weight-sensitive applications. These assemblies incorporate polyamide or ETFE inner tubes with synthetic fiber reinforcement, reducing unit weight by 30-40% compared to nitrile rubber equivalents. Cargo operators and low-cost carriers operating high-frequency turnarounds are adopting these configurations to improve ground crew ergonomics and reduce fuel consumption during equipment positioning.
REACH restrictions on phthalate plasticizers are compelling European compounders to reformulate cover compounds. The ECHA authorization list now classifies common hose plasticizers as substances of very high concern, forcing migration to bio-based alternatives. German and French hose assemblers are accelerating qualification programs for citrate and polyester plasticizer systems to maintain CE marking compliance.
Airline procurement departments are consolidating ground support equipment suppliers into integrated service contracts. Rather than purchasing hoses, couplings, and monitoring hardware separately, carriers now specify performance-based agreements with single-source providers. This bundling is most advanced at Middle Eastern hub operators, where Emirates and Etihad have consolidated refueling system procurement under five-year managed service arrangements.
Aircraft Refueling Hose Market Segmentation
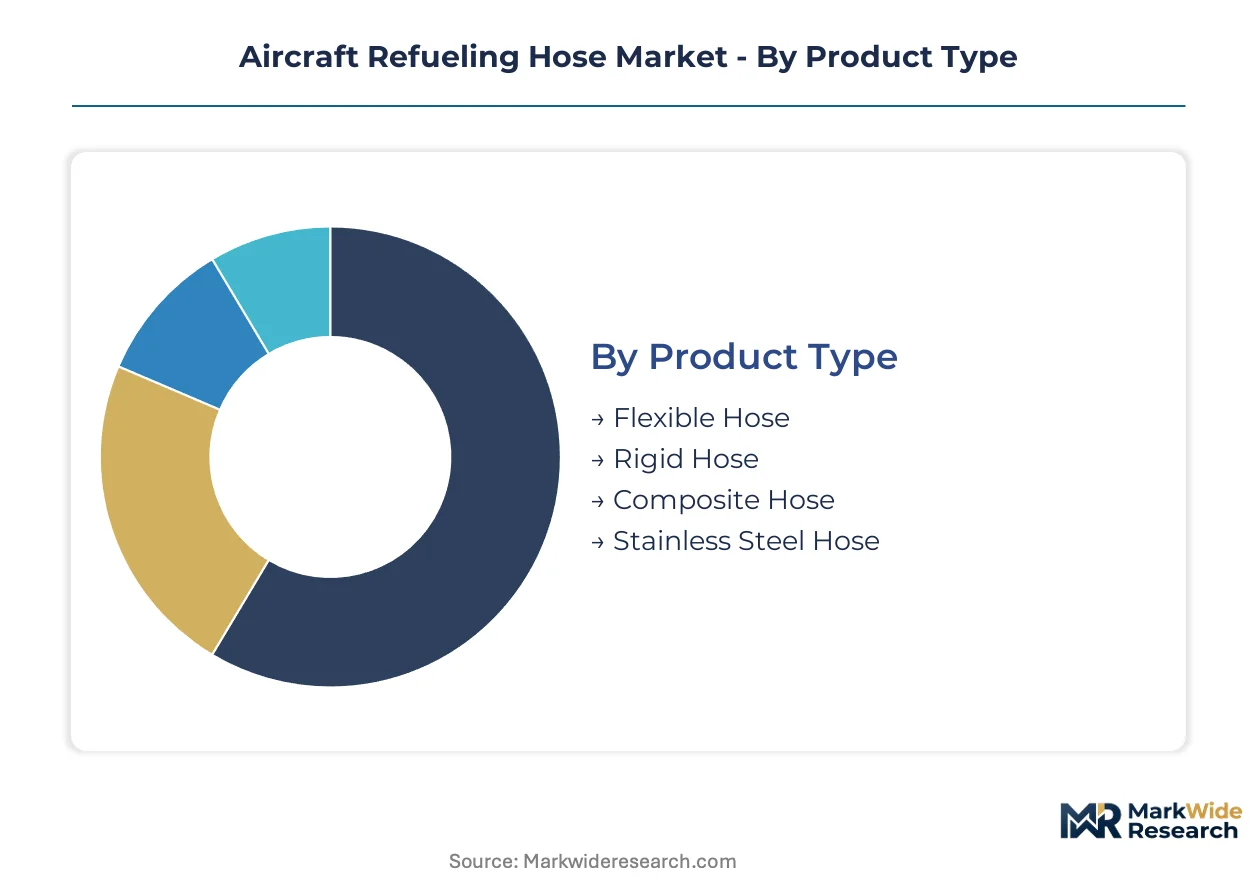
Aircraft refueling hose procurement splits across four distinct axes: physical construction, operator type, fueling interface technology, and dimensional specification. Each axis carries different certification burdens and replacement economics that shape supplier positioning and buyer decision frameworks.
Product Type:
Material composition and reinforcement architecture determine pressure ratings, weight profiles, and compatibility with aromatic fuel blends.
- Flexible Hose:Nitrile rubber inner tubes with textile or wire braid reinforcement dominate commercial apron operations. Garuda Indonesia and Lion Air specify these for narrow-body turnarounds at Jakarta and Denpasar hubs where maneuverability constraints demand kink-resistant constructions.
- Composite Hose:Polyamide or ETFE barrier layers with synthetic fiber reinforcement cut unit weight by 30-40% versus all-rubber equivalents. Cargo operators at Dubai and Singapore Changi are adopting these for high-frequency positioning cycles where ground crew ergonomics drive total cost of ownership.
- Rigid Hose:Metallic or semi-rigid constructions serve fixed hydrant pit installations. These configurations minimize pressure loss across long underground runs at greenfield airports in Chengdu and Navi Mumbai.
- Stainless Steel Hose:Corrosion-resistant braided assemblies withstand aggressive fuel additives and coastal humidity. Military fuel farms at Diego Garcia and Guam specify these for 20-year service life requirements.
Mature deployment sits with flexible hose configurations. Newer deployment is concentrated in composite hose variants.
End User:
Operator categories impose divergent performance specifications, from commercial turnaround speed to military contingency redundancy.
- Commercial Airlines:Scheduled carriers operating Boeing 737 and Airbus A320 fleets drive standardization around single-point underwing connections. AirAsia and IndiGo procurement teams negotiate five-year hose replacement cycles tied to fleet renewal timelines.
- Military Aircraft:Air forces require multi-point refueling systems for rapid deployment scenarios. NATO standardization agreements and China's PLA Air Force specifications both mandate wire-braid reinforcement for tactical fueling trucks.
- Cargo Carriers:FedEx and DHL Express ground handlers prioritize lightweight composite hoses for wide-body freighter operations where equipment positioning frequency exceeds passenger airline norms.
- General Aviation:Fixed-base operators at secondary airports utilize lower-pressure rated assemblies for piston and turboprop refueling. These installations face less stringent aromatic compatibility testing than jet fuel applications.
Volume concentration sits with commercial airlines. Margin expansion is concentrated in military procurement channels.
Technology:
Fueling interface architecture determines hose coupling complexity, flow rate requirements, and spill containment protocols.
- Single-Point Refueling:Underwing pressure fueling through a single connection dominates commercial aviation. Boeing and Airbus both design aircraft around this standard, creating installed base lock-in for compatible ground equipment.
- Multi-Point Refueling:Simultaneous connection to multiple fuel tanks accelerates military aircraft turnaround. These systems require synchronized pressure management across parallel hose assemblies.
- Overwing Refueling:Gravity-fed systems persist at general aviation fields and remote military forward operating locations. Hose assemblies for these applications operate at substantially lower pressure ratings.
- Underwing Refueling:Pressure-assisted connections for high-wing aircraft configurations. Regional turboprop operators at Indonesian and Philippine island airports specify these for ATR 72 and De Havilland Canada Dash 8 fleets.
Standardization sits with single-point configurations. Operational complexity is concentrated in multi-point military systems.
Diameter:
Internal bore dimension directly constrains flow velocity, pressure drop, and compatibility with aircraft fuel panel geometry.
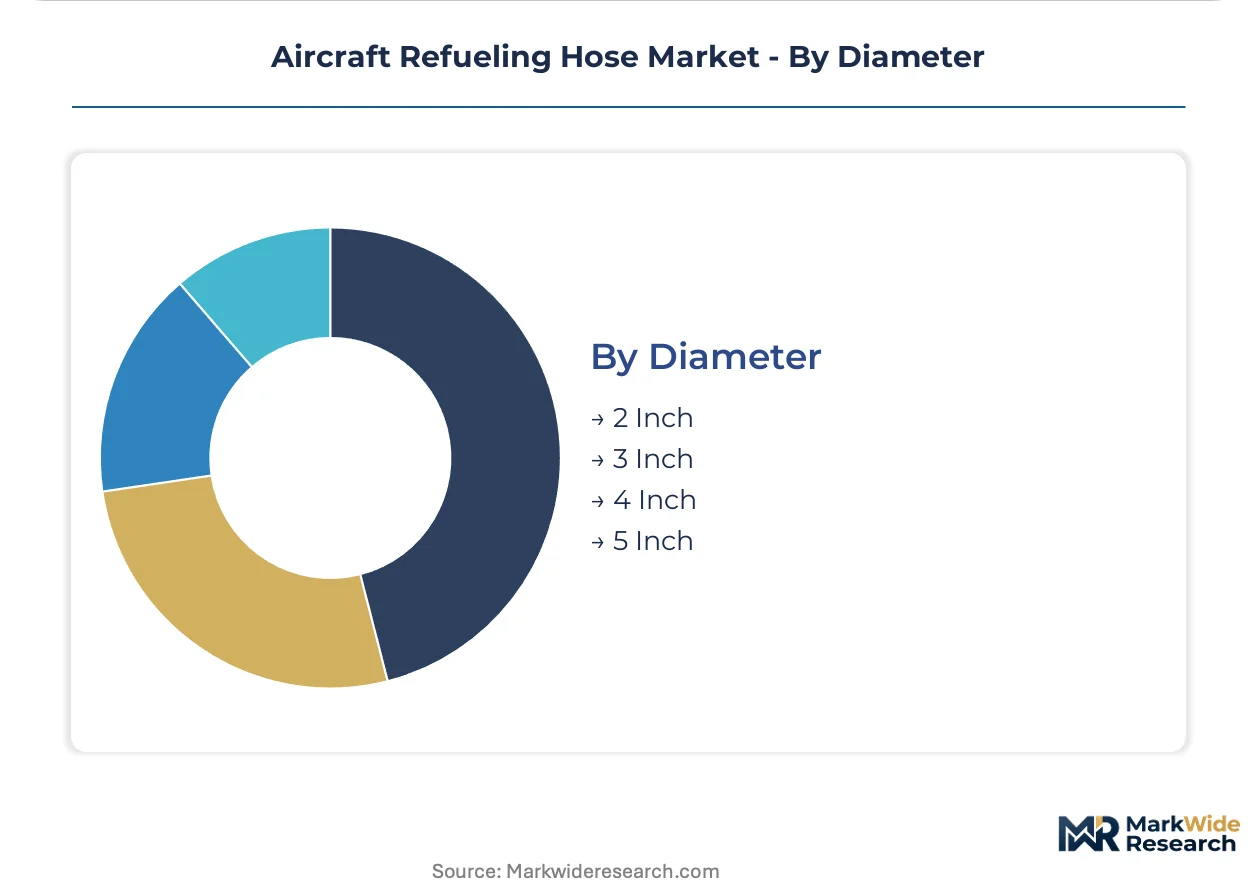
- 3 Inch:Balances flow rate with handling ergonomics for narrow-body commercial operations. This specification dominates procurement at Indian low-cost carriers where rapid turnaround protocols limit fueling window duration.
- 4 Inch:Wide-body aircraft and high-flow military tanker applications require larger bore hoses. These assemblies incorporate heavier wire-braid reinforcement to manage pressure ratings across extended lengths.
- 2 Inch:Restricted to general aviation and helicopter refueling where fuel panel orifice dimensions preclude larger connections. Ground support equipment at Southeast Asian resort airports specifies these for private jet operations.
- 5 Inch:Specialized applications include strategic airlift and aerial refueling tanker ground support. These large-diameter assemblies require dedicated handling equipment and extended certification testing.
Procurement volume sits with 3-inch specifications. Performance requirements are concentrated in 4-inch and 5-inch military applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acrylonitrile feedstock availability in South Korea and Japan anchors polymer compounding capacity for aviation-grade nitrile rubber. Hose assembly demand clusters near major airport construction zones and military fuel farm installations.
United States
Defense fuel farm modernization at Diego Garcia and Guam drives stainless steel hose procurement for 20-year service life requirements. FAA TSO-C110a certification governs all domestic manufacturing. Industrial concentration sits with Eaton's captive manufacturing scale anchoring North American defense contracts.
China
Greenfield airport construction in Chengdu and 40+ new aviation fueling systems require certified hose assemblies for hydrant systems and mobile dispensers. CAAC coordinates with GB aviation fuel equipment standards to condition domestic market access. Polymer compounding capacity concentrates in state-owned petrochemical corridors.
Germany
ECHA authorization list classifications on phthalate plasticizers force compounders to reformulate cover compounds for citrate and polyester alternatives. REACH compliance deadlines accelerate qualification programs at hose assemblers. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized aviation rubber processors.
India
AirAsia and IndiGo procurement teams negotiate five-year hose replacement cycles tied to narrow-body fleet renewal timelines. BIS certification requirements and DGFT import classifications fragment compliance pathways. The PLI scheme offers 4-6% reimbursement on domestic manufacturing of certified fuel-handling equipment at Navi Mumbai and Delhi-NCR assembly sites.
Indonesia
Garuda Indonesia and Lion Air are adding 200+ narrow-body aircraft through 2030, each requiring underwing single-point refueling connections and ground support hose inventory. Airport infrastructure expansion at Jakarta and Denpasar hubs proceeds fastest. Regional turboprop operators at island airports specify pressure-assisted connections for ATR 72 fleets.
Aircraft Refueling Hose Market Vendor Landscape
Global majors compete with regional champions across certification pathways and polymer compounding expertise. The supply base shows moderate concentration, with three specialized compounders controlling the majority of aviation-grade nitrile rubber production. Two strategic archetypes dominate: integrated fluid systems providers bundling hose, coupling, and monitoring hardware, and polymer specialists competing through advanced compounding for extreme-climate deployments. Competitive moves center on backward integration into captive polymer supply and geographic expansion through local assembly partnerships.
Among North American industrials, Parker Hannifin and Eaton occupy positions as scale-driven systems integrators. Parker Hannifin exemplifies the bundled-service archetype, while Eaton anchors defense procurement through manufacturing presence. Trelleborg represents the European polymer specialization vector, with its name signaling Scandinavian compounding heritage. These three names illustrate how competitive positioning splits between integrated systems and materials science depth.
| Leading Market Players |
|---|
| Parker Hannifin |
| Eaton |
| Goodyear |
| Aero Tec Laboratories |
| Hose Master |
| Trelleborg |
| Elaflex |
| Garsite |
| RYCO Hydraulics |
| Others |
Supply Flow & Price Mechanics
Thermoplastic barrier hose adoption is compressing unit economics while fragmenting supplier tiers across the aircraft refueling hose value chain. This material transition simultaneously reduces raw material exposure to acrylonitrile volatility and creates dual qualification requirements that reshape procurement negotiations between ground handlers and assembly manufacturers.
Pricing Analysis
Warranty and service bundling separates premium hose suppliers from commodity assemblers in contract negotiations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales support scope. Cost compression in standard-tier nitrile rubber assemblies is intensifying because long-term airline contracts lock in legacy pricing while feedstock costs fluctuate. Low-cost carriers operating narrow-body fleets exhibit highest price sensitivity, whereas military procurement channels prioritize 20-year service life guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements at major airlines and defense fuel farms mandate multi-supplier qualification for critical hose assemblies. Manufacturing concentrates in the United States, Germany, and China, with polymer compounding anchored in South Korea and Japan. Aviation-grade nitrile rubber draws from specialized petrochemical corridors, while thermoplastic barrier layers rest on polyamide and ETFE resin supply. Single-source vulnerability at the three dominant aviation compounders creates cascading lead time risk. Distribution runs through OEM-direct channels for defense contracts and integrated ground support equipment providers for commercial airlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft refueling hose market is becoming a vertical-integration race as manufacturers pursue captive polymer compounding to escape feedstock volatility and certification bottlenecks. Control over nitrile rubber formulation or thermoplastic barrier extrusion represents the decisive upstream lever.
For Market Incumbents: Cement polymer compounding capabilities through acquisition or joint venture with South Korean or Japanese petrochemical specialists. Lock in exclusive supply agreements with Garuda Indonesia and Lion Air ahead of their 200+ narrow-body fleet expansion. The threat of thermoplastic barrier displacement demands defensive investment in polyamide extrusion capacity and accelerated FAA-EASA dual certification programs. For New Entrants and Emerging Players: India's PLI scheme for aviation equipment opens a window for domestic hose assembly operations serving AirAsia and IndiGo replacement cycles. Target composite hose configurations for cargo carriers at Dubai and Singapore Changi where weight reduction commands premium positioning. A go-to-market partnership with established ground support equipment integrators bypasses direct airline procurement barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated fluid systems providers seeking polymer depth. The five-to-ten year viability window favors compounders with demonstrated SAF compatibility reformulation capabilities. Acquisition target archetype: mid-scale aviation rubber processor with EASA CS-25 and FAA TSO-C110a approvals and established relationships with Indonesian or Indian carriers. The signal to watch is aromatic content specification tightening by EASA that forces accelerated replacement demand across installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive nitrile rubber supply insulates margin from acrylonitrile price swings at Eaton and Trelleborg. |
| SAF Compatibility Certification Investment | EASA aromatic content mandates create replacement demand for reformulated hose assemblies across European installed bases. |
| Integrated Monitoring System Development | RFID-enabled predictive maintenance contracts lock in five-year managed service arrangements with Emirates and Etihad. |
| Local Assembly Partnership in Indonesia | Jakarta and Denpasar proximity reduces logistics costs for Garuda Indonesia and Lion Air fleet expansion programs. |
| Thermoplastic Barrier Technology Licensing | Polyamide and ETFE expertise transfer accelerates weight-reduction adoption at FedEx and DHL Express cargo operations. |
Methodological Framework
Trade association filings, customs import records, and aviation regulatory certification databases formed the secondary backbone for this analysis. Primary interviews with procurement directors at Southeast Asian low-cost carriers, polymer compounding specialists in Baden-Württemberg, and ground support equipment maintenance heads at Dubai and Singapore Changi validated demand assumptions. Bottom-up triangulation against top-down market sizing from airport construction project databases and fleet expansion announcements ensured cross-verification of volume estimates.
Historical trendline analysis of hose replacement cycles, fleet age distributions, and greenfield airport construction pipelines anchored the projection framework. Segmentation modeling incorporated material construction type, end-user category, fueling interface technology, and internal diameter specification across the analysis window. CAGRs were derived from weighted average of fleet growth projections, SAF mandate implementation timelines, and infrastructure investment commitments. Industry-specific inputs included aromatic compatibility testing schedules and dual certification completion rates.
The model assumes a particular technology adoption path; alternative pathways for thermoplastic barrier penetration would alter the outlook if weight reduction economics shift faster than anticipated. Forecasts reflect assumptions regarding EASA-FAA regulatory harmonization progress and polymer chemist labor pool expansion. A model refresh is warranted upon material change in sustainable aviation fuel blend specifications or major disruption at specialized aviation compounder facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market