
 North America Renewable Aviation Fuel Market | 2026-2036
North America Renewable Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
North America Renewable Aviation Fuel Market Analytics
A capital-intensity divergence between integrated refiners and technology licensors is reorganizing competitive tiers in North America renewable aviation fuel. Neste Oyj leverages its Singapore-to-US supply chain to anchor premium hydroprocessed esters and fatty acids capacity on the Gulf Coast. Montana Renewables competes through backward integration into regional feedstock collection across the northern Rockies. LanzaTech Global Inc. differentiates via gas-fermentation technology that converts waste carbon into alcohol-to-jet intermediates.
North America renewable aviation fuel comprises synthesized hydrocarbons meeting ASTM D7566 specifications, produced through hydroprocessing of lipids, gasification of biomass, or alcohol conversion pathways to achieve jet-engine compatibility and lifecycle carbon reductions. The product-type dimension centers on hydroprocessed sustainable aviation fuel as the dominant commercial category, while Fischer-Tropsch synthetic jet fuel occupies a nascent but technically validated position for military offtake. Among end users, commercial airlines command the largest volume commitments, whereas cargo carriers represent the fastest-growing demand segment as logistics operators align with Scope 3 reduction targets.
The US EPA administers renewable volume obligations under the Renewable Fuel Standard, while California's Air Resources Board enforces the Low Carbon Fuel Standard with declining carbon-intensity benchmarks that directly inflate SAF credit values. FAA sustainability grants and the Inflation Reduction Act's clean fuel production tax credits further reshape project economics for domestic biorefinery developers. Stakeholders must monitor how state-level low-carbon fuel programs fragment or harmonize compliance pathways across US and Canadian jurisdictions.
Market Dynamics
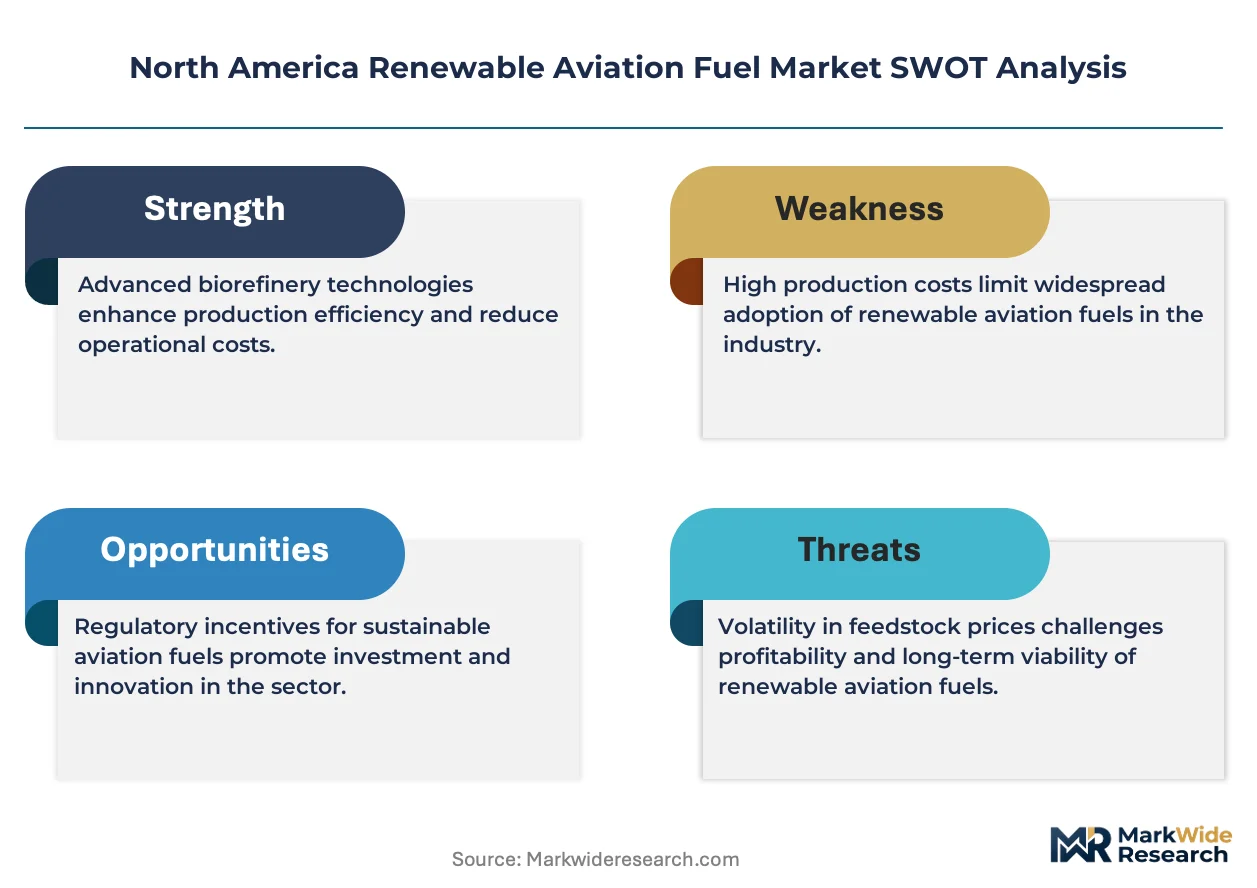
ASTM D7566 certification pathways are fragmenting competitive tiers between hydroprocessed lipid producers and emerging alcohol-to-jet developers, forcing capital allocation decisions that favor either feedstock security or technology licensing scale.
Growth Catalysts
- California's Low Carbon Fuel Standard:Declining carbon-intensity benchmarks inflate SAF credit values and concentrate offtake commitments from major carriers operating West Coast hubs.
- Fischer-Tropsch synthetic jet fuel:Military procurement programs under the US Department of Defense validate alternative pathways beyond hydroprocessed esters and fatty acids.
- Pacific Northwest biorefinery clusters:Existing infrastructure and port access create concentrated production zones that reduce logistics costs for feedstock import and fuel export.
Market Restraints
- Feedstock cost volatility:Used cooking oil and animal fat prices swing with agricultural commodity cycles, compressing margins for hydroprocessed SAF producers without long-term supply contracts.
- Technology licensor concentration:Patent control over gas-fermentation and alcohol-to-jet catalysts rests with a narrow set of technology holders, limiting independent project development.
- Blending wall constraints:Current ASTM D7566 specifications cap neat SAF blending at 50 percent with conventional jet fuel, restricting full displacement potential.
Strategic Opportunities
- Inflation Reduction Act clean fuel production tax credits:Section 45Z credits reshape project economics for domestic biorefinery developers constructing first-of-a-kind facilities.
- Canadian provincial clean fuel regulations:British Columbia and Quebec mandates create parallel offtake markets with less competition for feedstock supply than California.
- Power-to-liquid synthesis:Electrofuel pathways combining green hydrogen with captured carbon dioxide offer lifecycle carbon reductions beyond conventional biomass routes.
Industry Challenges
- ASTM D7566 annex certification timelines:Novel production pathways face multi-year qualification processes that delay commercial deployment and tie up R&D capital.
- Alcohol-to-jet catalyst engineering:Scaling gas-fermentation systems from pilot to commercial throughput requires specialized biochemical process expertise in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Renewable Aviation Fuel Market |
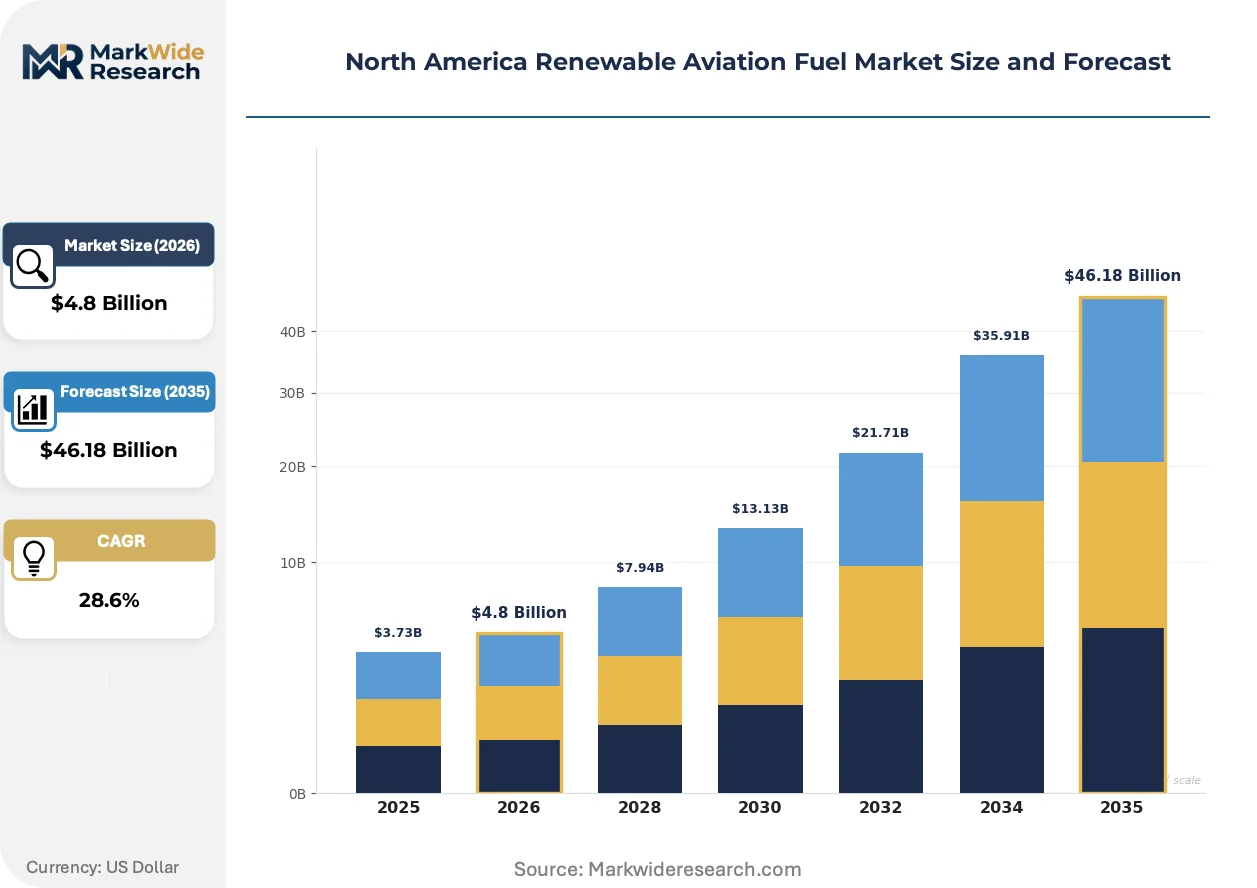
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sustainable Aviation Fuel, Biojet Fuel, Fischer-Tropsch Synthetic Jet Fuel, Alcohol-to-Jet Fuel End User: Commercial Airlines, Private Aviation, Cargo Carriers, Military Aviation Distribution Channel: Direct Supply, Fuel Suppliers, Airport Fueling Systems, Refineries Technology: Hydroprocessing, Gasification, Pyrolysis, Alcohol Conversion |
| Companies Covered | Montana Renewables, Neste Oyj, World Energy LLC, Gevo Inc., TotalEnergies SA, Honeywell UOP, Fulcrum BioEnergy Inc., LanzaTech Global Inc., Red Rock Biofuels LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Renewable Aviation Fuel Market Evolving Landscape
Technology convergence between synthetic fuel production and carbon capture is compressing development cycles for next-generation SAF pathways. Regulatory pressure and carrier procurement mandates are accelerating investment in alternative feedstock routes.
Alcohol-to-jet technology converts waste carbon streams through gas-fermentation into ethanol intermediates suitable for upgrading to synthetic jet fuel. Cargo carriers with Scope 3 reduction targets are piloting offtake agreements for this pathway at faster contract velocity than passenger airlines. Power-to-liquid electrofuels are displacing conventional hydroprocessed SAF in long-term carrier procurement strategies due to superior lifecycle carbon accounting.
The US EPA renewable volume obligations under the Renewable Fuel Standard now include SAF-specific carve-outs that redirect compliance credit flows. Domestic biorefinery developers are restructuring project financing to capture these obligations alongside California LCFS credits. Gulf Coast production hubs are responding by expanding hydroprocessing capacity to serve both regulatory markets simultaneously.
Long-term purchase agreements are replacing spot market procurement as the dominant contracting mode for renewable aviation fuel. Major carriers are negotiating decade-long offtake commitments directly with producers, bypassing traditional fuel suppliers and intermediaries. This pattern is most visible among US legacy airlines operating transcontinental routes where fuel cost hedging intersects with carbon disclosure requirements.
North America Renewable Aviation Fuel Market Segmentation
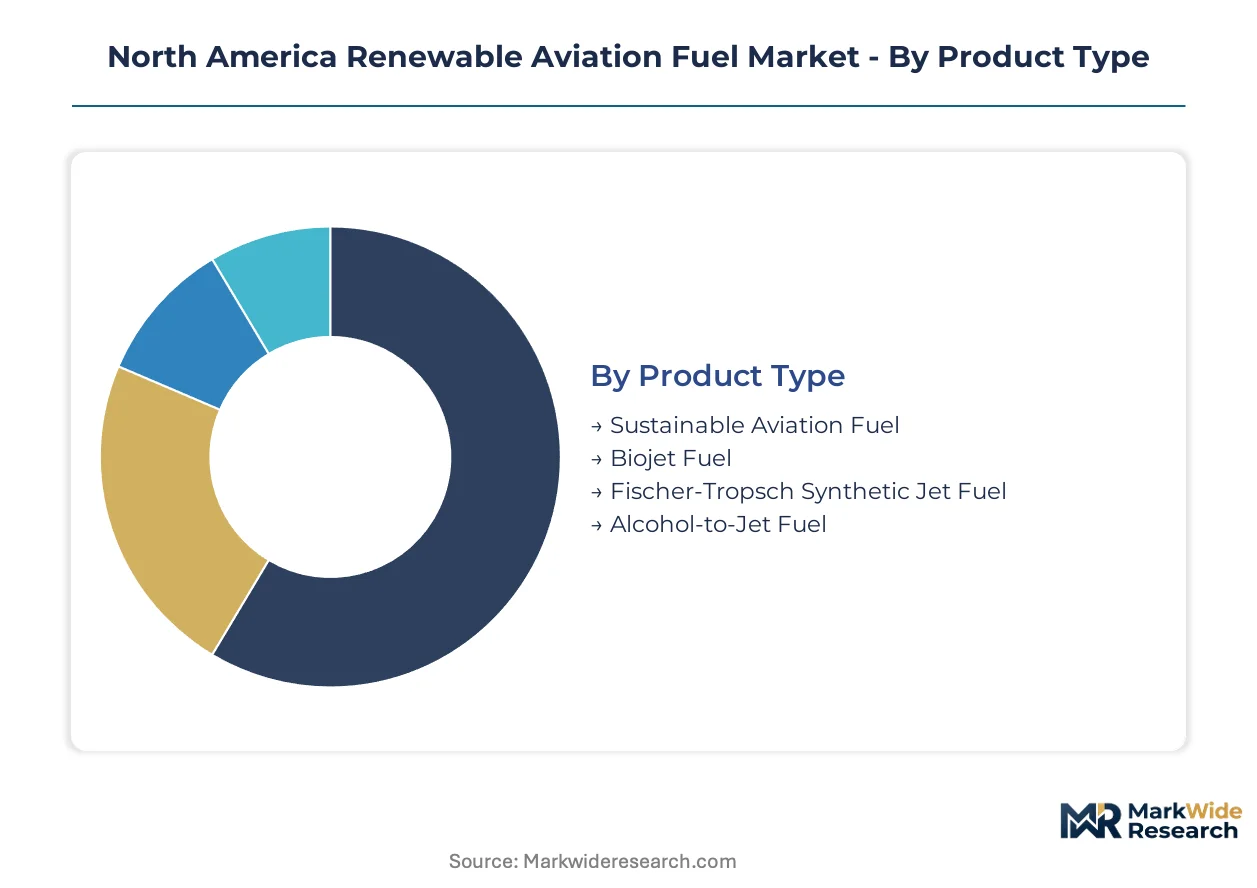
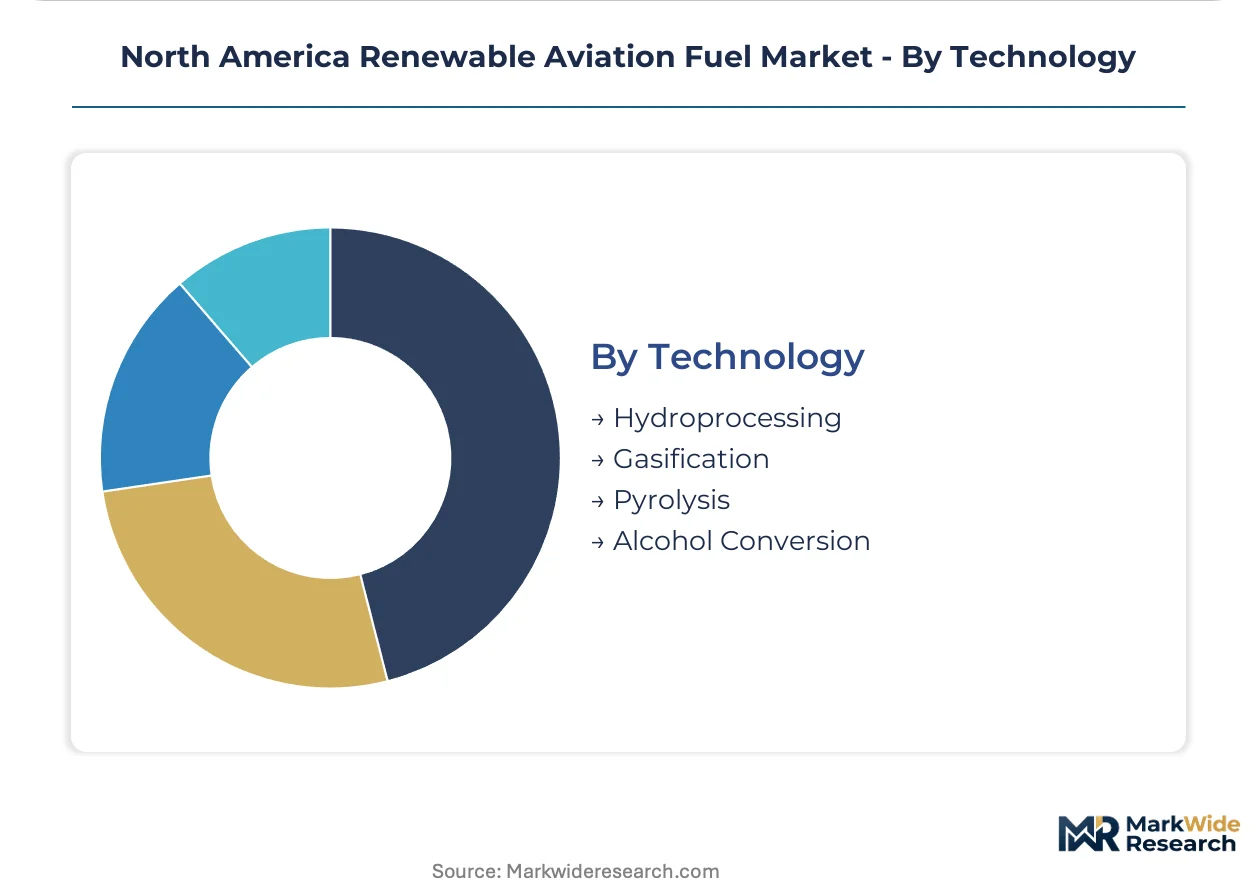
Renewable aviation fuel procurement patterns diverge sharply across production pathways and customer types. ASTM D7566 certification requirements and feedstock availability create asymmetric substitution pressures that reshape segment prioritization for biorefinery developers and carrier procurement teams.
Product Type:
Hydroprocessed esters and fatty acids face the strongest substitution pressure as alcohol-to-jet and power-to-liquid pathways mature with superior lifecycle carbon accounting.
- Sustainable Aviation Fuel:Hydroprocessed lipids meeting ASTM D7566 Annex A specifications dominate commercial offtake from US legacy carriers operating transcontinental routes. California LCFS credit values concentrate demand among West Coast-based airlines seeking compliance with declining carbon-intensity benchmarks.
- Biojet Fuel:Lipid-derived synthetic paraffinic kerosene from renewable feedstocks serves as the primary drop-in replacement for conventional jet fuel in current blending operations. Pacific Northwest biorefinery clusters anchor production capacity due to existing port infrastructure for feedstock import.
- Fischer-Tropsch Synthetic Jet Fuel:Biomass gasification pathway validated for military aviation procurement under US Department of Defense sustainability mandates.
- Alcohol-to-Jet Fuel:Gas-fermentation ethanol intermediates upgraded through dehydration and oligomerization.
Sustainable aviation fuel anchors the volume base while alcohol-to-jet fuel gains share at the steepest rate.
End User:
Customer procurement scale determines contract structure, with volume tiers separating long-term offtake negotiators from spot-market purchasers.
- Commercial Airlines:Legacy US carriers command the largest procurement volumes through decade-long direct agreements with producers. FAA sustainability grants and Inflation Reduction Act Section 45Z tax credits reshape project economics for facilities supplying this segment.
- Cargo Carriers:Logistics operators with Scope 3 reduction targets pilot alcohol-to-jet offtake agreements at faster contract velocity than passenger airlines. FedEx and UPS procurement teams negotiate separately from passenger carrier fuel pools.
- Private Aviation:Fractional ownership fleets and corporate flight departments source through specialized fuel suppliers with premium pricing for low-volume deliveries.
- Military Aviation:US Air Force and Navy procurement programs validate alternative production pathways beyond commercial hydroprocessed routes.
Commercial airlines anchor the volume base while cargo carriers expand most quickly.
Distribution Channel:
Channel selection reflects infrastructure maturity and regulatory credit capture requirements across US and Canadian jurisdictions.
- Direct Supply:Long-term purchase agreements between producers and major carriers bypass traditional intermediaries. This contracting mode concentrates among US legacy airlines with dedicated sustainability procurement teams.
- Fuel Suppliers:Integrated energy companies aggregate SAF volumes for carrier customers without direct producer relationships.
- Airport Fueling Systems:Hydrant infrastructure at major hubs enables blended fuel delivery to multiple carriers simultaneously.
- Refineries:Co-processing facilities at conventional petroleum refineries handle hydroprocessing capacity expansion.
Direct supply anchors the volume base while airport fueling systems climb the fastest as hydrant infrastructure expands.
Technology:
Process maturity and capital intensity separate commercially deployed pathways from pilot-scale alternatives awaiting ASTM certification.
- Hydroprocessing:Lipid transesterification and hydrotreating to paraffinic kerosene represents the dominant commercial technology. Gulf Coast production hubs expand capacity to serve both RFS and LCFS compliance markets simultaneously.
- Gasification:Biomass-to-syngas conversion enables Fischer-Tropsch synthesis for military aviation specifications.
- Pyrolysis:Thermal decomposition of lignocellulosic feedstocks produces bio-oil intermediates requiring upgrading.
- Alcohol Conversion:Ethanol dehydration and oligomerization creates synthetic jet fuel from gas-fermentation outputs.
Hydroprocessing anchors the volume base while alcohol conversion shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America renewable aviation fuel market exhibits a pronounced trade asymmetry: the United States imports refined SAF volumes from Nordic producers while domestic biorefinery capacity concentrates in export-oriented Gulf Coast and Pacific Northwest clusters. Canadian production remains insufficient for cross-border supply, forcing both nations to develop parallel domestic supply chains under divergent regulatory credit systems.
United States
California and the Pacific Northwest anchor domestic offtake demand through the state's Low Carbon Fuel Standard and concentrated airline hub operations. The EPA administers renewable volume obligations under the Renewable Fuel Standard with SAF-specific carve-outs that redirect compliance credit flows toward domestic producers. Gulf Coast biorefinery clusters near Houston and Port Arthur expand hydroprocessing capacity to serve both RFS and LCFS markets simultaneously.
Canada
British Columbia and Quebec provincial clean fuel regulations create parallel offtake markets with less feedstock competition than California. Environment and Climate Change Canada coordinates with the country's national energy regulator to align federal carbon pricing with provincial low-carbon fuel mandates. Alberta's existing oil refining infrastructure near Edmonton hosts pilot projects for co-processing renewable feedstocks through conventional hydrotreaters.
Mexico
Mexico City International Airport and Monterrey cargo hubs generate nascent demand from logistics operators seeking Scope 3 reductions for cross-border freight. The country's national energy regulator has not enacted binding SAF mandates, leaving procurement driven by voluntary corporate sustainability commitments. Baja California and Sonora states explore feedstock supply relationships with California biorefineries given geographic proximity.
North America Renewable Aviation Fuel Market Competitive Landscape
Concentration sits with integrated refiners and technology licensors rather than pure-play producers, creating a tiered structure where capital intensity separates commercial-scale operators from pilot-stage developers. Two strategic archetypes dominate: backward-integrated regional feedstock aggregators in the northern Rockies and Gulf Coast, and technology licensors controlling gas-fermentation and alcohol-to-jet catalyst patents. Dominant competitive moves include long-term offtake contracting with major carriers and strategic partnerships between feedstock suppliers and hydroprocessing capacity owners.
Within the integrated refiner archetype, Neste Oyj and Montana Renewables exemplify divergent geographic positioning strategies for North American market access. LanzaTech Global Inc. occupies the technology licensor tier, representing the gas-fermentation pathway that converts waste carbon streams into alcohol-to-jet intermediates. These three entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| Montana Renewables |
| Neste Oyj |
| World Energy LLC |
| Gevo Inc. |
| TotalEnergies SA |
| Honeywell UOP |
| Fulcrum BioEnergy Inc. |
| LanzaTech Global Inc. |
| Red Rock Biofuels LLC |
| Others |
Value Network & Pricing Analysis
Gulf Coast hydroprocessing scale economies concentrate production capacity near Houston and Port Arthur, compressing unit costs for integrated refiners while anchoring price floors for the broader market. This geographic clustering concentrates bargaining power among backward-integrated operators with captive feedstock supply, forcing smaller technology licensors to compete on carbon-intensity premiums rather than base price.
Pricing Analysis
Commercial airlines anchor long-term offtake contracting as the dominant pricing structure, with decade-spanning agreements replacing spot market procurement. Price differentiation rests on California LCFS credit stacking versus standalone RFS compliance value, with West Coast deliveries commanding premiums over Gulf Coast supply. Pricing pressure stems from used cooking oil and animal fat cost volatility compressing margins for hydroprocessed SAF producers without long-term supply contracts. Cargo carriers demonstrate highest price sensitivity due to thinner operating margins, while military aviation procurement shows lowest sensitivity given sustainability mandate compliance requirements.
Supply Chain Analysis
Strait of Malacca transit underwrites Nordic-to-US SAF import flows, creating a chokepoint that concentrates supply risk for non-domestic volumes. Geographic supply concentration centers on Singapore refining hubs, US Gulf Coast biorefinery clusters, and emerging Pacific Northwest production zones. Raw material dependencies include waste lipid collection networks, agricultural residue feedstocks, and green hydrogen for power-to-liquid pathways. Single-source vulnerability runs through proprietary gas-fermentation catalyst supply controlled by narrow technology licensor tiers. Distribution runs through airport hydrant infrastructure at major hubs, enabling blended fuel delivery to multiple carriers simultaneously.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across US states and Canadian provinces creates white-space opportunities for specialized operators targeting specific compliance credit markets. Divergent carbon-intensity benchmarking between California LCFS and federal RFS programs fragments demand into addressable niches.
For Market Incumbents: Secure long-term feedstock supply contracts through backward integration into regional waste oil collection networks, insulating margin structures from agricultural commodity volatility. Expand hydroprocessing capacity at Gulf Coast hubs to capture simultaneous RFS and LCFS credit stacking. Alcohol-to-jet technology licensors represent an emerging substitution threat requiring monitoring of ASTM D7566 annex certification timelines. For New Entrants and Emerging Players: Differentiate on power-to-liquid electrofuel pathways with superior lifecycle carbon accounting that commands premium pricing from cargo carriers with aggressive Scope 3 reduction targets. Target Canadian provincial markets in British Columbia and Quebec where feedstock competition remains less intense than California. Pursue direct offtake negotiations with logistics operators rather than competing for legacy airline fuel pool contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors gas-fermentation platform developers with proven pilot-scale throughput awaiting commercial deployment. Long-term viability over the next decade hinges on successful ASTM certification for novel production pathways and sustained regulatory support for clean fuel tax credits. Monitor Inflation Reduction Act Section 45Z credit implementation as an inflection indicator for domestic biorefinery project economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Montana Renewables demonstrates regional waste oil collection network control reduces input cost volatility. |
| Technology Licensing Scale-Up | LanzaTech's gas-fermentation platform validates alternative pathways beyond conventional hydroprocessing routes. |
| Multi-Regulatory Credit Stacking | Gulf Coast producers capture simultaneous RFS and LCFS compliance value through strategic geographic positioning. |
| Direct Airline Offtake Contracting | Major carriers bypass traditional fuel suppliers through decade-long purchase agreements with biorefinery developers. |
| Power-to-Liquid Capacity Buildout | Electrofuel pathways combining green hydrogen with captured carbon offer lifecycle carbon reductions beyond biomass routes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, California Air Resources Board credit transaction data, and FAA sustainability grant disclosures. Primary interviews engaged biorefinery project developers, airline fuel procurement directors, and clean fuel regulatory compliance officers. Secondary validation drew from EIA biofuel production statistics, IEA renewable energy outlooks, and customs trade data for Nordic SAF import volumes. Bottom-up capacity buildout modeling triangulated against top-down demand projections from carrier fleet decarbonization commitments.
Segmentation dimensions modeled include production pathway technology, end-user category, and regulatory compliance framework across the projection horizon. Value outputs reflect capacity utilization assumptions, feedstock cost curves, and credit value projections under existing policy frameworks. CAGRs were derived from facility commissioning timelines and airline offtake contract velocity. Forecast inputs incorporated ASTM D7566 certification pipeline status and provincial mandate expansion trajectories in Canada.
The analysis sits within stated boundaries; outcomes outside sustained federal tax credit support and state-level low-carbon fuel program expansion would require recalibration. Forecasts reflect assumptions regarding technology cost reduction curves and regulatory stability across US and Canadian jurisdictions. Practitioners should keep alternative scenarios live as feedstock availability constraints and blending wall specifications evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market