
 Aviation Gasoline (Avgas) Market | 2026-2036
Aviation Gasoline (Avgas) Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Gasoline (Avgas) Market Intelligence
The split between leaded Avgas 100LL and emerging unleaded alternatives is realigning procurement patterns across the general aviation supply chain. Shell leverages its integrated refining and distribution footprint to sustain volume leadership at major hub airports. ExxonMobil anchors its position through proprietary additive packages and long-term supply contracts with fixed base operators. Chevron Corporation competes on geographic reach, particularly across the western United States where its branded FBO network dominates.
Aviation gasoline is a specialized petroleum fuel formulated for spark-ignition piston aircraft engines, with Avgas 100LL containing up to 0.56 grams of tetraethyl lead per liter to prevent detonation in high-compression powerplants. Its primary purpose is to deliver consistent octane performance across varying altitude and temperature conditions where automotive gasoline would fail. Among product grades, Avgas 100LL occupies the dominant share due to universal engine compatibility, though Avgas 91/96 and 82UL are gaining traction as the FAA certifies more engines for lower-octane unleaded operation. On the application side, training and recreational flying absorb the bulk of volume, while crop dusting commands premium pricing due to remote delivery logistics and seasonal surge requirements.
The FAA's Piston Aviation Fuels Initiative, EPA Clean Air Act authority over lead emissions, and ASTM International's D910 and D7547 specifications collectively determine which formulations reach market and how quickly. These frameworks create compliance costs that favor integrated refiners with dedicated aviation fuel laboratories and certification teams. Stakeholders must track FAA fleet-wide unleaded certification progress and state-level airport lead mitigation mandates to anticipate infrastructure investment timing and product mix transitions.
Market Dynamics
The EPA's leaded fuel phase-out mandate and the FAA's Piston Aviation Fuels Initiative are forcing refiners to reconfigure production lines and FBOs to invest in dual-fuel infrastructure before certification timelines solidify.
Growth Catalysts
- Flight School Expansion:Training academies in Florida, Texas, and Arizona are doubling fleet orders to address pilot shortages, locking in multi-year offtake agreements with fixed base operators.
- FAA Unleaded Certification Pathway:The Piston Aviation Fuels Initiative is accelerating engine approvals for 100-octane unleaded formulations, expanding the addressable fleet beyond legacy powerplants.
- Remote Agricultural Aviation:Crop dusting operations in the Midwest and Central Valley require high-octane fuel deliveries to unimproved airstrips, sustaining premium pricing tiers for specialized logistics providers.
Market Restraints
- Tetraethyl Lead Supply Concentration:Only two domestic suppliers produce the tetraethyl lead additive essential for Avgas 100LL, creating single-source vulnerability for remaining leaded production.
- ASTM D910 Revision Friction:Specification updates for unleaded alternatives require multi-year balloting and interlaboratory testing, delaying product standardization and insurer acceptance.
- Refinery Conversion Economics:Alkylation unit retrofits for high-octane unleaded output demand capital commitments exceeding $50 million per facility, deterring independent refiners.
Strategic Opportunities
- Unleaded Infrastructure Pre-positioning:FBO chains in California and Colorado are installing multi-product dispensers ahead of state-level lead mitigation mandates, capturing first-mover positioning.
- Alternative Feedstock Pathways:Bio-based aromatic compounds from lignin processing are demonstrating 100-octane equivalence in ASTM testing, opening renewable certification routes.
- Digital Fuel Management Platforms:Cloud-based inventory systems integrating tank level monitoring with automated replenishment are reducing working capital requirements for rural distributors.
Industry Challenges
- Aviation Fuel Chemist Shortage:Specialized formulation expertise for octane enhancement and additive blending is retiring faster than universities produce replacements, constraining R&D velocity.
- Fleet-Wide Unleaded Transition Coordination:Engine manufacturers, airframe OEMs, and fuel suppliers must synchronize STC issuance with distribution infrastructure deployment, requiring unprecedented cross-industry governance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Gasoline (Avgas) Market |
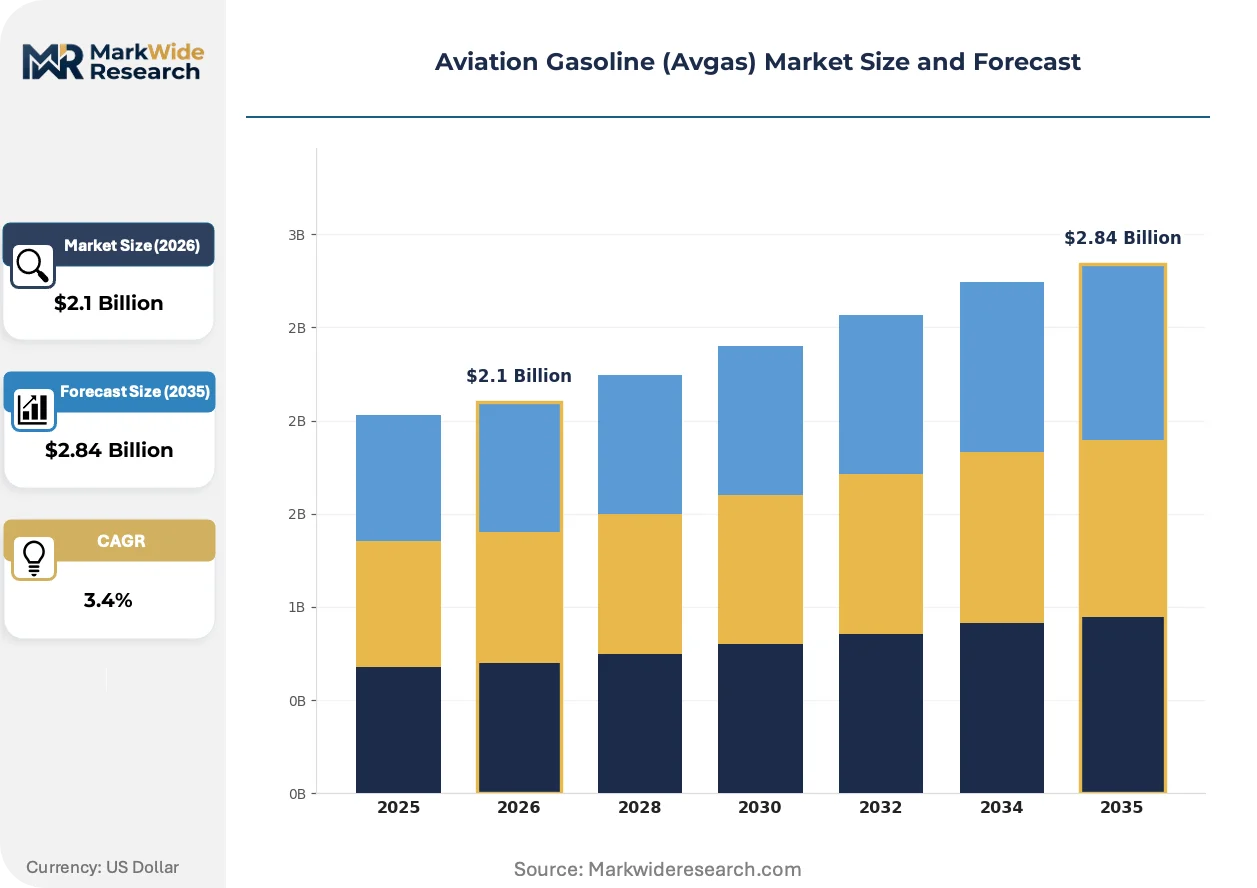
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $2.84 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Avgas 100LL, Avgas 82UL, Avgas 115/145, Avgas 100/130, Avgas 91/96 End User: Private Pilots, Air Taxi Operators, Flight Schools, Agricultural Aviation, Air Racing Application: Recreational Flying, Training, Crop Dusting, Aerobatics, Aerial Surveying Distribution Channel: Aviation Fuel Providers, Fixed Base Operators, Direct Sales, Fuel Retailers, Aero Clubs |
| Companies Covered | TotalEnergies, Chevron Corporation, ExxonMobil, Indian Oil Corporation Limited, Repsol, Shell, Phillips 66, Vitol Group, BP Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Gasoline (Avgas) Market Strategic Shifts & Innovations
Digitalization of fuel logistics and the emergence of certified unleaded alternatives are compressing traditional supply chain hierarchies while regulatory deadlines force simultaneous investment across production, distribution, and consumption nodes.
Automated tank gauging systems equipped with ultrasonic sensors and cellular telemetry are automating inventory reconciliation for FBO operators. Mid-sized airports in Texas and Arizona are deploying these systems to eliminate manual dipstick measurements and reduce out-of-stock incidents during peak training seasons. The technology is automating procurement trigger points, shifting replenishment from calendar-based to consumption-driven models.
The EPA's endangerment finding on leaded aviation fuel under the Clean Air Act is compelling state environmental agencies to advance airport-specific compliance timelines. California's Air Resources Board has mandated lead emissions reductions at municipal fields, pressuring FBOs to install vapor recovery systems and accelerate unleaded dispenser deployment. Refiners are responding with dedicated California-blend production runs to meet anticipated specification divergence.
Flight schools are consolidating fuel purchasing through cooperative procurement organizations, displacing individual FBO negotiations. These buying cooperatives aggregate volume across multiple training fleets to secure delivered-price contracts directly with regional terminals. The practice is most advanced in the Southeast, where ATP Flight School and regional academies have established shared fuel committees to standardize quality assurance and pricing terms.
Aviation Gasoline (Avgas) Market Segmentation
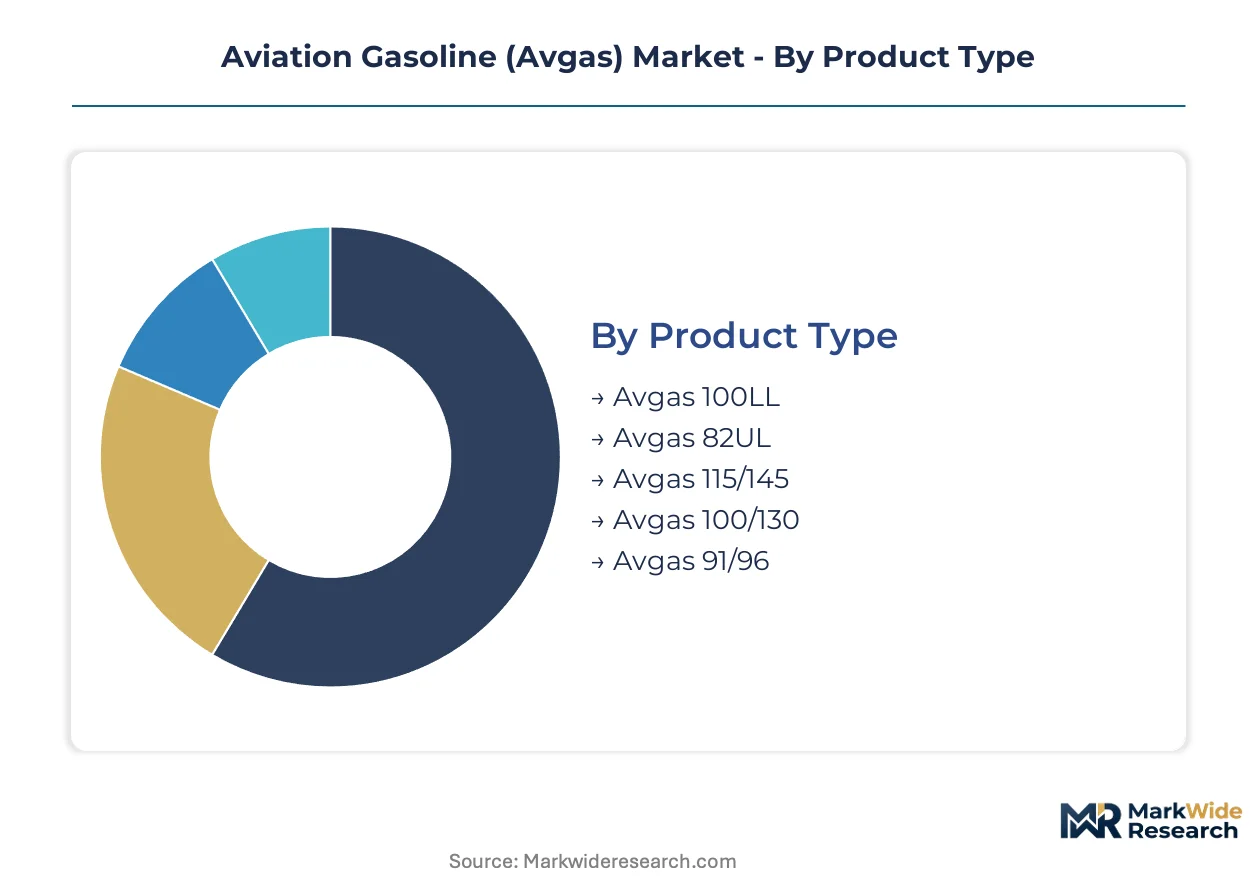
Segmentation in aviation gasoline reveals how capital deployment, regulatory exposure, and operational intensity fragment demand across distinct supply configurations. Each dimension—product grade, end user, application, and distribution channel—carries unique infrastructure requirements and margin structures that determine competitive positioning.
Product Type:
Capital intensity varies dramatically by octane rating and lead content, with high-octane unleaded formulations demanding the most substantial refinery reconfiguration investments.
- Avgas 100LL:Contains up to 0.56 grams of tetraethyl lead per liter to prevent detonation in high-compression piston engines. Demand concentrates among legacy training fleets in Florida and Arizona where engine compatibility concerns delay transition timelines.
- Avgas 82UL:An unleaded lower-octane formulation certified for specific engine types. Flight schools in California are adopting this grade fastest as state-level lead mitigation mandates advance ahead of federal timelines.
- Avgas 115/145:High-octane military specification fuel now limited to air racing and vintage warbird operations.
- Avgas 100/130:Historical grade largely superseded by 100LL, retained only for specific agricultural aviation applications in remote Midwest locations.
- Avgas 91/96:Lower-octane leaded formulation serving legacy light sport aircraft and some aerobatic platforms in the Southeast.
Avgas 100LL absorbs the bulk of installed capacity; Avgas 82UL is expanding most quickly.
End User:
Operational scale and fuel procurement sophistication separate end users into distinct commercial tiers with varying contract structures and quality assurance requirements.
- Flight Schools:High-volume consumers operating standardized fleets with predictable scheduling patterns. ATP Flight School and regional academies in Texas are consolidating purchasing through cooperative procurement organizations to secure delivered-price contracts.
- Agricultural Aviation:Seasonal surge demand from crop dusting operations requiring remote airstrip delivery. Central Valley operators pay premium logistics fees for unimproved field access during planting and harvest windows.
- Private Pilots:Fragmented individual owners purchasing through FBO retail dispensers with limited volume leverage.
- Air Taxi Operators:Part 135 certificate holders with scheduled routes demanding consistent supply reliability at secondary airports.
- Air Racing:Niche high-performance segment requiring specialized 115/145 grade availability at event locations.
Flight Schools command the largest contract volumes; Agricultural Aviation generates the highest per-gallon margins.
Application:
Performance requirements and operating environment severity determine fuel specification selection and delivery infrastructure needs across use cases.
- Training:Repetitive takeoff-landing cycles in high-temperature conditions demand consistent octane performance. Arizona and Florida operations consume disproportionate volume relative to flight hours due to density altitude challenges.
- Crop Dusting:Low-altitude high-power operation with frequent power changes stresses engine detonation margins. Midwest operators require guaranteed supply during compressed seasonal windows when planting schedules dictate daily availability.
- Recreational Flying:Weekend and vacation patterns with flexible scheduling and lower annual hour accumulation.
- Aerobatics:Inverted flight fuel system requirements and high-G maneuver loads impose specialized additive package needs.
- Aerial Surveying:Extended low-power cruise configurations with intermittent high-power climbs for repositioning.
Training applications dominate gallon throughput; Crop Dusting sustains the steepest premium pricing tiers.
Distribution Channel:
Asset ownership models and customer proximity requirements create distinct competitive moats across supply chain configurations.
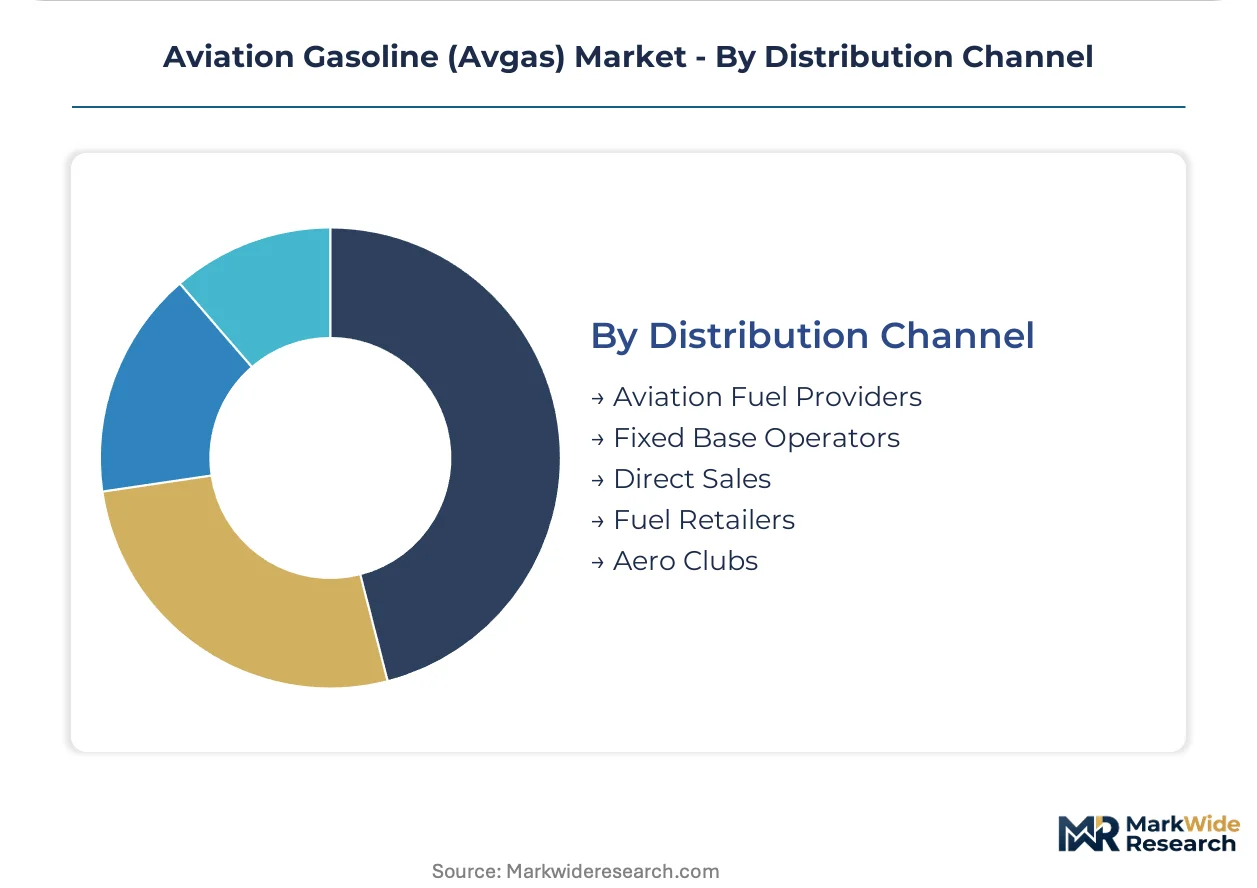
- Fixed Base Operators:Integrated service providers combining fuel sales with hangar, maintenance, and ground support at general aviation airports. Western United States FBO chains leverage Chevron-branded networks for geographic coverage advantages.
- Aviation Fuel Providers:Refiner-affiliated distributors managing terminal-to-wing logistics. Shell's integrated refining footprint enables hub airport volume leadership through dedicated aviation fuel laboratories.
- Direct Sales:Large fleet operators contracting directly with regional terminals, bypassing FBO markups through cooperative procurement structures.
- Fuel Retailers:Multi-product petroleum marketers with aviation as secondary line, common in rural agricultural regions.
- Aero Clubs:Member-owned cooperatives with limited storage capacity and high price sensitivity.
Fixed Base Operators control the majority of physical touchpoints; Direct Sales channels are gaining share fastest among consolidated training fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors North American general aviation manufacturing and fuel demand, with its dense cluster of airframe OEMs and flight training operations driving disproportionate Avgas consumption relative to population. The global market fragments across distinct regulatory timelines and fleet compositions, with each major aviation jurisdiction pursuing different lead-phase-out trajectories.
United States
Flight schools in Florida, Texas, and Arizona operate the world's densest concentration of piston training aircraft, generating sustained high-volume demand. The FAA's Piston Aviation Fuels Initiative coordinates federal certification pathways for unleaded alternatives. California's Air Resources Board mandates lead emissions reductions at municipal airports ahead of federal timelines, pressuring FBOs in Los Angeles and San Francisco basins to install dual-fuel infrastructure.
Canada
Bush aviation operations in Ontario and British Columbia require reliable high-octane supply to remote strips with limited storage capacity. Transport Canada aligns with FAA certification timelines while maintaining distinct environmental assessment protocols. Prairie agricultural aviation clusters around Saskatoon and Regina sustain seasonal surge demand for crop dusting applications.
Germany
Recreational flying clubs across Bavaria and Baden-Württemberg operate aging piston fleets with limited unleaded conversion options. The European Union's REACH regulation constrains tetraethyl lead additive availability, accelerating refinery transitions. Frankfurt and Munich FBO networks serve as distribution hubs for Central European general aviation fuel supply.
Brazil
Agricultural aviation in Mato Grosso and Goiás dominates national Avgas consumption, with crop dusting operations requiring guaranteed seasonal supply to unimproved airstrips. ANP, the national petroleum regulator, maintains import-dependent supply chains given limited domestic refining capacity. São Paulo state flight training academies represent the fastest-growing demand segment outside agricultural applications.
Australia
Remote station aviation in Queensland and Northern Territory sustains premium pricing tiers due to logistics complexity and limited infrastructure. The Civil Aviation Safety Authority defers to ASTM specifications while monitoring EPA lead findings for regulatory alignment. Sydney and Melbourne metropolitan training operations concentrate demand in coastal population corridors.
Aviation Gasoline (Avgas) Market Key Industry Players
Premium-margin players sit above commodity-margin players across refinery integration and additive formulation capabilities. The market consolidates around integrated oil majors with dedicated aviation fuel laboratories and long-term FBO contracts, while independent refiners struggle with conversion economics. Three archetypes dominate: vertically integrated majors controlling terminal-to-wing supply chains, regional distributors specializing in remote logistics, and cooperative procurement organizations aggregating flight school demand. Competitive moves concentrate on dual-fuel infrastructure pre-positioning and ASTM certification lobbying.
Within the integrated major tier, Shell, ExxonMobil, and Chevron Corporation anchor competitive positioning through distinct strategic emphases. Shell leverages its global refining footprint and hub airport presence. ExxonMobil emphasizes proprietary additive packages and supply contract duration. Chevron Corporation concentrates geographic coverage across western United States FBO networks. These three exemplify how scale and integration separate sustainable participants from margin-challenged independents facing refinery conversion costs exceeding viable returns.
| Leading Market Players |
|---|
| TotalEnergies |
| Chevron Corporation |
| ExxonMobil |
| Indian Oil Corporation Limited |
| Repsol |
| Shell |
| Phillips 66 |
| Vitol Group |
| BP Plc |
| Others |
Cost & Logistics Intelligence
California's Air Resources Board lead emissions mandate gates qualified supply for premium-tier Avgas formulations, restricting refinery participation to facilities with dedicated aviation fuel laboratories and dual-fuel production capability. This environmental compliance threshold concentrates pricing power among integrated majors while excluding independent refiners from California-blend premiums.
Pricing Analysis
Engine uptime reliability anchors value-based pricing for agricultural aviation operators facing compressed seasonal windows. Pricing stratifies across 100LL certification, 82UL state-compliant grades, and military-specification 115/145 tiers. Cost compression in unleaded formulations is intensifying because alkylation unit retrofits demand capital commitments exceeding viable returns for non-integrated producers. Flight schools operating standardized Cessna and Piper fleets exhibit highest price sensitivity through cooperative procurement structures, while crop dusting operators in the Central Valley demonstrate lowest sensitivity due to remote delivery premiums.
Supply Chain Analysis
Regional distribution centers in Texas, Louisiana, and California coordinate hub-and-spoke patterns for FBO replenishment across the western United States. Tetraethyl lead additive production concentrates in two domestic suppliers, creating single-source vulnerability for remaining 100LL output. The supply chain draws from alkylate feedstock, aromatic compounds, and certified additive packages. Tariff exposure on specialty chemical imports presents structural risk. Distribution runs through refiner-affiliated terminals to branded FBO networks and direct-sales cooperative procurement organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aviation fuel chemist capacity constraints prop pricing premiums by limiting formulation R&D velocity and slowing refinery certification timelines. This bottleneck sustains margin capture for integrated producers with captive technical expertise.
For Market Incumbents: Deploy ASTM certification lobbying to accelerate D910 specification balloting for unleaded alternatives ahead of competitor laboratory investments. Anchor position through long-term supply contracts with fixed base operator chains in Florida and Arizona training corridors. Defend against bio-based aromatic compound substitutes by pre-positioning dual-fuel infrastructure at California municipal airports ahead of state mandate deadlines.
For New Entrants and Emerging Players: Begin with digital fuel management platform development targeting rural agricultural distributors in the Midwest lacking automated inventory systems. White-space concentrates in cloud-based tank gauging with cellular telemetry for unimproved airstrip operations. Target crop dusting cooperatives in the Central Valley through subscription-based replenishment models displacing manual procurement triggers.
For Investors and Strategic Acquirers: FAA fleet-wide unleaded certification acceleration is the leading indicator that refinery conversion economics will shift from marginal to attractive returns. Long-term viability favors integrated majors with backward control over alkylate production and captive aviation fuel laboratories. Acquisition archetype: regional distributors with established FBO relationships in high-growth training markets. Watch state-level airport lead mitigation mandate proliferation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Infrastructure Pre-Positioning | California FBO chains capture first-mover positioning ahead of Air Resources Board compliance deadlines. |
| ASTM D910 Specification Lobbying | Accelerated balloting timelines reduce competitor laboratory certification lead times. |
| Cooperative Procurement Organization Formation | Flight schools in Texas and Florida aggregate volume leverage against individual FBO negotiations. |
| Alkylation Unit Retrofit Investment | High-octane unleaded production capability locks in post-lead transition supply contracts. |
| Digital Fuel Management Platform Deployment | Automated replenishment systems reduce working capital requirements for rural agricultural distributors. |
Research Approach
Independent corroboration across refinery operations executives, fixed base operator procurement leads, and agricultural aviation fleet managers underwrites the qualitative findings in this study. Primary interviews with aviation fuel chemists, cooperative procurement organization administrators, and EPA regulatory affairs specialists combined with secondary validation from FAA certification filings, EPA Clean Air Act enforcement databases, and ASTM International balloting records. Bottom-up volume modeling across product grades and top-down macroeconomic triangulation anchored the analytical framework.
Comparable-period anchoring to historical Avgas consumption patterns across the projection horizon informed growth trajectory calibration. Segmentation dimensions modeled include octane rating tier, end-user operational scale, application intensity, and distribution channel ownership structure. CAGRs derived from refinery capacity utilization trends, flight school fleet expansion orders, and state-level environmental mandate adoption curves. Forecast inputs incorporated tetraethyl lead supply concentration risk and unleaded engine certification velocity.
Underlying measurement precision varies by segment; flight school volume aggregates carry tighter precision than fragmented private pilot retail purchases. Forecasts reflect documented assumptions regarding FAA certification timelines and refinery conversion capital deployment. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market