
 Soft Wall Military Shelter Market | 2026-2036
Soft Wall Military Shelter Market Size, Share, and Industry Trends Forecast 2026-2036
Soft Wall Military Shelter Market Intelligence
A transition from single-source contracts to multi-source procurement frameworks for expeditionary equipment is shifting the competitive landscape. HDT Global specializes in integrated systems for command and control, while General Dynamics leverages its vast defense contracting network. Concurrently, European providers like Röder HTS Höcker GmbH differentiate through highly modular and rapidly deployable shelter systems tailored for NATO requirements.
Soft wall military shelters are rapidly deployable, non-rigid structures constructed from high-performance, weather-resistant textiles mounted on collapsible frames. These systems are engineered to provide temporary, mobile housing and operational space for military forces in forward-deployed settings. Within product types, air-inflated shelters are gaining share due to their minimal logistical footprint. For applications, demand for integrated medical facilities and command centers commands a premium over basic living quarters.
Procurement specifications are heavily influenced by national and alliance-level standards. In the United States, the Berry Amendment mandates domestic sourcing for textiles, while NATO Standardization Agreements (STANAGs) ensure interoperability among allied forces. These regulations directly shape material selection and supply chain structures for manufacturers. The key decision for suppliers now revolves around balancing cost-competitiveness with adherence to increasingly stringent ballistic protection and climate control requirements.
Market Dynamics
The central tension is the dual demand for alliance-wide interoperability and national sourcing mandates. NATO Standardization Agreements push for common platforms, while regulations like the US Berry Amendment restrict textile supply chains, shaping procurement.
Growth Catalysts
- Defense Modernization:National defense budget increases in countries like Germany and the United Kingdom are accelerating the replacement of legacy shelter systems for expeditionary forces.
- Field Hospital Demand:Requirements for rapidly deployable medical facilities with integrated climate control create a premium segment for military and disaster relief operations.
- Advanced Fabric Technology:Lighter, durable textiles with multi-spectral camouflage enhance shelter survivability and reduce logistical footprints for forward-deployed units.
Market Restraints
- High Input Material Costs:The price of specialized ballistic and fire-retardant textiles, sourced from limited certified suppliers, creates significant cost pressure on manufacturers.
- Stringent Certification Hurdles:Meeting multiple standards like US MIL-SPEC and NATO STANAGs extends product development timelines and increases testing costs for suppliers.
- Supply Chain Bottlenecks:Critical components, including specialized frame extrusions and high-performance textiles, are concentrated in a few suppliers, creating vulnerability.
Strategic Opportunities
- Integrated Energy Solutions:Incorporating flexible solar panels and energy storage into shelter fabrics offers an opportunity to reduce reliance on fossil-fuel generators in the field.
- Unmanned Systems Support:Developing specialized shelters for maintaining and operating unmanned aerial and ground systems represents a new, high-value application.
- Eastern European Modernization:Defense forces in Poland and Romania are seeking NATO-interoperable equipment, creating opportunities for suppliers that meet STANAGs.
Industry Challenges
- Legacy System Integration:Ensuring new shelter systems are compatible with existing military power grids, communication networks, and HVAC equipment presents a significant technical and logistical challenge.
- Complex Sourcing Compliance:Navigating domestic content requirements like the Berry Amendment while managing a global supply chain for other components complicates manufacturing and procurement for suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soft Wall Military Shelter Market |
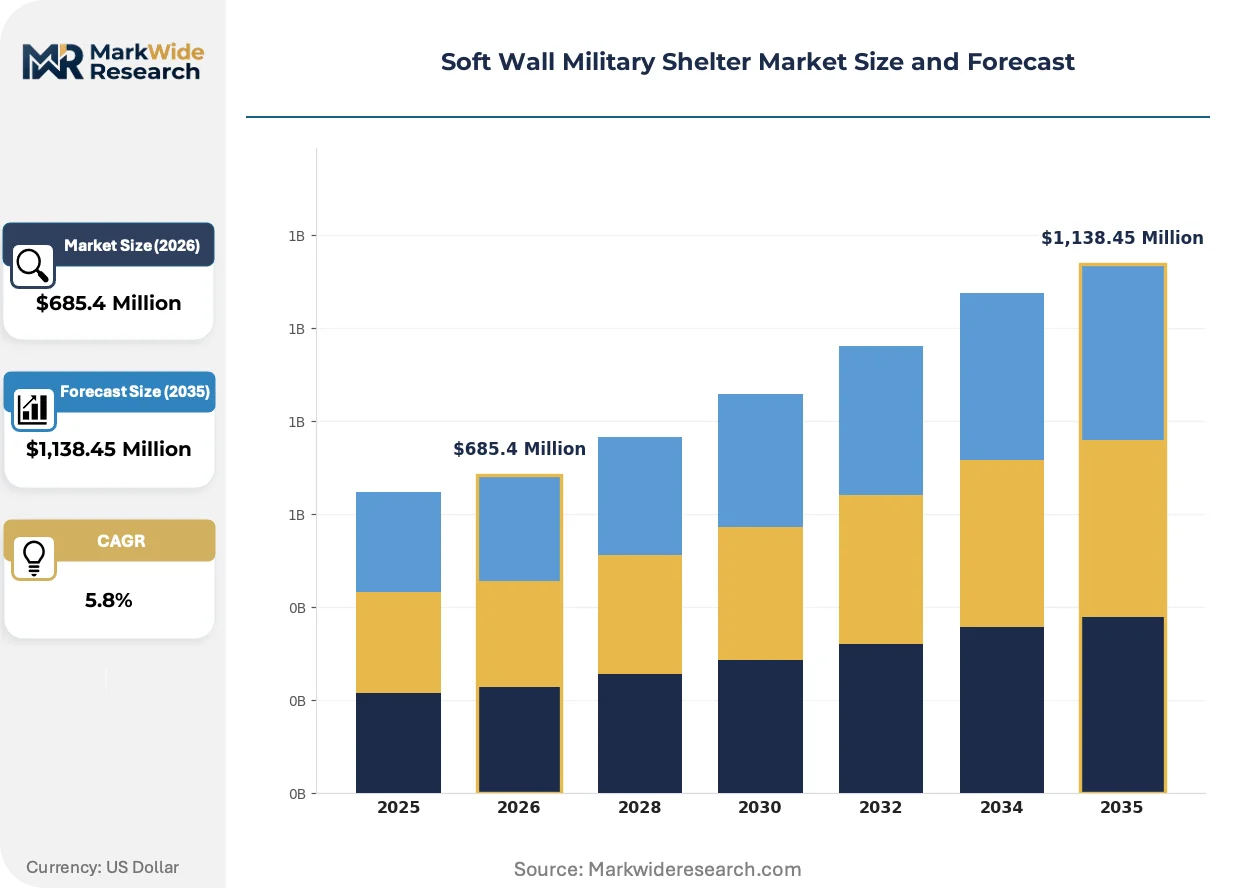
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expandable Shelters, Rapid Deployment Shelters, Insulated Shelters, Air-Inflated Shelters Technology: Ballistic Fabric, Water-Resistant Coatings, Temperature Control Systems, Modular Designs End User: Military Personnel, Disaster Relief Organizations, Humanitarian Agencies, Government Defense Contractors Application: Command Centers, Medical Facilities, Living Quarters, Training Areas |
| Companies Covered | HDT Global, Alaska Structures, Röder HTS Höcker GmbH, General Dynamics, Weatherhaven, Big Top Manufacturing, Gillard SAS, AAR Corp, Outdoor Venture Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soft Wall Military Shelter Market Strategic Shifts & Innovations
The convergence of advanced material science with embedded digital systems defines the next generation of soft wall shelters. This evolution prioritizes operational intelligence and reduced logistical demands for expeditionary forces, not just structural integrity.
Smart textiles with embedded sensors provide real-time monitoring of structural integrity, internal climate, and external threats. Special operations forces and medical units are primary adopters. This technology is integrating environmental and structural data into command networks, enhancing situational awareness and preventative maintenance.
NATO Standardization Agreements focused on energy efficiency are influencing shelter design across member nations. These standards compel manufacturers to develop systems with improved insulation and reduced thermal signatures to lower fuel consumption. Command post and medical facility segments are most affected, driving investment in compliant climate control solutions.
A demand-side shift involves moving from buying individual components to acquiring complete, integrated camp systems from a single provider. This disrupts procuring shelters, generators, and environmental control units separately. This model is most visible in large US Department of Defense and German Bundeswehr tenders for expeditionary infrastructure.
Soft Wall Military Shelter Market Segmentation
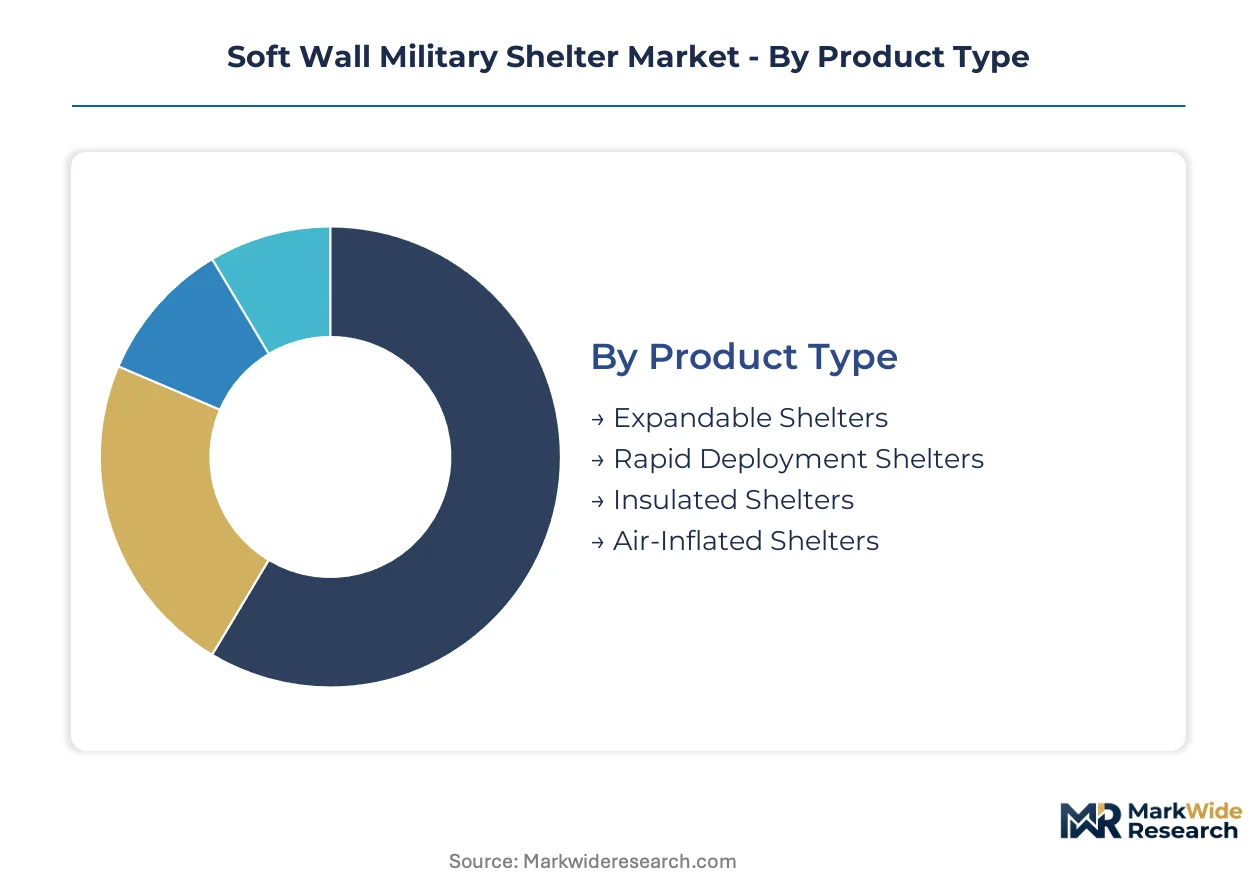
The soft wall military shelter market segments reflect diverse operational needs and technological advancements, influencing procurement decisions across defense and humanitarian sectors. Understanding these segments helps manufacturers align product development with specific end-user demands and strategic priorities.
Product Type:
Buyers prioritize shelter characteristics based on mission requirements and deployment speed for temporary structures.
- Air-Inflated Shelters:These structures utilize high-pressure air to maintain their form, offering minimal logistical footprint and rapid deployment. Demand concentrates within special operations forces and rapid response units seeking quick setup in austere environments.
- Expandable Shelters:These systems feature modular components that extend or fold out from a compact transport configuration, providing increased interior space upon deployment. Military forces in the United States and Germany favor these for command posts requiring scalable operational areas.
- Rapid Deployment Shelters:These shelters focus on quick assembly and disassembly, typically using lightweight, interlocking frame systems and pre-attached fabric covers. Disaster relief organizations and humanitarian agencies utilize these for immediate emergency response.
- Insulated Shelters:These designs incorporate advanced thermal barriers within their fabric walls, maintaining stable internal temperatures in extreme hot or cold climates. Expeditionary forces in diverse global theaters require these for personnel comfort and equipment protection.
Volume sits with Rapid Deployment Shelters; growth tilts toward Air-Inflated Shelters.
Technology:
The supply chain for soft wall military shelters concentrates around specific technological capabilities, impacting material sourcing and product differentiation.
- Ballistic Fabric:These advanced textile composites incorporate materials like aramid fibers or high-density polyethylene, providing protection against small arms fire and fragmentation. Procurement in the United States and the United Kingdom drives demand for enhanced force protection.
- Modular Designs:These systems feature interchangeable components and standardized interfaces, allowing for flexible configuration and easy expansion or integration with other units. NATO forces, particularly in Germany, seek modularity for interoperability and rapid re-tasking.
- Water-Resistant Coatings:Specialized polymer or silicone-based treatments are applied to shelter fabrics, creating a hydrophobic barrier against rain, snow, and humidity. Military units in high-precipitation regions, such as those in Northern Europe, require superior weatherproofing.
- Temperature Control Systems:Integrated heating, ventilation, and air conditioning (HVAC) units or passive insulation designs manage internal climate, crucial for personnel comfort and sensitive equipment. Medical facilities and command centers demand precise environmental regulation.
Ballistic Fabric solutions currently hold the largest share; Modular Designs are expanding most quickly.
End User:
Customer type dictates procurement scale and specialized requirements for soft wall military shelters.
- Military Personnel:This segment includes all branches of armed forces, requiring shelters for a wide range of applications from forward operating bases to temporary barracks. Defense modernization initiatives in countries like Germany and the United Kingdom drive significant procurement volume.
- Disaster Relief Organizations:These groups deploy shelters for emergency housing, medical aid stations, and logistical hubs in humanitarian crises. Rapid deployability and ease of transport are critical factors for these non-governmental entities.
- Humanitarian Agencies:International and national aid organizations use soft wall shelters for refugee camps, mobile clinics, and temporary schools in conflict zones and disaster-affected areas. Durability and long-term sustainability are key considerations for these users.
- Government Defense Contractors:These entities procure shelters as part of larger contracts for integrated base camps, logistical support, or specialized mission equipment for military clients. Project-based tenders often specify unique design and integration requirements.
Military Personnel constitute the largest user base; Humanitarian Agencies show the steepest expansion trajectory.
Application:
The specific intended use drives the integration of features and environmental controls within soft wall shelters.
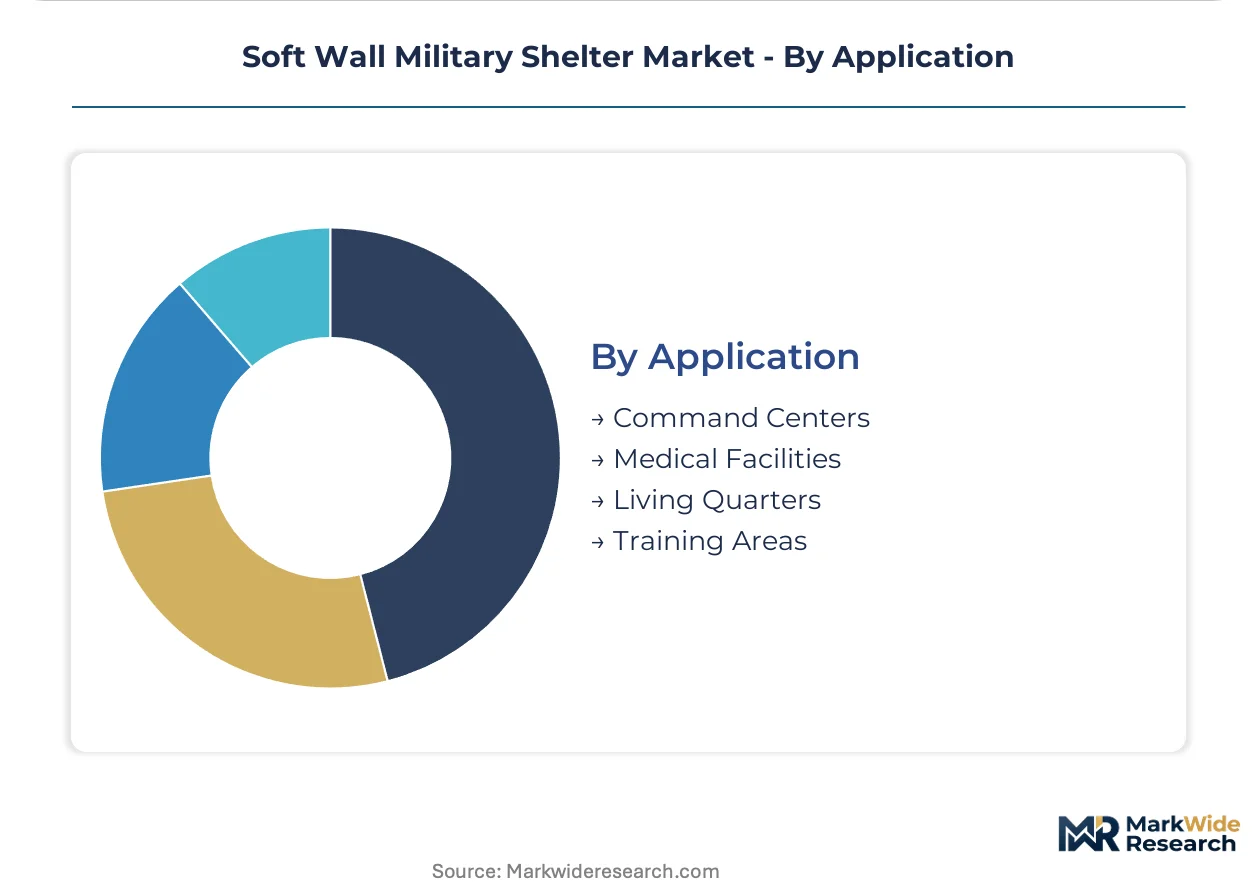
- Command Centers:These applications require robust communication integration, secure environments, and sophisticated climate control for sensitive electronic equipment and personnel. The United States Department of Defense frequently procures these for expeditionary operations.
- Medical Facilities:Soft wall shelters configured as field hospitals, aid stations, or quarantine units demand stringent environmental controls, sterile interior finishes, and reliable power for medical devices. Demand for these integrated solutions commands a premium.
- Living Quarters:These shelters provide basic housing for military personnel or displaced populations, emphasizing comfort, weather protection, and ease of setup. Large-scale procurement often focuses on cost-effectiveness and durability for extended deployments.
- Training Areas:Shelters used in training scenarios offer temporary cover, simulated operational environments, or administrative space for exercises. These applications prioritize durability and reusability over highly specialized features.
Living Quarters represent the highest volume application; Medical Facilities are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized textile production, particularly for high-performance fabrics, anchors procurement across major defense markets. These advanced materials are critical for the next generation of soft wall military shelters. Key nations are investing heavily in domestic capabilities and alliance-level interoperability.
United States
The United States drives substantial demand for advanced soft wall shelters, particularly for integrated command centers and medical facilities. The Berry Amendment mandates domestic sourcing for textiles, influencing supply chain structures. Major defense contractors in the Washington D.C. metropolitan area and Virginia frequently engage in large-scale procurement for expeditionary forces.
Germany
German defense modernization initiatives accelerate the replacement of legacy shelter systems, emphasizing modular designs and NATO interoperability. The Bundeswehr's procurement standards, aligned with NATO Standardization Agreements, shape material and design specifications. Industrial clusters in Bavaria and North Rhine-Westphalia house manufacturers specializing in advanced military infrastructure.
United Kingdom
United Kingdom procurement focuses on enhanced force protection and rapidly deployable systems for expeditionary operations. Increased defense budgets support the acquisition of shelters with advanced ballistic fabric technology. Defense technology hubs in the South East of England contribute to innovation in shelter design and material science.
Poland
Poland's defense forces are actively seeking NATO-interoperable equipment, including soft wall shelters that meet STANAG requirements for rapid deployment. The country's ongoing military modernization program drives demand for advanced field infrastructure. Warsaw and its surrounding regions are seeing increased activity in defense sector manufacturing and integration.
Romania
Romanian military investment targets the modernization of its defense capabilities and deeper integration into NATO structures. This creates opportunities for suppliers of soft wall shelters that comply with alliance standards for field hospitals and command posts. Defense procurement activities in Bucharest reflect a focus on interoperable and climate-controlled solutions.
Soft Wall Military Shelter Market Key Industry Players
Global majors compete with regional champions across the spectrum of soft wall military shelter solutions. The market exhibits a tiered structure, with established defense contractors operating alongside specialized textile and frame manufacturers. Strategic archetypes include integrated systems providers and modular design innovators. Companies frequently pursue strategic partnerships and portfolio diversification to enhance their market reach.
Within the integrated systems archetype, HDT Global exemplifies comprehensive command and control solutions. General Dynamics, a large US-based defense contractor, occupies a position leveraging its vast contracting network for military hardware. Röder HTS Höcker GmbH, a German-based entity, represents the modular design innovator segment, specializing in rapidly deployable shelter systems tailored for NATO requirements.
| Leading Market Players |
|---|
| HDT Global |
| Alaska Structures |
| Röder HTS Höcker GmbH |
| General Dynamics |
| Weatherhaven |
| Big Top Manufacturing |
| Gillard SAS |
| AAR Corp |
| Outdoor Venture Corporation |
Cost & Logistics Intelligence
Specialized textile input costs, particularly for aramid fibers, cascade through the soft wall military shelter supply chain, directly influencing the final pricing tiers for ballistic and insulated products. This cost pressure impacts manufacturers' ability to balance feature integration with budget constraints.
Pricing Analysis
Warranty and service bundling significantly influence the perceived value of soft wall military shelters, with comprehensive after-sales support often integrated into project-based contracts. Pricing stratifies across premium, standard, and economy tiers based on certification levels like NATO STANAGs and customization for integrated systems. Upward pricing pressure stems from the high cost of specialized ballistic fabrics and stringent certification hurdles. Disaster relief organizations exhibit the highest price sensitivity, while military command centers accept premium pricing for advanced features.
Supply Chain Analysis
Ballistic fabric supply rests on a limited number of certified producers, primarily in the United States and specialized European manufacturers. The supply chain sources high-performance textiles and specialized frame extrusions, creating dependencies on a few key component providers. Single-source vulnerability represents a structural risk, compounded by national regulatory restrictions like the US Berry Amendment. Distribution runs through direct sales channels to defense contractors and government agencies, along with specialized integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a supply-constrained narrative, with pricing propped up by limited certified manufacturing capacity for specialized ballistic fabrics. Meeting stringent MIL-SPEC and STANAG requirements creates a bottleneck for new entrants and existing players alike.
For Market Incumbents: Cement relationships with certified raw material suppliers to mitigate rising input material costs and supply chain bottlenecks. Deepen vertical integration into specialized textile production or frame extrusion to control critical component supply. Invest in R&D for advanced material science and smart textile integration to maintain a technological edge. Focus on securing long-term contracts with major defense clients like the US Department of Defense.
For New Entrants and Emerging Players: Capture market share by focusing on Eastern European modernization initiatives, particularly in Poland and Romania, where demand for NATO-interoperable equipment is high. Target the rapidly expanding Humanitarian Agencies segment with cost-effective, rapid deployment shelters. Differentiate through highly modular designs that meet STANAGs and offer integrated energy solutions. A go-to-market angle involves strategic partnerships with local defense integrators.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized textile manufacturers in Europe and modular design innovators in Germany, offering long-term viability driven by defense modernization. The market's structural shift towards integrated camp systems creates opportunities for acquiring firms with strong project management capabilities. Seek out companies with proprietary ballistic fabric technology or robust climate control solutions. A key signal to watch is sustained increases in national defense budget allocations for expeditionary infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Ballistic Fabrics | Addresses critical supply chain bottlenecks and reduces reliance on limited certified suppliers. |
| Strategic Partnership for Integrated Energy Solutions | Enhances shelter functionality and reduces reliance on fossil-fuel generators in the field. |
| Investment in Smart Textile R&D | Develops next-generation shelters with embedded sensors for real-time monitoring and threat detection. |
| NATO STANAG Certification Pursuit | Unlocks access to significant procurement opportunities in Eastern European defense markets. |
| Modular Design Portfolio Expansion | Caters to demand for flexible, rapidly reconfigurable operational spaces for diverse military applications. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. We engaged defense procurement officers, military logistics commands, textile engineers, and humanitarian aid coordinators for nuanced insights. This approach combined top-down market sizing with bottom-up validation. Secondary research involved defense budget reports, NATO Standardization Agreements, and military modernization program documents.
Market granularity was modeled across product type, technology, end-user, application, and regional defense spending, providing a comprehensive view across the analysis window. Our quantitative framework derived Compound Annual Growth Rates (CAGRs) from historical trends, projected market drivers, and expert consensus. Key forecast inputs included national defense modernization budgets and the adoption rates of advanced smart textiles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical instability and shifts in defense procurement policies. These forecasts reflect a set of carefully documented assumptions regarding technological advancements and market dynamics. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Equipment and Infrastructure
Rubber Tracks for Defense and Security Market
Military Equipment and Infrastructure
Air Independent Propulsion Systems for Submarine Market
Military Equipment and Infrastructure
Naval Vessel Maintenance, Repair, and Overhaul (MRO) Market
Military Equipment and Infrastructure
Turret Handlers Market
Military Equipment and Infrastructure
Man Portable Military Electronics Market
Military Equipment and Infrastructure
Global Landing String Equipment Market
Military Equipment and Infrastructure
Deployable Military Shelter Systems Market
Military Equipment and Infrastructure
Military Image Intensifier Tube Market
Military Equipment and Infrastructure
Defense Logistics Market
Military Equipment and Infrastructure
CBRNE Defense Market
Military Equipment and Infrastructure
Military Displays Market
Military Equipment and Infrastructure
NATO Military Aircraft Modernization and Retrofit Market
Military Equipment and Infrastructure
FLIR and Laser Designator Targeting Pods Market
Military Equipment and Infrastructure
Military Infrastructure and Logistics Market
Military Equipment and Infrastructure
Defense Ground Support Equipment Market
Military Equipment and Infrastructure
Global Remote Weapon Station Market