
 Aircraft Refueler Market | 2026-2036
Aircraft Refueler Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Refueler Market Analytics
A shift from single-source procurement to multi-source qualification is pivoting how fleet operators manage refueler supply chains. Garsite leverages in-house fabrication capabilities to control lead times on custom tank configurations. Westmor competes through regional service density across the central United States. STOKOTA anchors European demand with hydrant system integration expertise.
An aircraft refueler is a specialized ground support vehicle or fixed installation designed to transfer aviation fuel from storage to aircraft, incorporating filtration systems rated to remove particulates below specified thresholds and static grounding interlocks to prevent ignition hazards. Mobile refuelers dominate fleet procurement for airports with dispersed gate layouts or seasonal traffic swings, while hydrant dispensers command higher capital investment but yield lower per-gallon operating costs at hub terminals. Electric drive technology for refueler chassis is gaining specification traction among fixed base operators seeking to align with airport carbon reduction commitments.
The FAA mandates fueling equipment compliance with NFPA 407 and DOT hazardous materials standards, while EASA enforces equivalent hydrant system certification under CS-ADR-DSN provisions. China's CAAC implements GB 36220 for aviation ground fueling equipment, creating a three-jurisdiction compliance burden for multinational suppliers. Stakeholders must monitor evolving airport electrification mandates and SAF compatibility requirements as these will determine next-generation refueler design priorities.
Market Dynamics
Airport electrification mandates and sustainable aviation fuel compatibility requirements are forcing simultaneous chassis redesign and filtration system upgrades, compressing product development cycles while expanding certification burdens for equipment suppliers.
Growth Catalysts
- Commercial apron expansion:United States and Chinese airports are adding gates at hub terminals, requiring hydrant dispenser installations and mobile refueler fleet augmentation to service expanded aircraft parking positions.
- FAA NFPA 407 enforcement:Updated fueling safety standards mandate static grounding interlock upgrades and filtration threshold improvements, compelling fleet replacement cycles among fixed base operators.
- Electric chassis development:Battery-electric drive trains for refueler vehicles are gaining specification traction as airports commit to carbon reduction timelines and ground support equipment electrification.
Market Restraints
- Specialized steel and aluminum input costs:Custom tank fabrication relies on aviation-grade stainless steel and aluminum alloys subject to commodity price volatility, compressing margin visibility for fabricators.
- Three-jurisdiction compliance burden:Multinational suppliers must simultaneously satisfy FAA NFPA 407, EASA CS-ADR-DSN hydrant provisions, and China CAAC GB 36220 standards, multiplying certification costs.
- Hydrant system capital intensity:Underground fueling infrastructure requires substantial upfront investment versus mobile refuelers, limiting adoption to hub terminals with traffic density justification.
Strategic Opportunities
- India airport privatization wave:Greenfield airport development under the country's regional connectivity scheme creates first-mover positioning for hydrant system integrators and mobile refueler suppliers.
- SAF material compatibility:Sustainable aviation fuel blends with distinct chemical properties require filtration media and seal material upgrades, opening retrofit and new-build specification windows.
- Autonomous refueling interfaces:Integration of automated fueling arms with aircraft receptacle positioning systems converges robotics with fueling control electronics, enabling labor reduction at high-turnover gates.
Industry Challenges
- Cross-functional engineering talent scarcity:Simultaneous expertise in pressure vessel design, hazardous materials handling, and electric powertrain integration resides in limited supplier engineering teams.
- Legacy hydrant infrastructure interoperability:New dispenser installations must interface with decades-old underground piping and valve systems, complicating commissioning and acceptance testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Refueler Market |
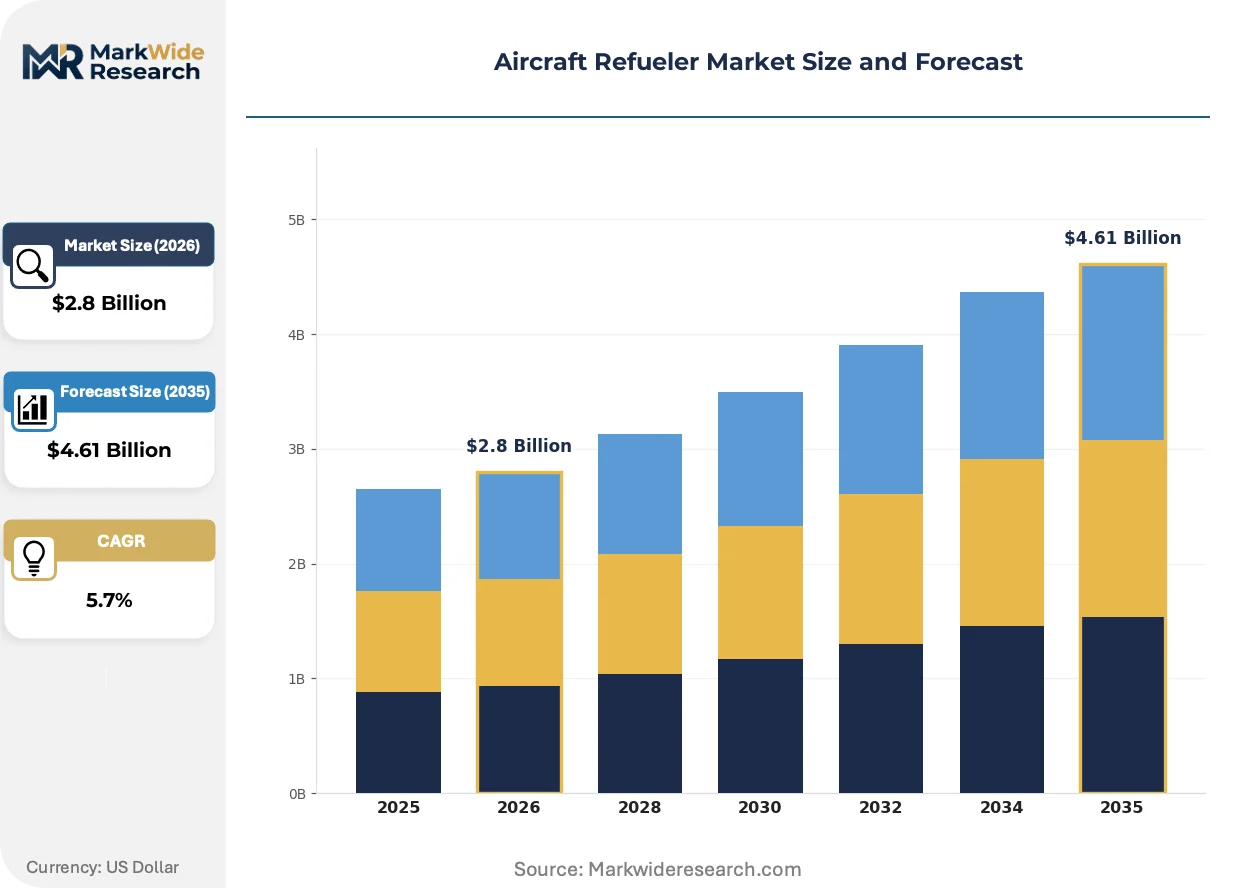
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Refuelers, Fixed Refuelers, Hydrant Dispensers, Fuel Trucks Technology: Electric, Hydraulic, Pneumatic, Manual End User: Military Bases, Commercial Airports, General Aviation, Fixed Base Operators Application: Aviation Fueling, Jet Fuel Supply, Emergency Services, On-Site Refueling |
| Companies Covered | Garsite, SkyMark, Westmor, Tremcar Inc., BETA Fueling, Bosserman, STOKOTA, IPWT, Showa Aircraft Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Refueler Market Evolving Landscape
Refueler design priorities are pivoting toward dual-certification architectures that accommodate both conventional jet fuel and emerging sustainable aviation fuel chemistries without hardware replacement.
Electric powertrain technology for refueler chassis is absorbing development resources across major ground support equipment portfolios. Fixed base operators at California and New York airports are specifying battery-electric units to satisfy state-level zero-emission ground equipment mandates. This shift is absorbing engineering bandwidth that previously focused on diesel efficiency improvements, compressing time-to-market for conventional product lines.
China's GB 36220 standard for aviation ground fueling equipment is tightening filtration and safety interlock requirements beyond legacy specifications. Domestic suppliers must recertify existing product lines, while multinational entrants face extended type-approval timelines. European manufacturers with established hydrant system expertise are responding by partnering with local fabrication facilities to accelerate market access.
Service contract unbundling is fragmenting traditional refueler procurement relationships. Airport authorities and fixed base operators are separating equipment purchase from aftermarket maintenance, creating standalone service revenue pools. This pattern is most visible in Germany, where municipal airport operators now tender multi-year maintenance agreements independent of original equipment supply.
Aircraft Refueler Market Segmentation
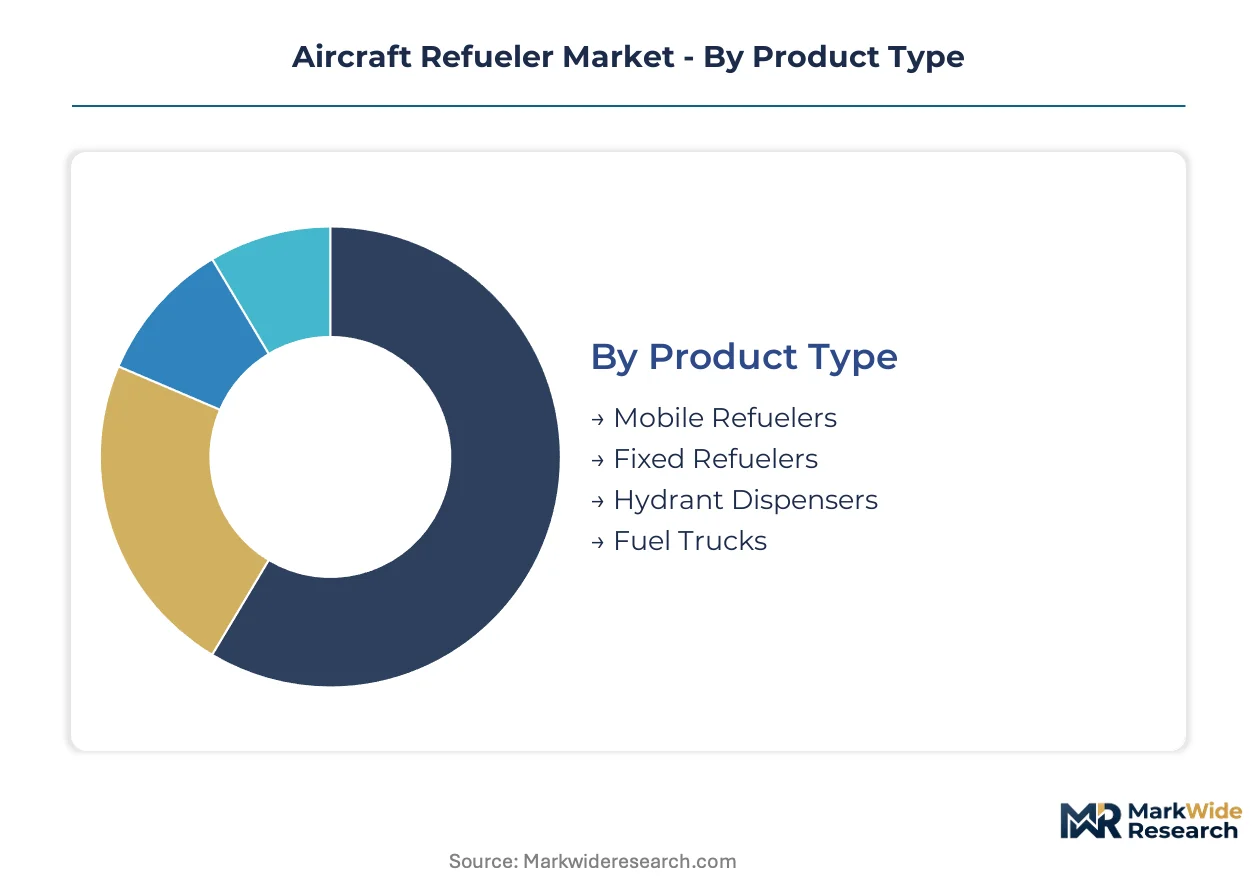
Refueler procurement decisions hinge on traffic density, gate configuration, and regulatory jurisdiction. Fleet operators weigh capital intensity against operating cost per gallon delivered. Technology selection increasingly reflects airport electrification mandates and SAF compatibility requirements.
Product Type:
Capital deployment and operational flexibility drive buyer selection across product categories.
- Mobile Refuelers:Self-contained tank vehicles with integrated pumping and filtration systems enable fuel delivery to dispersed aircraft positions without fixed infrastructure. Demand concentrates at regional airports and military installations across the United States and Germany where gate layouts preclude hydrant economics. Seasonal traffic swings and temporary apron expansions sustain procurement cycles for this category.
- Hydrant Dispensers:Underground pipeline-connected units reduce per-gallon operating costs through elimination of tank transport, though they require substantial upfront civil works and traffic density justification. Hub terminals in China and the United States—Beijing Capital, Shanghai Pudong, Dallas-Fort Worth, Atlanta—anchor installations as these airports expand apron infrastructure to accommodate fleet growth.
- Fixed Refuelers:Stationary above-ground or pit-mounted installations serve dedicated parking positions with direct aircraft connection capability.
- Fuel Trucks:Smaller-capacity vehicles address rapid turnaround requirements and narrow-body aircraft servicing at high-frequency gates.
Mobile Refuelers lead on scale; Hydrant Dispensers lead on momentum as hub terminals expand.
Technology:
Regulatory pressure on ground support equipment emissions is restructuring technology procurement priorities.
- Electric:Battery-electric powertrains eliminate tailpipe emissions and align with airport carbon reduction commitments, particularly at California and New York facilities subject to state-level zero-emission mandates. Range limitations and charging infrastructure requirements constrain deployment to shorter-duty cycles and centralized base operations.
- Hydraulic:Conventional diesel-hydraulic systems retain specification dominance where electrification infrastructure remains undeveloped and where extended range or high-duty cycles exceed current battery capabilities.
- Pneumatic:Compressed-air actuation systems serve specialized military applications requiring explosion-proof operation in hazardous environments.
- Manual:Hand-operated pumping and valve systems persist in legacy installations and low-volume general aviation settings where capital constraints outweigh labor cost considerations.
Hydraulic systems retain installed base dominance; Electric configurations are expanding most quickly under regulatory pressure.
End User:
Procurement scale and specification complexity vary sharply across user categories.
- Commercial Airports:Hub and regional terminals in the United States and China drive fleet-scale procurement with multi-unit tenders and extended service contracts. These operators specify integrated hydrant systems and mobile refueler fleets simultaneously, demanding compliance with FAA NFPA 407 or CAAC GB 36220 standards.
- Military Bases:Defense installations require hardened equipment with electromagnetic compatibility, rapid deployment capability, and interoperability with diverse aircraft types including tankers and cargo platforms.
- Fixed Base Operators:FBOs at general aviation airports purchase smaller mobile units with emphasis on rapid turnaround and customer service differentiation.
- General Aviation:Private airfields and flying clubs acquire minimal-capacity equipment with manual or simplified control systems.
Commercial Airports concentrate procurement volume; Military Bases sustain premium specification demand.
Application:
Operational mission defines filtration requirements, flow rates, and safety system configurations.
- Aviation Fueling:Standard commercial and military aircraft servicing demands particulate filtration below specified thresholds, static grounding interlocks, and flow rates calibrated to aircraft type. This application absorbs the majority of equipment deployment at United States and Chinese hub terminals.
- Jet Fuel Supply:Bulk transfer operations from storage to distribution points emphasize high-volume pumping capacity and pipeline-compatible pressure specifications.
- Emergency Services:Rapid response configurations prioritize deployment speed and all-terrain mobility for disaster relief and contingency operations.
- On-Site Refueling:Temporary or remote location servicing requires self-sufficient tank capacity and independence from fixed infrastructure.
Aviation Fueling dominates equipment deployment; Emergency Services commands specialized premium configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting fabrication capacity toward jurisdictions with streamlined certification pathways, as the three-jurisdiction compliance burden for FAA, EASA, and CAAC standards creates cost-of-compliance gaps that suppliers exploit through strategic facility placement.
United States
Commercial apron expansion at Dallas-Fort Worth and Atlanta hubs is driving hydrant dispenser procurement alongside mobile refueler fleet augmentation. FAA enforcement of updated NFPA 407 standards is compelling static grounding interlock upgrades among fixed base operators. Kansas-based fabrication clusters supply regional airport operators across the central corridor with customized tank configurations.
China
Beijing Capital and Shanghai Pudong terminals are expanding gate infrastructure to accommodate fleet growth, requiring integrated hydrant systems. CAAC implementation of GB 36220 standards is tightening filtration and safety interlock requirements beyond legacy specifications. Domestic suppliers in the Yangtze River Delta are recertifying product lines to meet the new national standards.
Germany
Municipal airport operators are unbundling equipment procurement from aftermarket maintenance, creating standalone service revenue pools. EASA hydrant system certification under CS-ADR-DSN provisions governs dispenser installations at Frankfurt and Munich hubs. Industrial concentration in North Rhine-Westphalia anchors European demand for hydrant system integration expertise.
India
Greenfield airport development under the regional connectivity scheme is creating first-mover positioning opportunities for equipment suppliers. The country's national aviation regulator is aligning ground support equipment standards with international norms to facilitate fleet modernization. Hyderabad and Bangalore clusters are emerging as procurement centers for southern region airport expansions.
Japan
Fixed base operators at Narita and Haneda are evaluating electric chassis specifications to align with airport carbon reduction commitments. METI guidelines on ground support equipment electrification are shaping procurement priorities among domestic carriers. Showa Aircraft Industry exemplifies specialized manufacturing concentration in the Chubu industrial corridor.
Aircraft Refueler Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue electric powertrain specialization and SAF compatibility certification. The supplier base exhibits moderate concentration with distinct capability clusters around pressure vessel fabrication, hydrant system integration, and regional service density. Three archetypes dominate: vertically integrated fabricators controlling custom tank production, hydrant specialists with civil works integration expertise, and regional service networks competing on proximity. Competitive moves center on backward integration into aviation-grade steel sourcing and strategic partnerships with local fabrication facilities to accelerate market access in high-barrier jurisdictions.
Among North American fabricators, Garsite and Westmor exemplify divergent strategic positions. Garsite represents the vertically integrated archetype with in-house fabrication capabilities, while Westmor anchors regional service density across the central United States. STOKOTA occupies a distinct position among European specialists, with hydrant system integration expertise concentrated in the Benelux region. Showa Aircraft Industry Co., Ltd. exemplifies Japanese precision manufacturing specialization in ground support equipment.
| Leading Market Players |
|---|
| Garsite |
| SkyMark |
| Westmor |
| Tremcar Inc. |
| BETA Fueling |
| Bosserman |
| STOKOTA |
| IPWT |
| Showa Aircraft Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Electric chassis development for refueler vehicles is compressing product development cycles while simultaneously concentrating procurement leverage among airports with carbon reduction mandates. This dual pressure on engineering bandwidth and buyer concentration is reshaping cost economics across fabrication tiers.
Pricing Analysis
Distributor margins on mobile refuelers typically range wider than direct-to-airport hydrant dispenser contracts. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified units with advanced filtration from basic configurations and legacy refurbished fleets. Price differentiation centers on certification grade and after-sales service bundling, with municipal airport operators in Germany exhibiting highest price sensitivity due to unbundled procurement practices. Cost compression in standard-tier mobile refuelers is intensifying because commodity volatility in aviation-grade stainless steel feeds directly into tank fabrication quotes.
Supply Chain Analysis
Freight costs for oversized pressure vessel components from fabrication clusters in Kansas and the Yangtze River Delta constrain supplier margin flexibility on cross-continental deliveries. Geographic supply concentration rests on the United States, China, and Germany, where specialized steel mills and aluminum alloy producers anchor upstream input availability. Raw material dependencies hinge on aviation-grade stainless steel, aluminum alloys, and advanced filtration media. Single-source vulnerability in electric powertrain components poses structural risk as battery supply concentrates among limited qualified vendors. Distribution runs through regional service networks for mobile refuelers and direct civil works contractors for hydrant installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
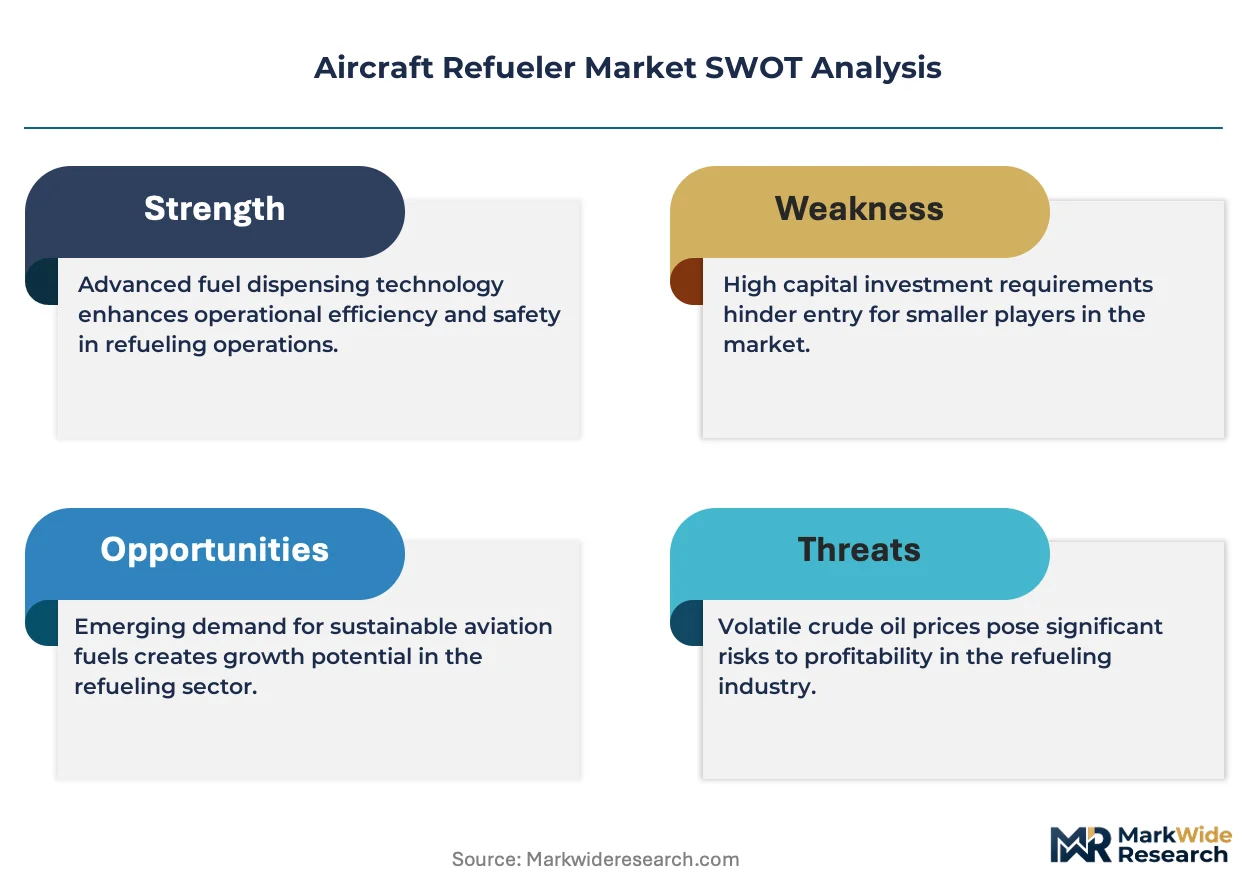
The aircraft refueler market functions as a stable compounder underpinned by regulatory-mandated fleet replacement cycles that sustain predictable procurement velocity regardless of traffic growth fluctuations.
For Market Incumbents: Anticipate margin compression from emerging electric powertrain specialists by deepening backward integration into aviation-grade steel sourcing and accelerating dual-certification architectures for SAF compatibility. Certification investment in China's GB 36220 standards represents the priority defensive lever against domestic supplier recapture. For New Entrants and Emerging Players: Begin with India's greenfield airport privatization wave, where first-mover positioning in hydrant system integration remains penetrable before incumbent service density solidifies. Target fixed base operators at California and New York airports with battery-electric chassis specifications as the most accessible specification entry point under state-level zero-emission mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service networks competing on proximity rather than vertical fabrication control. Long-term viability across the analysis window favors suppliers with captive hydrant civil works expertise and electric chassis development bandwidth. Watch SAF blend ratio mandates as the signal indicating inflection toward filtration media retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Architecture Development | Enables simultaneous jet fuel and SAF compatibility without hardware replacement at FAA-regulated airports. |
| Backward Integration into Steel Sourcing | Captures margin visibility against commodity volatility in aviation-grade stainless steel input markets. |
| Electric Chassis Platform Investment | Aligns product portfolios with California and New York zero-emission ground equipment mandates. |
| Regional Service Network Expansion | Competes on proximity for unbundled maintenance contracts at German municipal airport operators. |
| Local Fabrication Partnership Formation | Accelerates CAAC GB 36220 type-approval timelines for European hydrant system specialists entering China. |
Research Methodology
Bottom-up commercial airport and military base modeling reconciled against top-down fabrication capacity tracking forms the analytical core of this study. Primary interviews with fleet procurement managers, ground support equipment maintenance directors, airport engineering consultants, and regulatory compliance officers combined with secondary validation against FAA enforcement records, CAAC type-approval databases, EASA CS-ADR-DSN certification logs, and customs trade data on aviation-grade steel imports. Triangulation between demand-side procurement patterns and supply-side production cluster activity anchored volume estimates.
Historical trendline analysis of refueler fleet deployments across the analysis window established baseline growth parameters for projection modeling. Segmentation dimensions include product type, powertrain technology, end-user category, and regional regulatory jurisdiction. CAGRs derived from curve-fitting procedures applied to documented procurement cycles at named hub terminals. Industry-specific forecast inputs encompass apron expansion timelines at Dallas-Fort Worth and Shanghai Pudong, plus electric chassis specification adoption rates at California fixed base operators.
Several conditions sit outside the modeled scope, including military contingency procurement surges and abrupt SAF blend mandate acceleration. Forecasts reflect documented assumptions regarding certification timeline stability and commodity price band persistence. A model refresh is warranted upon material change in FAA NFPA 407 enforcement intensity or CAAC GB 36220 recertification deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aircraft Fuel System Market
Aircraft Fuel Systems
Refueling Aircraft Market
Aircraft Fuel Systems
Aviation Refueling Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market