
 Middle-East and Africa Aviation Fuel Market | 2026-2036
Middle-East and Africa Aviation Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aviation Fuel Market Foresight
Specialized refinery technician availability is bifurcating the Middle-East and Africa aviation fuel market into Gulf states with trained workforces and sub-Saharan markets facing chronic skills shortages. Emirates National Oil Company leverages its Jebel Ali refinery complex to dominate jet fuel supply across Dubai's aviation hub. Saudi Aramco sustains massive upstream-to-downstream integration that anchors its position as the region's largest producer of aviation-grade kerosene. TotalEnergies SE competes through specialized logistics networks that extend into Francophone African markets where infrastructure gaps persist.
Middle-East and Africa aviation fuel encompasses refined petroleum products meeting strict flash point, freeze point, and energy density specifications for turbine and piston aircraft propulsion, with Jet A-1 representing the dominant kerosene-based formulation requiring -47°C maximum freeze point for high-altitude operations. Jet A-1 commands the largest volume share across the region due to compatibility with commercial turbofan engines operating from Cairo to Cape Town. Commercial Airlines generate the dominant revenue pool among end users, while Cargo Airlines represent the fastest-expanding segment as Ethiopian Airlines and Qatar Airways scale dedicated freighter fleets. Direct Sales channels control premium margin capture at major hubs, though Brokers occupy critical intermediary roles in fragmented East African markets lacking integrated fuel farm infrastructure.
The General Civil Aviation Authority of the United Arab Emirates enforces sulfur content and particulate standards that exceed baseline International Air Transport Association guidelines, forcing suppliers to upgrade hydrotreating capacity. Saudi Arabia's Saudi Standards, Metrology and Quality Organization aligns domestic aviation fuel specifications with ASTM D1655 and DEF STAN 91-91 frameworks to ensure military and civilian interoperability. South Africa's National Regulator for Compulsory Specifications mandates traceability protocols that shape import logistics for non-refining nations. Stakeholders must monitor sustainable aviation fuel certificate trading mechanisms and local blending incentives as European Union border adjustments begin pressuring long-haul carriers serving Middle-East and Africa routes.
Market Dynamics
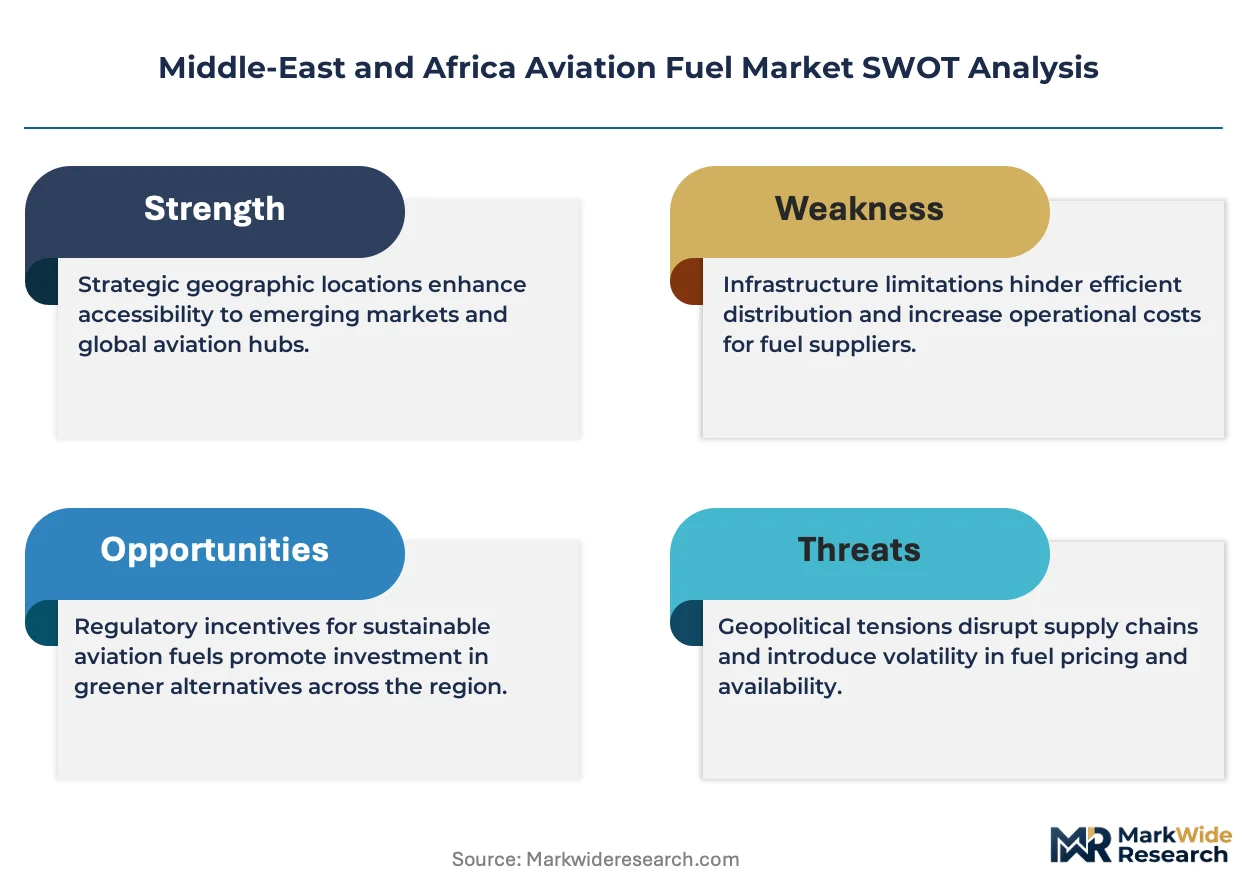
Sustainable aviation fuel mandates from the International Air Transport Association are forcing carriers across the Gulf Cooperation Council to reconfigure supply agreements and upgrade storage infrastructure for blended kerosene formulations.
Growth Catalysts
- Fleet expansion programs:Commercial airlines in the United Arab Emirates and Saudi Arabia are placing multi-year aircraft orders that lock in long-term jet fuel offtake commitments.
- CORSIA compliance deadlines:The International Air Transport Association's carbon offset scheme is compelling carriers to source certified lower-emission fuel blends for international routes.
- Hub infrastructure investments:Dubai International Airport and Abu Dhabi International Airport are expanding fuel farm capacity to capture transshipment volumes from African carriers.
Market Restraints
- Crude price volatility:Jet fuel crack spreads remain exposed to Brent crude swings, compressing refining margins for independent suppliers without upstream integration.
- Refinery concentration:Over half of regional aviation kerosene originates from Saudi Aramco's integrated complexes, creating single-source dependency risk for East African importers.
- Hydrotreater capacity limits:Sulfur reduction requirements exceed existing unit throughput at older facilities in sub-Saharan Africa, forcing reliance on imported product.
Strategic Opportunities
- East African supply gaps:Ethiopia and Kenya lack integrated refining capacity, creating openings for logistics operators to establish coastal import terminals with inland distribution networks.
- Sustainable aviation fuel certificates:European Union border adjustment mechanisms are incentivizing Middle Eastern carriers to secure SAF credits for long-haul routes into European airspace.
- Direct sales channel expansion:Major hubs are bypassing traditional broker networks to capture margin through integrated fuel farm operations at Dubai and Doha airports.
Industry Challenges
- Specialized technician scarcity:Hydrotreater operations and quality control laboratories require certified personnel that sub-Saharan markets cannot source locally.
- ASTM D1655 certification timelines:New storage facilities face extended approval cycles from national regulators to meet flash point and freeze point specifications.
- Legacy fuel farm integration:Older airport infrastructure lacks automated metering systems compatible with modern into-plane delivery protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aviation Fuel Market |
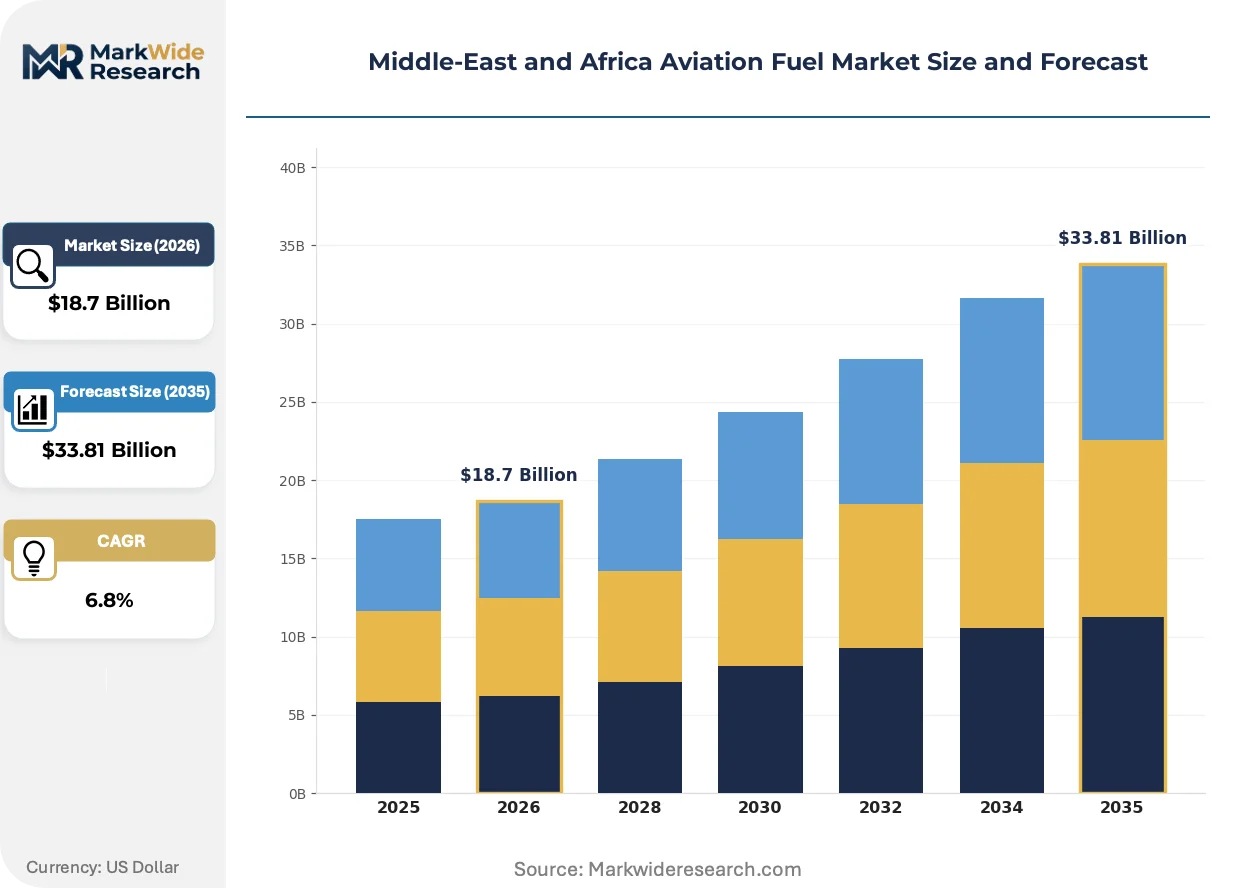
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Jet A, Jet A-1, Jet B, Avgas End User: Commercial Airlines, Cargo Airlines, Military, General Aviation Distribution Channel: Direct Sales, Brokers, Fuel Suppliers, Online Platforms Application: Passenger Flights, Cargo Transportation, Military Operations, Private Flights |
| Companies Covered | Emirates National Oil Company, Abu Dhabi National Oil Company, Saudi Aramco, TotalEnergies SE, Shell PLC, Chevron Corporation, BP PLC, Exxon Mobil Corporation, QatarEnergy, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aviation Fuel Market Shifts & Advancements
Digital fuel management platforms and sustainable aviation fuel blending infrastructure are restructuring how suppliers interact with carriers across the Middle-East and Africa aviation fuel ecosystem.
Advanced into-plane fueling systems equipped with real-time density and temperature sensors are bifurcating ground handling operations at major hubs. Emirates National Oil Company and comparable integrated suppliers are deploying these units at Dubai International Airport to reduce turnaround times for wide-body fleets. The technology is compressing the competitive position of smaller handlers reliant on manual sampling and paper documentation.
The General Civil Aviation Authority of the United Arab Emirates has enacted sulfur content limits that exceed International Air Transport Association baselines, forcing suppliers to upgrade hydrotreating capacity. Refiners serving Dubai and Abu Dhabi airports are investing in additional desulfurization units to maintain supply eligibility. Cargo airlines operating dedicated freighter fleets face the steepest compliance costs due to higher per-tonne fuel consumption profiles.
Long-term offtake agreements are displacing spot market purchases among commercial carriers with predictable route networks. Ethiopian Airlines and Qatar Airways are negotiating multi-year contracts directly with refinery operators to lock in volume security. This pattern is most visible across the Gulf Cooperation Council, where integrated suppliers leverage captive production to offer price stability unavailable through broker-mediated transactions.
Middle-East and Africa Aviation Fuel Market Segmentation
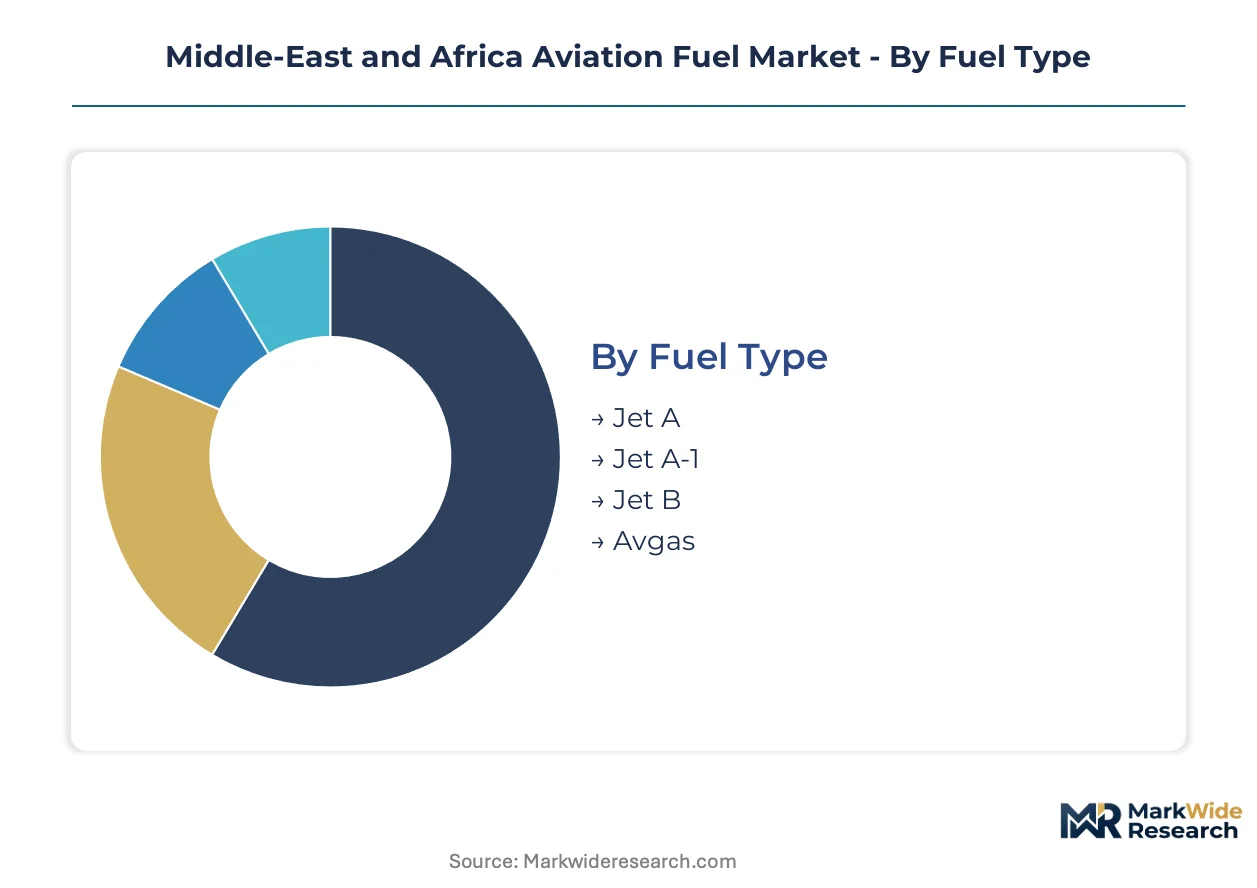
Aviation fuel segmentation in the Middle-East and Africa reveals how margin pools shift between standardized kerosene formulations and specialized military or general aviation products. Understanding these divides exposes where suppliers can defend premium positioning versus competing on volume throughput.
Fuel Type:
Jet A-1 commands the deepest margin pools across the region due to its universal compatibility with commercial turbofan engines and stricter freeze point specifications that filter out lower-grade competitors.
- Jet A:A kerosene-based fuel with higher freeze point tolerance than Jet A-1, primarily stocked at airports serving domestic US-originated aircraft. Demand concentrates in Egypt and Morocco where American-built regional jets operate short-haul routes, though carriers face operational constraints during high-altitude winter crossings.
- Jet A-1:The region's dominant aviation fuel formulation requiring -47°C maximum freeze point certification for high-altitude turbine operations. Dubai International Airport and Abu Dhabi International Airport anchor massive offtake volumes as Emirates and Etihad scale wide-body fleets, with Saudi Aramco's integrated complexes supplying the upstream kerosene base.
- Jet B:A wide-cut fuel blending naphtha and kerosene for extreme cold environments. Military operators in northern African theaters specify this grade for tactical aircraft deployed in high-altitude conditions.
- Avgas:Leaded and unleaded gasoline formulations for piston-engine aircraft. General aviation operators in South Africa and Kenya drive sporadic demand for 100LL and emerging unleaded alternatives as environmental regulations tighten.
The dominant share belongs to Jet A-1, while Avgas is closing the gap fastest as flight schools and private aviation expand in South Africa and the UAE.
End User:
Volume concentration tilts heavily toward scheduled passenger carriers, though cargo operators are rewriting procurement patterns with dedicated freighter networks.
- Commercial Airlines:Scheduled passenger carriers operating turbofan fleets on fixed route networks. Emirates, Qatar Airways, and Ethiopian Airlines lock in multi-year offtake agreements directly with refinery operators, bypassing broker intermediaries to secure price stability unavailable on spot markets.
- Cargo Airlines:Dedicated freighter operators and belly-hold cargo divisions. Qatar Airways Cargo and Ethiopian Airlines Cargo are scaling dedicated freighter fleets, driving disproportionate fuel consumption growth as e-commerce flows expand between the Gulf and sub-Saharan Africa.
- Military:National air forces and coalition operations requiring specialized JP-8 and F-34 formulations. Saudi Arabia's Royal Saudi Air Force and the UAE Air Force anchor regional demand for military-grade kerosene with enhanced thermal stability specifications.
- General Aviation:Private pilots, charter services, and flight training academies. Dubai's expanding business aviation sector and South Africa's recreational flying clubs sustain fragmented demand for smaller-volume fueling.
Commercial Airlines retain the largest volume position, yet Cargo Airlines are expanding most quickly as dedicated freighter fleets multiply across Addis Ababa and Doha hubs.
Distribution Channel:
Control over fuel farm infrastructure determines whether suppliers capture full margin or surrender value to intermediaries.
- Direct Sales:Integrated suppliers operating captive fuel farms and into-plane delivery systems at major airports. Emirates National Oil Company leverages its Jebel Ali refinery complex to dominate Dubai International Airport's direct refueling operations, compressing turnaround times for wide-body fleets through automated metering infrastructure.
- Brokers:Intermediary traders aggregating volumes across fragmented markets lacking integrated storage. East African markets including Kenya and Ethiopia rely heavily on broker-mediated transactions as coastal import terminals feed inland distribution networks.
- Fuel Suppliers:Independent operators with storage assets but limited upstream integration. TotalEnergies SE competes through specialized logistics networks extending into Francophone African markets where infrastructure gaps persist.
- Online Platforms:Digital procurement interfaces for spot market transactions and contract management. Adoption remains nascent across the region as legacy direct relationships dominate high-volume carrier negotiations.
Direct Sales channels control premium margin capture at Gulf hubs, though Brokers maintain critical intermediary functions in fragmented East African markets.
Application:
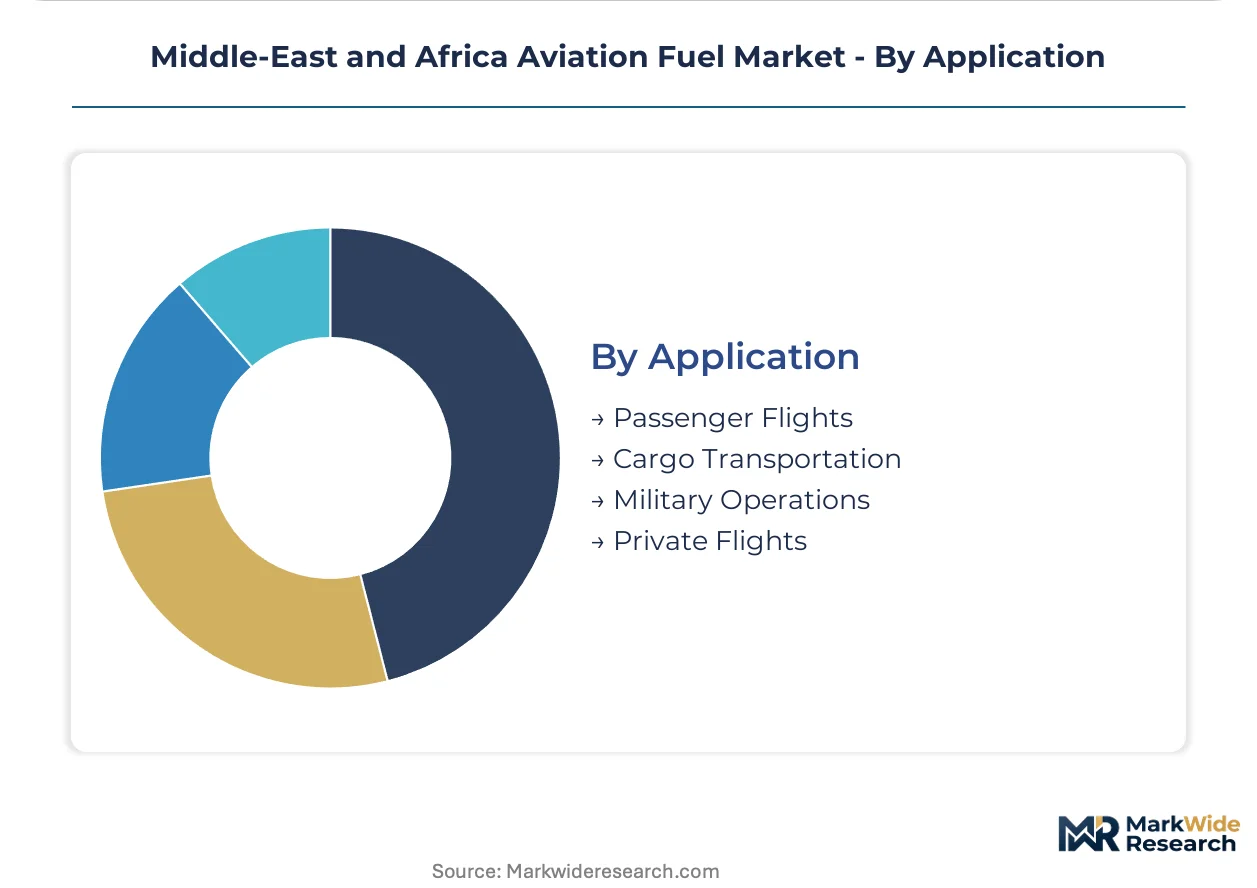
Operational intensity varies dramatically between high-frequency passenger rotations and sporadic military or private deployments.
- Passenger Flights:Scheduled commercial services on fixed route networks. Dubai International Airport's passenger terminals drive the region's highest single-site jet fuel consumption as Emirates operates one of the world's largest Airbus A380 and Boeing 777 fleets.
- Cargo Transportation:Dedicated freighter operations and integrated logistics services. Ethiopian Airlines' cargo division at Addis Ababa Bole International Airport anchors sub-Saharan Africa's fastest-expanding aviation fuel demand node.
- Military Operations:Tactical and strategic air missions with specialized fuel requirements. The UAE's Al Dhafra Air Base and Saudi Arabia's King Khalid Air Base sustain concentrated demand for military-grade kerosene with enhanced thermal stability.
- Private Flights:Business aviation and personal aircraft operations. Dubai's Al Maktoum International Airport and South Africa's Lanseria Airport serve expanding private flight demand from corporate and high-net-worth individuals.
Passenger Flights dominate absolute consumption, yet Cargo Transportation is gaining share fastest as dedicated freighter networks expand across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The General Civil Aviation Authority of the United Arab Emirates enforces sulfur content standards that exceed International Air Transport Association baselines, anchoring regulatory gravity in the Gulf. Saudi Arabia's Saudi Standards, Metrology and Quality Organization aligns domestic specifications with ASTM D1655 frameworks. South Africa's National Regulator for Compulsory Specifications mandates traceability protocols that shape import logistics.
United Arab Emirates
Dubai International Airport and Abu Dhabi International Airport drive concentrated jet fuel demand as Emirates and Etihad scale wide-body fleets. The General Civil Aviation Authority enforces particulate standards stricter than IATA guidelines, forcing hydrotreater upgrades. Jebel Ali refinery complexes anchor supply infrastructure serving transshipment volumes from African carriers.
Saudi Arabia
Saudi Aramco's integrated upstream-to-downstream complexes supply over half of regional aviation kerosene, locking in volume security for domestic carriers. The Saudi Standards, Metrology and Quality Organization aligns military and civilian fuel specifications with DEF STAN 91-91 frameworks. King Khalid International Airport and King Abdulaziz International Airport concentrate demand nodes for scheduled passenger and cargo rotations.
South Africa
Johannesburg's OR Tambo International Airport and Cape Town International Airport sustain the continent's most sophisticated aviation fuel logistics outside the Gulf. The National Regulator for Compulsory Specifications mandates batch traceability that shapes coastal import terminal operations. Durban's refining corridor supplies inland distribution networks serving general aviation and flight training academies.
Ethiopia
Addis Ababa Bole International Airport anchors sub-Saharan Africa's fastest-expanding cargo fuel demand as Ethiopian Airlines scales dedicated freighter fleets. The Ethiopian Civil Aviation Authority enforces storage facility certification timelines that extend approval cycles for new infrastructure. Coastal import terminals at Djibouti feed inland broker-mediated distribution networks lacking integrated fuel farm capacity.
Qatar
Hamad International Airport drives concentrated demand as Qatar Airways and Qatar Airways Cargo expand passenger and freighter operations. The Qatar Civil Aviation Authority monitors sustainable aviation fuel certificate trading mechanisms ahead of European Union border adjustments. Doha's integrated fuel farm operations bypass traditional broker networks to capture premium margins through direct sales channels.
Middle-East and Africa Aviation Fuel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle-East and Africa aviation fuel ecosystem. National oil companies with captive refinery assets command volume throughput and price stability unavailable to independent traders. Two strategic archetypes dominate: integrated upstream-to-downstream operators leveraging Jebel Ali and Ras Tanura complexes, and specialized logistics providers extending into Francophone African infrastructure gaps. Competitive moves concentrate on direct sales channel expansion at major hubs and coastal import terminal establishment for East African supply gaps.
Among Gulf-based integrated suppliers, Emirates National Oil Company and Abu Dhabi National Oil Company occupy positions anchored to Dubai and Abu Dhabi airport fuel farm operations. Saudi Aramco represents the scale-driven archetype with upstream-to-downstream control over regional kerosene supply. TotalEnergies SE sits within the specialized logistics tier, extending networks into Francophone African markets where storage infrastructure remains fragmented.
| Leading Market Players |
|---|
| Emirates National Oil Company |
| Abu Dhabi National Oil Company |
| Saudi Aramco |
| TotalEnergies SE |
| Shell PLC |
| Chevron Corporation |
| BP PLC |
| Exxon Mobil Corporation |
| QatarEnergy |
| Others |
Supply & Pricing Matrix
ASTM D1655 and DEF STAN 91-91 certification regimes gate both supplier qualification and price differentiation in Middle-East and Africa aviation fuel markets, with hydrotreater-equipped refiners commanding premiums over import-dependent terminals lacking desulfurization capacity.
Pricing Analysis
Gulf-to-East-African price spreads of fifteen to twenty-five percent reflect integrated refining advantages at Jebel Ali and Ras Tanura versus broker-mediated coastal imports feeding Addis Ababa and Nairobi. Contract-based long-term offtake agreements dominate procurement among Emirates and Qatar Airways, locking volume security that spot-dependent African carriers cannot access. Price differentiation rests on sulfur content compliance and freeze point certification tiers, with cargo airlines facing steepest cost compression due to higher per-tonne consumption profiles. Price sensitivity concentrates among general aviation operators and flight training academies in South Africa and Kenya, while integrated Gulf carriers prioritize supply security over marginal cost.
Supply Chain Analysis
Strategic stockpile preferences dominate Gulf hub operations, with Dubai International Airport and Hamad International Airport maintaining thirty-to-forty-five-day inventory buffers against Red Sea logistics disruptions. Geographic supply concentrates in Saudi Arabia, the United Arab Emirates, and Qatar, where Saudi Aramco and Emirates National Oil Company control upstream kerosene base stocks. Raw material dependencies center on Brent-linked crude feedstocks, hydrogen for hydrotreating, and specialized additives for thermal stability. Single-source vulnerability from Saudi Aramco's regional kerosene dominance creates structural risk for East African importers. Distribution runs through integrated fuel farm operations at Gulf hubs, fragmenting into broker-mediated coastal terminals and inland trucking networks across sub-Saharan Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Middle-East and Africa aviation fuel markets sit in early-cycle expansion as sustainable aviation fuel blending mandates from the International Air Transport Association create new compliance-driven procurement categories before European Union border adjustments take full effect.
For Market Incumbents: Consolidate hydrotreater capacity advantages through backward integration into hydrogen supply and captive additive manufacturing, defending against specialty chemical entrants targeting SAF blending components. Lock long-term offtake extensions with Ethiopian Airlines and Qatar Airways Cargo before independent traders establish East African coastal terminals. Priority investment centers on automated into-plane metering systems at Dubai and Doha to compress turnaround times and justify premium positioning.
For New Entrants and Emerging Players: Lead with coastal import terminal development at Djibouti and Mombasa, targeting the broker-mediated supply gap for Ethiopian and Kenyan cargo carriers lacking integrated fuel farm access. Penetrable white space concentrates in sustainable aviation fuel certificate aggregation and trading services for Gulf carriers seeking European route compliance. Go-to-market positioning emphasizes logistics flexibility and smaller minimum order quantities unavailable from integrated refinery operators.
For Investors and Strategic Acquirers: Carve-out targets emerge from national oil company downstream divisions seeking to monetize non-core aviation fuel logistics assets in Francophone African markets. Long-term viability favors operators with coastal storage positions and inland distribution networks across high-growth East African economies. Signal to watch: European Union carbon border adjustment implementation timelines accelerating SAF certificate demand and reshaping procurement patterns across Middle-East and Africa routes.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Blending Infrastructure Investment | Positions suppliers for IATA CORSIA compliance deadlines affecting Emirates and Etihad route networks. |
| East African Coastal Terminal Development | Captures broker-mediated volumes from Ethiopian Airlines Cargo and Kenya Airways freighter expansion. |
| Automated Into-Plane System Deployment | Compresses turnaround times at Dubai International Airport, squeezing manual-handling competitors. |
| Hydrotreater Capacity Expansion | Meets General Civil Aviation Authority sulfur standards exceeding baseline IATA guidelines. |
| Long-Term Offtake Agreement Renegotiation | Locks volume security with Qatar Airways before independent traders establish Doha alternatives. |
Research Methodology
Operator-level perspectives from refinery operations managers, aviation fuel procurement leads at Gulf carriers, into-plane service supervisors, and national regulator compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, International Air Transport Association fuel reports, General Civil Aviation Authority enforcement disclosures, and refinery capacity databases. Bottom-up volume modeling triangulated against top-down kerosene demand projections across the analysis window.
Sensitivity analysis tested forecast robustness against crude price volatility scenarios and SAF mandate acceleration timelines. Segmentation dimensions modeled include fuel type grade, end-user category, distribution channel structure, and airport hub tier across the projection horizon. CAGRs derived from historical consumption patterns, fleet order backlogs, and route network expansion disclosures. Industry-specific inputs incorporated hydrotreater capacity utilization rates and sustainable aviation fuel certificate trading liquidity assumptions.
Forecasts assume regulatory continuity in General Civil Aviation Authority enforcement regimes and Saudi Standards, Metrology and Quality Organization alignment frameworks; material policy shifts would require re-modeling. Specific risks include single-source refinery concentration, Red Sea logistics disruptions, and accelerated European Union border adjustment implementation. Revision becomes warranted when SAF blending mandate thresholds or carbon certificate pricing crosses inflection points altering carrier procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
Aircraft Refueler Market
Aircraft Fuel Systems
Military Jet Fuel Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Aerospace Fluid Conveyance System Market
Aircraft Fuel Systems
Aircraft Valves Market
Aircraft Fuel Systems
Hydrogen Aircraft Market
Aircraft Fuel Systems
Aerial Refueling Systems Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Aviation Refueling Market