
 Global Unmanned Aerial Vehicle Landing Gears Market | 2026-2036
Global Unmanned Aerial Vehicle Landing Gears Market Size, Share, and Industry Trends Forecast 2026-2036
Global Unmanned Aerial Vehicle Landing Gears Market Outlook
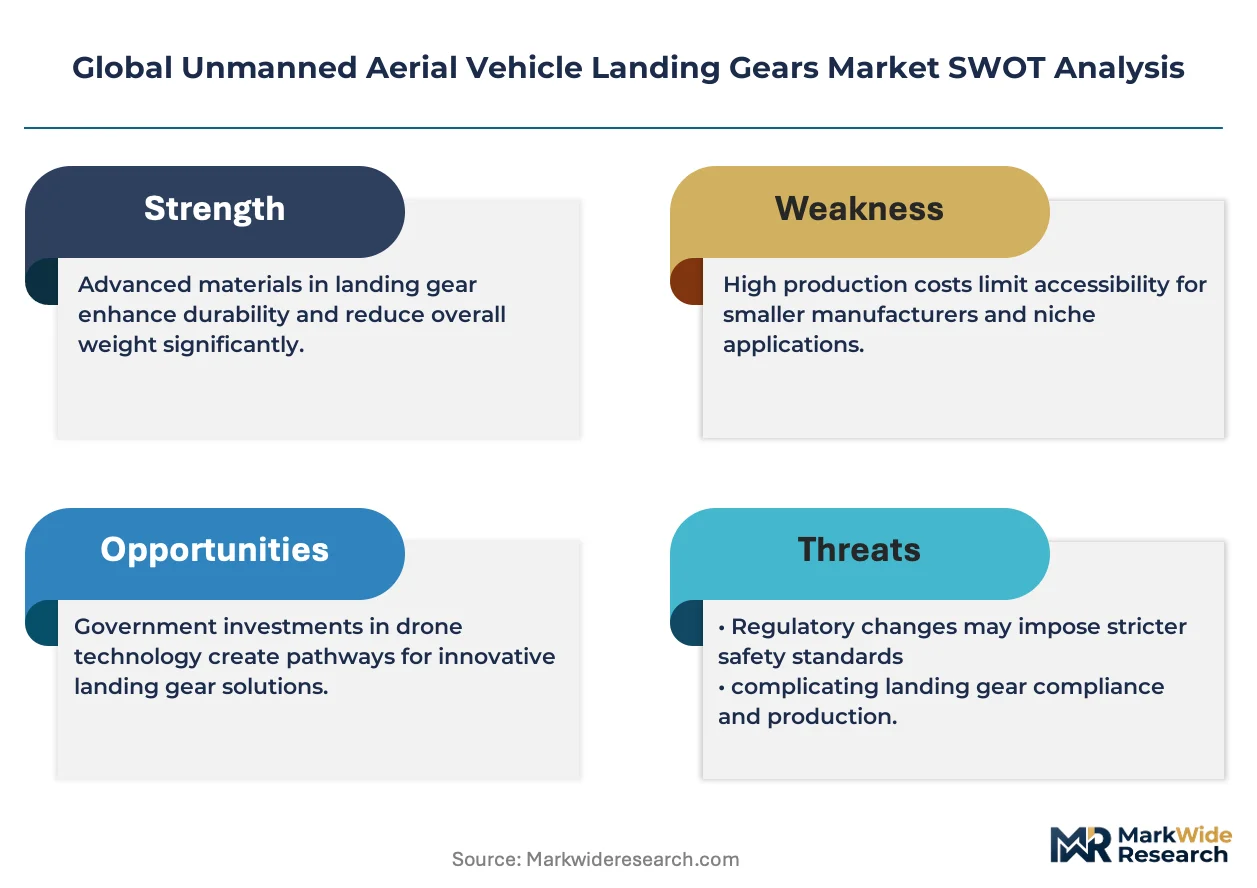
Aftermarket maintenance and overhaul subscription packages is realigning how OEMs monetize landing gear lifecycles. Safran Landing Systems leverages its global MRO network to capture recurring revenue from military operators. UTC Aerospace Systems anchors its position through captive aftermarket channels tied to original equipment placements. Heroux-Devtek differentiates by specializing in lightweight strut assemblies for tactical UAV weight classes.
Unmanned aerial vehicle landing gears are structural undercarriage assemblies engineered to absorb impact loads during takeoff, landing, and ground handling, typically fabricated from aluminum alloys or carbon fiber composites with specified stroke lengths and energy absorption ratings calibrated to platform gross weights. Their primary purpose is to protect avionics payloads and airframe integrity during repeated ground contact cycles across austere operating surfaces. Retractable landing gear configurations command premium positioning due to drag reduction benefits on long-endurance missions, while skid landing gear dominates rotary-wing UAV segments where ground footprint minimization matters. Carbon fiber composites represent the fastest-expanding material category as platforms chase payload fraction improvements, though aluminum alloys still occupy the volume core of military procurement specifications.
FAA certification standards for unmanned systems under 14 CFR Part 89, EASA drone type certification pathways, and ISO 21384-3 airworthiness guidelines collectively shape landing gear design loads, fail-safe requirements, and test protocols that manufacturers must satisfy for market access. Military operators increasingly specify MIL-STD-810 environmental testing for undercarriage components deployed in contested logistics environments. Stakeholders must monitor how emerging heavy-lift UAV classes above 500 kg maximum takeoff weight will force updates to existing structural qualification baselines and supplier qualification scopes.
Market Dynamics
Military ISR mission requirements and FAA Part 107 airworthiness evolution are compressing development cycles for ruggedized landing systems. Platform operators now demand retractable configurations that reduce drag on extended endurance flights.
Growth Catalysts
- EU Drone Regulations:EASA type certification pathways for UAVs above 25 kg are mandating redundant landing gear structures, expanding addressable demand for qualified suppliers.
- Carbon Fiber Composites:Tactical UAV weight class reductions are accelerating substitution of aluminum strut assemblies with filament-wound composite landing gear legs.
- United States Defense Corridor:Pentagon procurement of Group 4-5 unmanned systems is concentrating landing gear orders around domestic forge and machining clusters.
Market Restraints
- Titanium Alloy Input Costs:Sponge and mill product price volatility is compressing margins on high-performance oleo strut assemblies for heavy-lift platforms.
- Single-Source Forging Capacity:Large titanium closed-die forging presses concentrate in three North American facilities, creating supply concentration risk for critical structural forgings.
- MIL-STD-810 Qualification Burden:Environmental testing requirements for sand, dust, and temperature extremes add 14-18 months to new supplier qualification timelines.
Strategic Opportunities
- India UAV Manufacturing:PLI scheme incentives for drone component localization are opening procurement channels for landing gear suppliers establishing domestic machining operations.
- Urban Air Mobility Integration:eVTOL platforms require novel load-distribution architectures, creating white space for oleo-pneumatic and electromagnetic landing system specialists.
- ISO 21384-3 Harmonization:Emerging global airworthiness guidelines for unmanned systems are reducing multi-jurisdiction certification duplication costs for compliant designs.
Industry Challenges
- Composite Repair Technician Scarcity:Military depot and civil MRO facilities lack sufficient personnel trained in carbon fiber landing gear damage assessment and restoration.
- Legacy Platform Retrofit Integration:Fixed-gear UAV designs require structural hardpoint modifications to accommodate retractable landing gear upgrades without airframe recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Unmanned Aerial Vehicle Landing Gears Market |
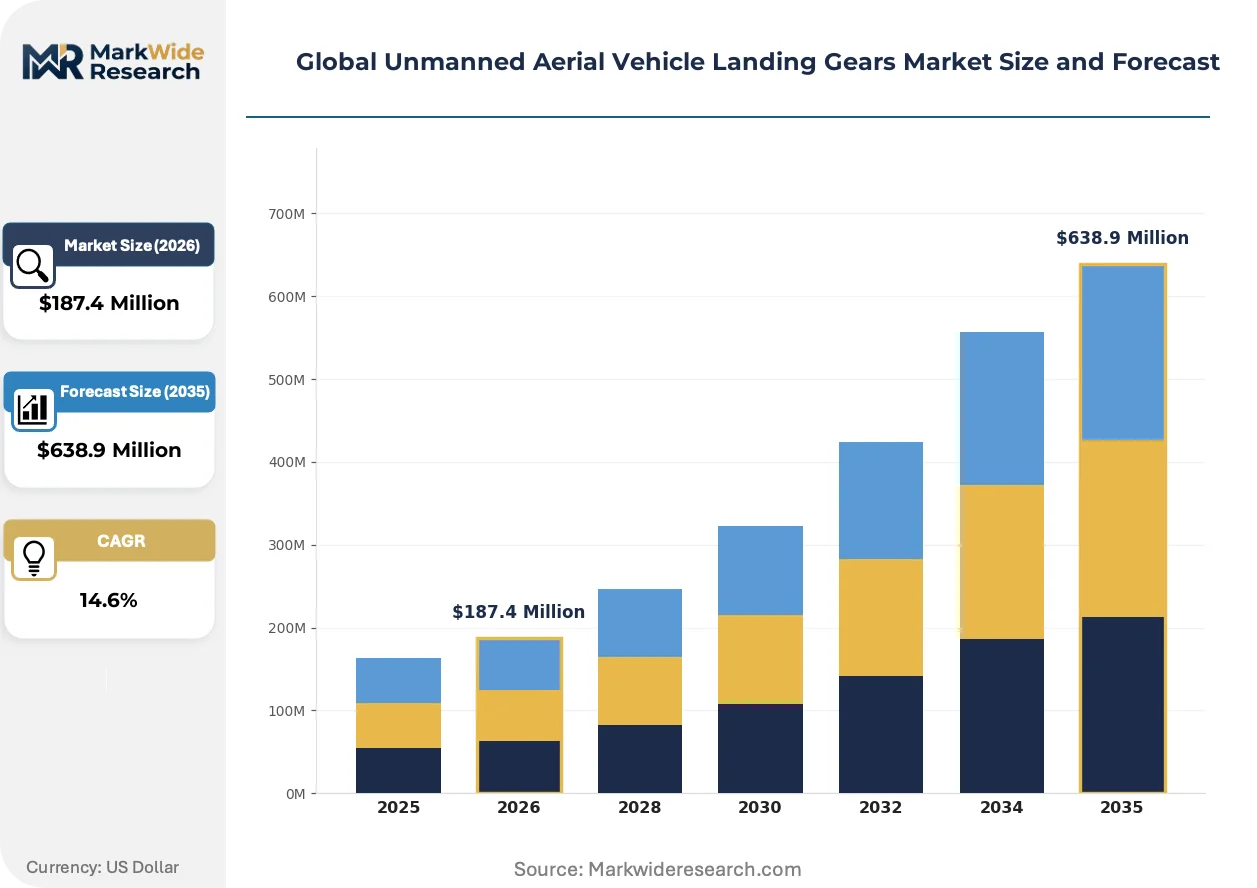
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Landing Gear, Retractable Landing Gear, Skid Landing Gear, Tricycle Landing Gear Material: Aluminum Alloys, Carbon Fiber Composites, Steel Alloys, Polymeric Materials End User: Military, Commercial, Research, Agriculture Technology: Electric Actuation, Hydraulic Systems, Mechanical Systems, Hybrid Systems |
| Companies Covered | GE Aviation, The Boeing Company, Safran Landing Systems, BAE Systems plc, Northrop Grumman Corporation, UTC Aerospace Systems, Lockheed Martin Corporation, Airbus SE, Heroux-Devtek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Unmanned Aerial Vehicle Landing Gears Market Strategic Shifts
Active materials and adaptive damping technologies are reshaping how landing gear systems manage impact energy across variable payload configurations. These advances compress development cycles while expanding operational envelope boundaries.
Magnetorheological fluid dampers are integrating into tactical UAV main landing gear struts to enable real-time stroke resistance adjustment based on gross weight sensors. Special forces operators deploying variable-payload ISR platforms are specifying these adaptive systems for austere-field reliability. This capability is integrating formerly separate mechanical and electronic control domains into unified landing gear management architectures.
EASA's drone type certification framework is mandating fail-safe deployment mechanisms for retractable landing gear on platforms above 150 kg MTOW. Manufacturers must now demonstrate gravity-free extension and locked-down indication systems under single-fault conditions. Heavy-lift cargo UAV developers in Germany and France are restructuring hydraulic architectures to meet these requirements ahead of 2026 implementation deadlines.
Defense procurement offices are consolidating landing gear purchases into platform-level subsystem contracts rather than discrete component awards. Tier-one UAV integrators in Israel and the United States are absorbing landing gear design responsibility and sourcing directly from forge and composite houses. This disintermediation is compressing supplier margins while rewarding vertically capable manufacturers with airframe design influence.
Global Unmanned Aerial Vehicle Landing Gears Market Segmentation
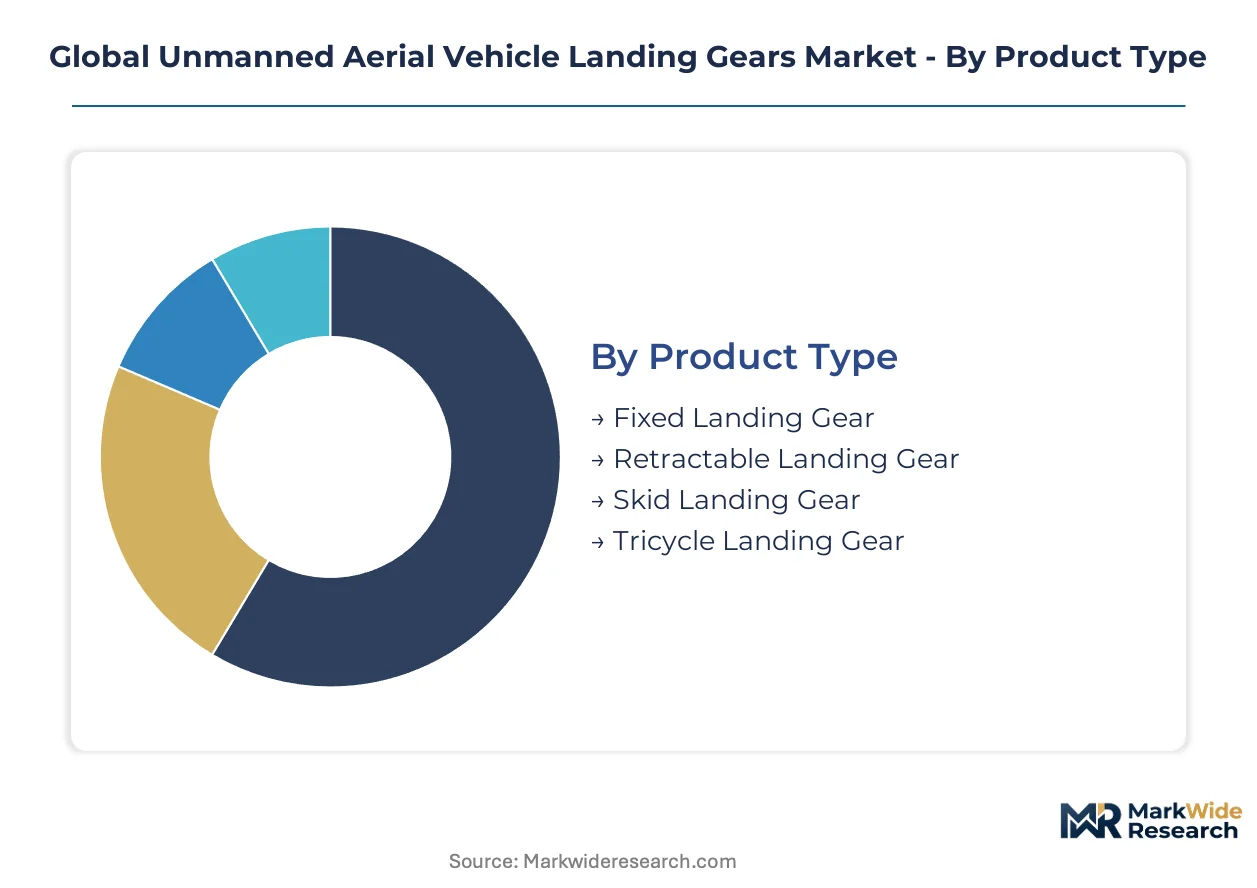
UAV landing gear configurations must balance weight, complexity, and mission endurance. Platform operators select architectures based on payload fraction targets and field maintenance constraints. Segmentation reveals where embedded integration outperforms standalone assemblies.
Product Type:
Fixed landing gear dominates tactical platforms where mechanical simplicity outweighs drag penalties. Retractable systems embed deeper into airframe architectures, demanding tighter integration with flight control electronics.
- Fixed Landing Gear:Strut assemblies remain permanently extended, eliminating actuation failure modes. Israeli defense contractors specify these for desert-deployed ISR platforms where sand infiltration threatens mechanical complexity. The configuration sacrifices cruise efficiency for depot-level maintainability.
- Retractable Landing Gear:Stowable assemblies reduce form drag during loiter phases. Pentagon Group 4-5 procurement mandates these for missions exceeding 20-hour endurance. Integration with landing gear control units adds software qualification burden.
- Skid Landing Gear:Tubular steel or composite runners suit rotary-wing UAVs. Chinese agricultural drone manufacturers favor these for paddy-field operations where wheeled ground handling fails.
- Tricycle Landing Gear:Nose-wheel steering configurations stabilize heavy-lift platforms during crosswind landings. German cargo UAV developers specify these for 500 kg-plus payloads.
Fixed landing gear leads volumes today; retractable configurations are gaining share fastest.
Material:
Material selection traces payload fraction requirements against unit cost tolerance. Military specifications anchor aluminum procurement while commercial operators experiment with composite substitution.
- Aluminum Alloys:7075-T6 and 7050 forgings dominate structural strut production. United States defense contractors specify these alloys for MIL-STD-810 shock qualification. Established supply chains from Pennsylvania and Ohio machining clusters ensure predictable lead times.
- Carbon Fiber Composites:Filament-wound legs achieve 40% weight reduction versus metallic equivalents. French tactical UAV programs specify these for hand-launched platforms below 25 kg MTOW. Repair infrastructure scarcity limits military adoption.
- Steel Alloys:4340 and 300M ultra-high-strength steels withstand repeated hard landings. Israeli manufacturers select these for carrier-based UAV arrestment loads.
- Polymeric Materials:Injection-molded nylon and PEEK bushings reduce friction in pivot joints. Chinese consumer drone producers specify these for cost-sensitive volume production.
Aluminum alloys dominate procurement volumes; carbon fiber composites are climbing the fastest.
End User:
End-use segmentation separates specification rigor from price elasticity. Military operators prioritize environmental qualification over acquisition cost.
- Military:ISR and strike platforms demand MIL-STD-810 sand, dust, and temperature cycling. United States Special Operations Command specifies ruggedized strut assemblies for austere forward operating bases.
- Commercial:Package delivery and infrastructure inspection operators prioritize MTTR over MTBF. German logistics integrators specify quick-release strut modules for hub turnaround.
- Research:Academic and experimental platforms tolerate higher failure rates for cost access. Indian aerospace institutes source aluminum fixed gear for prototype validation.
- Agriculture:Crop-spraying UAVs require corrosion-resistant finishes for chemical exposure. Brazilian plantation operators specify anodized aluminum with fluoropolymer topcoats.
Military end-use commands premium positioning; commercial applications show steepest expansion trajectory.
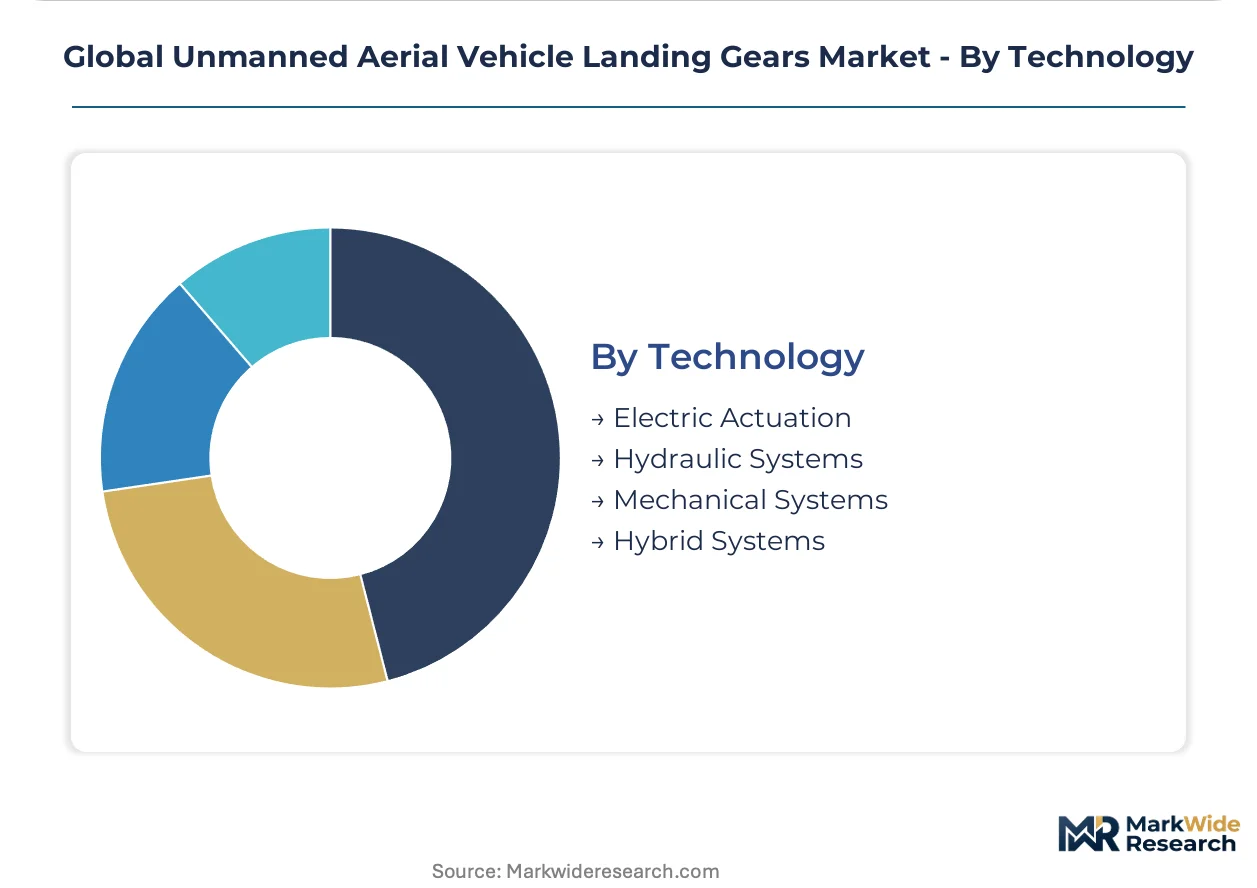
Technology:
Actuation technology selection determines maintenance intervals and single-point failure modes. Electric architectures displace hydraulics in platforms below 150 kg MTOW.
- Electric Actuation:Brushless DC motors with ball screw transmissions enable precise position feedback. EASA type certification pathways for UAVs above 25 kg mandate locked-down indication systems. French eVTOL developers specify these for fail-safe gravity deployment.
- Hydraulic Systems:Oleo-pneumatic struts provide superior energy absorption for heavy-lift platforms. United States Navy carrier-based UAV programs retain these for arrestment shock mitigation. Seal degradation in sandy environments drives maintenance burden.
- Mechanical Systems:Spring and damper assemblies eliminate power dependency. Israeli tactical platforms specify these for electronic warfare resilience.
- Hybrid Systems:Electric primary actuation with mechanical backup satisfies emerging fail-safe mandates. German heavy-lift cargo UAV prototypes integrate these for 2026 certification deadlines.
Hydraulic systems retain heavy-lift dominance; electric actuation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's domestic UAV program expansion contrasts with Israel's export-focused defense specialization, while the United States concentrates procurement around established defense corridors. Each geography shapes landing gear demand through distinct regulatory and industrial pathways.
United States
Pentagon Group 4-5 unmanned system procurement drives ruggedized landing gear orders. FAA Part 89 certification standards for unmanned systems establish design load requirements. Pennsylvania and Ohio machining clusters supply aluminum alloy forgings for military strut assemblies.
China
Domestic agricultural and tactical UAV production scales demand for corrosion-resistant skid configurations. MIIT drone regulations under GB standards tighten airworthiness compliance for commercial platforms. Yangtze River Delta manufacturers integrate composite landing legs into hand-launched systems below 25 kg.
Israel
Defense export contracts concentrate procurement of fixed-gear assemblies for desert-deployed ISR platforms. Israeli military specifications emphasize MIL-STD-810 environmental qualification. Tel Aviv-area integrators source steel alloy struts for carrier-based UAV arrestment applications.
Germany
Heavy-lift cargo UAV development above 500 kg MTOW creates demand for tricycle configurations. EASA drone type certification mandates fail-safe deployment mechanisms for retractable systems. Bavarian aerospace clusters prototype hybrid electric-hydraulic actuation architectures.
India
PLI scheme incentives for drone component localization attract landing gear suppliers establishing machining operations. DGFT import substitution policies favor domestic aluminum strut production. Karnataka and Maharashtra aerospace parks host emerging fabrication capabilities for tactical UAV weight classes.
Global Unmanned Aerial Vehicle Landing Gears Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with defense procurement favoring established aerospace suppliers while commercial UAV builders source from regional fabricators. The market exhibits tiered concentration: global landing system houses anchor military contracts, mid-scale specialists capture tactical platform orders, and regional machine shops serve agricultural drone producers. Two dominant competitive moves reshape positioning: defense integrators absorb landing gear design responsibility through backward integration into forge and composite sourcing, and MRO networks expand subscription-based lifecycle service packages.
Among global landing system houses, Safran Landing Systems and UTC Aerospace Systems exemplify the integrated tier, occupying positions where captive aftermarket channels reinforce original equipment placements. Heroux-Devtek represents the specialization archetype, with its corporate structure signaling focus on precision-machined assemblies. These three entities anchor the competitive landscape without exhausting its diversity, as regional fabricators and emerging composite houses continue fragmenting commercial and agricultural segments.
| Leading Market Players |
|---|
| GE Aviation |
| The Boeing Company |
| Safran Landing Systems |
| BAE Systems plc |
| Northrop Grumman Corporation |
| UTC Aerospace Systems |
| Lockheed Martin Corporation |
| Airbus SE |
| Heroux-Devtek |
| Others |
Value Chain & Pricing Dynamics
Captive aftermarket networks anchor pricing power for established landing gear suppliers while compressing margins for component-only vendors. Defense integrators absorbing design responsibility through backward integration into forge sourcing simultaneously secure supply position and capture value formerly distributed across tiered supplier tiers.
Pricing Analysis
Capacity additions in India's PLI-subsidized machining corridors are reshaping price floors for aluminum strut assemblies. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810 qualified military configurations from commercial-grade fixed gear and agricultural skid systems. Cost compression in the commercial tier is intensifying because Chinese agricultural drone manufacturers source directly from Yangtze River Delta fabricators. Military operators show least price sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Titanium sponge supply rests on concentrated North American and Japanese specialty metal producers. The industry draws from Pennsylvania and Ohio machining clusters for aluminum forgings, Chinese composite houses for filament-wound legs, and Israeli steel specialists for carrier-arrestment struts. Single-source vulnerability concentrates in large closed-die forging presses. Distribution runs through platform-level subsystem contracts rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's PLI-subsidized fabrication costs and Germany's EASA-mandated certification premiums for fail-safe retractable systems.
For Market Incumbents: Cement captive aftermarket channels through subscription-based MRO packages that lock in military operator lifecycles. Deepen upstream control over titanium forging capacity to offset single-source supply risk. Prioritize ISO 21384-3 harmonization investments to reduce multi-jurisdiction certification duplication costs against emerging composite house entrants. For New Entrants and Emerging Players: Enter via India's component localization incentives by establishing aluminum machining operations in Karnataka aerospace parks. The most penetrable white space sits in quick-release strut modules for German logistics integrators prioritizing hub turnaround speed over military-grade qualification. Lead with electric actuation architectures for sub-150 kg platforms where EASA mandates are creating first-mover certification advantages. For Investors and Strategic Acquirers: Consolidation pressure builds where defense integrators disintermediate tier-one landing gear suppliers through direct forge sourcing. Long-term viability favors vertically capable manufacturers retaining airframe design influence alongside captive aftermarket networks. Target acquisition profile: mid-scale specialists with MIL-STD-810 qualification credentials and established relationships with Israeli or United States defense contractors. Watch EASA's 2026 fail-safe deployment deadlines as inflection indicator for hybrid actuation technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Forging | Secures critical structural capacity against North American supply concentration risk. |
| Composite Landing Gear Certification Investment | Positions suppliers for French tactical UAV weight reduction programs. |
| Subscription MRO Service Launch | Mirrors Safran's recurring revenue capture from military operator lifecycles. |
| India PLI Scheme Manufacturing Entry | Unlocks procurement channels for domestic UAV component localization mandates. |
| Hybrid Electric-Hydraulic Actuation Development | Addresses EASA fail-safe requirements for German heavy-lift cargo UAV prototypes. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions with UAV platform engineers, defense procurement officers, landing gear design leads, and aftermarket service managers combined with secondary validation against FAA Part 89 certification databases, EASA type certification filings, MIL-STD-810 test records, and customs trade data for aluminum and titanium mill products. Bottom-up build-ups from segment-level unit economics triangulated against top-down market sizing from defense procurement disclosures.
Historical reference periods anchored volume and value trajectories across the analysis window. The forecast framework modeled product type, material category, end-use segment, actuation technology, and geographic production hub as core dimensions. CAGRs derived from weighted average growth rates across these segments, with specific inputs including Pentagon Group 4-5 procurement schedules, EASA regulatory implementation timelines, and composite material substitution curves in tactical UAV weight classes.
Inputs from defense procurement databases and regulatory filing systems were available through the study window; gaps in emerging heavy-lift UAV prototype cost structures introduce uncertainty bands around commercial segment projections. Forecasts reflect documented assumptions regarding certification timeline adherence and raw material price stability. A small set of named triggers—including EASA fail-safe mandate enforcement, India PLI scheme renewal terms, and titanium sponge price volatility—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
Military Autonomous Robot Market
Unmanned Systems
Unmanned Systems Market
Unmanned Systems
Europe Aerospace Robotics Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Unmanned Aerial Vehicle Payload and Subsystems Market
Unmanned Systems
Autonomous Drone Platform Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Autonomous Precision Guided Munition Market
Unmanned Systems
Loitering Munition System Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Global Submarine Payload Market
Unmanned Systems
Unmanned Surface Vehicle Market
Unmanned Systems
EMEA Dismounted Soldier Systems Market