
 Aircraft Wheels Brakes Market | 2026-2036
Aircraft Wheels Brakes Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Wheels Brakes Market Outlook
Modular brake system packaging is restructuring how airlines procure landing gear components, shifting from discrete part purchases to integrated wheel-and-brake kits that simplify fleet maintenance. Honeywell International Inc leverages its integrated avionics-to-landing-gear portfolio to anchor long-term OEM contracts across narrowbody platforms. Safran Group competes through specialized carbon-carbon brake manufacturing capabilities that dominate high-heat commercial applications. Parker-Hannifin Corporation extends its hydraulic systems expertise into electromechanical brake actuation architectures for next-generation aircraft.
Aircraft wheels and brakes encompass the rotating assemblies and friction-based deceleration systems mounted on landing gear struts, typically fabricated from aluminum or titanium forgings with carbon-carbon composite heat sinks rated for temperatures exceeding 1,500°C during rejected takeoff events. These systems serve the primary function of converting kinetic energy into controlled thermal dissipation during landing, taxi, and emergency braking maneuvers. The commercial aircraft application segment leads absolute volume as global passenger traffic drives fleet renewal, while the MRO end-user channel captures expanding margin pools from aging brake disc replacement cycles. Composite material formulations within product type classifications are displacing traditional steel brake configurations as operators seek weight reduction and extended mean time between overhaul.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate specific energy absorption capacities and stopping distance performance for transport category aircraft brake systems. The EPA's emerging per- and polyfluoroalkyl substances restrictions are forcing reformulation of hydraulic fluids and anti-corrosion coatings used in wheel assembly lubrication systems. Stakeholders must monitor how dual regulatory pressure from aviation safety agencies and environmental regulators reshapes material qualification timelines and supplier certification burdens.
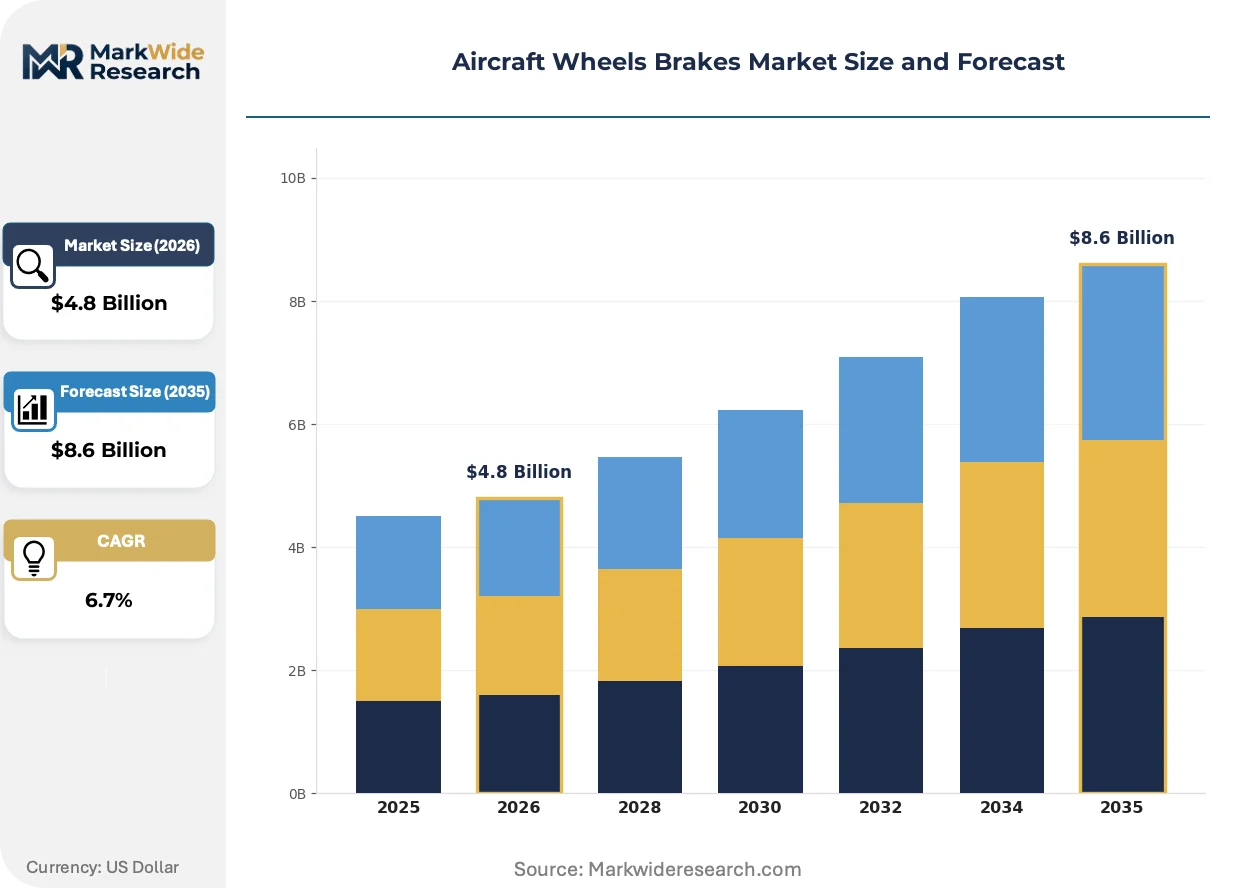
Market Dynamics
Carbon-carbon composite brake assemblies are displacing traditional steel configurations across narrowbody and widebody fleets, driven by FAA and EASA thermal performance mandates that now require 1,500°C heat rejection capacity during rejected takeoff scenarios. This material transition concentrates procurement power with OEMs capable of integrated wheel-and-brake kit production.
Growth Catalysts
- FAA Part 25 Certification Standards:Updated energy absorption mandates for transport category aircraft are accelerating fleet-wide brake system upgrades as carriers seek to maintain airworthiness certificates without operational grounding.
- Commercial Aviation Fleet Expansion:Narrowbody aircraft deliveries across Asia-Pacific and Middle Eastern carriers are generating sustained demand for original equipment brake assemblies with extended mean time between overhaul specifications.
- Carbon-Carbon Manufacturing Scale-Up:Specialized heat sink production facilities in the United States and France are achieving cost parity with steel alternatives through automated layup processes and reduced cycle times.
Market Restraints
- Raw Material Concentration:Aerospace-grade carbon fiber precursor supply concentrates in Japanese and US chemical plants, exposing brake manufacturers to polyacrylonitrile price volatility and allocation constraints during capacity crunches.
- Specialized Labor Scarcity:Carbon-carbon composite layup technicians and thermal analysis engineers remain concentrated at legacy OEM facilities, limiting new entrant production scaling without multi-year training investments.
- EASA CS-25 Certification Burden:Extended qualification timelines for new brake formulations and heat sink geometries create 18-36 month market entry barriers that favor incumbent suppliers with established regulatory relationships.
Strategic Opportunities
- Electromechanical Actuation Convergence:Hydraulic-to-electric brake system transitions on next-generation aircraft platforms are creating white space for suppliers with electromechanical control expertise to capture value previously held by hydraulic specialists.
- India Fleet Modernization:IndiGo and Air India's narrowbody expansion programs under the country's PLI scheme for aerospace components are opening localized MRO and assembly opportunities for brake system providers meeting BIS quality standards.
- EPA PFAS Restrictions:Emerging prohibitions on per- and polyfluoroalkyl substances in hydraulic fluids and anti-corrosion coatings are forcing formulation innovation that first-movers can patent and license across the aftermarket channel.
Industry Challenges
- Legacy System Integration Complexity:Electromechanical brake architectures must maintain backward compatibility with existing Boeing and Airbus landing gear interfaces, requiring redundant certification pathways that extend development timelines.
- Thermal Modeling Talent Gap:Computational fluid dynamics specialists capable of simulating 1,500°C transient heat rejection remain scarce, forcing OEMs to retain external consultants at premium rates during peak certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Wheels Brakes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honeycomb, Solid, Composite, Steel Application: Commercial Aircraft, Military Aircraft, Cargo Aircraft, Business Jets Material: Aluminum, Titanium, Carbon, Magnesium End User: OEMs, MROs, Airlines, Leasing Companies |
| Companies Covered | Honeywell International Inc, Safran Group, Parker-Hannifin Corporation, Collins Aerospace, Crane Aerospace & Electronics, RTX Corporation, Meggitt PLC, Liebherr-International AG, AAR Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Wheels Brakes Market Strategic Shifts
Integrated wheel-and-brake kit procurement is compressing supplier tiers and reshaping how airlines contract for landing gear lifecycle support. Three material and operational shifts are restructuring competitive positioning.
Electromechanical brake actuation architectures are unifying power distribution and control electronics within single housing units that replace discrete hydraulic lines, accumulators, and valves. Regional carriers and low-cost operators in Southeast Asia are specifying these configurations on new A320neo and 737 MAX deliveries to reduce maintenance touchpoints. The technology is unifying previously separate hydraulic and avionics supplier ecosystems into consolidated electromechanical system portfolios.
EASA's emerging F-Gas Regulation amendments are targeting hydrofluorocarbon-based fire suppression systems and heat transfer fluids used in brake cooling circuits. European MRO facilities must now inventory alternative chemistries and retrain handling personnel before 2027 phase-in deadlines. Widebody operators with heavy European route exposure are accelerating brake system refurbishment cycles to align with these environmental compliance timelines.
Airline engineering departments are consolidating wheel and brake procurement under single-source integrated supply agreements that bundle initial equipment, scheduled overhaul, and unscheduled repair under fixed per-landing fees. Low-cost carriers with standardized narrowbody fleets in the United States and Brazil are driving this model adoption to convert capital expenditure into predictable operating costs. The shift is most visible among ultra-low-cost operators with aircraft utilization rates exceeding 12 block hours daily, where brake reliability directly impacts fleet availability metrics.
Aircraft Wheels Brakes Market Segmentation
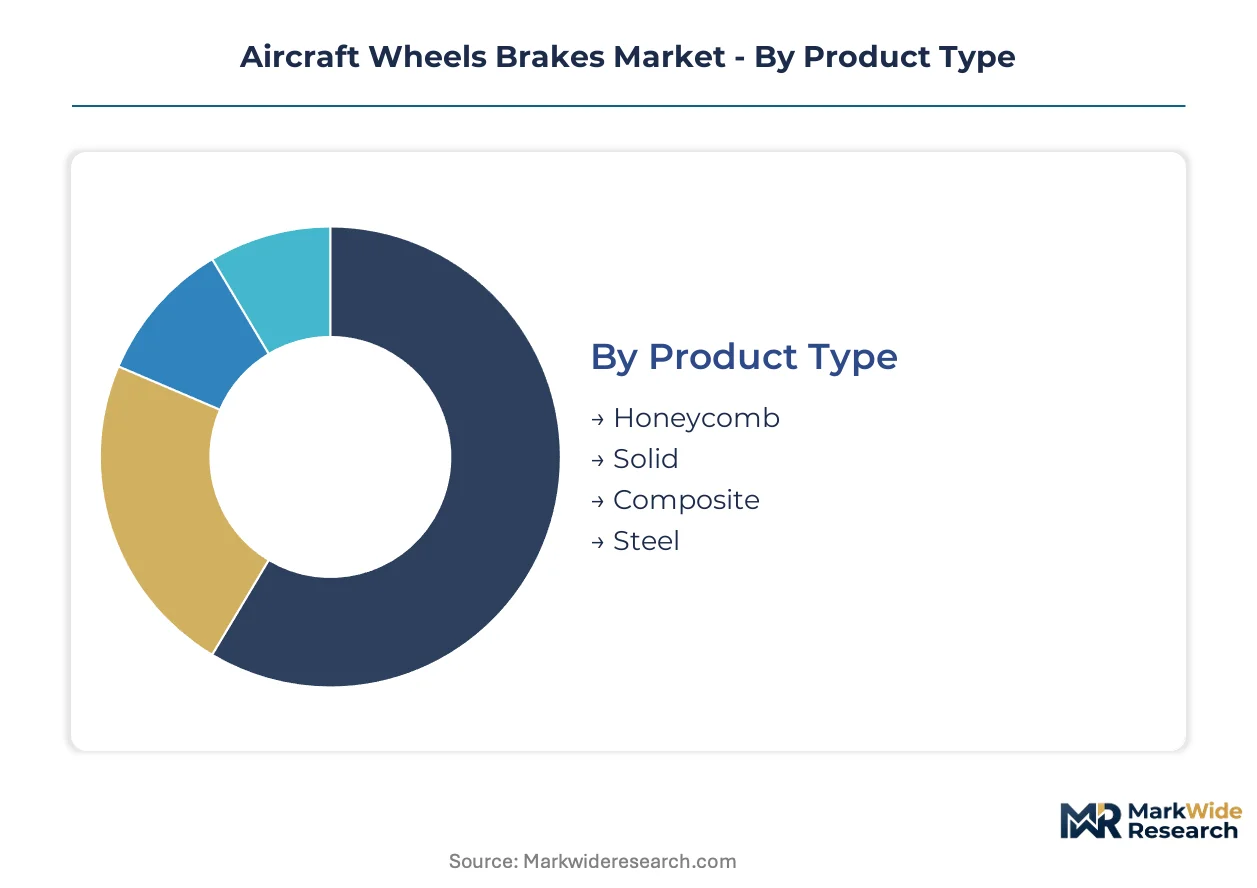
Aircraft wheels and brakes procurement decisions hinge on thermal performance specifications, fleet utilization intensity, and regulatory certification pathways. Understanding how demand fragments across product architectures, operator types, and material systems clarifies where supplier investments yield sustainable margin capture.
Product Type:
Operator maintenance economics and heat rejection requirements drive product selection, with carbon-carbon configurations commanding premium positioning for high-cycle narrowbody operations.
- Composite:Carbon-carbon brake assemblies withstand temperatures exceeding 1,500°C during rejected takeoff events, making them mandatory for FAA Part 25 certification on new-generation narrowbody deliveries. Airlines with utilization rates above 10 block hours daily specify these configurations to extend mean time between overhaul and minimize unscheduled removals.
- Honeycomb:Lightweight aluminum honeycomb wheel structures reduce unsprung mass on regional jet platforms, improving fuel efficiency during high-frequency short-haul cycles. Demand concentrates among turboprop and regional jet operators in the United States and Brazil where landing gear weight reduction directly impacts payload economics.
- Solid:Forged aluminum and titanium solid wheels serve legacy widebody and military platforms requiring structural simplicity and field repairability.
- Steel:Traditional steel brake configurations persist in cargo and converted freighter aircraft where acquisition cost sensitivity outweighs thermal performance advantages.
Volume sits with Honeycomb wheels on regional platforms; growth tilts toward Composite brake assemblies as thermal mandates tighten.
Application:
Fleet renewal cycles and defense procurement budgets determine application-level demand concentration, with commercial aviation generating recurring aftermarket revenue pools.
- Commercial Aircraft:Narrowbody and widebody passenger jets drive absolute unit demand, with brake replacement cycles accelerating as global fleet age exceeds 12 years on average. Asia-Pacific carriers expanding A320neo and 737 MAX fleets under long-term operating leases generate sustained OEM and MRO procurement.
- Military Aircraft:Fighter and transport platforms require specialized heat sink geometries rated for arrested landing energy absorption on carrier decks and austere field operations.
- Cargo Aircraft:Converted freighter and dedicated cargo operations prioritize brake durability over weight reduction, extending steel configuration viability.
- Business Jets:Fractional ownership fleets and corporate flight departments specify integrated wheel-and-brake kits to minimize downtime at fixed-base operator facilities.
Revenue concentrates in Commercial Aircraft; aftermarket margin expansion is steepest in Business Jets.
Material:
Weight-strength tradeoffs and thermal conductivity specifications govern material selection, with supply chain concentration in aerospace-grade precursor production creating procurement risk.
- Carbon:Carbon-carbon composite heat sinks dominate high-performance brake applications, with Japanese and US chemical plants supplying polyacrylonitrile precursor under long-term allocation agreements. EASA CS-25 thermal performance mandates are accelerating displacement of metallic alternatives across European-registered fleets.
- Aluminum:Forged aluminum wheels remain standard on narrowbody platforms where cost efficiency and established MRO repair networks outweigh marginal weight savings from titanium alternatives.
- Titanium:High-strength titanium forgings serve widebody landing gear where structural load requirements exceed aluminum capabilities.
- Magnesium:Magnesium alloys appear in specialized military and legacy applications where electromagnetic interference considerations limit alternative materials.
Procurement volume favors Aluminum wheels; carbon fiber precursor constraints are accelerating most quickly in Carbon brake heat sinks.
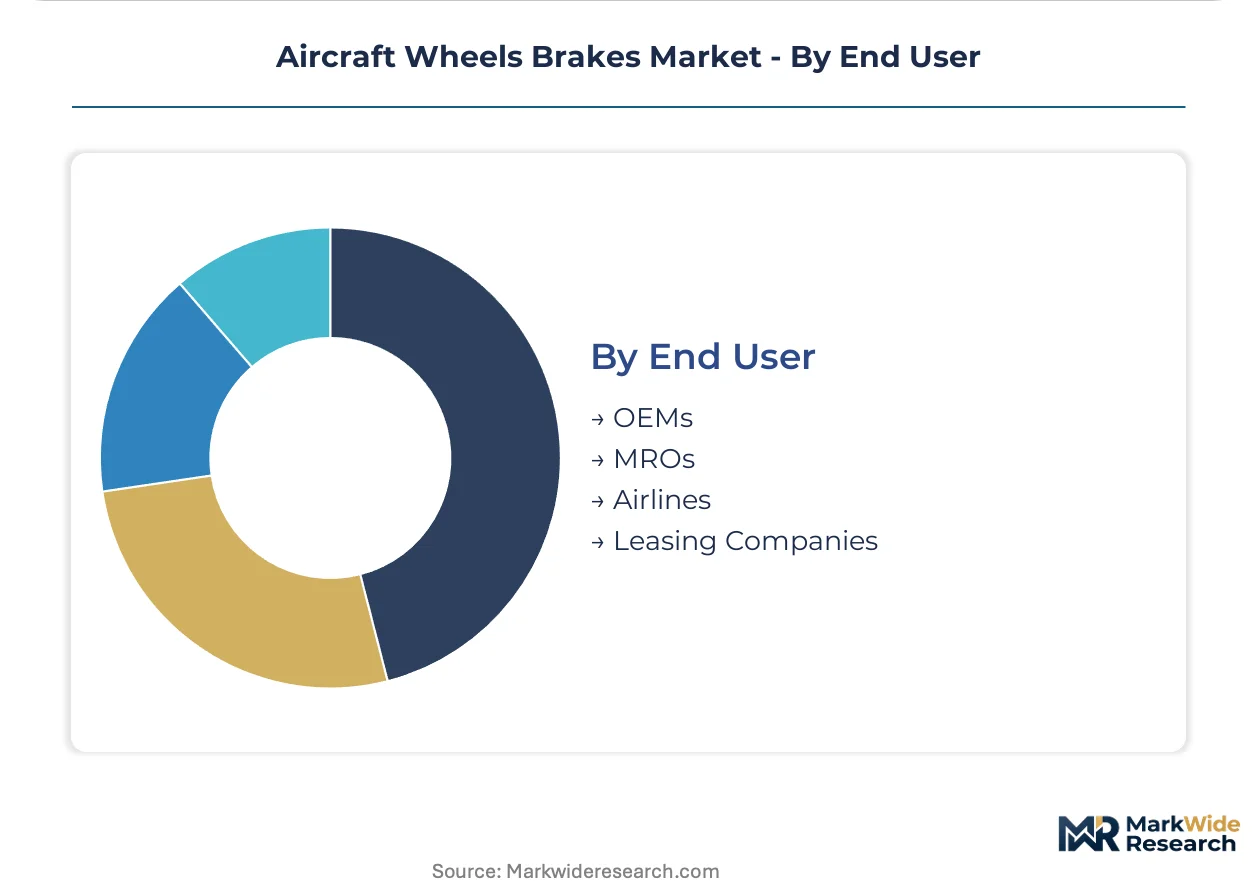
End User:
Capital deployment models and technical capabilities determine end-user procurement patterns, with leasing companies emerging as consolidated decision-makers.
- MROs:Maintenance, repair, and overhaul facilities capture expanding brake disc replacement cycles as aging fleets extend service life through component refurbishment rather than airframe retirement. US-based MRO networks with FAA Part 145 certification dominate North American aftermarket volume.
- OEMs:Original equipment manufacturers specify integrated wheel-and-brake kits on new aircraft deliveries, consolidating supplier tiers and locking in long-term aftermarket service agreements.
- Airlines:Legacy carriers with in-house engineering capabilities maintain direct procurement relationships for unscheduled brake replacements.
- Leasing Companies:Aircraft lessors increasingly specify brake system configurations at delivery to standardize maintenance costs across lessee transitions.
Transaction volume centers on MROs; contract consolidation is expanding most quickly among Leasing Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of carbon-carbon brake heat sinks concentrates in the United States and France, while consumption tilts toward Asia-Pacific fleet expansion hubs. OEM assembly plants and specialized composite manufacturing facilities anchor supply in established aerospace clusters. Demand follows narrowbody delivery schedules and MRO network density.
United States
FAA Part 25 certification mandates and narrowbody fleet renewal drive brake system procurement. The EPA's emerging PFAS restrictions on hydraulic fluids force formulation changes across domestic MRO networks. Wichita, Kansas and Phoenix, Arizona host integrated wheel-and-brake assembly facilities serving Boeing and Airbus platforms.
France
EASA CS-25 thermal performance standards and carbon-carbon manufacturing expertise position French suppliers for European-registered fleet upgrades. The EU F-Gas Regulation amendments target hydrofluorocarbon-based heat transfer fluids in brake cooling systems. Toulouse and Le Havre concentrate specialized heat sink production and landing gear integration facilities.
China
COMAC C919 deliveries and indigenous narrowbody programs create demand for qualified brake system suppliers meeting CAAC certification requirements. MIIT aerospace industrial policies prioritize domestic landing gear component capabilities. Shanghai and Xi'an host emerging MRO hubs expanding brake overhaul capacity for Asia-Pacific carriers.
India
IndiGo and Air India narrowbody expansion under the PLI scheme for aerospace components drives localized procurement opportunities. BIS quality standards and DGFT import substitution policies shape supplier qualification pathways. Bangalore and Hyderabad concentrate emerging MRO facilities seeking FAA Part 145 and EASA Part 145 dual certifications.
United Kingdom
Legacy MRO infrastructure and Rolls-Royce engine aftermarket networks sustain brake system refurbishment demand. The CAA maintains alignment with EASA certification standards post-Brexit while operating independent approval pathways. Derby and Bristol host specialized landing gear repair stations serving European and Middle Eastern operators.
Aircraft Wheels Brakes Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across integrated wheel-and-brake kit supply. Market structure tilts toward consolidation as OEMs bundle procurement under long-term service agreements. Three archetypes dominate: avionics-to-landing-gear integrators, carbon-carbon composite specialists, and hydraulic-systems diversifiers. Competitive moves center on electromechanical actuation transitions and aftermarket service contract consolidation.
Among diversified industrial conglomerates, Honeywell International Inc and RTX Corporation occupy positions spanning avionics through landing gear systems. Safran Group exemplifies the carbon-carbon manufacturing specialist archetype with concentrated heat sink capabilities. Parker-Hannifin Corporation represents hydraulic-systems players extending into electromechanical architectures. These three anchors illustrate how supplier portfolios align with the technology transitions reshaping procurement patterns.
| Leading Market Players |
|---|
| Honeywell International Inc |
| Safran Group |
| Parker-Hannifin Corporation |
| Collins Aerospace |
| Crane Aerospace & Electronics |
| RTX Corporation |
| Meggitt PLC |
| Liebherr-International AG |
| AAR Corp |
| Others |
Value Chain & Pricing Dynamics
EPA PFAS restrictions on hydraulic fluids and anti-corrosion coatings gate qualified supplier access and premium-tier pricing for carbon-carbon brake assemblies, concentrating procurement power with OEMs holding validated alternative formulations. This environmental mandate reshapes both material qualification timelines and the cost structure of compliant wheel-and-brake kits across FAA-regulated fleets.
Pricing Analysis
Margin tightening in steel brake configurations reflects carbon-carbon displacement across narrowbody platforms. Three-tier pricing structure across FAA-certified premium, EASA-aligned standard, and legacy economy levels differentiates procurement contracts, with certification grade and volume scale as primary drivers. Cost-down pressure on steel alternatives accelerates because operators prioritize extended mean time between overhaul specifications. Regional carriers and cargo converters exhibit highest price sensitivity; integrated kit buyers at major OEMs show least.
Supply Chain Analysis
Specialized carbon-carbon composite layup technician scarcity in Wichita, Kansas and Le Havre, France constrains heat sink production scaling. Aerospace-grade polyacrylonitrile precursor supply draws from Japanese and US chemical plants, with carbon fiber fabric and titanium forgings as critical inputs. Single-source vulnerability in Japanese precursor allocation exposes manufacturers to capacity crunches. Distribution runs through FAA Part 145 and EASA Part 145 certified MRO networks serving airline and lessor fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-carbon manufacturing capacity bottlenecks prop pricing power for qualified suppliers, with thermal analysis engineering talent scarcity extending lead times for new entrant certification. This supply-constrained structure favors incumbents with established EASA and FAA regulatory relationships.
For Market Incumbents: Cement long-term aftermarket service agreements with lessors standardizing brake configurations across lease transitions. Lock in polyacrylonitrile precursor allocation contracts with Japanese suppliers to defend against raw material concentration risk. Prioritize electromechanical actuation R&D to capture value migrating from hydraulic specialists on next-generation platforms. For New Entrants and Emerging Players: India's PLI scheme for aerospace components opens a window for localized MRO facilities seeking dual FAA-EASA certification to serve IndiGo and Air India narrowbody expansion. Target brake disc refurbishment cycles at US-based Part 145 networks as the most penetrable aftermarket entry point. Pursue partnership-based qualification pathways with established OEMs to bypass 18-36 month EASA CS-25 certification barriers. For Investors and Strategic Acquirers: Electromechanical brake architecture adoption on A320neo and 737 MAX deliveries is the leading indicator that hydraulic-to-electric transition value pools are materializing. Focus acquisition screening on electromechanical control specialists and carbon-carbon composite manufacturers with thermal modeling capabilities. Watch for EPA PFAS restriction enforcement dates as signals of formulation innovation licensing opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Electromechanical Actuation Development | Unifies power distribution and control electronics to replace discrete hydraulic lines on next-generation narrowbody platforms. |
| Carbon-Carbon Manufacturing Scale-Up | Automated layup processes in Wichita and Le Havre achieve cost parity with steel alternatives through reduced cycle times. |
| Integrated Wheel-and-Brake Kit Procurement | Compresses supplier tiers by bundling initial equipment, scheduled overhaul, and unscheduled repair under fixed per-landing fees. |
| PFAS-Free Formulation Investment | Positions first-movers to patent and license alternative hydraulic fluids and anti-corrosion coatings across aftermarket channels. |
| Dual Certification MRO Expansion | Bangalore and Hyderabad facilities seek FAA Part 145 and EASA Part 145 credentials to capture India fleet modernization demand. |
Study Parameters
Multi-period observation of FAA airworthiness directive issuance, EASA certification timeline data, and carbon fiber precursor allocation patterns anchored the trend analysis, supplemented by interviews with brake system engineering directors, MRO procurement managers, airline fleet planning executives, and thermal analysis specialists. Secondary validation drew from FAA Part 25 and EASA CS-25 regulatory filings, EPA emerging substance restriction notices, customs trade data on aerospace-grade carbon fiber imports, and SEC 10-K disclosures from diversified landing gear suppliers. Bottom-up unit demand modeling triangulated against top-down fleet expansion projections from aircraft manufacturer delivery schedules.
Segment-weighting across product type, application, material system, and end-user channel structured the analytical framework across the projection horizon. Modeled dimensions included composite versus steel brake configurations, narrowbody versus widebody platform classifications, and OEM versus MRO procurement channels. CAGRs derived from fleet age distribution analysis, brake replacement cycle frequency, and thermal mandate compliance upgrade rates. Industry-specific inputs incorporated rejected takeoff energy absorption specifications and mean time between overhaul benchmarks by operator utilization intensity.
Caveats apply where EASA F-Gas Regulation amendment implementation timing, Japanese polyacrylonitrile plant capacity allocation decisions, or electromechanical architecture certification delays could materially shift the outlook. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Cables Market
Aircraft
Aviation Crew Management System Market
Aircraft
Aircraft Door Market
Aircraft
North America Aviation Market
Aircraft
GCC Business Jet Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Water Bomber Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Electric Aircraft Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
US Military Aviation Market
Aircraft
Light Electric Aircraft Market
Aircraft
Aerospace Turbojet Market
Aircraft
Commercial Aircraft Fadec Market