
 Helicopter Lighting Market | 2026-2036
Helicopter Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Lighting Market Outlook
Market Dynamics
Aftermarket service revenue is narrowing toward LED retrofit and modular upgrade kits as operators phase out legacy incandescent systems. Collins Aerospace leverages its integrated avionics platform to bundle lighting with flight-control upgrades across military and civil segments. Honeywell International Inc. anchors its position through FAA-certified repair stations that control channel access for domestic rotorcraft operators. Whelen Engineering Company, Inc. specializes in strobe and anti-collision systems for emergency medical services fleets.
Technology and Segmentation
Helicopter lighting encompasses illumination systems engineered to FAA and EASA photometric standards, with LED arrays now dominating new installations due to lower draw on aircraft electrical buses and extended mean-time-between-failures exceeding ten thousand hours. External lights and navigation lights command the largest share of product-type revenue as regulatory visibility mandates apply universally across civil and military fleets. LED technology displaces halogen across retrofit programs where operators prioritize weight reduction and thermal management in constrained airframe spaces.
Regulatory Environment
FAA airworthiness directives and EASA CS-29 certification requirements govern anti-collision, position, and landing-light performance, forcing manufacturers to maintain dual-approval testing protocols for transatlantic market access. MIL-STD-3009 and DEF-STAN 00-970 shape military procurement specifications in the United States and the United Kingdom, respectively, with compliance serving as a gatekeeper to defense contracts. Stakeholders must monitor evolving night-vision-goggle compatibility standards and emerging urban air mobility certification pathways that will redefine lighting architecture for next-generation rotorcraft platforms.
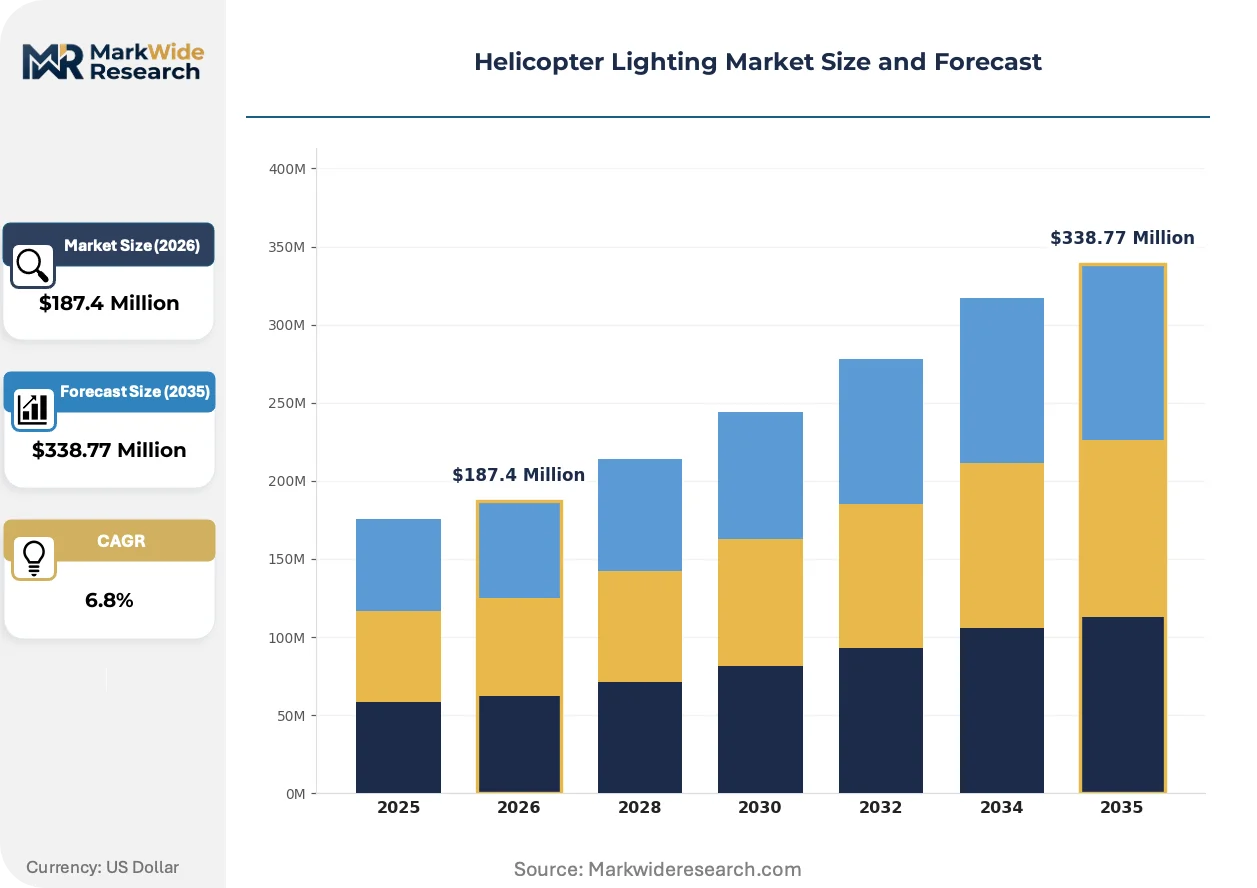
Market Dynamics
LED retrofit mandates from FAA airworthiness directives are compressing replacement cycles across military and emergency services fleets, forcing operators to accelerate capital deployment toward solid-state illumination architectures.
Growth Catalysts
- FAA Airworthiness Directives:Regulatory mandates for anti-collision and position lighting compliance are compelling fleet-wide LED upgrades across aging rotorcraft platforms in the United States.
- MIL-STD-3009 Night-Vision Compatibility:Military procurement specifications requiring NVG-compatible cockpit and external lighting are standardizing infrared-suppressed LED arrays across defense operators.
- Emergency Medical Services Fleet Expansion:Air ambulance operators in Germany and Japan are retrofitting high-intensity strobe systems to meet expanded night-flight authorization requirements.
Market Restraints
- Aviation-Grade Semiconductor Supply Concentration:High-reliability LED driver ICs depend on a limited supplier base concentrated in East Asian foundries, creating single-source vulnerability.
- Dual-Certification Cost Burden:Simultaneous FAA and EASA testing protocols for photometric compliance add 40-60% to qualification timelines versus single-jurisdiction approval.
- Thermal Management Material Costs:Aerospace-grade aluminum-nitride substrates and phase-change thermal interface materials face price volatility tied to rare earth processing capacity.
Strategic Opportunities
- Urban Air Mobility Certification Pathways:Emerging eVTOL platforms under FAA SC-VTOL and EASA SC-VTOL special conditions will require novel distributed lighting architectures without precedent in conventional rotorcraft.
- Modular Upgrade Kit Distribution:Direct-to-operator e-commerce channels for FAA-PMA lighting components are bypassing traditional MRO intermediaries in the United States civil market.
- Japan Defense Modernization:METI-funded indigenous rotorcraft development programs are creating captive demand for domestic lighting system integration.
Industry Challenges
- Photometric Test Engineer Scarcity:Qualified specialists capable of executing FAA-accepted light distribution measurements remain concentrated at a handful of certified laboratories, creating bottlenecks.
- Legacy 28VDC Bus Integration:LED retrofit kits must maintain compatibility with aging aircraft electrical architectures designed for incandescent load profiles, complicating power conditioning design.
- Intellectual Property Fragmentation:Patent thickets around optical lens geometries and thermal management architectures complicate clean-sheet product development for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Lighting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Internal Lights, External Lights, Navigation Lights, Search Lights Technology: LED, Xenon, Halogen, Incandescent End User: Civil Aviation, Military, Emergency Services, Private Operators Installation Type: Fixed, Modular, Portable, Retrofit |
| Companies Covered | Collins Aerospace, Luminator Technology Group, Aero Dynamix, Inc., Precise Flight, Inc., Oxley Group, Astronics Corporation, Honeywell International Inc., Whelen Engineering Company, Inc., Cobham plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Lighting Market Strategic Shifts
Photometric performance requirements are converging with power electronics miniaturization to reshape how lighting systems integrate with airframe architectures and mission equipment.
Chip-on-board LED arrays with integrated phosphor conversion are collapsing the physical separation between emitter and optic in landing and searchlight applications. Military operators in the United States are fielding these packages to eliminate filament fragility in high-vibration environments. The resulting form-factor reduction is collapsing available space claims in constrained nose and tail installations, enabling multi-sensor payload integration previously impossible.
EASA CS-29 Amendment 7 photometric standards are tightening angular intensity distribution tolerances for anti-collision lighting. Manufacturers must now demonstrate compliance across expanded temperature and vibration envelopes before European type certification. Civil operators in Germany are responding by consolidating procurement specifications to pre-qualified platform-agnostic lighting suites.
Aftermarket service unbundling is separating hardware supply from installation labor and ongoing airworthiness support. Emergency medical services fleets in Japan are contracting directly with component PMA holders while retaining independent MRO relationships for physical mounting and electrical integration. This bifurcation is most pronounced in HEMS segments where operational tempo demands rapid turnaround without OEM channel dependency.
Helicopter Lighting Market Segmentation
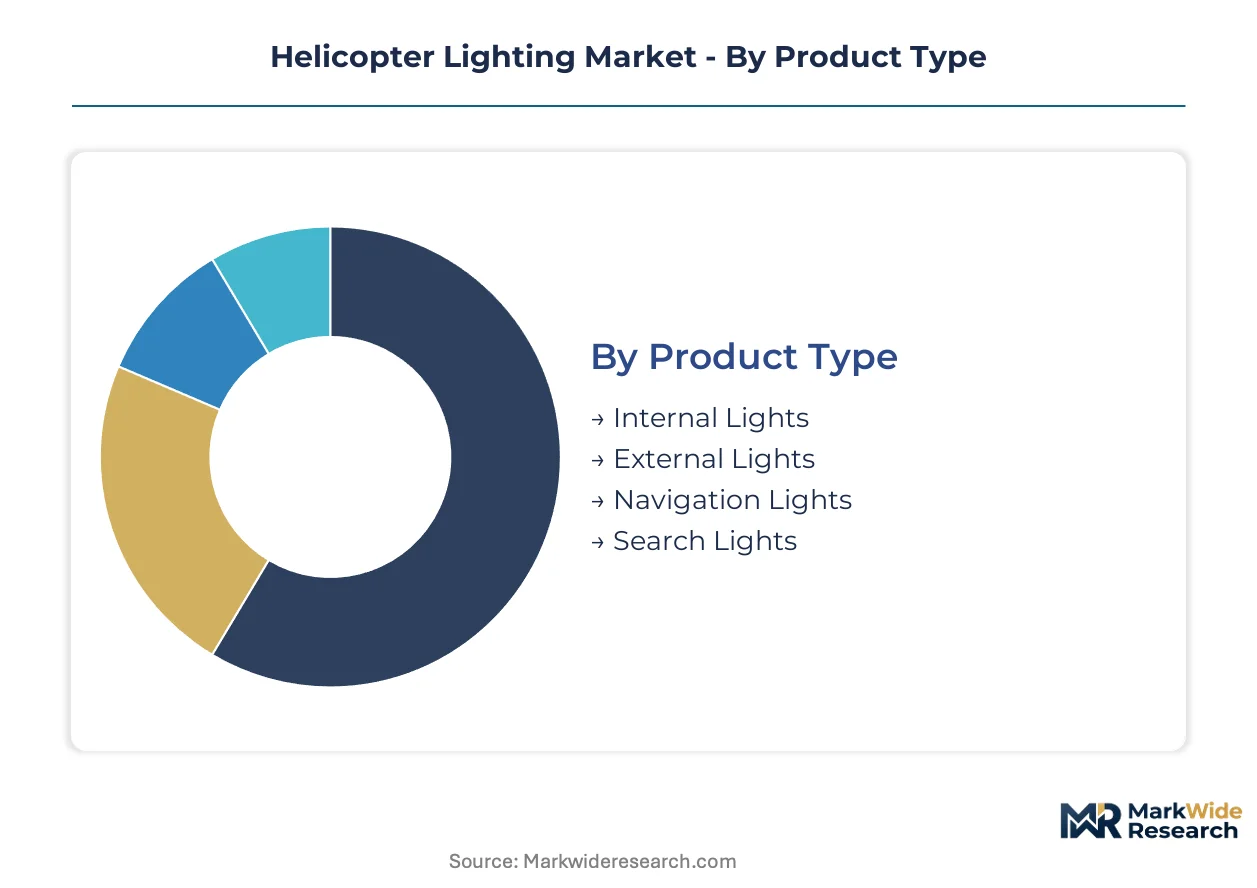
Helicopter lighting segmentation reflects divergent technical requirements across mission profiles, regulatory jurisdictions, and airframe generations. Product architecture, illumination technology, and installation methodology each create distinct procurement patterns and aftermarket service opportunities.
Product Type:
The use-case spectrum spans cockpit ergonomics, external visibility compliance, and mission-specific illumination for search and rescue operations.
- External Lights:Anti-collision strobes and position lights engineered to FAA and EASA photometric standards dominate fleet-wide retrofit programs. Demand concentrates in United States military rotorcraft depots where MIL-STD-3009 compliance mandates infrared-suppressed LED arrays for night-vision compatibility.
- Navigation Lights:Red, green, and white position lighting systems required for civil airworthiness certification across all operational categories. German emergency medical services operators are consolidating procurement around platform-agnostic lighting suites to streamline multi-type fleet maintenance.
- Internal Lights:Cockpit and cabin illumination systems optimized for pilot visual acuity and passenger safety during night operations.
- Search Lights:High-intensity directional beams for search and rescue, law enforcement, and offshore utility missions.
Established volume favors External Lights; emerging adoption favors Search Lights as night-flight authorizations expand in emergency services segments.
Technology:
Cost tier stratification separates premium solid-state architectures from legacy filament systems nearing obsolescence.
- LED:Solid-state arrays with mean-time-between-failures exceeding ten thousand hours and reduced electrical bus draw. United States defense operators are accelerating fleet-wide retrofits as FAA airworthiness directives compress replacement cycles for aging incandescent installations.
- Halogen:Tungsten-halogen lamps remaining in service on legacy platforms where thermal management constraints preclude LED retrofit. Japanese domestic rotorcraft manufacturers maintain limited procurement for indigenous defense programs with extended platform lifecycles.
- Xenon:High-intensity discharge systems for searchlight applications requiring extreme luminous output.
- Incandescent:Filament-based illumination approaching phase-out across regulated aviation segments.
Technology migration concentrates procurement spend in LED; regulatory pressure is displacing incandescent and halogen across certified aviation operations.
End User:
Customer type determines specification stringency, with defense and emergency services imposing the most demanding certification requirements.
- Military:Night-vision-goggle-compatible lighting systems governed by MIL-STD-3009 procurement specifications. United States Army and Navy rotorcraft depots are driving aftermarket demand for infrared-suppressed LED retrofit kits across aging UH-60 and AH-64 platforms.
- Emergency Services:Air ambulance and search-and-rescue operators requiring high-intensity strobes and landing lights for expanded night-flight operations. German HEMS fleets are retrofitting anti-collision systems to meet tightened EASA CS-29 Amendment 7 photometric standards.
- Civil Aviation:Commercial rotorcraft operators subject to FAA and EASA visibility mandate compliance.
- Private Operators:Corporate and personal rotorcraft with flexible specification requirements and extended replacement intervals.
Military procurement anchors technology development investment; Emergency Services represents the steepest expansion trajectory as air ambulance fleet utilization intensifies.
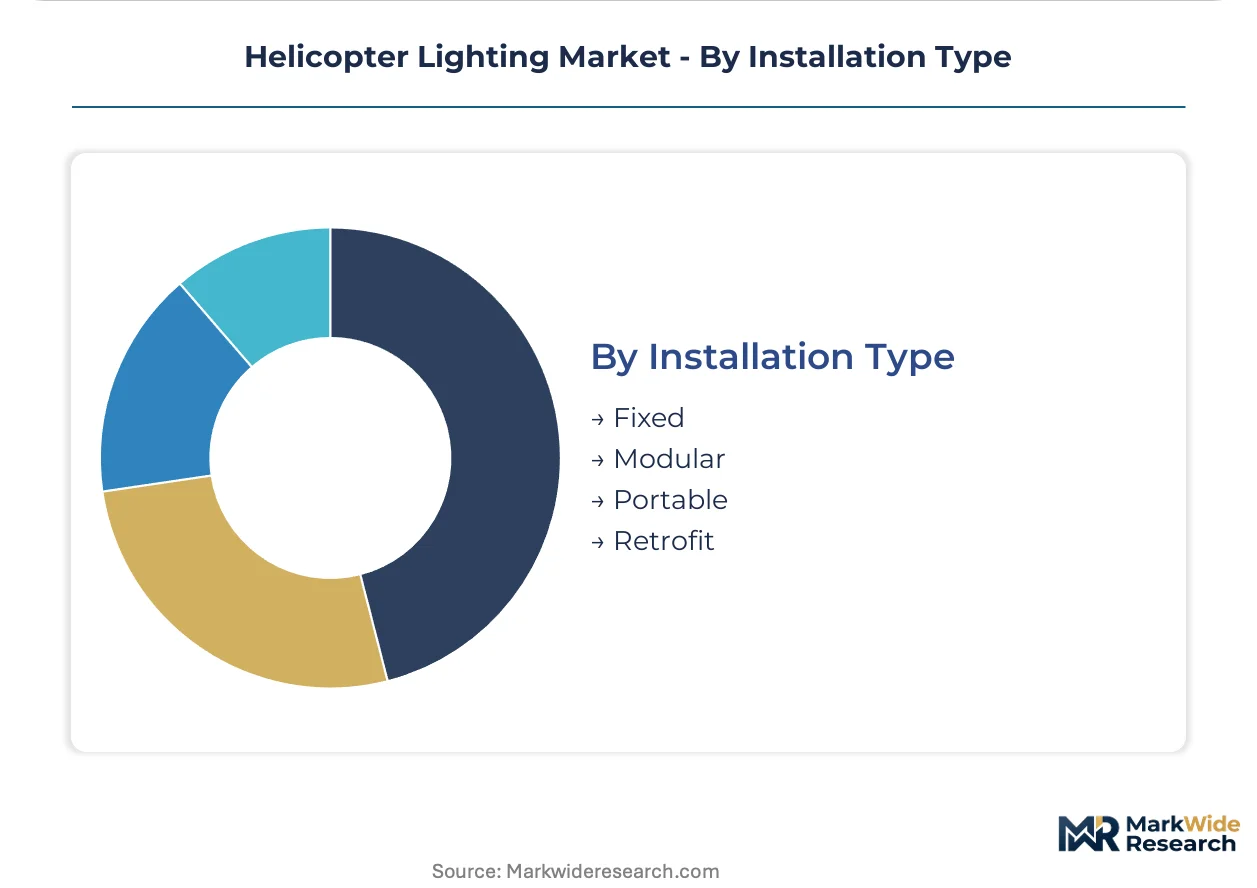
Installation Type:
Supply concentration in certified repair stations shapes channel access and operator procurement flexibility.
- Retrofit:LED upgrade kits and modular replacement systems for legacy airframes with incumbent incandescent or halogen installations. United States civil operators are bypassing traditional MRO intermediaries through direct-to-operator e-commerce channels for FAA-PMA lighting components.
- Modular:Platform-agnostic lighting suites enabling rapid field replacement and standardized inventory across mixed fleets. Japanese defense modernization programs are specifying modular architectures for indigenous rotorcraft development to reduce lifecycle logistics burden.
- Fixed:Permanent integrated installations specified for new-production airframes.
- Portable:Temporary or mission-configurable lighting for specialized operations and ground support.
Retrofit installation captures current aftermarket volume; modular architectures are gaining share fastest as fleet operators prioritize logistics standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized aerospace lighting suppliers cluster near defense procurement centers and established rotorcraft manufacturing hubs. FAA, EASA, and MIL-STD certification requirements create geographic stickiness as manufacturers co-locate with testing laboratories and military depot networks.
United States
Army and Navy rotorcraft depots drive aftermarket LED retrofit demand for aging UH-60 and AH-64 platforms. FAA airworthiness directives mandate anti-collision lighting compliance across civil and military fleets. Connecticut and Iowa host concentrated strobe and anti-collision system manufacturers serving domestic emergency medical services operators.
Germany
EASA CS-29 Amendment 7 photometric standards tighten angular intensity tolerances for anti-collision systems on HEMS fleets. The country's national aviation regulator enforces expanded temperature and vibration envelope testing before European type certification. Bavaria anchors platform-agnostic lighting suite procurement for consolidated multi-type fleet maintenance.
Japan
METI-funded indigenous rotorcraft development programs generate captive demand for domestic lighting system integration. Defense modernization budgets prioritize modular architectures to reduce lifecycle logistics burden. Nagoya and Tokyo metropolitan areas concentrate avionics integration specialists serving both civil and military operators.
United Kingdom
DEF-STAN 00-970 shapes military procurement specifications with compliance serving as gatekeeper to defense contracts. The national aviation authority maintains dual-approval testing protocols aligned with EASA standards. South West England hosts night-vision-goggle compatibility testing facilities for infrared-suppressed LED arrays.
France
EASA certification requirements govern anti-collision and position lighting performance for civil rotorcraft operators. The national military procurement agency specifies NVG-compatible cockpit illumination for combat helicopter fleets. Toulouse and Paris-Saclay clusters concentrate photometric engineering expertise for transatlantic market access.
Helicopter Lighting Market Competitive Environment
Diversified aerospace conglomerates and specialized lighting manufacturers split the market along certification depth and application focus. Tier-one suppliers leverage integrated avionics platforms to bundle lighting with broader system upgrades. Three archetypes dominate: full-service avionics integrators, component specialists with PMA authority, and defense-focused NVG compatibility experts. Competitive moves center on modular upgrade kit distribution and direct-to-operator e-commerce channel development.
Among diversified aerospace conglomerates, Collins Aerospace and Honeywell International Inc. occupy positions spanning civil and military segments with integrated platform offerings. Whelen Engineering Company, Inc. exemplifies the component specialist archetype with focused strobe and anti-collision system expertise. These three anchors illustrate how certification breadth and application depth determine competitive positioning in regulated aviation supply chains.
| Leading Market Players |
|---|
| Collins Aerospace |
| Luminator Technology Group |
| Aero Dynamix, Inc. |
| Precise Flight, Inc. |
| Oxley Group |
| Astronics Corporation |
| Honeywell International Inc. |
| Whelen Engineering Company, Inc. |
| Cobham plc |
| Others |
Value Chain & Pricing Dynamics
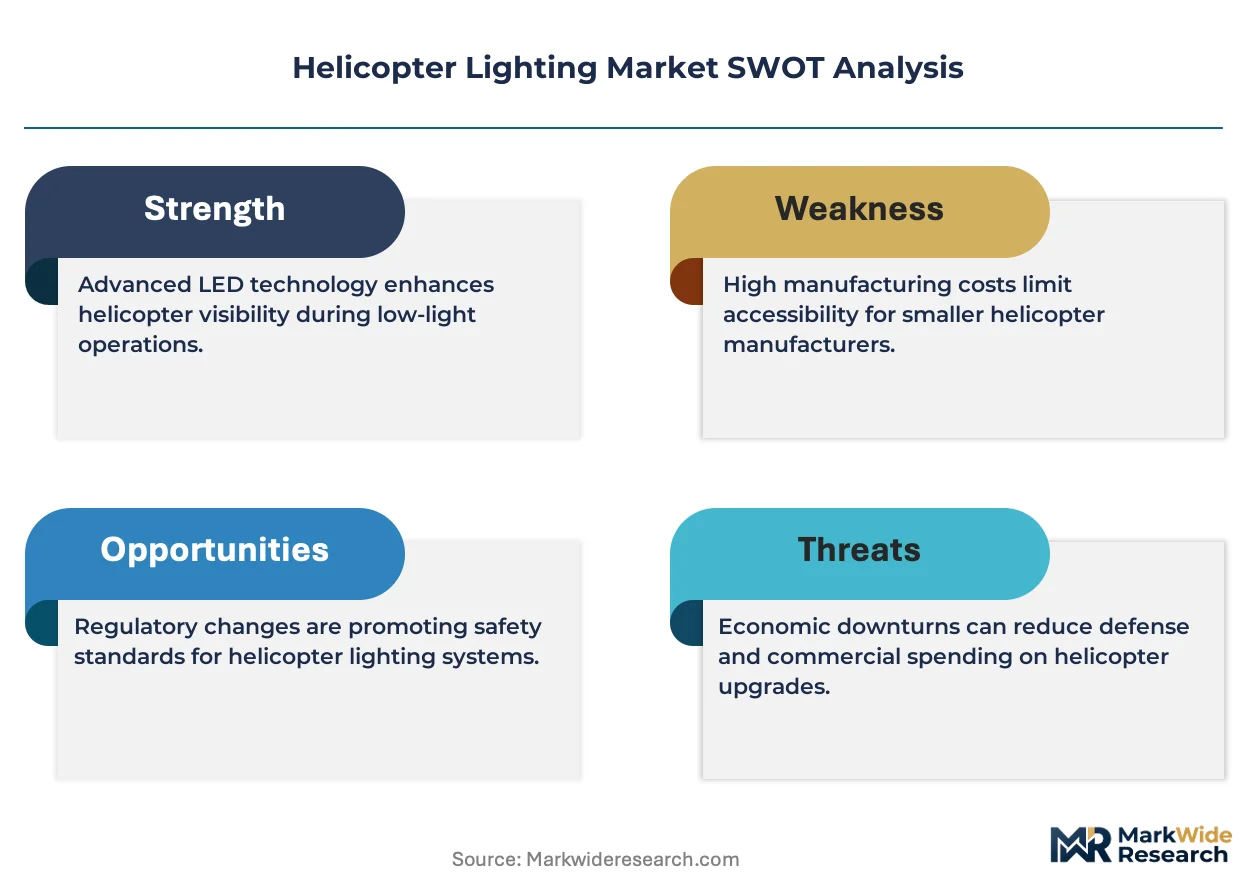
Single-source dependency on East Asian foundries for high-reliability LED driver ICs compresses both pricing tier spreads and supply chain resilience across military and civil rotorcraft lighting procurement. FAA and EASA dual-certification requirements compound cost structures while concentrating supplier power among certified manufacturers with transatlantic testing capabilities.
Pricing Analysis
FAA airworthiness directives dictate the pricing tier structure across helicopter lighting procurement, separating MIL-STD-3009 certified military systems from standard civil aviation offerings. Three-tier pricing structure across premium NVG-compatible, standard FAA-compliant, and economy non-certified tiers reflects certification depth and thermal management material grades. Cost compression in economy tiers is intensifying because Japanese and German operators are consolidating procurement around platform-agnostic modular suites. Emergency medical services fleets exhibit highest price sensitivity due to rapid fleet turnover demands, while United States defense depots prioritize performance over unit economics.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk planning for aerospace-grade aluminum-nitride substrates and phosphor conversion materials. Manufacturing concentrates in Japan, Germany, and the United States for final assembly and photometric testing, while raw material processing draws from Chinese rare earth facilities and Taiwanese semiconductor foundries. Single-source vulnerability persists for aviation-grade LED driver ICs. Distribution runs through FAA-certified repair stations and direct-to-operator e-commerce channels for PMA components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helicopter lighting market is entering a cyclical recovery phase as FAA airworthiness directives force fleet-wide LED retrofits across aging military and emergency services platforms. Defense modernization budgets in Japan and sustained HEMS fleet expansion in Germany provide durable demand anchors.
For Market Incumbents: Pre-empt modular architecture standardization by acquiring PMA-certified component specialists before platform-agnostic procurement consolidates channel control. Lock in exclusive repair station relationships with United States Army and Navy rotorcraft depots to defend against direct-to-operator e-commerce disruption. Invest in dual FAA-EASA testing capacity to capture transatlantic certification premiums as EASA CS-29 Amendment 7 tightens photometric tolerances. For New Entrants and Emerging Players: Urban air mobility eVTOL lighting architectures under FAA SC-VTOL special conditions represent the most penetrable entry point given absence of incumbent legacy platform lock-in. Japanese METI-funded indigenous rotorcraft programs offer second-mover advantage through domestic integration partnerships absent entrenched foreign supplier relationships. Pursue night-vision-goggle compatibility certification as differentiated positioning against general aviation lighting commoditization. For Investors and Strategic Acquirers: Component specialists with PMA authority and established FAA repair station networks command scarcity premia in a market bifurcating between integrated avionics bundles and unbundled aftermarket hardware. Long-term viability hinges on exposure to defense procurement cycles and emergency services fleet replacement waves rather than civil aviation cyclicality. Monitor EASA CS-29 Amendment 7 implementation timelines as inflection indicator for European aftermarket consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NVG-Compatible LED Retrofit Certification | MIL-STD-3009 compliance opens United States Army and Navy depot contracts to qualified suppliers. |
| Dual FAA-EASA Testing Capacity Expansion | Simultaneous transatlantic approval slashes qualification timelines for platform-agnostic lighting suites. |
| Direct-to-Operator E-Commerce Channel | FAA-PMA component sales bypass traditional MRO intermediaries in United States civil markets. |
| Modular Upgrade Kit Standardization | Platform-agnostic architectures reduce inventory burden for German HEMS multi-type fleet operators. |
| eVTOL Distributed Lighting Development | FAA SC-VTOL special conditions require novel architectures without conventional rotorcraft precedent. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with rotorcraft fleet managers, FAA-certified repair station engineers, military procurement officers, and photometric test laboratory specialists. Secondary validation drew from FAA airworthiness directive filings, EASA certification databases, MIL-STD-3009 specification documents, and defense budget appropriation records. Bottom-up segment sizing triangulated against top-down market reconstruction across product type, technology, end user, and installation methodology dimensions.
Calibration against historical retrofit cycle timing and regulatory implementation lags anchored the analytical framework across the projection horizon. Segmentation modeling spanned illumination technology, product architecture, customer type, and geographic regulatory cluster. CAGRs were derived from installed base age profiles, replacement cycle compression factors, and emerging platform adoption curves. Forecast inputs incorporated night-vision-goggle compatibility mandate expansion and urban air mobility certification pathway development.
Practitioners should monitor East Asian semiconductor foundry capacity allocation and rare earth processing export restrictions for early signals of supply constraint propagation. Forecasts reflect assumptions regarding sustained FAA enforcement of anti-collision lighting directives and stable defense procurement appropriations in Japan and the United States. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Supersonic Jet Market
Aircraft
Firefighting Aircraft Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
US Aircraft Windshield Wiper and Washer System Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Aircraft Mounts Market
Aircraft
Tanker Aircraft Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Wind Tunnel Market
Aircraft
Air Deflector Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
GCC Business Jet Market