
 Aircraft Window Frame Market | 2026-2036
Aircraft Window Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Window Frame Market Analysis
Aerospace composites engineering talent scarcity is reorganizing supplier hierarchies across the aircraft window frame value chain. GKN Aerospace leverages captive thermoplastic processing expertise to sustain European OEM relationships. Spirit AeroSystems anchors North American narrowbody programs through integrated fuselage-window assemblies. PPG Industries differentiates via proprietary transparency-to-frame bonding systems that control aftermarket replacement cycles.
Aircraft window frames are structural boundary components that seal pressurized cabin environments, typically machined from 7075-T6 aluminum or fabricated from carbon fiber-reinforced thermoplastics to achieve specific strength-to-weight ratios and fatigue resistance under cyclic pressurization loads. Composite product types are capturing expanded share as Boeing 787 and Airbus A350 programs normalize non-metallic fuselage architectures, though aluminum retains maturity in narrowbody retrofit channels. Commercial aviation applications dominate absolute volume, while military aviation segments concentrate margin pools through low-rate, high-specification programs requiring electromagnetic interference shielding.
FAA airworthiness standards and EASA CS-25 certification frameworks govern structural integrity, flammability, and bird-strike resistance requirements that dictate material selection and testing protocols. EPA REACH-aligned substance restrictions in Europe and evolving FAA directives on cabin safety margins are compressing qualification timelines for new frame designs. Stakeholders must monitor OEM platform rate decisions and regulatory harmonization progress between FAA and EASA to anticipate capacity allocation and certification investment requirements.
Market Dynamics
Narrowbody fleet renewal programs at Boeing and Airbus are compressing qualification timelines for lightweight frame assemblies while FAA airworthiness directives on cabin pressurization integrity force material recertification investments across the supply base.
Growth Catalysts
- Composite Material Transition:Carbon fiber-reinforced thermoplastics are displacing 7075-T6 aluminum in next-generation fuselage architectures as Boeing 787 and Airbus A350 programs normalize non-metallic structural designs.
- FAA Certification Pressure:Airworthiness directives on cabin pressurization integrity are accelerating material testing protocols and creating replacement demand for legacy aluminum frame inventories.
- Narrowbody Production Surge:United States-based OEM final assembly lines are anchoring procurement volumes for integrated fuselage-window assemblies across single-aisle commercial programs.
Market Restraints
- Aerospace Composites Talent Scarcity:Thermoplastic processing expertise concentrates at a handful of European and North American suppliers, limiting supplier base expansion and compressing margins for second-tier fabricators.
- Aluminum Price Volatility:7075-T6 alloy input costs fluctuate with aerospace-grade aluminum supply constraints, squeezing profitability for retrofit channel manufacturers dependent on metallic legacy designs.
- REACH-Aligned Substance Restrictions:EPA and ECHA chemical compliance frameworks are extending qualification timelines for new bonding agents and surface treatments used in frame-to-transparency assemblies.
Strategic Opportunities
- Aftermarket Transparency Bonding Systems:Proprietary adhesive technologies that control replacement cycle timing present margin expansion potential for component suppliers serving airline maintenance operations.
- Military Electromagnetic Shielding Specifications:Low-rate, high-specification defense programs requiring EMI-resistant frame architectures offer pricing power unavailable in commercial volume production.
- EASA-FAA Regulatory Harmonization:Converging certification standards between European and US regulators could reduce duplicate testing costs for suppliers serving dual-jurisdiction OEM customers.
Industry Challenges
- Fatigue Testing Bottlenecks:Cyclic pressurization load validation under CS-25 and FAA Part 25 frameworks consumes extended calendar time, delaying new design market entry.
- Integrated Assembly Complexity:Fuselage-window module consolidation by tier-one suppliers is compressing independent frame manufacturer addressable market scope.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Window Frame Market |
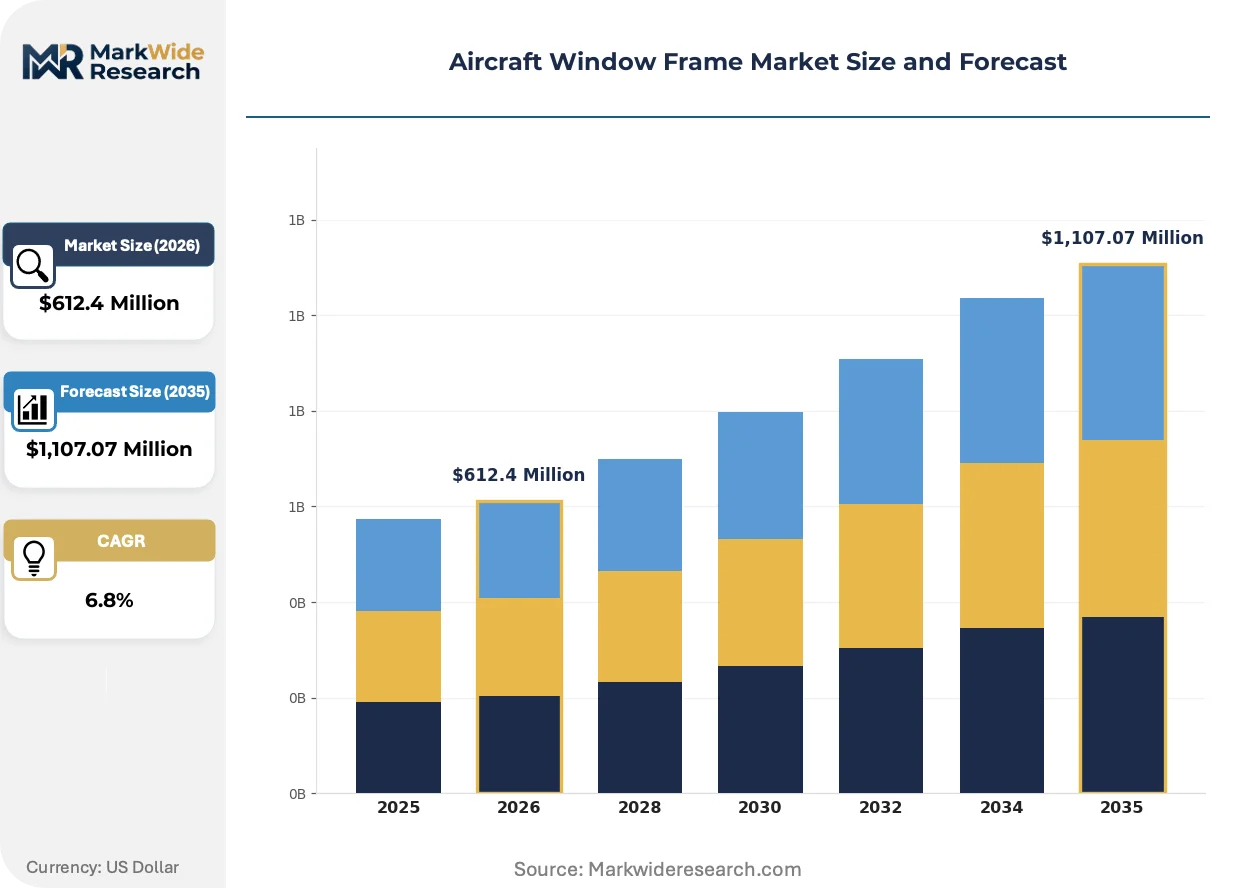
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Composite, Plastic, Steel Application: Commercial Aviation, Military Aviation, General Aviation, Cargo Aviation Installation Type: OEM, Aftermarket, Retrofit, Replacement End User: Aerospace Manufacturers, Maintenance Providers, Aircraft Operators, Aviation Authorities |
| Companies Covered | GKN Aerospace, PPG Industries, Inc., Spirit AeroSystems, ACE Advanced Composite Engineering GmbH, LMI Aerospace, SIFCO Industries Inc., The Nordam Group LLC, Collins Aerospace, Otto Fuchs KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Window Frame Market Emerging Trajectories
Material science advances and regulatory convergence are restructuring competitive advantage around thermoplastic processing capabilities and bonded assembly expertise rather than traditional machining scale.
Thermoplastic composite window frames are fragmenting established aluminum supply relationships as Airbus A350 and Boeing 787 derivative programs expand non-metallic fuselage content. Tier-one aerostructures suppliers with captive composite processing lines are capturing expanded procurement share from legacy machined-component specialists. This technology diffusion is compressing addressable market scope for standalone aluminum frame manufacturers while elevating qualification barriers for new thermoplastic entrants.
EASA CS-25 certification updates on structural integrity and flammability are forcing material substitution decisions across European narrowbody retrofit channels. Airlines operating mixed fleets must maintain dual inventory positions or accelerate aluminum-to-composite transition schedules. The regulatory friction most severely impacts regional carriers with limited engineering resources to manage parallel certification compliance.
Airline procurement departments are consolidating window frame purchasing through long-term fuselage assembly contracts rather than discrete component sourcing. Independent frame manufacturers face channel displacement as Spirit AeroSystems and GKN Aerospace bundle structural modules into single-supplier agreements. This concentration is most advanced in North American narrowbody production, where Boeing's tier-one restructuring has eliminated multi-source component procurement for new-build aircraft.
Aircraft Window Frame Market Segmentation
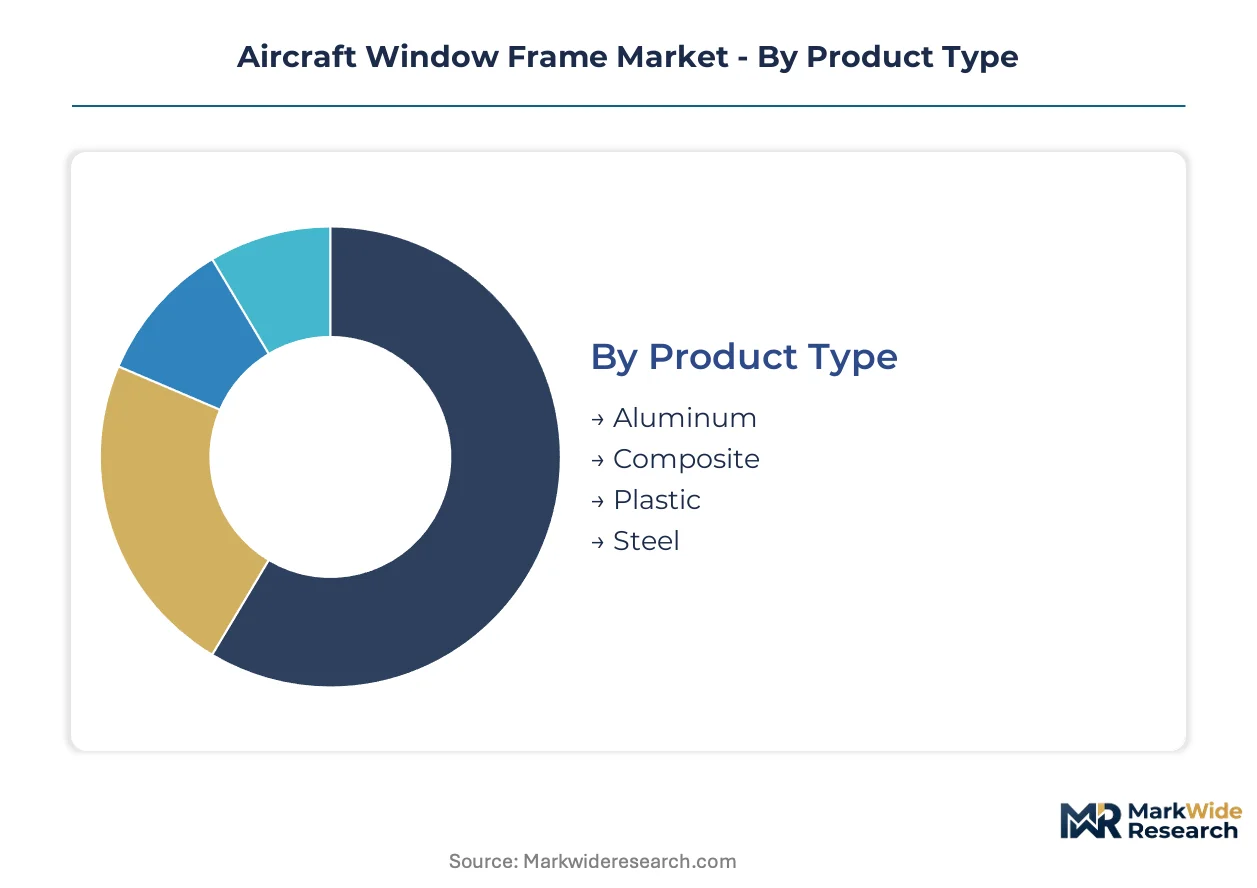
Segmentation in aircraft window frames reveals how material chemistry, regulatory jurisdiction, and procurement channel structure allocate margin pools across the value chain. Each dimension exposes distinct competitive barriers and customer concentration patterns that reshape supplier positioning.
Product Type:
Channel flow diverges sharply: composite and aluminum frames move through tier-one fuselage integrators to OEM assembly lines, while plastic and steel variants serve fragmented aftermarket distributors and military MRO depots.
- Aluminum:7075-T6 alloy dominates narrowbody retrofit channels where FAA airworthiness directives on pressurization integrity sustain replacement demand. United States-based maintenance providers anchor procurement volumes for legacy fleet support, though thermoplastic substitution compresses long-term growth.
- Composite:Carbon fiber-reinforced thermoplastics flow through Spirit AeroSystems and GKN Aerospace to Boeing 787 and Airbus A350 final assembly. Boeing's tier-one restructuring has consolidated composite frame sourcing under integrated fuselage contracts, elevating qualification barriers for standalone suppliers.
- Plastic:Polycarbonate and acrylic derivatives serve general aviation and interior partition applications where load-bearing requirements are minimal.
- Steel:Corrosion-resistant alloys concentrate in military cargo platforms requiring electromagnetic interference shielding under MIL-STD specifications.
By volume, aluminum leads. By growth pace, composite is expanding most quickly.
Application:
Cost tier stratification separates commercial volume production from military premium pricing, with general aviation occupying a mid-tier characterized by distributor fragmentation.
- Commercial Aviation:Narrowbody and widebody programs at Boeing and Airbus drive absolute frame consumption, with procurement consolidating through long-term fuselage assembly contracts rather than discrete component orders.
- Military Aviation:Low-rate, high-specification programs for fighter and surveillance platforms command pricing power through EMI-resistant architectures and bird-strike hardening requirements.
- General Aviation:Business jet and turboprop manufacturers source through fragmented supplier networks with shorter qualification cycles.
- Cargo Aviation:Freighter conversion programs at Israel Aerospace Industries and ST Engineering generate episodic demand for reinforced frame assemblies.
Commercial aviation generates the highest absolute revenue. Military aviation captures the steepest margin premiums per unit.
Installation Type:
Customer type determines contract structure: OEM channels demand multi-year supply agreements with embedded R&D cost recovery, while aftermarket and retrofit transactions favor spot purchasing with compressed lead times.
- OEM:Boeing and Airbus final assembly lines in the United States, France, and Germany anchor procurement through tier-one aerostructures suppliers. Spirit AeroSystems bundles window frames into integrated fuselage modules, displacing independent component sourcing.
- Aftermarket:Airline maintenance operations source replacement frames through PMA-certified distributors, with PPG Industries controlling transparency-to-frame bonding systems that influence replacement cycle timing.
- Retrofit:Narrowbody fleet renewal programs compress qualification timelines for lightweight frame assemblies as carriers accelerate aluminum-to-composite transitions.
- Replacement:Unscheduled demand from fatigue failures or bird-strike damage flows through AOG logistics channels with premium pricing.
OEM commands the largest revenue pool. Aftermarket offers the most attractive margin expansion potential for proprietary bonding technology holders.
End User:
Supply concentration varies by procurement sophistication: aerospace manufacturers consolidate through tier-one integrators, while maintenance providers and aircraft operators fragment across distributor networks.
- Aerospace Manufacturers:Boeing, Airbus, and Embraer specify frame architectures through design authority contracts that lock in suppliers for program durations spanning decades.
- Maintenance Providers:Lufthansa Technik, ST Engineering, and AAR Corp. manage dual inventory positions for mixed fleets under EASA and FAA jurisdiction, extending qualification timelines for new designs.
- Aircraft Operators:Delta Air Lines, United Airlines, and Air France-KLM consolidate purchasing through airframe OEM service agreements, reducing direct component procurement.
- Aviation Authorities:FAA and EASA certification requirements dictate material testing protocols and flammability standards that frame suppliers must satisfy before market entry.
Aerospace manufacturers concentrate the highest procurement volumes. Aviation authorities exert the most decisive influence on supplier qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes aircraft window frames primarily through integrated fuselage contracts, while European procurement fragments across national aerospace clusters and Asian demand concentrates in Japanese precision manufacturing and Chinese emerging capacity.
United States
Narrowbody production lines at Boeing's Renton and Charleston facilities anchor procurement volumes for composite and aluminum frame assemblies. FAA airworthiness directives on cabin pressurization integrity sustain replacement demand across legacy fleets. Wichita, Kansas hosts Spirit AeroSystems' integrated fuselage operations, consolidating window frame sourcing under single-supplier agreements.
Germany
Airbus Hamburg final assembly drives demand for thermoplastic composite frames across A320 and A350 programs. EASA CS-25 certification requirements govern structural integrity testing protocols for European-registered aircraft. Bavaria's aerospace corridor around Munich hosts specialized suppliers serving both commercial and defense programs.
France
Airbus Toulouse operations normalize carbon fiber-reinforced fuselage architectures across widebody platforms. REACH-aligned substance restrictions from ECHA compress qualification timelines for new bonding agents and surface treatments. The Occitanie region concentrates thermoplastic processing expertise for next-generation frame designs.
United Kingdom
GKN Aerospace's Western operations sustain European OEM relationships through captive composite manufacturing capabilities. The country's aerospace regulator aligns with EASA certification frameworks while maintaining distinct national approval pathways. Bristol and the Southwest England cluster specialize in advanced materials engineering for window frame applications.
Japan
Boeing 787 supply chain participation drives precision machining demand for metallic frame components and subassemblies. METI industrial policy supports aerospace composites capability development through targeted R&D subsidies. The Chubu region around Nagoya hosts tier-two suppliers integrated into global OEM procurement networks.
Aircraft Window Frame Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive structure. Tier-one aerostructures suppliers with captive thermoplastic processing lines capture expanded procurement share from legacy machined-component specialists. Three archetypes dominate: integrated fuselage module suppliers, standalone composite frame fabricators, and aluminum retrofit specialists. Consolidation through long-term OEM design authority contracts and strategic partnerships for composite technology licensing represent the dominant competitive moves reshaping supplier hierarchies.
Among European-integrated specialists, GKN Aerospace and Otto Fuchs KG exemplify the tier-one archetype with established OEM relationships, while Spirit AeroSystems anchors North American narrowbody programs through bundled structural modules. These three occupy positions that reflect the market's bifurcation between integrated fuselage suppliers and standalone component fabricators.
| Leading Market Players |
|---|
| GKN Aerospace |
| PPG Industries, Inc. |
| Spirit AeroSystems |
| ACE Advanced Composite Engineering GmbH |
| LMI Aerospace |
| SIFCO Industries Inc. |
| The Nordam Group LLC |
| Collins Aerospace |
| Otto Fuchs KG |
| Others |
Supply Flow & Price Mechanics
Long-term fuselage assembly contracts lock in composite frame supply for Boeing and Airbus while anchoring price visibility across multi-year OEM procurement cycles. This contract structure compresses spot-market participation for standalone aluminum frame manufacturers facing 7075-T6 alloy cost volatility.
Pricing Analysis
Project-based pricing for integrated fuselage-window modules dominates OEM channels, with cost differentiation driven by thermoplastic certification grade and volume scale across narrowbody programs. Cost compression in aluminum retrofit tiers is intensifying because legacy fleet replacement demand concentrates among price-sensitive regional carriers. Military EMI-hardened specifications command the steepest premiums, while aftermarket PMA distributors exhibit the highest price sensitivity.
Supply Chain Analysis
Inbound logistics costs from aerospace-grade aluminum smelters in Russia and China feed into 7075-T6 alloy pricing volatility for metallic frame fabricators. Raw material dependencies center on carbon fiber prepregs from Japan, thermoplastic resins from Germany, and specialty coatings from the United States. Single-source vulnerability concentrates in thermoplastic processing equipment where European suppliers control qualification-critical machinery. Distribution runs through tier-one aerostructures integrators bundling frames into fuselage modules for final assembly delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aircraft window frame demand sits in early-cycle expansion as Boeing 787 and Airbus A350 derivative programs normalize non-metallic fuselage architectures and compress aluminum-to-composite transition timelines.
For Market Incumbents: Shield composite processing margins by securing captive thermoplastic resin supply agreements before aerospace-grade polymer shortages deepen. Accelerate FAA-EASA dual certification investments to preempt regulatory divergence costs as Spirit AeroSystems and GKN Aerospace consolidate integrated fuselage procurement.
For New Entrants and Emerging Players: Aftermarket transparency bonding services represent the most penetrable white-space where PPG Industries maintains near-exclusive control over replacement cycle timing. Target military EMI-shielding specifications for fighter and surveillance platforms where low-rate production tolerates higher supplier qualification costs and pricing power remains intact.
For Investors and Strategic Acquirers: Capital is best deployed toward tier-two composite fabricators with established Boeing or Airbus design authority relationships but lacking integrated fuselage bundling capabilities. Thermoplastic processing talent scarcity signals long-term viability for specialists with qualified engineering benches. Watch Boeing's tier-one restructuring pace as the inflection indicator for independent frame manufacturer addressable market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Processing Capacity Expansion | Captive composite lines at Spirit AeroSystems and GKN Aerospace lock in Boeing and Airbus sourcing. |
| FAA-EASA Dual Certification Investment | Harmonized CS-25 and Part 25 approvals reduce duplicate testing costs for cross-jurisdiction suppliers. |
| Proprietary Bonding Agent Development | PPG Industries controls aftermarket replacement cycles through transparency-to-frame adhesive systems. |
| Military EMI Shielding Specialization | MIL-STD specifications for fighter platforms command pricing power unavailable in commercial volume. |
| Backward Integration into Resin Supply | Captive thermoplastic polymer sourcing insulates margins from aerospace-grade material shortages. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EASA CS-25 certification databases, and OEM procurement disclosures. Interviews with tier-one aerostructures procurement directors, composite processing engineers, airline maintenance planners, and regulatory compliance officers informed demand and qualification assessments. Secondary validation drew from customs trade records, SEC 10-K aerospace segment filings, and REACH substance restriction updates. Bottom-up frame consumption estimates triangulated against top-down OEM production rate projections.
Segmentation dimensions modeled include material chemistry, application category, installation channel, and geographic regulatory jurisdiction across the projection horizon. CAGRs derived from production rate trajectories at Boeing and Airbus final assembly lines, fleet renewal schedules, and composite substitution curves in narrowbody programs. Industry-specific inputs incorporated thermoplastic qualification timelines under FAA Part 25 and EASA CS-25 frameworks.
Forecasts assume regulatory continuity in FAA and EASA certification regimes; material policy shifts would require re-modeling. Cyclic pressurization fatigue testing bottlenecks, aluminum alloy supply disruptions, or OEM tier-one restructuring acceleration could compress or extend projected adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Global Commercial Aircraft Disassembly Market
Aircraft
Aircraft Elevator Market
Aircraft
Aeronautic Propeller Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
Europe Freighter Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Aircraft Control Surface Market
Aircraft
Europe Attack Helicopter Market