
 M2M Satellite Communication Market | 2026-2036
M2M Satellite Communication Market Size, Share, and Industry Trends Forecast 2026-2036
M2M Satellite Communication Market Intelligence
The expansion of ground station infrastructure in Australia and South America is reconfiguring service delivery for M2M satellite communication. This shift enables lower latency connections for critical applications. Iridium Communications Inc. leverages its established LEO constellation for global pole-to-pole coverage. Viasat Inc. competes by offering high-throughput services in specific high-demand corridors.
M2M satellite communication involves the automated transmission of small data packets between remote devices over satellite networks, bypassing terrestrial infrastructure. These systems typically operate in the L-band or Ku/Ka-bands to connect assets in areas with no cellular coverage. Low Earth Orbit (LEO) technology is gaining share over traditional Geostationary (GEO) systems due to lower latency. Within applications, asset tracking and remote monitoring for logistics and energy sectors constitute the largest and most mature use cases.
Regulatory frameworks from bodies like the U.S. Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT) govern spectrum allocation and terminal certification. These regulations directly impact market entry and the operational footprint of service providers. Consequently, end-user decisions will increasingly balance service cost against the reliability and latency offered by competing LEO and GEO network architectures.
Market Dynamics
The central dynamic shaping the M2M satellite communication market is the architectural competition between incumbent Geostationary (GEO) networks and challenger Low Earth Orbit (LEO) constellations. This rivalry is reconfiguring cost structures, service capabilities, and market access for end-users in remote connectivity applications.
Growth Catalysts
- LEO Constellation Deployment:The proliferation of LEO satellite networks expands service availability and lowers latency, enabling real-time asset tracking for agriculture and mining operations in vast, remote territories like Australia and Canada.
- Logistics Sector Demand:Logistics and transportation companies require uninterrupted connectivity for fleet management and supply chain visibility, driving adoption of satellite M2M to fill coverage gaps left by terrestrial cellular networks.
- Spectrum Allocation Policies:Regulatory bodies, including the U.S. FCC, are streamlining the allocation of spectrum and licensing for new satellite systems, which lowers barriers to entry and fosters competition among service providers.
Market Restraints
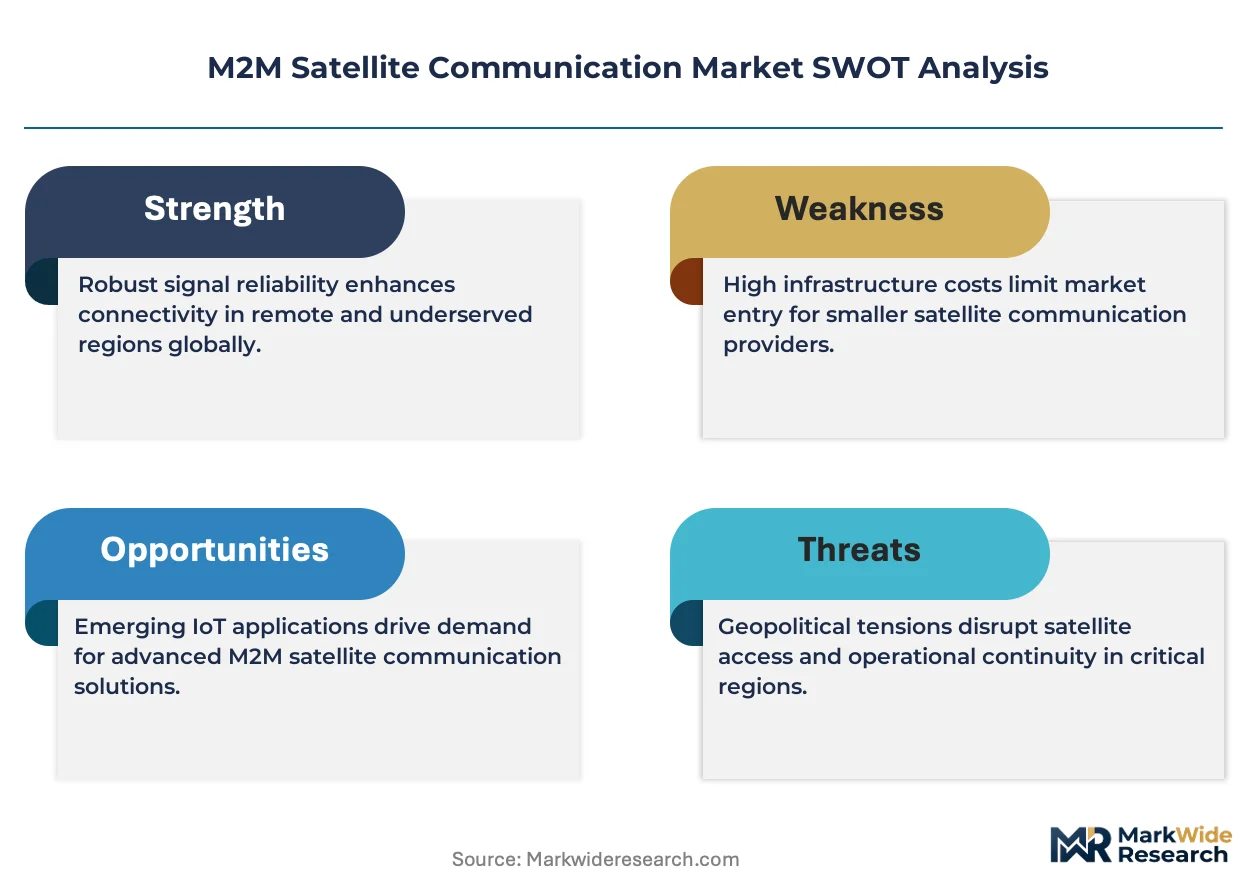
- High Terminal and Service Costs:The upfront cost of satellite terminals and the recurring subscription fees remain significantly higher than cellular alternatives, limiting adoption to use cases where no other connectivity option exists.
- Network Latency Differences:While LEO systems offer improvement, the inherent latency of satellite communication, especially with older GEO systems, makes it unsuitable for certain time-critical industrial control applications compared to fiber or 5G.
- Fragmented Regulatory Approvals:Service providers face complex and lengthy approval processes to secure landing rights and spectrum access in each country, slowing the rollout of seamless global services and increasing operational overhead.
Strategic Opportunities
- Direct-to-Device Connectivity:Integrating satellite connectivity directly into standard smartphones and IoT chips presents a major opportunity to expand the market beyond specialized terminals for emergency messaging and low-bandwidth data.
- Maritime and Aviation Expansion:There is significant potential in providing M2M services for vessel monitoring, safety systems, and aircraft telemetry in underserved regions like the South China Sea and across the Indian Ocean.
- IoT and AI Integration:Combining satellite M2M data with AI-powered analytics platforms enables the development of high-value services like predictive maintenance for remote energy infrastructure and smart agriculture solutions.
Industry Challenges
- Legacy System Integration:End-users face significant technical hurdles and costs when attempting to integrate satellite M2M data streams with their existing enterprise software, such as ERP and proprietary fleet management systems.
- Capital Expenditure Intensity:The enormous cost of designing, manufacturing, launching, and operating a satellite constellation creates a formidable barrier to entry, concentrating the market among a few heavily capitalized players.
- Interoperability Standards:A lack of universal standards for M2M terminals and communication protocols can lead to vendor lock-in and prevent seamless roaming between different satellite networks, complicating procurement for global enterprises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | M2M Satellite Communication Market |
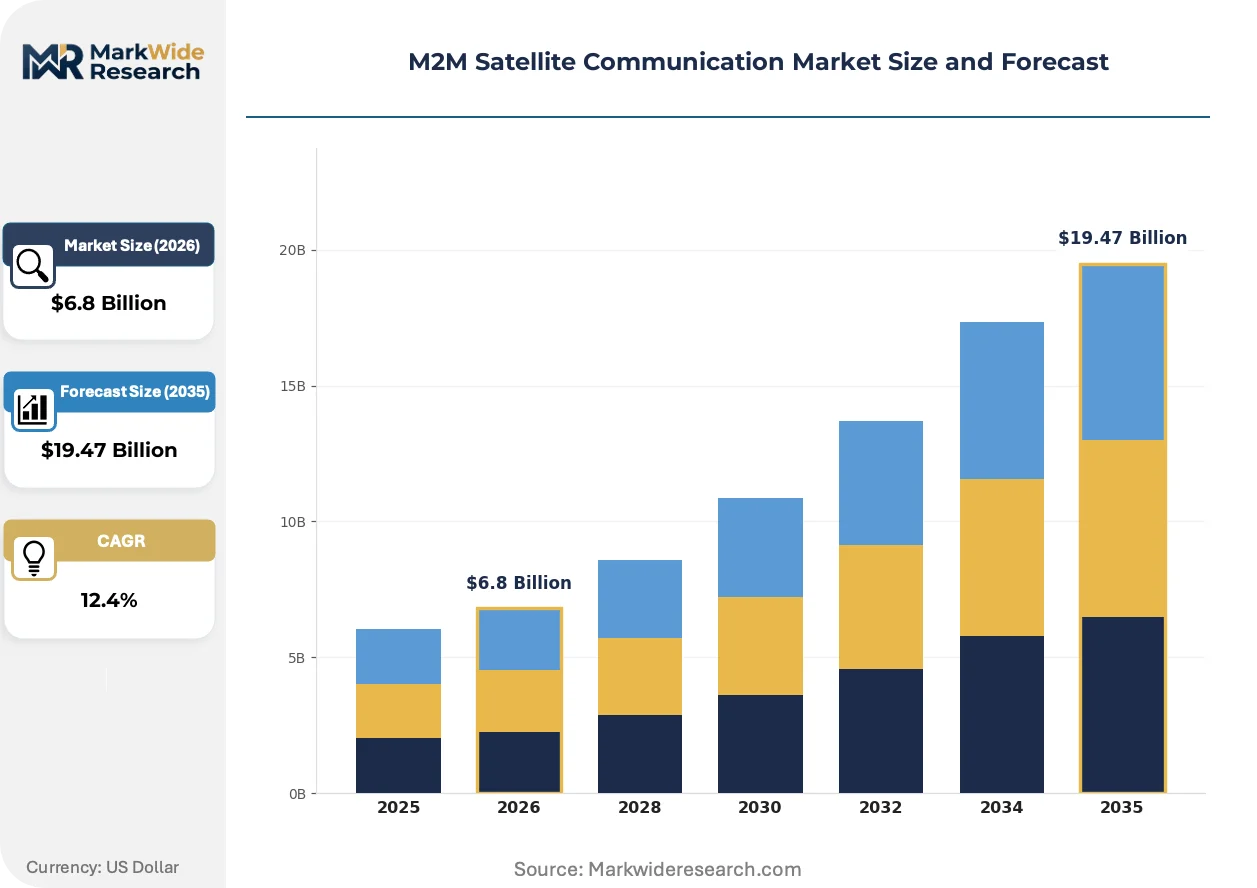
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Geostationary, Medium Earth Orbit, Low Earth Orbit, Highly Elliptical Orbit Application: Fleet Management, Asset Tracking, Remote Monitoring, Environmental Sensing End User: Logistics Providers, Maritime Operators, Agriculture Services, Emergency Responders Service Type: Data Transmission, Voice Communication, Telemetry, Broadband Access |
| Companies Covered | Iridium Communications Inc., Viasat Inc., Globalstar Inc., Inmarsat Global Limited, EchoStar Corporation, Gilat Satellite Networks, Honeywell International, Marlink, ORBCOMM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
M2M Satellite Communication Market Strategic Shifts & Innovations
The market is defined by a technological push toward smaller, more power-efficient hardware and a demand-side pull for more integrated, software-defined connectivity solutions. This evolution is enabling satellite M2M to address a wider array of use cases in remote and mobile environments.
Terminal hardware innovation focuses on miniaturization and power efficiency to connect battery-operated assets. Industries such as agriculture and environmental monitoring are rapidly adopting these devices for large-scale, low-touch sensor deployments in remote fields. The market for asset tracking hardware is migrating from bulky, power-intensive GEO-based terminals to compact, energy-efficient devices optimized for LEO networks, enabling longer field life and lower total cost of ownership.
Regulatory bodies like the International Telecommunication Union (ITU) are increasingly focused on policies for sustainable space utilization, including orbital debris mitigation. This trend imposes new satellite design and end-of-life de-orbiting requirements on constellation operators, directly impacting manufacturing costs and mission planning. The satellite manufacturing segment is most affected, now embedding de-orbiting capabilities and tracking compliance with frameworks that govern space traffic management.
End-users are shifting from purchasing raw data packets to procuring managed service contracts that bundle connectivity with hardware, data analytics, and platform access. This change disrupts the traditional airtime reseller model, compelling network operators to build or partner for end-to-end solution capabilities. This trend is most prominent in the global logistics and heavy equipment sectors, where customers demand turnkey asset visibility rather than discrete connectivity components.
M2M Satellite Communication Market Segmentation
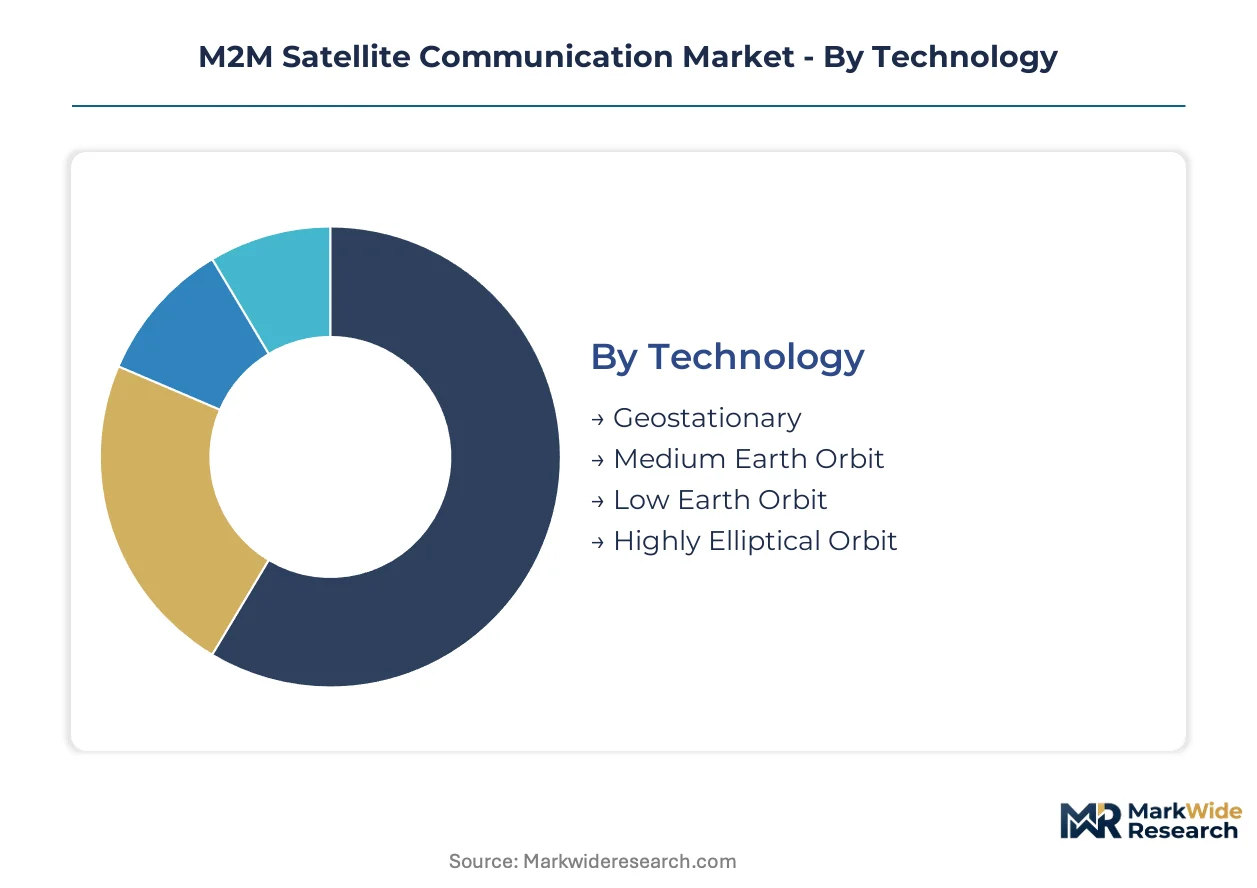
The M2M satellite communication market segments define distinct operational profiles and service requirements. Understanding these divisions helps service providers tailor solutions and optimize network resources for specific end-user needs. This segmentation clarifies where technological advancements and service delivery models will have the greatest impact on market expansion.
Technology:
The intensity of after-sales service requirements often varies significantly across different satellite technologies, influencing operational expenditures for both providers and end-users.
- Low Earth Orbit:LEO systems utilize numerous small satellites in orbits typically below 2,000 km, enabling significantly lower latency and global coverage for M2M devices. Demand concentrates in remote asset tracking for agriculture in Australia, where real-time data improves operational efficiency.
- Geostationary:GEO satellites operate in a fixed position relative to the Earth at approximately 35,786 km, providing wide coverage areas but with higher latency. This technology remains crucial for established maritime communication routes across the Indian Ocean, where continuous, broad-area coverage is prioritized over speed.
- Medium Earth Orbit:MEO constellations orbit between 2,000 km and 35,786 km, offering a balance between coverage area and latency compared to LEO and GEO systems. These systems find niche applications in specific governmental and defense communications requiring robust, secure links.
- Highly Elliptical Orbit:HEO systems use elongated elliptical paths, primarily to provide extended coverage over polar regions where GEO satellites are ineffective. This technology supports scientific research and specialized remote sensing missions in high-latitude territories.
By volume, Low Earth Orbit leads. By growth pace, Low Earth Orbit is ahead.
Application:
Application focus drives specific hardware and software requirements, directly affecting the complexity and cost of M2M satellite deployments for various industries.
- Asset Tracking:This application involves monitoring the location and status of mobile or stationary assets using satellite-enabled M2M devices. Mining operations in Canada extensively utilize asset tracking for equipment visibility and safety compliance in remote areas.
- Remote Monitoring:Remote monitoring focuses on collecting data from unattended sensors or equipment in isolated locations, often for predictive maintenance or environmental sensing. Energy companies deploy remote monitoring for pipeline integrity and wellhead performance across vast, unpopulated regions.
- Fleet Management:Fleet management leverages M2M satellite communication for vehicle tracking, route optimization, and driver behavior analysis in logistics and transportation sectors. This ensures continuous visibility for long-haul trucking fleets operating beyond cellular range.
- Environmental Sensing:Environmental sensing applications gather data on weather patterns, soil conditions, and water levels from remote sensors for climate research and agricultural planning. These systems support precision agriculture initiatives in large-scale farming areas.
The demand for Asset Tracking is driven by logistics needs, while Remote Monitoring addresses critical infrastructure oversight.
End User:
Different end-user segments exhibit unique procurement patterns and operational scales, influencing the commercial strategies of M2M satellite service providers.
- Logistics Providers:These companies require seamless, global connectivity for managing diverse fleets and supply chains, often integrating satellite M2M with existing enterprise resource planning systems. Logistics providers prioritize reliability and cost-effectiveness for tracking high-value cargo across continents.
- Agriculture Services:Agricultural businesses utilize M2M satellite communication for precision farming, livestock monitoring, and irrigation management in vast, rural areas lacking terrestrial infrastructure. This enables data-driven decisions for crop yield optimization and resource allocation in countries like Brazil.
- Maritime Operators:Shipping companies and offshore platforms depend on satellite M2M for vessel tracking, crew communication, and operational telemetry, particularly in international waters. This ensures safety and regulatory compliance for global maritime trade routes.
- Emergency Responders:Emergency services deploy satellite M2M for critical communication and data transmission during disaster relief operations or in areas with compromised terrestrial networks. These services provide essential connectivity for coordination and situational awareness in crisis zones.
Specific operational requirements dictate the selection of M2M solutions for Logistics Providers and Agriculture Services.
Service Type:
The type of service offered dictates the bandwidth requirements and data packet sizes, directly impacting satellite network design and pricing models for M2M applications.
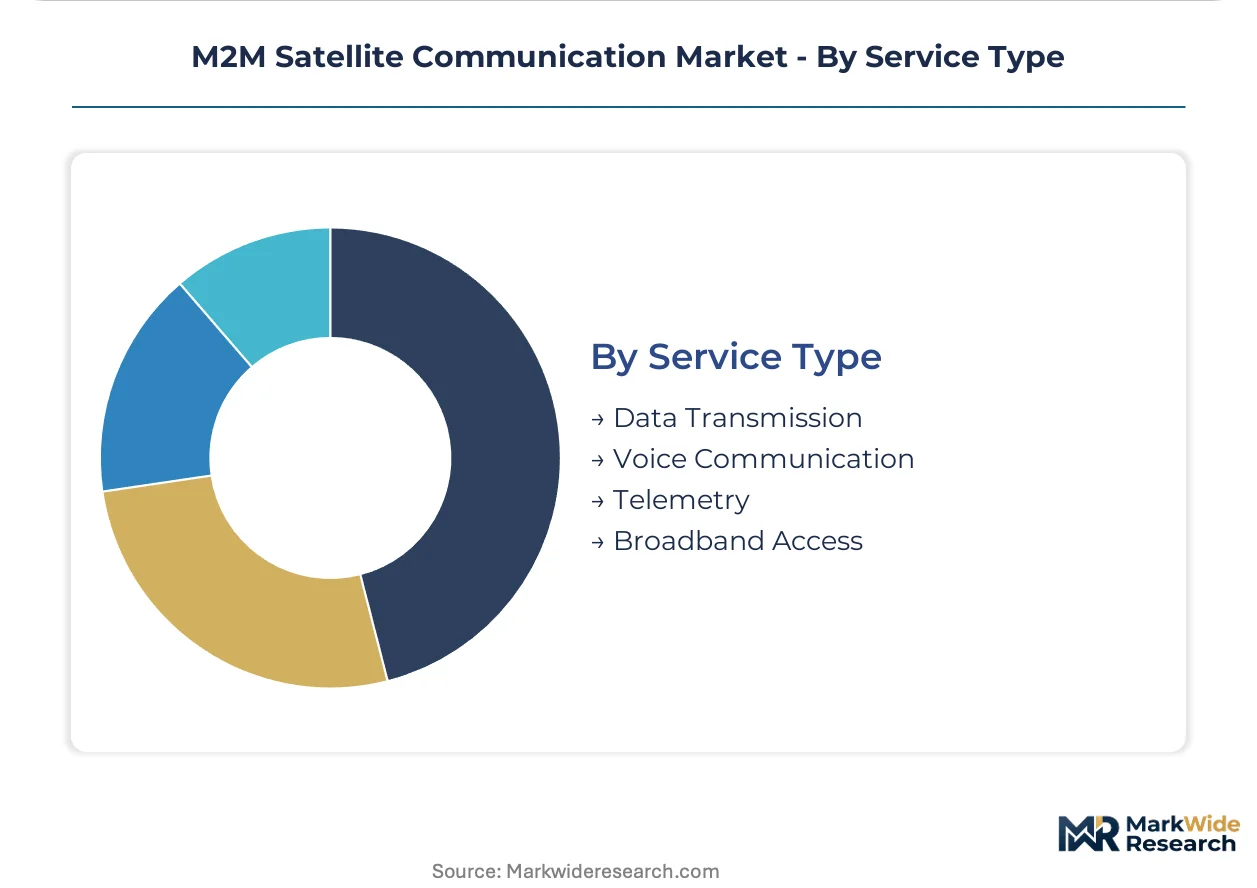
- Data Transmission:This service involves sending small, intermittent data packets from M2M devices to central monitoring stations, such as sensor readings or asset location updates. It forms the backbone of remote monitoring applications for industrial machinery and environmental sensors.
- Telemetry:Telemetry focuses on the automated measurement and transmission of data from remote instruments to receiving equipment for monitoring and analysis. This is essential for infrastructure management, like monitoring oil and gas pipelines or utility grids in remote areas.
- Voice Communication:While less common for pure M2M, voice communication services provide critical human-to-human interaction capabilities, often as a backup for emergency situations or field personnel support. This service is vital for maritime and remote field operations.
- Broadband Access:Broadband access provides higher bandwidth for more data-intensive applications, though less typical for traditional M2M, it supports remote offices or larger data transfers from specialized equipment. This enables more comprehensive data collection from remote scientific outposts.
While Data Transmission dominates in volume, Telemetry offers higher value per connection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Federal Communications Commission (FCC) significantly influences the global M2M satellite communication market through its spectrum allocation and licensing policies. These regulatory decisions often set precedents for other national bodies, shaping market entry and operational standards worldwide. Expanding ground station infrastructure further reconfigures service delivery for critical applications.
United States
Demand for M2M satellite communication in the United States stems from extensive logistics networks and remote energy infrastructure monitoring. The U.S. FCC's streamlined licensing for new satellite systems fosters competition among service providers. Silicon Valley and aerospace hubs like Seattle drive innovation in LEO constellation technology and ground segment solutions.
Australia
Australia's vast, remote territories create strong demand for M2M satellite communication in agriculture and mining. The national telecommunications regulator supports infrastructure expansion, including new ground stations. Perth and Brisbane serve as operational centers for resource companies leveraging satellite M2M for asset tracking and environmental sensing.
Canada
Canadian mining operations and remote logistics require M2M satellite communication for equipment visibility and safety compliance in challenging environments. Health Canada and other regulatory bodies ensure compliance for devices used in remote health monitoring. Alberta's energy sector and Ontario's logistics hubs are primary adopters of these satellite solutions.
Brazil
Brazilian agriculture services utilize M2M satellite communication for precision farming, livestock monitoring, and irrigation management across its expansive rural areas. ANVISA, Brazil's regulatory agency, approves communication devices for various industrial applications. São Paulo and Minas Gerais are key regions for agricultural technology integration and satellite connectivity deployment.
Germany
Germany's advanced manufacturing and logistics sectors drive demand for M2M satellite communication in supply chain visibility and fleet management. The Federal Network Agency (Bundesnetzagentur) regulates spectrum use and market access for satellite operators. Munich and Hamburg serve as centers for industrial IoT development and maritime logistics, respectively, integrating satellite M2M solutions.
M2M Satellite Communication Market Key Industry Players
Incumbent Geostationary (GEO) network operators and challenger Low Earth Orbit (LEO) constellation providers split the M2M satellite communication market. This rivalry reconfigures cost structures and service capabilities for end-users in remote connectivity. Strategic partnerships and technology licensing represent dominant competitive moves among these players.
Within the LEO constellation tier, Iridium Communications Inc. represents a well-established provider, offering global pole-to-pole coverage for M2M devices. Viasat Inc. exemplifies a high-throughput GEO satellite operator, occupying a position in specific high-demand corridors. Globalstar Inc. sits within the challenger LEO segment, focusing on low-bandwidth data and messaging services for remote asset tracking.
| Leading Market Players |
|---|
| Iridium Communications Inc. |
| Viasat Inc. |
| Globalstar Inc. |
| Inmarsat Global Limited |
| EchoStar Corporation |
| Gilat Satellite Networks |
| Honeywell International |
| Marlink |
| ORBCOMM |
| Others |
Cost & Logistics Intelligence
The South China Sea maritime corridor's cost dynamics directly influence M2M satellite service pricing. This reflects the concentrated supply of LEO satellite capacity and drives price differentiation for high-throughput services.
Pricing Analysis
Geographic price spreads for M2M satellite communication services vary significantly across regions like Australia and the Indian Ocean. The dominant pricing structure involves subscription-based tiered data plans, often bundled with hardware and managed services. Price differentiation stems from service reliability in remote areas and the specific latency requirements of critical applications. Pricing softness reflects the increasing competition from new LEO constellation deployments, particularly for low-bandwidth applications. Agriculture services in Brazil exhibit high price sensitivity, while maritime operators prioritize service continuity over marginal cost savings.
Supply Chain Analysis
U.S. export control regimes for satellite components significantly limit the global flow of advanced M2M communication hardware. Manufacturing of satellite components concentrates in the United States, China, and Europe. The industry relies heavily on specialized semiconductors, high-frequency transceivers, and radiation-hardened electronics. Single-source vulnerability for critical LEO satellite components presents a notable structural risk. Distribution runs through a network of specialized integrators and value-added resellers who bundle connectivity with customer solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The M2M satellite communication market presents a fragmentation opportunity, driven by the demand-side shift towards direct-to-device connectivity. This creates numerous niches for specialized services beyond traditional asset tracking.
For Market Incumbents: Build proprietary end-to-end service platforms to create customer stickiness and manage data analytics. Integrate LEO and GEO network capabilities to offer hybrid solutions, mitigating the threat from pure-play LEO providers. Invest heavily in ground station infrastructure in emerging markets like Brazil to enhance service delivery. Control over customer data and analytics serves as a key lever for long-term competitive advantage.
For New Entrants and Emerging Players: Establish a beachhead in direct-to-device connectivity for low-bandwidth emergency messaging. Target the underpenetrated environmental sensing application in remote agricultural areas like Canada. Focus on developing highly miniaturized, power-efficient terminals that offer a lower total cost of ownership. A go-to-market angle emphasizing integration with existing IoT platforms will accelerate adoption.
For Investors and Strategic Acquirers: Software-defined satellite network management platforms represent attractive acquisition targets for long-term viability over the next 5-10 years. These platforms enable flexible service provisioning and advanced data analytics, crucial for high-value services. Companies specializing in AI integration for predictive maintenance applications in remote energy infrastructure are also strategic. The signal to watch is the successful commercialization of direct-to-device satellite chipsets.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Hybrid LEO/GEO Solutions | Offers diverse connectivity options for logistics providers, balancing latency and coverage across global routes. |
| Invest in Direct-to-Device Chipsets | Expands market reach to standard smartphones and IoT devices, reducing hardware costs for end-users. |
| Acquire AI-Powered Analytics Firms | Enhances predictive maintenance capabilities for remote energy infrastructure, adding value beyond raw data. |
| Expand Ground Station Infrastructure | Reduces latency and improves service reliability for critical asset tracking in regions like Australia. |
| Standardize M2M Communication Protocols | Facilitates seamless roaming and interoperability between different satellite networks, benefiting global enterprises. |
Research Approach
A standing panel of satellite network engineers, logistics fleet managers, and agricultural technology specialists provided ongoing calibration for market insights. Primary interviews with industry stakeholders were validated against secondary data from ITU spectrum reports, FCC filings, and company financial disclosures. This approach ensured robust bottom-up and top-down triangulation of market figures.
Scenario-bracketing provided a robust analytical framework across the projection horizon, accounting for varying LEO deployment rates. The market was segmented by technology, application, end-user, and service type, alongside regional regulatory environments. Compound annual growth rates were derived through a weighted average of segment-specific expansion trajectories. Satellite launch schedules and remote asset deployment trends served as key forecast inputs.
Sensitivities concentrate around unforeseen regulatory changes and rapid technological obsolescence of existing satellite hardware. Forecasts reflect documented assumptions regarding spectrum allocation and LEO constellation build-out. Material shifts in global trade policies or major satellite launch failures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
China Satellite Connectivity Market
Satellite
India Satellite Communication Market
Satellite
Optical Satellite Communication Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Satellite Manufacturing Market
Satellite
Israel Satellite Communications Market
Satellite
South Korea Satellite Communication Market
Satellite
Japan Satellite Imagery Services Market
Satellite
Commercial LEO Satellite Market
Satellite
All-Electric Propulsion Satellites Market
Satellite
Japan Satellite-Based Earth Observation Market
Satellite
Satellite Communication Equipment Market
Satellite
Small Satellite Launch Market
Satellite
Middle East Satellite Communications Market
Satellite
Global Remote Sensing Services Market
Satellite
Canada Satellite Connectivity Market