
 Global Business Aircraft Market | 2026-2036
Global Business Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Global Business Aircraft Market Analysis
Sustainable propulsion architecture is rewriting how original equipment manufacturers configure airframes and powertrain integration. Bombardier leverages its Global family platform to sustain ultra-long-range positioning against Gulfstream Aerospace Corporation, which anchors super-midsize and large-cabin categories through the G700 program. Dassault Aviation differentiates via the Falcon trijet design philosophy and integrated digital flight control systems.
Business aircraft encompass fixed-wing turbine-powered platforms purpose-built for private, corporate, or government transport, typically featuring pressurized cabins, certified ceiling altitudes above 40,000 feet, and range capabilities from 1,500 to 7,500 nautical miles depending on segment class. Their primary commercial purpose centers on time arbitrage for executive travelers and specialized mission profiles including medical evacuation and priority cargo. Heavy jets concentrate the highest absolute margin pools due to unit economics and customization intensity, while light jets represent the fastest-growing delivery category as charter services and air taxi platforms scale fleet standardization. Turboprop variants retain structural importance in secondary airport networks where runway length and operating cost thresholds exclude jet alternatives.
The Federal Aviation Administration administers type certification and operational standards under Part 135 and Part 91 frameworks, while the European Union Aviation Safety Agency enforces CS-25 certification requirements and emissions monitoring protocols that shape product development timelines and market access conditions. The International Civil Aviation Organization's carbon offsetting and reduction scheme progressively tightens compliance obligations for international operations. Stakeholders must monitor sustainable aviation fuel infrastructure deployment rates and evolving bilateral airworthiness agreements between the FAA and emerging certification authorities.
Market Dynamics
Sustainable aviation fuel mandates from the European Union and the Federal Aviation Administration are compressing product development cycles while forcing powertrain architecture decisions that will determine competitive positioning for the next decade.
Growth Catalysts
- SAF Blending Mandates:The European Union's ReFuelEU Aviation regulation requires escalating sustainable aviation fuel percentages at EU airports, creating procurement pull for compatible airframes.
- Fractional Ownership Models:Corporate travelers increasingly favor asset-light access arrangements over full ownership, expanding addressable demand for charter fleet operators.
- Hub-and-Spoke Inefficiencies:Commercial airline schedule rigidity at secondary U.S. airports sustains premium on business aircraft time arbitrage for executive travel.
Market Restraints
- SAF Supply Constraints:Production capacity for certified sustainable aviation fuel remains concentrated in limited geographies, creating feedstock cost volatility for operators.
- Airframe Development Costs:Clean-sheet certification programs require capital intensity that excludes all but established original equipment manufacturers from platform innovation.
- Pilot Availability:Training pipeline limitations for type-rated flight crew create operational ceiling constraints for fleet expansion at charter services.
Strategic Opportunities
- Urban Air Mobility Integration:Electric vertical take-off and landing platforms at metropolitan vertiports offer first-last-mile connectivity that extends business aircraft utility.
- Medical Evacuation Specialization:Dedicated air ambulance configurations address aging demographics in Japan and Switzerland where ground infrastructure gaps persist.
- CSRD Disclosure Requirements:The European Union's Corporate Sustainability Reporting Directive creates competitive differentiation for operators with verified emissions transparency.
Industry Challenges
- Flight Control Software Certification:Integrated digital avionics systems face extended validation timelines under FAA and EASA updated software assurance protocols.
- Specialized MRO Talent:Composite airframe repair expertise and next-generation powertrain maintenance skills concentrate at limited service centers, creating geographic bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Business Aircraft Market |
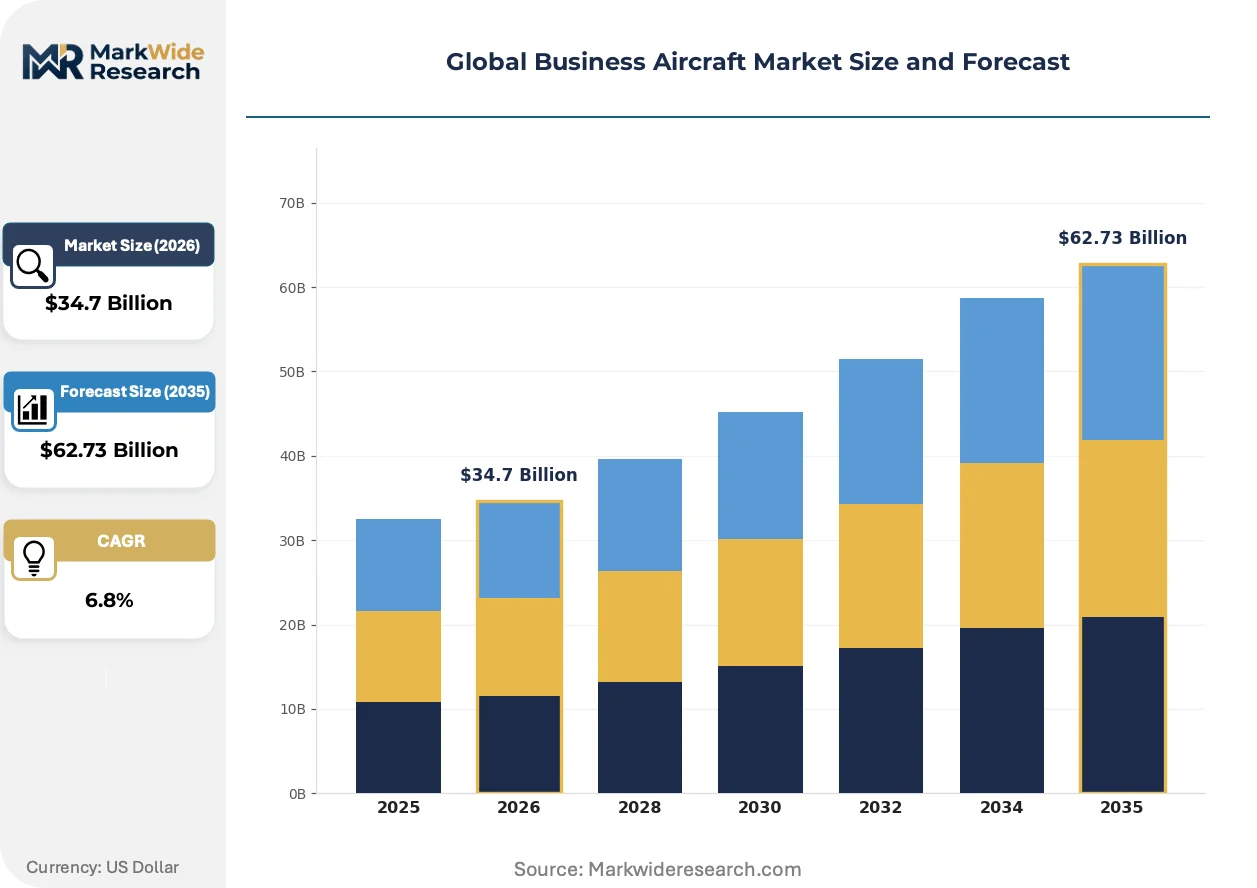
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $62.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Jet, Mid-size Jet, Heavy Jet, Turboprop End User: Corporate, Charter Services, Government, Private Owners Application: Executive Travel, Cargo Transport, Medical Evacuations, Air Taxi Service Type: Sales, Leasing, Maintenance, Management |
| Companies Covered | Bombardier, Dassault Aviation, Gulfstream Aerospace Corporation, Textron Aviation, Embraer, Airbus, Boeing, HondaJet, Cessna, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Business Aircraft Market Emerging Trajectories
Digital engineering workflows are compressing development timelines while regulatory pressure on emissions intensifies competition between propulsion architectures. Three forces are actively restructuring how value is created and captured.
Digital twin technology is virtualizing airframe design validation and maintenance prediction. Original equipment manufacturers deploy virtual environments to simulate structural load performance and systems integration before physical prototyping. Fleet operators adopt predictive maintenance platforms that model component degradation from operational data. This virtualization is compressing certification timelines and shifting aftermarket value toward software-enabled service contracts.
The European Union Aviation Safety Agency's CS-25 certification updates incorporate revised emissions monitoring protocols that tighten compliance thresholds for nitrogen oxides and particulate matter. Airframe manufacturers must demonstrate powertrain integration meets stage-specific limits to maintain market access. Large-cabin segment programs face the steepest adaptation requirements given thrust ratings and flight cycle profiles.
Charter brokers and fractional platforms are unbundling traditional ownership economics into subscription-based access models. Corporate travel managers prioritize utilization guarantees over asset depreciation exposure, redirecting procurement evaluation toward operator reliability metrics. This behavioral pivot is most pronounced in the United States, where hub-and-spoke commercial inefficiencies sustain willingness-to-pay premiums for on-demand departure flexibility.
Global Business Aircraft Market Segmentation
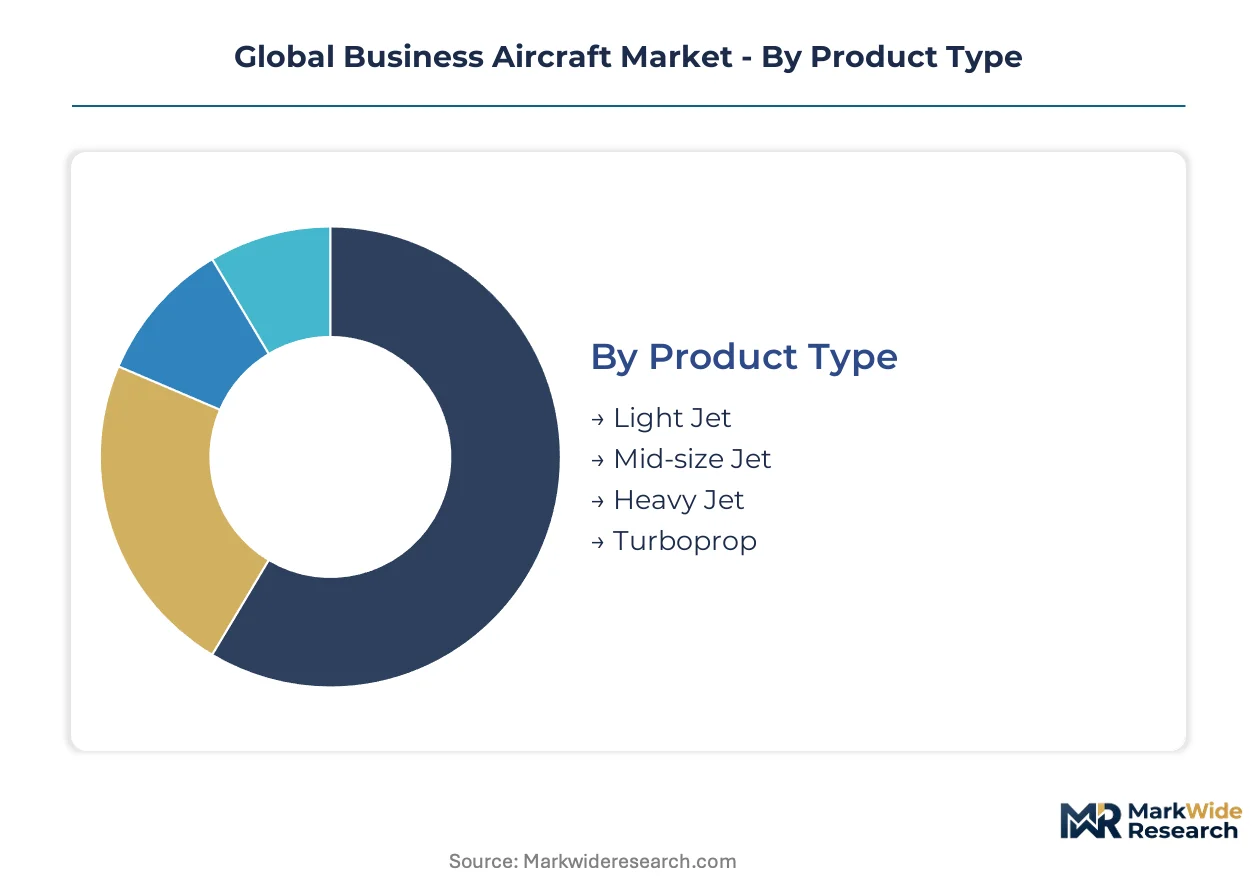
Segmentation in business aircraft reveals how mission profiles, capital structures, and regulatory exposure fragment procurement behavior. Understanding these fault lines clarifies why OEMs configure platform families across divergent operating economics and certification pathways.
Product Type:
Use-case spectrum spans from short-haul regional connectivity to intercontinental nonstop missions, with each tier demanding distinct airframe engineering and powertrain integration.
- Light Jet:Single-pilot-certified platforms with maximum takeoff weights under 10,000 pounds and ranges of 1,500–2,500 nautical miles. Demand concentrates in the United States among charter services scaling fractional-access fleets, driven by FAA Part 135 operational flexibility and secondary airport penetration. The category climbs fastest as air taxi platforms standardize on common type ratings.
- Heavy Jet:Large-cabin platforms exceeding 40,000 pounds MTOW with intercontinental range capabilities and stand-up cabin heights. Procurement clusters with corporate flight departments in Switzerland and Saudi Arabia, where executive time valuation and cabin customization intensity justify unit premiums. Established volume favors Heavy Jet; emerging adoption favors Light Jet.
- Mid-size Jet:Transcontinental-range platforms bridging super-midsize and large-cabin categories with 3,000–4,000 nautical mile capability. Gulfstream and Bombardier anchor this tier with integrated flight decks and enhanced cabin pressurization systems.
- Turboprop:Unpressurized and pressurized variants optimized for short-field performance and operating cost thresholds below jet alternatives. King Air family dominance persists in Australia and Canada where unimproved runway networks exclude jet operations.
Margin capture stratifies sharply: Heavy Jet sustains customization premiums; Light Jet sacrifices unit economics for fleet standardization velocity.
End User:
Capital deployment models determine procurement cadence, with asset-light access arrangements displacing traditional ownership across corporate travel budgets.
- Charter Services:Fleet operators providing on-demand or block-hour access without ownership transfer. Growth concentrates in the United States and United Arab Emirates, where NetJets and VistaJet scale fractional platforms under FAA and GCAA regulatory frameworks. The segment gains share fastest as corporate travel managers shed depreciation exposure.
- Corporate:Flight departments maintaining dedicated aircraft for executive transport with in-house crew and maintenance infrastructure. Procurement persists among Fortune 500 headquarters clusters in Texas and Connecticut, sustained by hub-and-spoke commercial airline inefficiencies.
- Government:State-owned or ministry-operated fleets for head-of-state transport, military liaison, and surveillance missions. Dassault and Airbus Defence anchor this channel in France and Germany through offset agreements and diplomatic protocol requirements.
- Private Owners:Individual high-net-worth operators with full ownership and personal type ratings. Concentration tracks wealth formation in Singapore and Monaco, where registry optimization and crew employment structures shape jurisdiction selection.
Contractual sophistication separates Charter Services from Private Owners; operational control requirements separate Corporate from Government procurement.
Application:
Mission specialization fragments airframe configuration, with modular interiors enabling rapid conversion between passenger and medical layouts.
- Executive Travel:Primary revenue driver encompassing point-to-point transport for corporate leadership and high-net-worth individuals. Demand anchors in the United States and United Kingdom, where schedule autonomy commands premium pricing against commercial alternatives.
- Medical Evacuations:Dedicated air ambulance configurations with stretcher systems, medical gas plumbing, and isolation capabilities. Japan and Switzerland drive specification intensity as aging demographics and alpine terrain gaps sustain dedicated fleet investment.
- Cargo Transport:Priority freight and time-critical logistics utilizing converted passenger cabins or factory cargo variants. DHL and FedEx operate specialized fleets from Leipzig and Memphis hubs for organ transport and high-value shipments.
- Air Taxi:Short-haul on-demand services bridging urban vertiports with conventional airports. Lilium and Joby target this segment in Germany and California, though certification timelines under EASA and FAA constrain near-term deployment.
Steepest expansion trajectory belongs to Medical Evacuations; deepest margin pool remains Executive Travel.
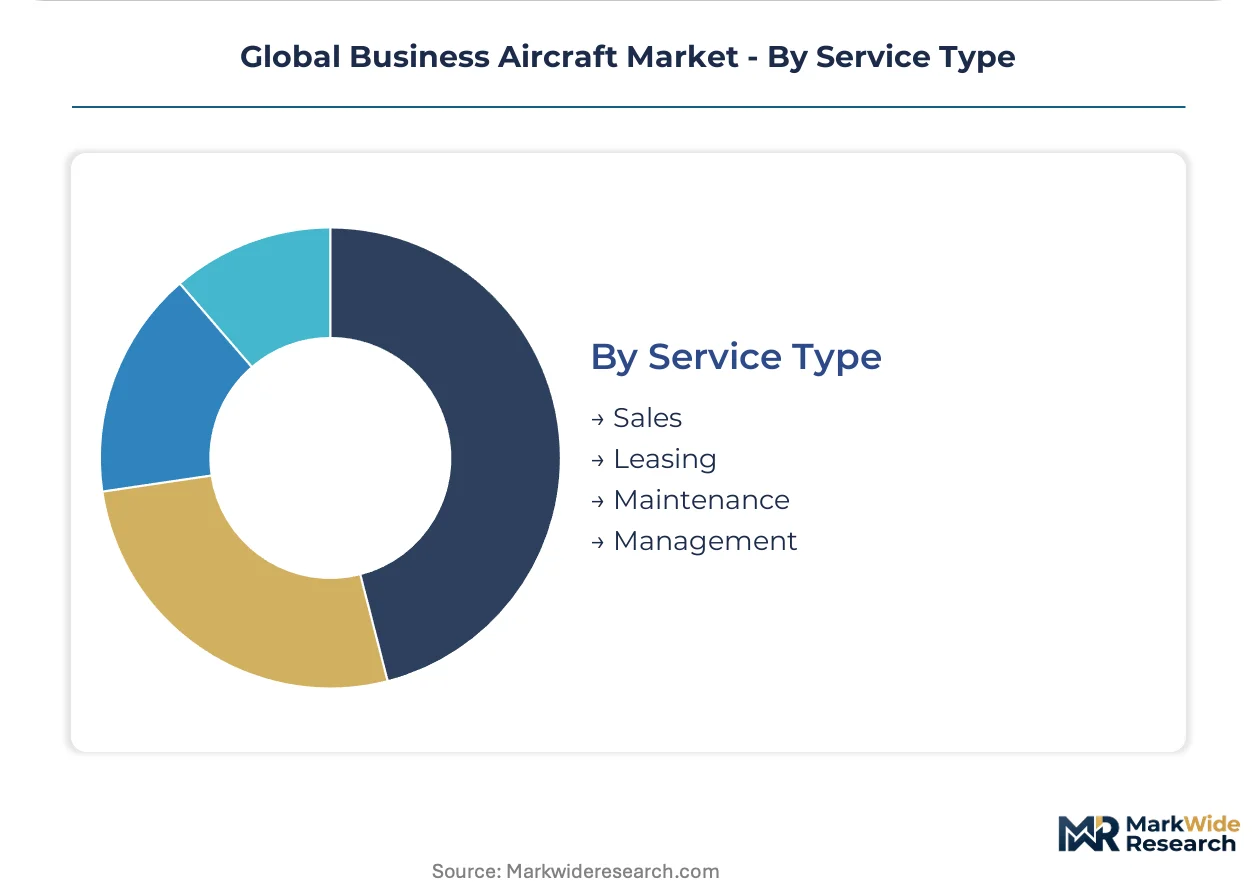
Service Type:
Value chain positioning determines recurring revenue capture versus transactional margin extraction.
- Management:Full-service flight department outsourcing encompassing crew employment, maintenance oversight, and regulatory compliance. Demand clusters among Private Owners in the United Kingdom and Switzerland seeking operational anonymity and scale efficiencies.
- Maintenance:Line and heavy maintenance, engine overhaul, and avionics upgrade services. Gulfstream and Bombardier anchor proprietary networks in the United States and Singapore, while independent MROs compete on turboprop and aging jet platforms.
- Leasing:Operating and finance lease structures enabling fleet flexibility without balance-sheet asset recognition. AerCap and GECAS dominate this channel for corporate flight departments seeking tax-advantaged structures.
- Sales:New aircraft delivery and pre-owned transaction brokerage. Pre-owned markets concentrate transaction velocity in Florida and Arizona, where registration tax advantages and inspection infrastructure cluster inventory.
Recurring revenue intensity favors Management; transaction margin concentration favors Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in business aircraft track asymmetrically, with the United States running substantial surpluses in large-cabin deliveries while Switzerland and Singapore function as re-export hubs for registry-optimized transactions. Demand geography concentrates where executive time valuation exceeds commercial airline schedule rigidity.
United States
Hub-and-spoke commercial inefficiencies at secondary airports sustain the world's deepest fleet penetration, with fractional ownership platforms scaling under FAA Part 135 operational frameworks. The Federal Aviation Administration's sustainable aviation fuel blending mandates under the Inflation Reduction Act procurement incentives are reshaping operator fuel contracts. Dallas-Fort Worth and Teterboro anchor the highest-density charter infrastructure clusters, where NetJets and VistaJet maintain crew domiciles.
Switzerland
Executive time valuation and alpine terrain medical evacuation requirements concentrate large-cabin procurement among Geneva and Zurich flight departments. Swissmedic coordinates with EASA on air ambulance certification reciprocity, enabling rapid configuration approvals for dedicated medevac interiors. Basel's tri-national airport zone hosts specialized MRO facilities serving Dassault and Bombardier fleets across French and German borders.
United Arab Emirates
Dubai and Abu Dhabi function as re-export and registry optimization centers for Saudi and Qatari principals seeking GCAA regulatory efficiency. MOHAP oversees medical evacuation licensing for air ambulance operators serving aging demographics across the Gulf Cooperation Council. Al Maktoum International's dedicated business aviation terminal infrastructure supports the highest per-capita heavy jet density globally.
China
Regulatory liberalization of low-altitude airspace under MIIT coordination is expanding accessible routes for business aircraft beyond traditional coastal corridors. The country's national aviation regulator maintains stringent type certification requirements that extend market access timelines for foreign OEMs. Shanghai Hongqiao and Beijing Daxing concentrate dedicated FBO infrastructure, though operational restrictions persist around military airspace corridors.
Brazil
Embraer's domestic manufacturing base sustains regional turboprop and light jet penetration across Latin American charter networks. ANVISA coordinates with the national aviation regulator on air ambulance medical equipment certification standards. São Paulo's Congonhas airport hosts the continent's densest business aviation infrastructure, serving mining and agribusiness executive travel across Portuguese-speaking Africa.
Global Business Aircraft Market Vendor Landscape
On the supply side, the industry is consolidated around a handful of integrated airframe manufacturers with captive certification expertise and proprietary service networks. Capital intensity and regulatory barriers exclude new entrants from clean-sheet platform development. Two strategic archetypes dominate: diversified aerospace conglomerates leveraging defense and commercial synergies, and pure-play business aviation specialists optimizing cabin customization intensity. Competitive positioning hinges on M&A-driven portfolio breadth and sustainable propulsion partnerships with engine OEMs.
Among North American-integrated manufacturers, Bombardier, Gulfstream Aerospace Corporation, and Textron Aviation exemplify contrasting scale and specialization strategies. Bombardier occupies a position as the ultra-long-range specialist following its commercial aviation divestiture. Gulfstream anchors the super-midsize and large-cabin categories through integrated flight deck and cabin pressurization differentiation. Textron's multi-brand architecture spans Cessna's light jet volume leadership and Beechcraft's turboprop dominance in secondary airport networks.
| Leading Market Players |
|---|
| Bombardier |
| Dassault Aviation |
| Gulfstream Aerospace Corporation |
| Textron Aviation |
| Embraer |
| Airbus |
| Boeing |
| HondaJet |
| Cessna |
| Others |
Supply Flow & Price Mechanics
Wichita's manufacturing cluster anchors North American airframe assembly capacity, concentrating supplier leverage over downstream charter operators and corporate flight departments. This geographic concentration translates directly into pricing power for OEMs configuring cabin customization packages and powertrain upgrades.
Pricing Analysis
Industrial OEM buyers anchor transactional pricing structures across heavy jet and light jet categories. Pricing stratifies across premium large-cabin configurations, standard mid-size platforms, and economy turboprop tiers based on certification level and customization intensity. Cost compression in light jet segments is intensifying because charter fleet standardization sacrifices unit margins for volume velocity. Corporate flight departments exhibit lowest price sensitivity due to executive time valuation, while fractional platform operators face acute margin pressure from fuel cost volatility.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates supply chain risk planning for composite airframe components and avionics systems. Manufacturing concentrates in the United States, France, and Canada for final assembly, while titanium alloys and carbon fiber prepregs draw from Japanese and German specialty suppliers. Single-source vulnerability persists for integrated flight deck processors certified under FAA and EASA protocols. Distribution runs through proprietary OEM service centers and independent MRO networks anchored in Dallas-Fort Worth, Geneva, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through fractional ownership platform consolidation, with NetJets and VistaJet aggregating procurement volume across standardized fleet commitments. This consolidation shifts negotiating leverage toward asset-light access models and away from traditional corporate flight departments.
For Market Incumbents: Insulate ultra-long-range positioning through captive sustainable aviation fuel partnerships and proprietary MRO network expansion in Dubai and Singapore. Gulfstream and Bombardier must defend against emerging electric vertical take-off and landing platforms by accelerating hybrid-electric powertrain certification timelines under FAA Part 25 frameworks.
For New Entrants and Emerging Players: Establish a beachhead in medical evacuation specialization for aging demographics across Japan and Switzerland. Air taxi platforms targeting German and California vertiport networks offer the most penetrable white space, with go-to-market traction hinging on EASA SC-VTOL certification reciprocity with FAA operational approvals.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because SAF mandate compliance creates durable competitive moats for incumbent OEMs with established certification expertise. Acquisition targets should emphasize composite MRO specialists with EASA Part 145 approvals. The signal to watch is sustainable aviation fuel infrastructure deployment rates at EU and US hub airports.
| Strategic Initiative | Industry Significance |
|---|---|
| SAF Supply Partnership | Secures feedstock access for ReFuelEU Aviation compliance across EU airport networks. |
| Digital Twin Deployment | Compresses Bombardier and Gulfstream certification timelines through virtual validation environments. |
| Vertiport Infrastructure Investment | Extends business aircraft utility through first-last-mile connectivity at Dubai and Los Angeles hubs. |
| Medical Evacuation Certification | Captures Swissmedic and ANVISA air ambulance specification intensity in alpine and Latin American markets. |
| Fractional Platform Acquisition | Consolidates charter demand aggregation under unified fleet management and crew domicile networks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FAA type certification databases, EASA CS-25 regulatory filings, and OEM delivery disclosure records. Interviews with fleet operations directors, charter brokerage principals, MRO service heads, and sustainable aviation fuel procurement officers were triangulated against customs trade data and airport traffic statistics. Bottom-up delivery forecasts were validated against top-down market sizing from corporate travel budget disclosures and fractional ownership platform financial statements.
Forecast inputs span aircraft class segmentation, propulsion architecture adoption curves, and regional regulatory cluster differentiation across the projection horizon. Modeled dimensions include product type, end-user capital structure, mission application, and service type positioning. CAGRs were derived from logistic diffusion curves fitted to historical delivery patterns and SAF infrastructure deployment trajectories. Industry-specific inputs incorporate pilot training pipeline constraints and bilateral airworthiness agreement negotiation status.
Stress conditions across sustainable aviation fuel cost volatility, clean-sheet certification timeline extensions, and fractional platform consolidation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EASA and FAA regulatory harmonization progress. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Ailerons Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Freighter Aircraft Market
Aircraft
Small Evtol Aircraft Market
Aircraft
Firefighting Aircraft Market
Aircraft
Air Starter Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Military Helicopters Market
Aircraft
Commercial Aircraft Market
Aircraft
Regional Jet Market
Aircraft
Amphibious Aircraft Market
Aircraft
Supersonic Jet Market
Aircraft
Fighter Aircraft Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market