
 Hybrid Aircraft Market | 2026-2036
Hybrid Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Aircraft Market Analysis
Regional aviation and urban air mobility is rebalancing away from conventional turboprop dependency toward hybrid-electric architectures. Airbus SE leverages distributed propulsion research across European test corridors to validate tilt-wing configurations. Boeing sustains dual-path investments in both hydrogen combustion and battery-electric subsystems for future narrow-body derivatives. Rolls-Royce Holdings plc anchors its position through turbogenerator development that bridges conventional gas turbine reliability with electric motor efficiency.
Hybrid aircraft integrate multiple propulsion sources—typically combining gas turbines, batteries, fuel cells, or electric motors—to optimize thrust delivery across flight phases while reducing fuel burn and emissions. These platforms employ power-split architectures where megawatt-class electric machines supplement or replace direct mechanical shaft power, enabling operational profiles from 50-seat regional routes to 19-passenger urban shuttle missions. The technology dimension shows hybrid-electric configurations commanding early investment intensity, while fuel cell variants attract longer-dated R&D commitments due to hydrogen storage density constraints. Among applications, urban air mobility absorbs disproportionate venture funding despite freight transport offering clearer payload-range economics and faster path to certification.
The FAA's Part 23 rewrite and EASA's SC-VTOL special condition framework jointly establish certification baselines for electric and hybrid propulsion, though divergence in battery thermal runaway test protocols creates dual-compliance burdens for OEMs targeting transatlantic sales. The EU Green Deal's ReFuelEU Aviation mandate progressively tightens sustainable aviation fuel quotas, indirectly favoring hybrid architectures that minimize fossil fuel dependency through operational electrification. Stakeholders must monitor whether China's CAAC adopts EASA-aligned certification standards or pursues indigenous criteria that fragment type validation for Asian market entry.
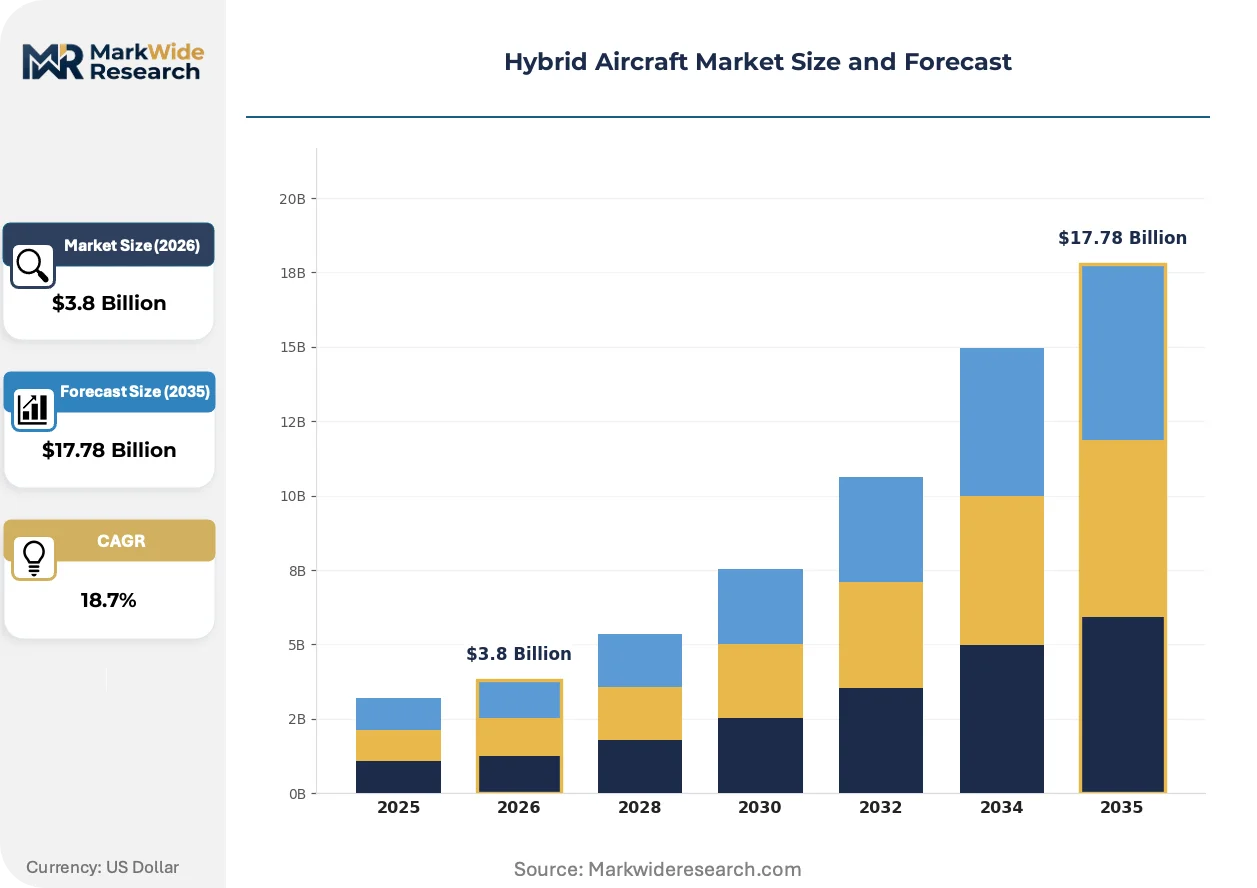
Market Dynamics
Certification pathway compression through FAA Part 23 reforms and EASA SC-VTOL frameworks is accelerating hybrid-electric platform commercialization timelines, forcing incumbents to restructure propulsion R&D budgets toward megawatt-class electric machine integration.
Growth Catalysts
- ReFuelEU Aviation mandate:The EU Green Deal's progressive sustainable aviation fuel quotas indirectly favor hybrid architectures that minimize fossil fuel dependency through operational electrification of regional routes.
- Urban air mobility infrastructure:Germany anchors fleet procurement acceleration as Volocopter and Lilium validate vertiport networks and air traffic management protocols for 19-passenger shuttle missions.
- Distributed propulsion validation:European test corridors enable tilt-wing configuration maturation, reducing technical risk for power-split architectures combining turbogenerators with battery-electric subsystems.
Market Restraints
- Hydrogen storage density constraints:Fuel cell variants face prolonged R&D timelines due to cryogenic tankage mass penalties that compress payload-range economics for regional aircraft.
- Dual-compliance certification burden:Divergence between FAA battery thermal runaway test protocols and EASA standards fragments type validation for OEMs targeting transatlantic sales.
- Specialized power electronics supply:Megawatt-class inverter and motor controller manufacturing concentrates among a limited supplier base, creating input cost volatility for hybrid propulsion integrators.
Strategic Opportunities
- Freight transport certification path:Cargo operators offer clearer payload-range economics and faster FAA Part 23 approval timelines compared to passenger urban air mobility platforms.
- CAAC regulatory alignment watch:Stakeholders monitor whether China's civil aviation regulator adopts EASA-aligned certification standards or pursues indigenous criteria that would fragment Asian market entry protocols.
- Retrofit kit development:Power-split architecture modularity enables aftermarket hybridization of existing regional turboprop fleets, opening installed base conversion revenue streams.
Industry Challenges
- Multiphysics simulation talent scarcity:Electromechanical propulsion integration requires specialized expertise in thermal-electric-mechanical coupled modeling that outstrips current aerospace engineering pipeline output.
- Battery degradation certification:EASA SC-VTOL special conditions demand extensive cycle-life validation data that extends type approval timelines and inflates development capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Aircraft Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.78 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Passenger, Cargo, Military, Recreational Technology: Electric, Hybrid-Electric, Fuel Cell, Turbofan End User: Commercial Airlines, Private Owners, Government Agencies, Cargo Operators Application: Urban Air Mobility, Freight Transport, Surveillance, Charter Services |
| Companies Covered | Airbus SE, The Boeing Company, RTX Corporation, General Electric Company, Embraer S.A., Safran SA, Rolls-Royce Holdings plc, Textron Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Aircraft Market Emerging Trajectories
Propulsion architecture decisions are locking in competitive positions for the next decade as hybrid-electric configurations mature ahead of hydrogen combustion alternatives, reshaping supplier relationships and fleet planning assumptions.
Tilt-wing distributed propulsion is overtaking conventional fixed-wing layouts for regional missions above 50 nautical miles. Urban air mobility operators in German test corridors are specifying tilt-rotor configurations for vertiport compatibility. This topology is compressing the addressable market for conventional turboprop retrofits in sub-500km routes.
EASA's SC-VTOL special condition framework establishes battery thermal runaway containment standards that exceed FAA Part 23 baseline requirements. European OEMs face additional engineering validation costs for transatlantic certification. The divergence pressures manufacturers to develop modular battery pack architectures that satisfy both regulatory regimes without complete redesign.
Regional airline procurement committees now weight total cost of ownership models that internalize carbon pricing exposure across 15-year fleet cycles. Nordic carriers lead this behavioral shift, embedding EU ETS liability forecasts into lease-versus-buy decisions. The practice spreads southward as ReFuelEU Aviation mandate compliance costs harden into operating budget line items.
Hybrid Aircraft Market Segmentation
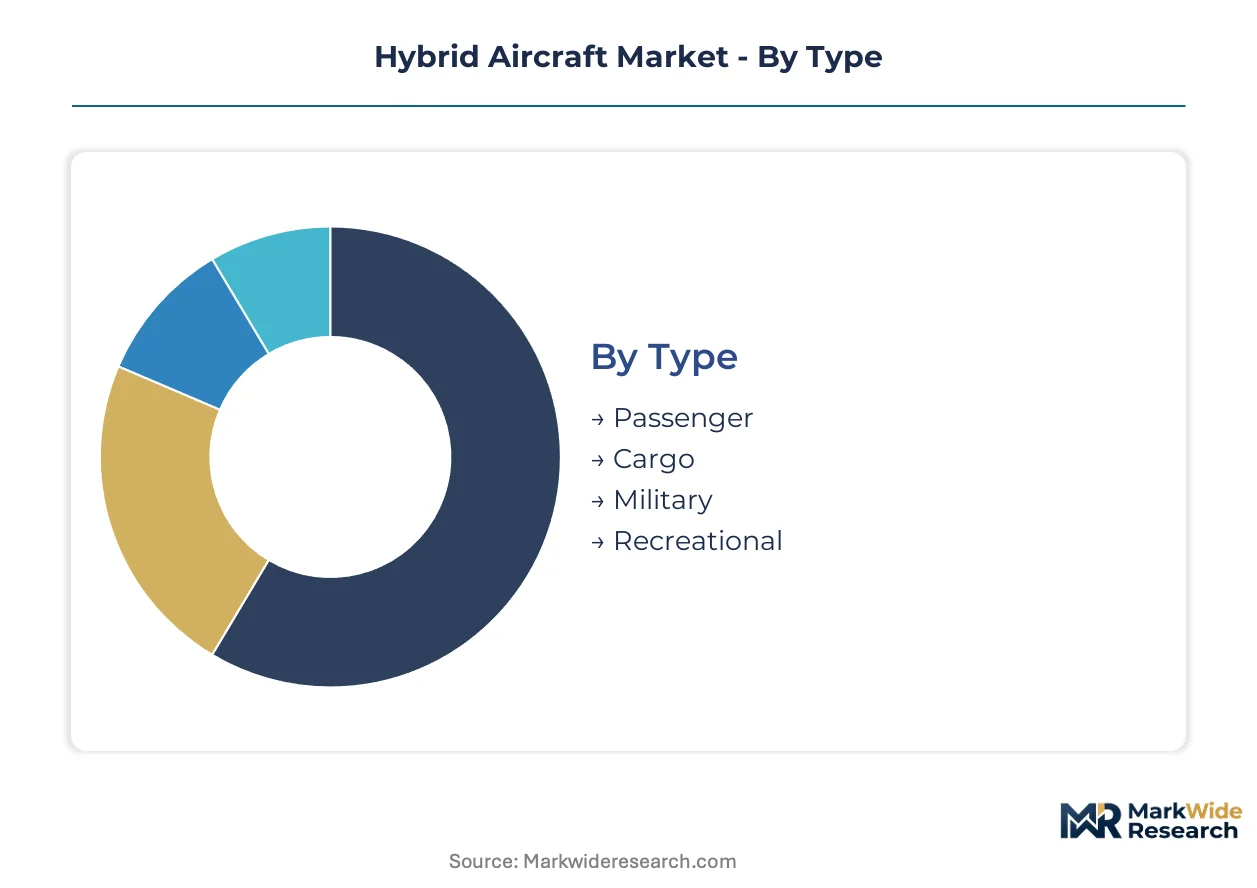
Hybrid aircraft segmentation reveals divergent certification pathways across mission profiles. Passenger platforms face EASA SC-VTOL battery thermal runaway standards, while cargo variants align with accelerated FAA Part 23 freight approvals. Technology choices lock in decade-long supplier relationships and fleet planning assumptions.
Type:
Certification burden varies sharply across type segments. Passenger aircraft navigate EASA SC-VTOL and FAA Part 23 dual-compliance for battery-electric architectures. Military platforms follow defense procurement protocols with classified performance thresholds. Cargo and recreational types exploit regulatory arbitrage between jurisdictions.
- Passenger:Tilt-wing distributed propulsion dominates 19-seat shuttle configurations. German vertiport networks and Nordic regional carriers concentrate procurement for 50-100 nautical mile routes under EU ETS compliance pressure.
- Cargo:Payload-range economics favor turbogenerator-battery power-split architectures. North American freight operators and Chinese e-commerce logistics providers drive fleet orders for sub-500kg payload platforms with simplified FAA Part 23 approval timelines.
- Military:Defense agencies specify silent-running electric modes for surveillance insertion missions with extended loiter requirements.
- Rereational:Private ownership concentrates in Switzerland and Australia under experimental airworthiness certificates with restricted operational envelopes.
Leading the category by volume: Cargo. Growing fastest: Passenger.
Technology:
Technology segments stratify by R&D maturity and hydrogen infrastructure readiness. Hybrid-electric configurations leverage existing turbogenerator supply chains. Fuel cell variants await cryogenic tankage mass reductions. Electric-only platforms face battery energy density ceilings for regional missions.
- Electric:Battery-electric architectures serve sub-100km urban missions with 30-minute reserve requirements. Volocopter and Lilium validate distributed motor configurations in German test corridors under EASA SC-VTOL monitoring.
- Hybrid-Electric:Power-split architectures combining Rolls-Royce turbogenerators with megawatt-class electric machines anchor 50-seat regional routes. Airbus SE validates tilt-wing configurations across European corridors to reduce technical risk.
- Fuel Cell:Hydrogen-electric systems face prolonged development timelines due to cryogenic storage mass penalties compressing payload-range economics.
- Turbofan:Conventional gas turbine baselines persist for long-haul derivatives awaiting hybrid retrofit kit compatibility.
Technology commanding investment intensity: Hybrid-Electric. Steepest expansion trajectory: Electric.
End User:
End user concentration determines pricing power and certification negotiation leverage. Commercial airlines embed carbon pricing exposure into 15-year total cost of ownership models. Government agencies mandate domestic content requirements affecting supplier selection.
- Commercial Airlines:Nordic carriers lead EU ETS liability integration into lease-versus-buy decisions. Regional procurement committees weight operational electrification against ReFuelEU Aviation mandate compliance costs.
- Cargo Operators:Freight specialists exploit clearer payload-range economics and faster FAA Part 23 certification paths compared to passenger platforms.
- Private Owners:High-net-worth individuals in Switzerland and UAE drive recreational tilt-rotor demand under experimental airworthiness frameworks.
- Government Agencies:Defense and border surveillance specifications require silent-running electric modes with classified endurance thresholds.
Dominant procurement volume: Commercial Airlines. Gaining share fastest: Cargo Operators.
Application:
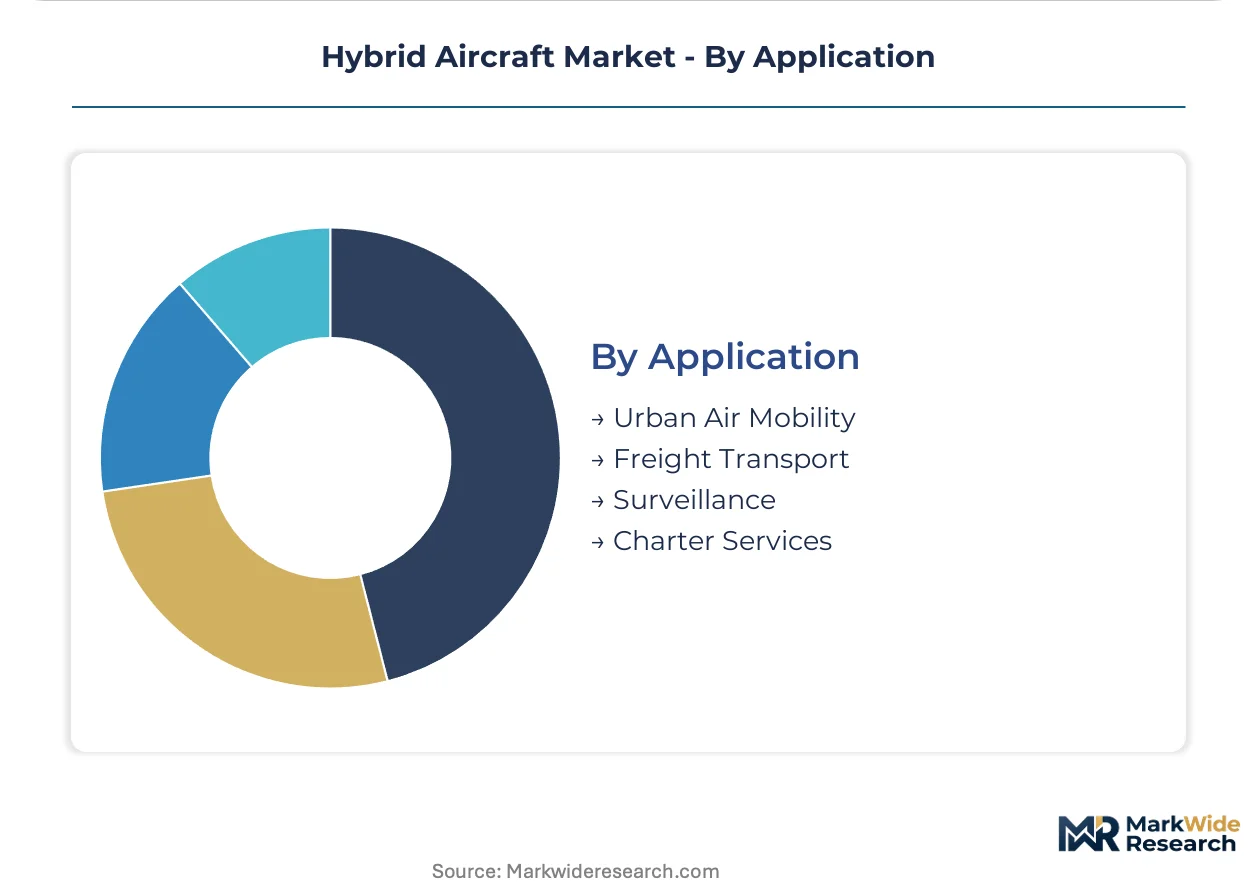
Application segments diverge by infrastructure dependency and traffic management complexity. Urban air mobility requires vertiport networks and unmanned traffic integration. Freight transport leverages existing logistics infrastructure with lower regulatory friction.
- Urban Air Mobility:19-passenger shuttle missions concentrate in German urban corridors with Volocopter and Lilium anchoring vertiport standardization. EASA SC-VTOL battery containment standards exceed FAA baselines, fragmenting transatlantic platform designs.
- Freight Transport:Sub-500kg payload logistics exploit clearer certification economics and existing warehouse-to-warehouse route structures. Chinese e-commerce operators and North American last-mile providers concentrate fleet procurement.
- Surveillance:Government border patrol and infrastructure monitoring missions demand extended loiter with silent electric transition capability.
- Charter Services:On-demand regional connectivity targets underserved routes between secondary cities with 50-seat hybrid-electric platforms.
Application absorbing disproportionate venture funding: Urban Air Mobility. Fastest path to certification: Freight Transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of hybrid-electric propulsion systems concentrates in Germany, France, and the United States, while demand absorption spreads across Nordic markets and Chinese urban corridors seeking fleet electrification.
United States
FAA Part 23 certification reforms accelerate type approval timelines for electric propulsion platforms. The IRA's clean aviation tax credits subsidize turbogenerator-battery integration R&D. California's Advanced Air Mobility corridor networks host distributed propulsion validation flights between regional airports.
Germany
Volocopter and Lilium anchor vertiport infrastructure deployment for 19-passenger urban shuttle missions. ReFuelEU Aviation mandates progressively tighten sustainable aviation fuel quotas favoring hybrid architectures. Bavaria's Munich-Augsburg test corridor validates tilt-wing configurations under EASA SC-VTOL monitoring.
China
E-commerce logistics providers concentrate procurement for sub-500kg payload hybrid platforms. CAAC regulatory alignment with EASA standards remains unresolved, fragmenting type validation protocols. Yangtze River Delta cities trial urban air mobility routes connecting Shanghai satellite districts.
France
Airbus SE leverages distributed propulsion research across Toulouse-Blagnac test facilities. EU Green Deal carbon pricing exposure drives Air France-KLM regional subsidiary fleet planning toward electrification. Île-de-France vertiport clusters anchor Paris metropolitan air mobility corridor development.
United Kingdom
Rolls-Royce Holdings plc anchors turbogenerator development bridging gas turbine reliability with electric motor efficiency. CAA adoption of EASA SC-VTOL battery thermal runaway standards lags, creating certification uncertainty. Bristol's aerospace engineering corridor concentrates megawatt-class electric machine integration talent.
Hybrid Aircraft Market Vendor Landscape
Top-tier vendors anchor integrated platform development, while specialist suppliers occupy component-tier positions. The market exhibits tiered concentration with full-aircraft OEMs controlling certification pathways and propulsion integrators capturing subsystem margins. Two strategic archetypes dominate: legacy aerospace conglomerates with turbogenerator heritage and venture-backed electric aviation pure-plays. Competitive moves center on vertiport infrastructure partnerships and distributed propulsion patent licensing.
Within the legacy conglomerate tier, Airbus SE and The Boeing Company exemplify dual-path investment strategies spanning hydrogen combustion and battery-electric subsystems. Rolls-Royce Holdings plc occupies a distinctive position bridging conventional gas turbine reliability with megawatt-class electric machine integration. Among specialized propulsion developers, RTX Corporation and Safran SA represent turbogenerator-battery power-split architecture specialists targeting regional route electrification.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| RTX Corporation |
| General Electric Company |
| Embraer S.A. |
| Safran SA |
| Rolls-Royce Holdings plc |
| Textron Inc. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up power electronics specialists concentrate megawatt-class inverter manufacturing in Germany and the United States, tightening pricing discipline through captive supply of critical motor controllers while externalizing battery pack cost volatility to platform integrators.
Pricing Analysis
Cost-down pressure on hybrid propulsion systems accelerates because EASA SC-VTOL battery thermal runaway certification requirements fragment platform designs. Three-tier pricing structure across Part 23-certified, SC-VTOL-compliant, and experimental airworthiness tiers separates OEMs by validation burden. Price differentiation traces to certification grade and after-sales service bundling. Cargo operators exhibit highest price sensitivity due to payload-range economics discipline, while government surveillance agencies accept premium pricing for silent-running electric mode performance.
Supply Chain Analysis
Megawatt-class electric machine supply rests on German and British specialty motor manufacturers feeding Rolls-Royce turbogenerator integration lines. Lithium-ion cell production draws from South Korean and Chinese cathode material suppliers. Cryogenic hydrogen tankage components hinge on French and Japanese composite specialists. Single-source vulnerability concentrates in silicon carbide inverter substrates. Distribution runs through airframe OEM final assembly lines with captive propulsion subsystem integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA SC-VTOL battery thermal runaway standards erect a cost-of-compliance moat that rewards early certification investment while marginalizing capital-constrained entrants unable to fund dual-validation engineering.
For Market Incumbents: Acquire turbogenerator-battery power-split architecture patents to lock in regional route electrification supplier relationships. Defensive consolidation around megawatt-class electric machine manufacturing capacity in Bavaria and Bristol protects against emerging Chinese e-commerce logistics entrants. Certification investment in FAA-EASA modular battery pack architectures preserves transatlantic pricing power. For New Entrants and Emerging Players: Digital-channel route partnerships with freight forwarder procurement platforms bypass incumbent airline sales cycles. White-space targets concentrate in Chinese Yangtze River Delta sub-500kg payload logistics and North American last-mile warehouse networks. Go-to-market angle emphasizes accelerated FAA Part 23 cargo certification timelines versus passenger platform delays. For Investors and Strategic Acquirers: Distressed-cycle entries favor turbogenerator specialists with EASA-validated test corridor access in Germany. Long-term viability frames around ReFuelEU Aviation mandate compliance cost internalization across 15-year fleet cycles. Acquisition target archetype: tilt-wing distributed propulsion patent holders with vertiport infrastructure partnerships. Signal to watch: CAAC regulatory alignment decision fragmenting or harmonizing Asian type validation protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Vertiport Infrastructure Partnership | Volocopter and Lilium anchor German urban corridor standardization for 19-passenger shuttle networks. |
| Dual-Certification Modular Battery Architecture | EASA SC-VTOL and FAA Part 23 compliance reduces redesign costs for transatlantic platform sales. |
| Turbogenerator Supply Agreement | Rolls-Royce Holdings plc captive supply secures regional route electrification performance guarantees. |
| Cargo-First Certification Pathway | Freight operators exploit faster FAA Part 23 approval timelines versus passenger urban air mobility delays. |
| Tilt-Wing Distributed Propulsion Patent Licensing | Airbus SE European test corridor validation reduces technical risk for power-split architectures. |
Methodological Framework
Regulatory filing databases, EASA certification documentation, and FAA Part 23 amendment records formed the secondary backbone. Primary interviews with propulsion system engineering directors, airline fleet procurement managers, vertiport infrastructure developers, and battery thermal runaway testing specialists validated technology readiness assessments. Bottom-up platform deployment forecasts and top-down sustainable aviation fuel mandate compliance models were triangulated against European test corridor flight data.
Historical trendline analysis of hybrid-electric propulsion R&D expenditure patterns informed projection framework construction across the analysis window. Segmentation dimensions modeled include propulsion architecture type, certification pathway tier, application mission profile, and regional regulatory cluster. CAGRs were derived from fleet procurement pipeline analysis and ReFuelEU Aviation mandate compliance cost trajectories. Industry-specific forecast inputs incorporated turbogenerator-battery integration timelines and cryogenic hydrogen tankage mass reduction curves.
The model holds under sustained EASA-FAA regulatory convergence; deviation in CAAC indigenous standard adoption or battery energy density plateau would shift commercialization timelines. Forecasts reflect documented assumptions regarding vertiport infrastructure deployment rates and carbon pricing mechanism expansion. A small set of named triggers—hydrogen storage mass breakthrough, multiphysics simulation talent pipeline expansion, and China regulatory alignment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Search and Rescue Aircraft Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Leasing Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Turboprop Aircraft Market
Aircraft
General Aviation Market
Aircraft
North America General Aviation Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Aircraft Exterior Mounts Market