
 Global Aircraft De-Icing Market | 2026-2036
Global Aircraft De-Icing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft De-Icing Market Intelligence
Direct supply agreements between fluid manufacturers and major airport authorities are rewriting traditional distribution models, bypassing smaller intermediaries. Clariant AG specializes in high-performance propylene glycol-based fluids, serving major European airports. JBT Corporation dominates the de-icing vehicle and equipment segment with its advanced systems. Vestergaard Company leverages its integrated solutions combining trucks and fluid application technology to secure long-term service contracts.
Aircraft de-icing involves the removal of frost, ice, or snow from an aircraft's surfaces to ensure safe flight operations. The process utilizes either chemical fluids, such as propylene or ethylene glycol mixtures, or thermal methods like electro-thermal systems embedded in wing structures. Fluid-based solutions represent the largest product type, driven by widespread use in commercial aviation for both anti-icing and de-icing procedures. Electro-thermal and mechanical systems are gaining traction in general aviation and for specific military applications where ground support is limited.
Regulatory compliance is a critical operational constraint, with standards set by the Federal Aviation Administration (FAA) in the United States and SAE International's AMS specifications. Europe's ECHA, through the REACH regulation, imposes strict environmental controls on the chemical composition of de-icing fluids, influencing product development. The key decision for airlines and airports will be balancing operational efficiency and cost with investments in more sustainable, less corrosive de-icing technologies.
Market Dynamics
The aircraft de-icing market is shaped by the fundamental tension between stringent environmental regulations and the operational demand for cost-effective, rapid turnaround times at airports. This dynamic forces a continuous re-evaluation of chemical fluid compositions and application technologies to meet both compliance and efficiency targets.
Growth Catalysts
- Commercial Aviation Expansion:The growth of low-cost carriers and the expansion of flight routes into colder climates in Eastern Europe and Canada directly increases the consumption of de-icing fluids and the need for ground support equipment.
- Regulatory Safety Mandates:Standards set by aviation authorities like the Federal Aviation Administration (FAA) and EASA enforce strict pre-flight de-icing protocols, making the process non-discretionary for commercial airlines during winter conditions.
- Advanced Airframe Integration:The development of new aircraft, particularly in business and general aviation, incorporates more sophisticated anti-icing technologies like electro-thermal systems, creating a market for specialized components and power systems.
Market Restraints
- Input Cost Volatility:The prices of primary de-icing fluid feedstocks, propylene glycol and ethylene glycol, are tied to volatile petrochemical markets, creating unpredictable operational costs for airlines and ground handlers.
- Environmental Compliance Costs:Europe's REACH framework imposes significant research, development, and registration costs on fluid manufacturers, limiting the range of permissible chemical agents and slowing the introduction of new formulations.
- Technical Limitations of Alternatives:While promising, electro-thermal and pneumatic de-icing systems face constraints related to power consumption, weight, and retrofit complexity, limiting their widespread adoption on legacy commercial aircraft fleets.
Strategic Opportunities
- Biodegradable Fluid Development:There is a significant opportunity to formulate and market fully biodegradable de-icing fluids that exceed current environmental standards, targeting airports in ecologically sensitive areas or those facing strict local regulations.
- Integrated Service and Fleet Management:Suppliers can offer comprehensive, long-term contracts to airports that bundle de-icing vehicles, fluid supply, maintenance, and operator training, shifting from transactional sales to a service-based model.
- Sensor-Driven Application Systems:Integrating optical or thermal sensors onto de-icing trucks to precisely measure ice thickness allows for optimized fluid application, reducing chemical waste, environmental runoff, and operational costs.
Industry Challenges
- High Capital Expenditure:The acquisition of modern de-icing trucks and the construction of centralized de-icing pads with compliant fluid collection and recycling systems represent a major capital investment for airport authorities.
- Certification and Standardization Hurdles:Gaining approval for new de-icing fluids under SAE International's AMS specifications is a time-consuming and expensive process, creating a high barrier to entry for new chemical formulations.
- Specialized Labor Requirements:Operating advanced de-icing equipment and managing fluid logistics requires trained and certified personnel, and seasonal demand creates challenges in retaining a skilled workforce year-round.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft De-Icing Market |
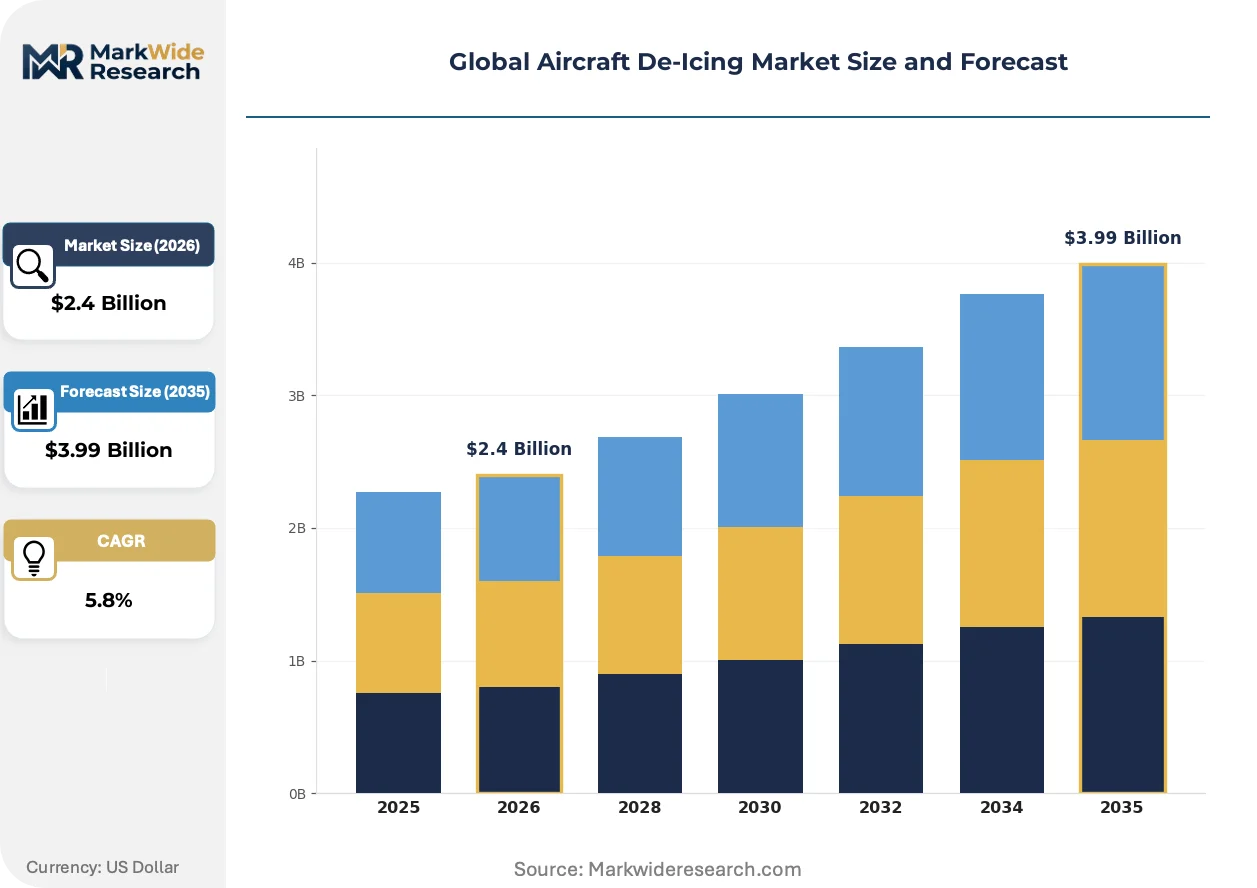
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluid, Heated Element, Mechanical System, Spray System Application: Commercial Aviation, Cargo Operations, Military Aviation, General Aviation End User: Airlines, Maintenance Providers, Airports, Ground Handling Services Technology: Electro-thermal, Infrared, Chemical De-Icing, Fluid De-Icing |
| Companies Covered | Collins Aerospace, JBT Corporation, BASF SE, Clariant AG, Vestergaard Company, Kilfrost Ltd., Global Ground Support LLC, Cryotech Deicing Technology, UTC Aerospace Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft De-Icing Market Strategic Shifts & Innovations
Product development is increasingly defined by a dual focus on environmental sustainability and operational precision. Innovations are geared toward minimizing chemical runoff through biodegradable formulations and reducing fluid consumption via smarter application technologies, directly addressing regulatory pressures and airline cost-control initiatives.
Electro-thermal systems, which use resistive heating elements embedded within wing and tail surfaces, offer a chemical-free method for preventing ice accretion. This technology is gaining favor in the general aviation and unmanned aerial vehicle sectors, where ground infrastructure is often unavailable. The market's technological trajectory is migrating from a complete reliance on external chemical application toward a hybrid approach where embedded systems are used for anti-icing on specific airframes.
Europe's REACH regulation, administered by the European Chemicals Agency (ECHA), is a powerful force influencing fluid composition. The framework mandates rigorous evaluation of the environmental and health impacts of chemical substances, effectively pushing certain additives and glycol types out of the market. Consequently, the product development pipeline for fluids sold in Europe is heavily skewed toward propylene glycol-based solutions with lower toxicity profiles.
A notable shift in airport ground handling involves moving from discrete equipment and fluid purchases to all-inclusive, long-term service agreements. This model transfers the responsibility for vehicle maintenance, fluid inventory management, and operational readiness to a single specialized provider. This approach is most prominent at major international airports in the United States and Germany, where predictable performance and cost management are critical during peak winter travel seasons.
Global Aircraft De-Icing Market Segmentation
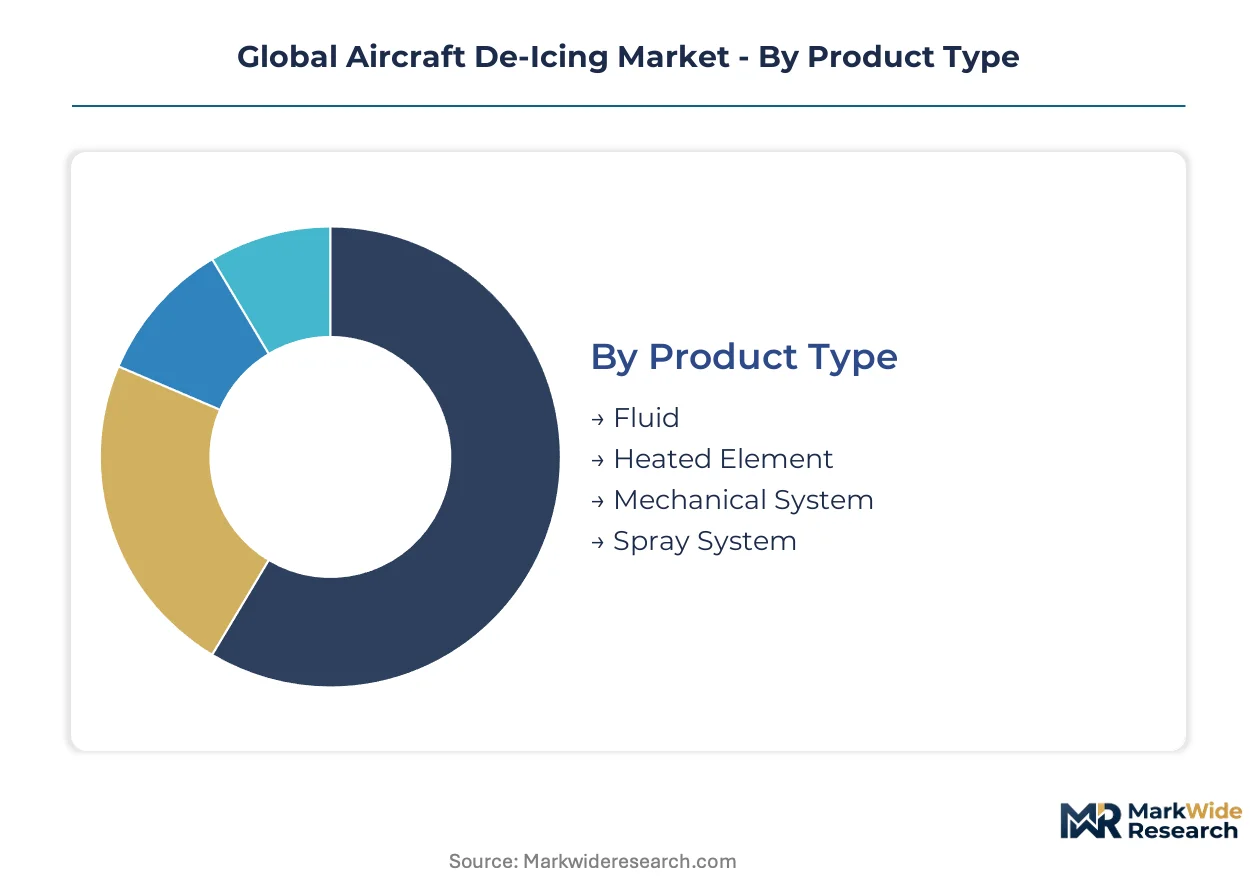
Understanding the distinct segments within the aircraft de-icing market provides clarity on where demand originates and how different solutions cater to specific operational needs. This granular view helps stakeholders align their strategies with prevailing product preferences, application requirements, and end-user demands across various aviation sectors.
Product Type:
The use-case spectrum for de-icing solutions ranges from chemical application for immediate ice removal to preventative heating elements integrated into aircraft structures.
- Fluid:These solutions involve the application of chemical mixtures, primarily propylene or ethylene glycol, to aircraft surfaces for both de-icing (ice removal) and anti-icing (prevention of ice formation). Demand concentrates at major commercial airports in the United States and Germany, driven by the need for rapid turnaround times and adherence to FAA and EASA safety protocols.
- Heated Element:This category encompasses electro-thermal systems embedded within aircraft components, such as wings and tail surfaces, using resistive heating to prevent ice accumulation. Adoption is gaining traction in general aviation and military applications where ground support is often limited, offering a chemical-free de-icing approach.
- Mechanical System:These systems involve physical removal methods, often used for snow or loose ice, typically employing brushes or pneumatic boots. They are commonly found in smaller airfields or for preliminary clearing before chemical treatment.
- Spray System:Specialized equipment designed for efficient and controlled application of de-icing fluids, optimizing coverage and reducing chemical waste. These systems are critical for large commercial aircraft operations.
Established volume favors Fluid; emerging adoption favors Heated Element.
Application:
Volume concentration dictates the scale and type of de-icing operations, with commercial aviation representing the largest segment due to its extensive flight schedules and passenger volume.
- Commercial Aviation:This segment includes de-icing for passenger and cargo flights operated by major airlines, requiring high-volume fluid application and specialized ground support equipment. Demand is particularly high in regions like Canada and northern Europe, where harsh winter conditions are frequent.
- General Aviation:De-icing services for private jets, charter planes, and smaller aircraft, often utilizing more flexible and sometimes integrated solutions like electro-thermal systems. This application prioritizes flexibility and on-demand services.
- Cargo Operations:De-icing for dedicated freight aircraft, which often operate on different schedules and routes than passenger flights, requiring robust and reliable de-icing to maintain supply chain integrity. These operations are critical at major logistics hubs.
- Military Aviation:Specialized de-icing for military aircraft, often involving unique operational requirements and sometimes more rugged or integrated systems suitable for diverse environments. This segment emphasizes operational readiness and mission capability.
Demand in Commercial Aviation drives the majority of revenue, while General Aviation presents specialized growth pockets.
End User:
Customer type defines the procurement and operational models for de-icing services and equipment, ranging from direct aircraft operators to specialized service providers.
- Airports:As central infrastructure providers, airports manage de-icing pads, fluid collection systems, and often contract or directly provide de-icing services to airlines. Major hubs in the United States and Germany invest heavily in compliant facilities and equipment.
- Airlines:The direct beneficiaries of de-icing services, airlines prioritize operational efficiency, safety compliance, and cost-effectiveness in their de-icing procedures. They often influence equipment specifications and fluid choices through their service agreements.
- Maintenance Providers:Companies specializing in aircraft maintenance often integrate de-icing services as part of their broader ground handling and operational support offerings. These providers require reliable equipment and fluid supply.
- Ground Handling Services:These entities execute the physical de-icing operations on behalf of airlines or airports, requiring skilled personnel and access to de-icing vehicles and fluids. Their efficiency directly impacts flight schedules.
Procurement decisions by Airports influence equipment sales, whereas Airlines focuses on operational efficiency.
Technology:
The maturity of de-icing technologies varies, with fluid-based methods being well-established and newer electro-thermal systems gaining prominence for specific applications.
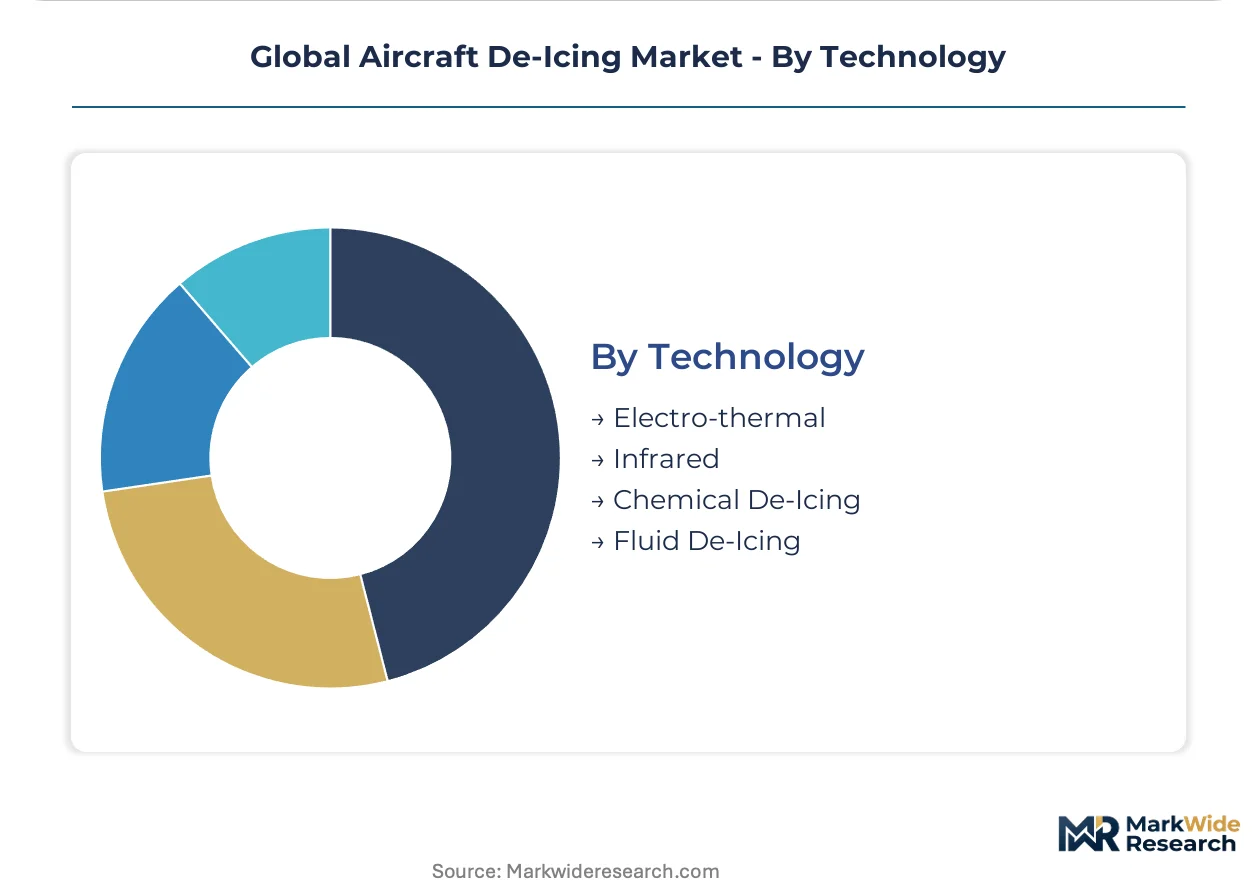
- Fluid De-Icing:This category encompasses the widely used chemical application methods, employing propylene or ethylene glycol-based fluids to remove and prevent ice on aircraft surfaces. This technology remains the industry standard for commercial aircraft due to its effectiveness and adaptability.
- Electro-thermal:Utilizing electric heating elements embedded within aircraft surfaces, this technology prevents ice formation by maintaining surface temperatures above freezing. It represents a chemical-free alternative, particularly for new aircraft designs in general aviation.
- Chemical De-Icing:A broad term for de-icing methods that rely on chemical agents to lower the freezing point of water and melt ice. This is closely related to fluid de-icing but can also include solid chemical applications in some contexts.
- Infrared:This technology uses infrared radiation to heat and remove ice from aircraft surfaces, offering a non-contact method. Infrared systems are under development for specific applications, aiming for energy efficiency.
Traditional methods like Fluid De-Icing maintain market share, while advanced systems such as Electro-thermal attract investment for future applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power exhibits asymmetry within the global aircraft de-icing market. European markets, particularly Germany, face higher compliance costs due to REACH regulations, influencing fluid pricing. Conversely, the United States prioritizes rapid turnaround times and operational efficiency, shaping its procurement models.
United States
The United States market drives significant demand for fluid-based de-icing solutions, particularly at its extensive network of commercial airports. FAA safety mandates enforce strict pre-flight de-icing protocols, making the process non-discretionary for airlines. Major hubs such as Chicago O'Hare and Denver International Airport continuously invest in compliant de-icing pads and equipment.
Canada
Canada experiences high demand for de-icing fluids and ground support equipment due to its severe winter conditions and expanding flight routes. Transport Canada regulations ensure rigorous de-icing procedures are followed for safe operations. Airports in Toronto and Montreal frequently upgrade their de-icing infrastructure to manage peak winter travel.
Germany
German airports, including Frankfurt and Munich, exhibit robust demand for de-icing services, driven by their status as major European aviation hubs. Europe's REACH regulation, enforced by ECHA, significantly influences the chemical composition of fluids used. These airports prioritize sustainable, propylene glycol-based solutions to meet stringent environmental controls.
France
French commercial aviation operations generate consistent demand for de-icing, particularly at its primary international gateways. EASA safety standards dictate the precise application of de-icing and anti-icing fluids across all flights. Paris Charles de Gaulle Airport, a critical European hub, focuses on optimizing fluid application for operational efficiency.
Global Aircraft De-Icing Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing specialized fluids and equipment. This market exhibits a tiered structure, with established players dominating integrated solutions and niche firms innovating in specific product types. Strategic archetypes include comprehensive service providers, specialized fluid manufacturers, and advanced equipment developers. Market participants pursue strategic partnerships and portfolio diversification to enhance their service offerings.
Within the integrated solutions segment, JBT Corporation exemplifies leadership in de-icing vehicle and equipment systems, anchoring a significant portion of airport ground support operations. Clariant AG, a Switzerland-based chemical company, represents a key player in high-performance propylene glycol-based fluid manufacturing, particularly for major European airports, where environmental regulations are stringent. Vestergaard Company, headquartered in Denmark, occupies a strategic position by leveraging its combined truck and fluid application technology to secure long-term service contracts with international airports, emphasizing operational efficiency and reliable service delivery.
| Leading Market Players |
|---|
| Collins Aerospace |
| JBT Corporation |
| BASF SE |
| Clariant AG |
| Vestergaard Company |
| Kilfrost Ltd. |
| Global Ground Support LLC |
| Cryotech Deicing Technology |
| UTC Aerospace Systems |
| Others |
Cost & Logistics Intelligence
Upstream volatility in petrochemical markets for propylene and ethylene glycol concentrates margin pressure on fluid manufacturers. This upstream cost uncertainty directly impacts downstream operational budgets for airlines and ground handling services, influencing procurement decisions.
Pricing Analysis
Configured-to-order pricing dominates for specialized de-icing vehicles and integrated service contracts, while per-unit transactional pricing applies to de-icing fluids. Price differentiation stems from the volume scale of fluid purchases and the inclusion of after-sales service for equipment. Pricing softness reflects intense competition among fluid suppliers and equipment manufacturers, particularly for standardized products. Airlines are highly price-sensitive for fluid costs, while airports prioritize long-term value for comprehensive integrated service contracts.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are increasingly common, particularly for long-term airport contracts. The supply of de-icing fluids draws from global petrochemical hubs, with specialized equipment manufacturing concentrated in the United States and Germany. Raw material dependencies include propylene glycol, ethylene glycol, and advanced vehicle components. Commodity price volatility for glycols represents a structural risk, alongside regulatory restrictions like Europe's REACH framework. Direct supply agreements between fluid manufacturers and major airport authorities define the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft de-icing market is in an early-cycle expansion, driven by the increasing penetration of commercial aviation into colder climates. This expansion creates sustained demand for both fluids and equipment.
For Market Incumbents: Pre-empt environmental regulatory shifts by accelerating investment in biodegradable fluid R&D and securing SAE AMS certifications for new formulations. Expand integrated service contracts to major international airports, bundling equipment, fluid supply, and maintenance to counter emerging electro-thermal technologies. Control distribution channels through strategic partnerships with ground handling services, mitigating margin pressure from new entrants.
For New Entrants and Emerging Players: Build out specialized offerings in niche segments like electro-thermal systems for general aviation, where ground infrastructure is limited. Target regional airports and Fixed-Base Operators (FBOs) with flexible, on-demand de-icing solutions. Focus on developing sensor-driven application systems to reduce fluid waste and demonstrate cost efficiencies. A direct-to-customer sales model emphasizing environmental compliance and operational savings offers a strong go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized fluid manufacturers and integrated service providers benefiting from non-discretionary safety mandates. This market offers sustainable demand over the next decade. Target acquisition archetypes include companies with strong intellectual property in biodegradable fluids or those holding long-term service contracts at critical aviation hubs. Regulatory tightening around fluid discharge serves as a key signal to watch, indicating accelerated adoption of sustainable alternatives and potential for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Fluid R&D | Reduces environmental impact and ensures compliance with evolving ECHA regulations. |
| Integrated Service Expansion | Secures long-term revenue streams by bundling equipment, fluids, and maintenance for major airports. |
| Sensor-Driven Application | Optimizes fluid usage, minimizing waste and operational costs for ground handlers. |
| Electro-thermal System Development | Targets the growing general aviation market with chemical-free de-icing solutions. |
| SAE AMS Certification Investment | Lowers entry barriers for new fluid formulations, accelerating market access. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary insights were gathered from airport operations managers, airline procurement heads, fluid chemists, and ground support equipment engineers. Secondary research leveraged FAA safety bulletins, ECHA REACH documentation, SAE International specifications, and company annual reports. This approach ensured bottom-up and top-down triangulation of market data.
Forecast inputs considered historical growth trends, projected commercial aviation expansion, and evolving regulatory landscapes across the analysis window. The analytical framework modeled market segmentation across product type, application, end-user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from a detailed assessment of market drivers and restraints. Key industry-specific forecast inputs included commercial aviation flight growth and environmental compliance costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major equipment manufacturers or fluid innovators would shift outcomes. Forecasts reflect assumptions regarding stable petrochemical feedstock prices and continued regulatory enforcement. Unforeseen changes in these factors, or rapid adoption of alternative de-icing technologies, could revise projections. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Global Aircraft Heat Exchanger Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Tanker Aircraft Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aviation Market
Aircraft
Flight Management Systems Market
Aircraft
Europe Helicopters Market
Aircraft
Light and Very Light Jets Market
Aircraft
US Military Aviation Market
Aircraft
Evtol Aircraft Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
LAMEA Aircraft Band Clamps Market
Aircraft
Aircraft Door Market
Aircraft
Aircraft Leasing Market
Aircraft
India Winglets Market