
 South Korea Aerospace and Defense Market | 2026-2036
South Korea Aerospace and Defense Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Aerospace and Defense Market Analytics
Aerospace engineering talent is bifurcating between legacy airframe disciplines and emerging unmanned systems expertise, creating recruitment bottlenecks for prime contractors. Korea Aerospace Industries sustains the largest design-to-flight-test workforce in the nation, concentrating on KF-21 fighter development. Hanwha Aerospace dominates land systems and artillery manufacturing, leveraging its Jeonju plant for tracked vehicle output. LIG Nex1 specializes in precision munitions and radar systems, occupying a critical tier in the domestic supply chain.
South Korea Aerospace and Defense encompasses the research, engineering, production, and sustainment of military aircraft, missiles, naval platforms, ground vehicles, and their associated electronics, typically requiring titanium alloy airframes, composite wing structures, and AESA radar architectures operating in X-band frequencies. The sector serves national security objectives through deterrence, territorial defense, and power projection capabilities. Aircraft within the product type dimension commands the largest share of current procurement budgets, while missiles represents the fastest-growing category driven by precision strike modernization. Defense electronics within the technology dimension concentrates margin pools, as semiconductor content in guided munitions and sensor fusion systems expands faster than platform hull costs.
MFDS standards govern aerospace material certification, while DAPA acquisition regulations mandate progressive domestic content thresholds for foreign platform selections. KOSPI disclosure requirements and the Defense Technology Security Act shape how Korean firms partner with overseas primes and protect sensitive capabilities. Stakeholders must track how Seoul recalibrates offset rules and technology transfer terms as indigenous platform maturity reduces reliance on foreign subsystem imports.
Market Dynamics
Seoul's Defense Acquisition Program Administration is tightening domestic content mandates for foreign platform selections, forcing technology transfer negotiations toward Korean subsystem suppliers and reshaping procurement economics across the aerospace cluster.
Growth Catalysts
- Indigenous fighter programs:The KF-21 development program sustains demand for titanium alloy airframes and composite wing structures, anchoring procurement volume at Korea Aerospace Industries' Sacheon facility.
- MFDS material certification:Streamlined aerospace-grade alloy approval processes are compressing supplier qualification timelines and accelerating domestic foundry capacity expansion.
- Precision strike modernization:AESA radar architectures and semiconductor-intensive guided munitions are absorbing R&D budgets faster than legacy platform hull investments.
Market Restraints
- Titanium sponge import dependence:Korean smelters source over seventy percent of feedstock from overseas, exposing margin structures to volatile commodity pricing and freight disruptions.
- Single-source radar component supply:X-band transmit/receive module fabrication concentrates in a narrow supplier base, creating vulnerability for active electronically scanned array production schedules.
- Defense Technology Security Act constraints:Export licensing requirements for sensitive subsystems limit Korean primes from capturing offset work on foreign platform sales.
Strategic Opportunities
- Busan naval shipyard ecosystem:Underutilized heavy fabrication capacity offers entry points for aerospace structural component manufacturing with minimal retooling investment.
- Unmanned systems convergence:Manned-unmanned teaming architectures are opening procurement channels for Korean firms with legacy avionics expertise to pivot into loyal wingman development.
- DAPA offset rule recalibration:Pending adjustments to technology transfer terms may permit Korean suppliers to retain intellectual property from foreign joint ventures previously subject to repatriation clauses.
Industry Challenges
- Aerospace engineering bifurcation:Workforce development programs struggle to produce sufficient unmanned systems software architects while maintaining legacy airframe structural engineering depth.
- Flight-test infrastructure saturation:Sacheon airfield capacity constraints are compressing prototype evaluation schedules for multiple concurrent indigenous programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Aerospace and Defense Market |
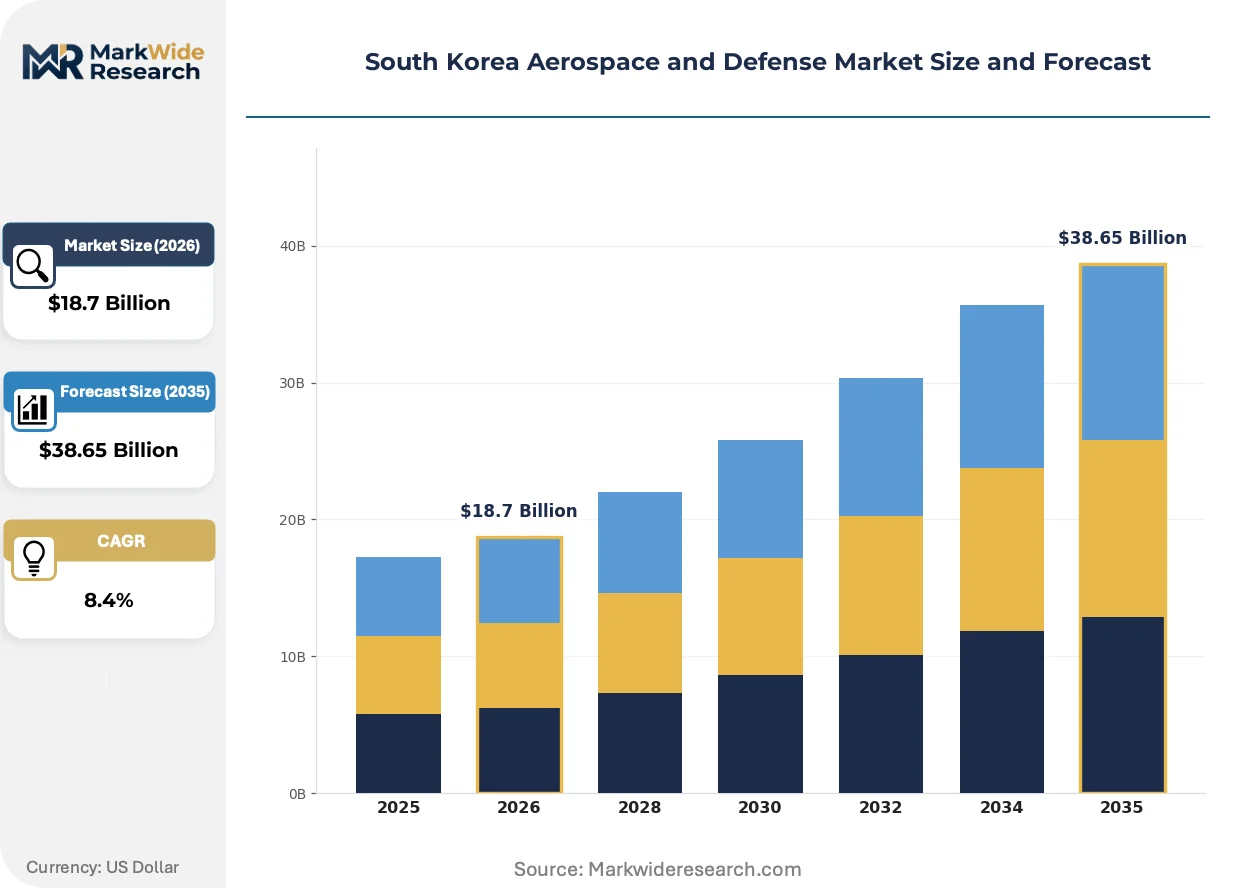
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aircraft, Missiles, Naval Systems, Ground Vehicles Technology: Aerospace Systems, Defense Electronics, Cybersecurity Solutions, Navigation Systems End User: Government Agencies, Military Contractors, Research Institutions, Private Defense Firms Application: Surveillance, Combat Operations, Transport, Training |
| Companies Covered | Hyundai Heavy Industries, Boeing, Korea Aerospace Industries, Korean Air, Hyundai Rotem, Hanwha Aerospace, Lockheed Martin, Poongsan, LIG Nex1, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Aerospace and Defense Market Evolving Landscape
Active electronically scanned array architectures are penetrating platforms previously served by mechanically scanned systems, redistributing value capture toward semiconductor suppliers and away from precision machining houses.
Silicon carbide power electronics are supplanting silicon-based thermal management in radar transmitter modules. DAPA procurement officers are mandating these upgrades in next-generation fighter subsystems. The shift is compressing qualification timelines for traditional foundry suppliers while elevating compound semiconductor fabricators in domestic supply chain negotiations.
The Defense Technology Security Act is tightening scrutiny over foreign partnership structures. Korean primes now face extended compliance reviews when licensing sensitive capabilities to overseas joint venture partners. Small-to-medium subsystem suppliers in the Sacheon cluster are responding by deepening captive engineering capacity rather than pursuing technology import arrangements.
Acquisition officers at the Republic of Korea Air Force are unbundling long-term sustainment contracts from initial platform procurement. Fixed-price logistics arrangements are displacing cost-plus through-life support agreements for indigenous aircraft. The shift is most visible in KF-21 program contracting, where Hanwha Aerospace and Korea Aerospace Industries compete separately for airframe production and depot maintenance work packages.
South Korea Aerospace and Defense Market Segmentation
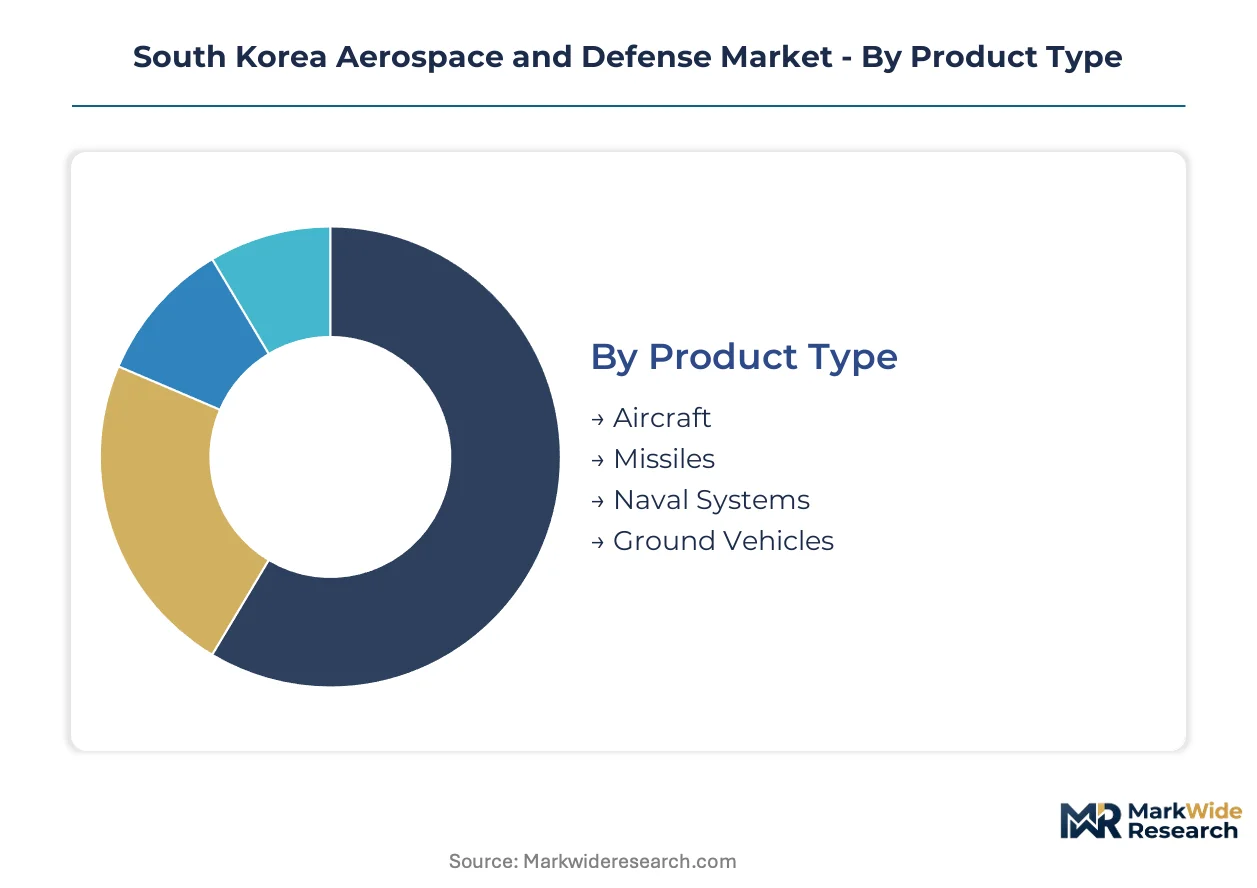
Procurement flows through distinct channels that reshape how Korean primes structure their bidding strategies. Defense Acquisition Program Administration contracting tiers favor different segment combinations, with technology content often unbundled from platform hull awards.
Product Type:
Aircraft and missiles move through DAPA's major program procurement channel, while naval systems and ground vehicles route through separate service-specific acquisition offices with diverging domestic content thresholds.
- Aircraft:Titanium alloy airframes and composite wing structures dominate material specifications for indigenous fighter programs. Republic of Korea Air Force modernization concentrates demand at Korea Aerospace Industries' Sacheon facility, where KF-21 production anchors multi-year procurement schedules.
- Missiles:Precision-guided munitions integrate AESA radar seekers and compound semiconductor guidance packages. Hanwha Aerospace and LIG Nex1 compete for stand-off weapon contracts as precision strike modernization accelerates.
- Naval Systems:Busan shipyard heavy fabrication capacity supports frigate and destroyer hull construction.
- Ground Vehicles:Tracked artillery and armored platforms sustain Jeonju plant output for Hanwha Aerospace.
By volume, aircraft leads procurement budgets. By growth pace, missiles is climbing the fastest as precision strike capabilities absorb R&D investment.
Technology:
Margin pools concentrate in semiconductor-intensive layers rather than mechanical subsystems, redistributing supplier power toward compound fabricators and away from precision machining houses.
- Aerospace Systems:Flight control actuators and environmental control units require MFDS-certified materials. Korea Aerospace Industries maintains captive design capacity for these mechatronic packages.
- Defense Electronics:Silicon carbide power electronics displace silicon-based thermal management in radar transmitters. DAPA mandates these upgrades in next-generation fighter subsystems, compressing qualification timelines for traditional foundries.
- Cybersecurity Solutions:Defense Technology Security Act compliance requirements shape foreign partnership structures.
- Navigation Systems:GPS-denied positioning architectures attract investment for contested environment operations.
Aerospace systems capture the largest share of current platform integration contracts. Defense electronics is expanding most quickly as semiconductor content rises faster than hull costs.
End User:
Contracting authority fragmentation across DAPA, service acquisition offices, and research funding streams creates distinct customer segments with incompatible procurement timelines.
- Government Agencies:DAPA and Republic of Korea Air Force Material Command issue platform-level procurements with multi-year appropriation cycles. These customers mandate progressive domestic content thresholds that reshape technology transfer negotiations.
- Military Contractors:Hanwha Aerospace and Korea Aerospace Industries subcontract precision components to Sacheon cluster suppliers, creating tiered supply relationships beneath prime contract awards.
- Research Institutions:Agency for Defense Development funds technology maturation prior to production qualification.
- Private Defense Firms:Emerging unmanned systems specialists compete for loyal wingman development contracts outside traditional platform hierarchies.
Government agencies dominate committed procurement volume. Private defense firms are gaining share fastest as unmanned systems open new vendor entry points.
Application:
Mission type determines subsystem packaging requirements, with surveillance platforms prioritizing sensor endurance and combat applications demanding hardened electronic architectures.
- Surveillance:AESA radar and signals intelligence payloads require extended loiter endurance. Republic of Korea Air Force airborne early warning programs concentrate demand for these integrated sensor packages.
- Combat Operations:Supersonic maneuverability and low-observable signatures drive KF-21 design specifications. Thermal management for high-power radar operation constrains airframe geometry choices.
- Transport:Tactical airlift and maritime patrol variants share common fuselage structures with mission-specific avionics swaps.
- Training:Jet trainer procurement sustains light fighter derivative production at reduced specification tiers.
Combat operations absorbs the largest development investment. Surveillance is expanding most quickly as sensor fusion architectures proliferate across platform types.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS certification standards anchor South Korea's aerospace regulatory framework, while DAPA procurement rules reshape domestic content requirements across the nation's defense industrial base. The market concentrates in metropolitan clusters where shipbuilding heritage, automotive supply chains, and government research institutions intersect.
Seoul Capital Area
Defense Acquisition Program Administration headquarters and Agency for Defense Development research campuses drive procurement policy formulation. The Defense Technology Security Act compliance reviews concentrate here, extending licensing timelines for foreign joint ventures. Pangyo Techno Valley hosts emerging unmanned systems software architects competing for loyal wingman development contracts.
Busan-Ulsan
Naval shipyard heavy fabrication capacity offers retooling entry points for aerospace structural components. Hyundai Heavy Industries anchors maritime platform construction, while underutilized welding and metallurgy infrastructure attracts airframe subsystem suppliers. The national government targets this corridor for defense manufacturing diversification beyond shipbuilding.
Sacheon-Gyeongsangnam-do
Korea Aerospace Industries' final assembly and flight-test operations anchor the national fighter modernization program. Titanium alloy airframe production and composite wing fabrication concentrate at this facility, with local supplier networks feeding precision machining and avionics integration. Flight-test infrastructure saturation here compresses prototype evaluation schedules.
Daegu-Gyeongbuk
Precision munitions and radar component suppliers cluster around legacy electronics manufacturing infrastructure. LIG Nex1 maintains specialized facilities for AESA radar architectures and semiconductor-intensive guidance packages. The region's compound semiconductor fabricators gain negotiating leverage as silicon carbide power electronics displace silicon-based thermal management.
Daejeon-Sejong
Agency for Defense Development research funding streams and technology maturation programs concentrate in this administrative hub. Government research institutions here shape pre-competitive technology roadmaps that downstream suppliers must anticipate. Sejong's regulatory proximity accelerates MFDS aerospace material certification approvals for domestic foundries.
South Korea Aerospace and Defense Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Korea's aerospace and defense sector. The market structure bifurcates between indigenous platform primes with captive design capacity and foreign system integrators supplying offset arrangements. Three archetypes dominate: state-linked conglomerates with diversified industrial holdings, specialized defense electronics houses with semiconductor expertise, and foreign primes operating through technology transfer joint ventures. Competitive positioning hardens through DAPA domestic content mandate compliance and in-house production of critical subsystems previously imported.
Among Korean-headquartered primes, Korea Aerospace Industries, Hanwha Aerospace, and LIG Nex1 occupy distinct tier positions. Korea Aerospace Industries exemplifies the integrated platform developer archetype, anchoring final assembly and flight-test operations. Hanwha Aerospace represents the diversified industrial conglomerate model, spanning land systems and precision munitions. LIG Nex1 sits within the specialized defense electronics tier, concentrating margin capture in semiconductor-intensive radar and guidance architectures. Foreign primes including Boeing and Lockheed Martin operate through offset structures subject to Defense Technology Security Act licensing constraints.
| Leading Market Players |
|---|
| Hyundai Heavy Industries |
| Boeing |
| Korea Aerospace Industries |
| Korean Air |
| Hyundai Rotem |
| Hanwha Aerospace |
| Lockheed Martin |
| Poongsan |
| LIG Nex1 |
| Others |
Value Network & Pricing Analysis
Korea Aerospace Industries' Sacheon facility generates scale economies in titanium alloy airframe fabrication that compress unit costs for indigenous fighter programs while elevating price floors for foreign subsystem imports subject to DAPA domestic content mandates.
Pricing Analysis
Geographic price spreads separate Busan shipyard structural component quotes from Sacheon precision-machined airframe assemblies by certification tier and MFDS material traceability. Contract-based long-term offtake dominates prime procurement, with price differentiation driven by domestic content thresholds and compound semiconductor content in radar subsystems. Cost compression in legacy mechanical subsystems intensifies as silicon carbide power electronics displace silicon-based thermal management. Military contractors exhibit lowest price sensitivity for AESA radar modules, while training aircraft procurement shows highest elasticity to specification tier adjustments.
Supply Chain Analysis
Extended lead times for titanium sponge feedstock strain Korean foundry scheduling, with inventory buffers insufficient to offset volatile commodity freight disruptions. Supply draws from Japan, Kazakhstan, and China for titanium sponge, while X-band transmit/receive modules rest on single-source domestic fabrication. Single-source vulnerability concentrates in semiconductor-intensive guidance packages. Distribution runs through DAPA-tiered contracting channels that unbundle platform hull awards from technology content procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through DAPA's progressive domestic content mandates, fragmenting foreign prime negotiating leverage while elevating Korean subsystem suppliers in technology transfer arrangements.
For Market Incumbents: Fortify captive engineering capacity for AESA radar architectures and compound semiconductor fabrication before DAPA offsets rules recalibrate intellectual property retention terms. Deepen backward integration into titanium alloy foundry operations to mitigate import feedstock volatility. Lock in long-term sustainment contracts as Republic of Korea Air Force unbundles depot maintenance from initial platform awards.
For New Entrants and Emerging Players: Anchor in Busan-Ulsan underutilized heavy fabrication capacity for aerospace structural component manufacturing with minimal retooling investment. Target loyal wingman development contracts where manned-unmanned teaming architectures open procurement channels outside traditional platform hierarchies. Pursue MFDS material certification early to compress supplier qualification timelines for domestic foundry expansion.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized defense electronics houses with semiconductor expertise over diversified industrial conglomerates exposed to land systems margin compression. Five-to-ten year viability hinges on compound semiconductor fabrication scale and DAPA compliance infrastructure. Watch for Defense Technology Security Act licensing timeline extensions as inflection indicators for foreign joint venture profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Foundry Capacity | Captive sponge-to-alloy production reduces exposure to Kazakhstan and Japan import volatility. |
| Silicon Carbide Power Electronics Scale-Up | DAPA-mandated radar subsystem upgrades elevate compound semiconductor fabricators in supply negotiations. |
| MFDS Material Certification Acceleration | Streamlined aerospace-grade alloy approvals compress Sacheon cluster supplier qualification timelines. |
| Loyal Wingman Development Program Entry | Manned-unmanned teaming architectures open procurement channels for avionics heritage pivots. |
| Long-Term Sustainment Contract Unbundling | Fixed-price logistics arrangements displace cost-plus through-life support for KF-21 depot maintenance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with DAPA procurement officers, Korea Aerospace Industries program managers, Hanwha Aerospace plant engineers, LIG Nex1 radar subsystem architects, and Sacheon cluster precision machining suppliers. Secondary validation drew from MFDS aerospace material certification databases, DAPA acquisition regulation filings, Defense Technology Security Act licensing records, Agency for Defense Development research funding disclosures, and Republic of Korea Air Force modernization budget appropriations. Bottom-up platform production estimates and top-down defense expenditure allocations were triangulated to reconcile volume and value outputs.
Across the analysis window, forecasts model product type segmentation across aircraft, missiles, naval systems, and ground vehicles alongside technology tier differentiation between aerospace systems and defense electronics. CAGRs derive from indigenous platform production schedules, precision strike modernization investment trajectories, and semiconductor content expansion rates in guided munitions. Forecast inputs include KF-21 multi-year procurement volumes, AESA radar architecture penetration curves, and DAPA domestic content threshold escalations.
Decision-makers should treat outputs as directional under sustained indigenous fighter program funding and stable titanium sponge import access; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Afterburner Market
Aircraft
US Aviation Market
Aircraft
Commercial Aircraft Market
Aircraft
Aircraft Landing Gear Market
Aircraft
North America General Aviation Market
Aircraft
Aircraft Door Market
Aircraft
Europe Turboprop Aircraft Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
GCC General Aviation Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Cargo Compartment Latches Market
Aircraft
Wind Tunnel Market
Aircraft
America Attack Helicopter Market
Aircraft
Airplane Landing Gear Market