
 America Freighter Aircraft Market | 2026-2036
America Freighter Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
America Freighter Aircraft Market Outlook
Buyer concentration among e-commerce and express logistics operators is hardening across the Americas. FedEx Express anchors its fleet renewal strategy around high-utilization hub-and-spoke networks. Boeing competes through production scale and established conversion programs for passenger-to-freighter modifications. Airbus SE differentiates with factory-built dedicated freighter variants designed for fuel efficiency.
A freighter aircraft is a fixed-wing platform engineered exclusively or primarily for cargo transport, typically featuring reinforced floors, wide cargo doors, and nose or tail loading apertures to accommodate unit load devices and outsized freight. Dedicated freighter variants from original equipment manufacturers incorporate main-deck cargo handling systems and structural provisions absent in converted passenger airframes. Converted freighters occupy the largest installed base due to lower capital entry costs, while dedicated freighters command premium positioning where route density justifies factory-new acquisition. Turbofan-powered widebodies dominate transoceanic scheduled services, and turboprop segments sustain regional express networks with shorter runway requirements.
The FAA enforces airworthiness standards under 14 CFR Part 25 that govern freighter certification, conversion integrity, and operational limitations across United States airspace. ICAO Annex 16 Vol. III and EPA aviation emissions guidelines shape engine selection and fleet modernization timelines for operators serving North American routes. Stakeholders must weigh conversion economics against dedicated freighter availability as feedstock passenger aircraft age and environmental compliance tightens.
Market Dynamics
E-commerce parcel volumes are compressing aircraft utilization cycles across the Americas, forcing operators to accelerate fleet renewal timelines while ICAO Annex 16 Vol. III emissions standards simultaneously constrain engine selection.
Growth Catalysts
- ICAO Annex 16 Vol. III Compliance:The EPA's alignment with international aviation emissions standards is mandating cleaner-burning turbofan platforms, creating replacement demand for aging freighter fleets.
- Hub-and-Spoke Network Density:Express logistics operators are expanding dedicated cargo fleets to serve southeastern United States distribution centers anchored by Atlanta, Miami, and Memphis.
- Passenger-to-Freighter Conversions:Feedstock availability from retired widebody passenger aircraft is sustaining lower-capital entry paths for regional cargo operators.
Market Restraints
- Feedstock Scarcity:Aging passenger aircraft suitable for conversion are depleting as 14 CFR Part 25 certification timelines extend and source airframes accumulate flight-hour limitations.
- Engine Supply Concentration:Turbofan propulsion systems for widebody freighters concentrate among a narrow supplier base, exposing operators to delivery bottlenecks and pricing power asymmetries.
- Runway Infrastructure:Regional turboprop-dependent networks face operational constraints where airport pavement strength and instrument approach systems limit payload-maximum operations.
Strategic Opportunities
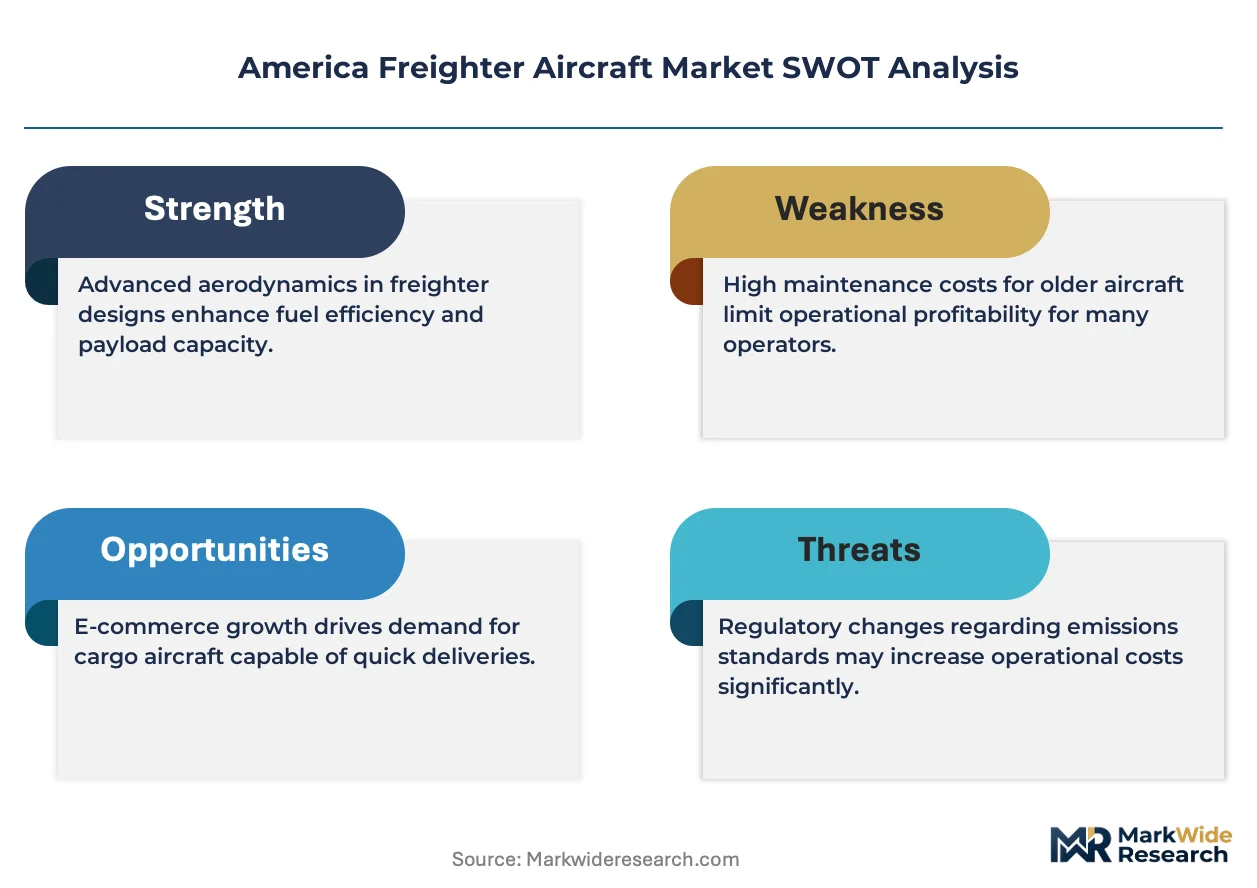
- Factory-Built Dedicated Freighters:Airbus SE's A350F and Boeing's 777-8F programs offer fuel efficiency advantages that reward route-density operators with sufficient volume to justify premium acquisition costs.
- Latin American Network Expansion:Underpenetrated cargo corridors connecting Miami to São Paulo, Bogotá, and Santiago present whitespace for scheduled freighter services.
- Sustainable Aviation Fuel Integration:The FAA's emissions certification pathways are creating early-mover advantages for operators securing SAF offtake agreements at major United States hubs.
Industry Challenges
- Conversion Certification Timelines:14 CFR Part 25 supplemental type certificate approvals for passenger-to-freighter modifications are extending lead times, compressing revenue windows for conversion specialists.
- Maintenance Technician Shortage:Specialized airframe and powerplant certification for widebody cargo systems is concentrating qualified labor at major United States maintenance, repair, and overhaul clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America Freighter Aircraft Market |
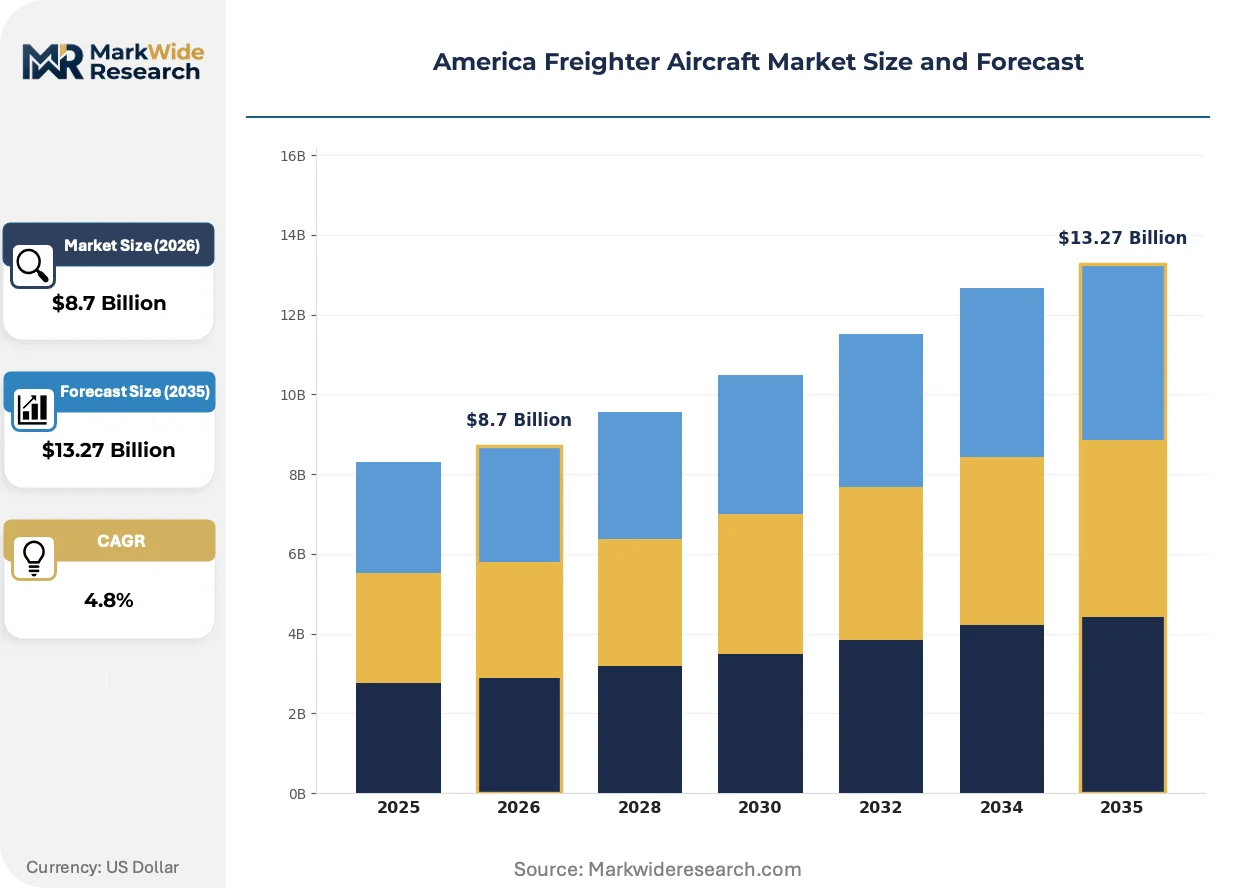
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Dedicated Freighter, Converted Freighter, Cargo Aircraft, Multi-Role Aircraft End User: Cargo Airlines, Freight Forwarders, E-Commerce Companies, Governments Technology: Turbojet, Turboprop, Jet Engine, Electric Propulsion Service Type: Scheduled Services, Charter Services, Express Delivery, Dedicated Operations |
| Companies Covered | Airbus SE, The Boeing Company, Textron Inc., ATR, Singapore Technologies Engineering Ltd., Embraer S.A., Lockheed Martin Corporation, Atlas Air Worldwide Holdings, Inc., FedEx Express (FedEx Corporation), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America Freighter Aircraft Market Strategic Shifts
Digital cargo tracking and predictive maintenance systems are compressing turnaround times at hub airports while sustainable aviation fuel infrastructure expands at major United States gateways.
Advanced loading systems and automated unit load device handling are unifying ground operations across hub-and-spoke networks. FedEx Express and UPS Airlines are deploying these platforms at Memphis and Louisville super-hubs to compress aircraft turnaround cycles below 45 minutes. This unifying technology is collapsing the operational gap between dedicated factory-built freighters and converted passenger aircraft, reshaping acquisition economics for mid-tier operators.
The FAA's enforcement of ICAO Annex 16 Vol. III emissions standards is accelerating engine retirement schedules for pre-2020 freighter fleets. Operators serving transoceanic routes face compressed compliance timelines, with widebody platforms most exposed to operating restriction risks. United States-based cargo carriers are prioritizing factory-new turbofan acquisitions over conversions to secure emissions-compliant propulsion.
Express logistics buyers are consolidating procurement around long-term capacity agreements with guaranteed uplift commitments. Regional cargo operators are losing spot-market leverage as e-commerce volume concentrates among three major United States networks. This pattern is most visible in the southeastern United States, where Atlanta and Miami gateways are capturing disproportionate freighter deployment.
America Freighter Aircraft Market Segmentation
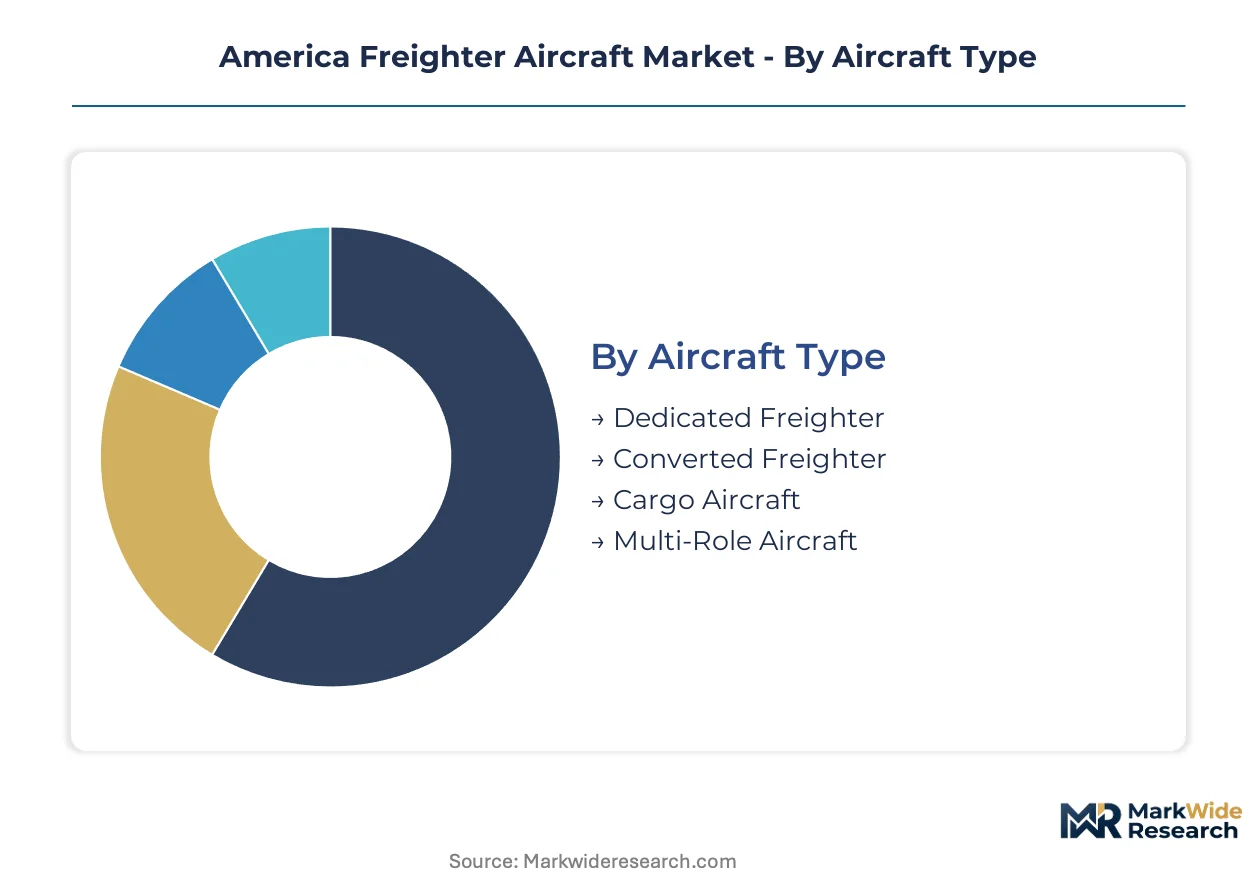
Freighter aircraft procurement patterns diverge sharply across operational profiles, with dedicated factory-built platforms commanding premium positioning against conversion economics. Segmentation reveals how e-commerce consolidation, emissions compliance timelines, and feedstock availability reshape fleet composition across the Americas.
Aircraft Type:
Customization intensity spans from purpose-engineered factory builds to modified passenger airframes with standardized conversion protocols.
- Dedicated Freighter:Factory-built airframes incorporate reinforced main-deck flooring, integrated cargo handling systems, and structural provisions absent in passenger conversions. Demand concentrates among FedEx Express and UPS Airlines operating high-utilization hub-and-spoke networks from Memphis and Louisville, where route density justifies premium acquisition against ICAO Annex 16 Vol. III compliance timelines.
- Converted Freighter:Passenger-to-freighter modifications exploit retired widebody feedstock from Boeing 767 and Airbus A330 platforms to lower capital entry costs. Regional cargo operators across the southeastern United States leverage these platforms where volume thresholds fail to support factory-new procurement.
- Cargo Aircraft:General-purpose freight platforms without dedicated freighter structural optimization serve intermittent charter demand and specialized outsized cargo requirements.
- Multi-Role Aircraft:Convertible configurations supporting rapid passenger-to-cargo reconfiguration address military and government contingency logistics with flexible mission profiles.
Most installed capacity flows through Converted Freighter platforms. Expansion is steepest in Dedicated Freighter acquisitions as emissions certification tightens.
End User:
Procurement scale concentrates among integrated networks with guaranteed volume commitments, while fragmented buyers compete for residual lift capacity.
- Cargo Airlines:Scheduled operators including Atlas Air and Kalitta Air deploy widebody turbofan fleets on transoceanic trunk routes, prioritizing fuel efficiency and emissions compliance for North Atlantic and transpacific corridors.
- Freight Forwarders:Non-asset-based logistics providers including DHL Global Forwarding and Kuehne+Nagel charter capacity on spot markets or contract block space agreements, exposing them to rate volatility during peak e-commerce seasons.
- E-Commerce Companies:Amazon Air and similar platforms operate captive freighter fleets to control last-mile delivery velocity, with network design centered on Amazon's Cincinnati/Northern Kentucky hub.
- Governments:Military and humanitarian operators acquire multi-role platforms through defense procurement channels, with requirements emphasizing unpaved runway capability and rapid reconfiguration timelines.
Contractual volume commitments from E-Commerce Companies are reshaping manufacturer delivery priorities. Charter exposure among Freight Forwarders is compressing as long-term agreements harden.
Technology:
Propulsion selection reflects runway infrastructure constraints against route distance and payload requirements.
- Turbojet:High-bypass turbofan engines dominate widebody freighter applications, with Pratt & Whitney and General Electric powerplants delivering thrust efficiency for transcontinental and intercontinental stage lengths.
- Turboprop:Regional express networks including FedEx Feeder operations deploy ATR 72-600F and similar platforms from short-runway airports across the Caribbean and Central America where pavement strength limits jet operations.
- Jet Engine:Medium-thrust turbofan variants power narrowbody converted freighters on domestic US routes with balanced fuel burn and speed requirements.
- Electric Propulsion:Battery-electric and hybrid-electric architectures remain developmental, with FAA certification pathways for sub-regional cargo applications targeting intra-state distribution networks.
Turbofan platforms carry the revenue ton-mile majority. Turboprop deployment is climbing fastest in Latin American network expansion.
Service Type:
Operating model selection determines asset utilization intensity and exposure to spot market cyclicality.
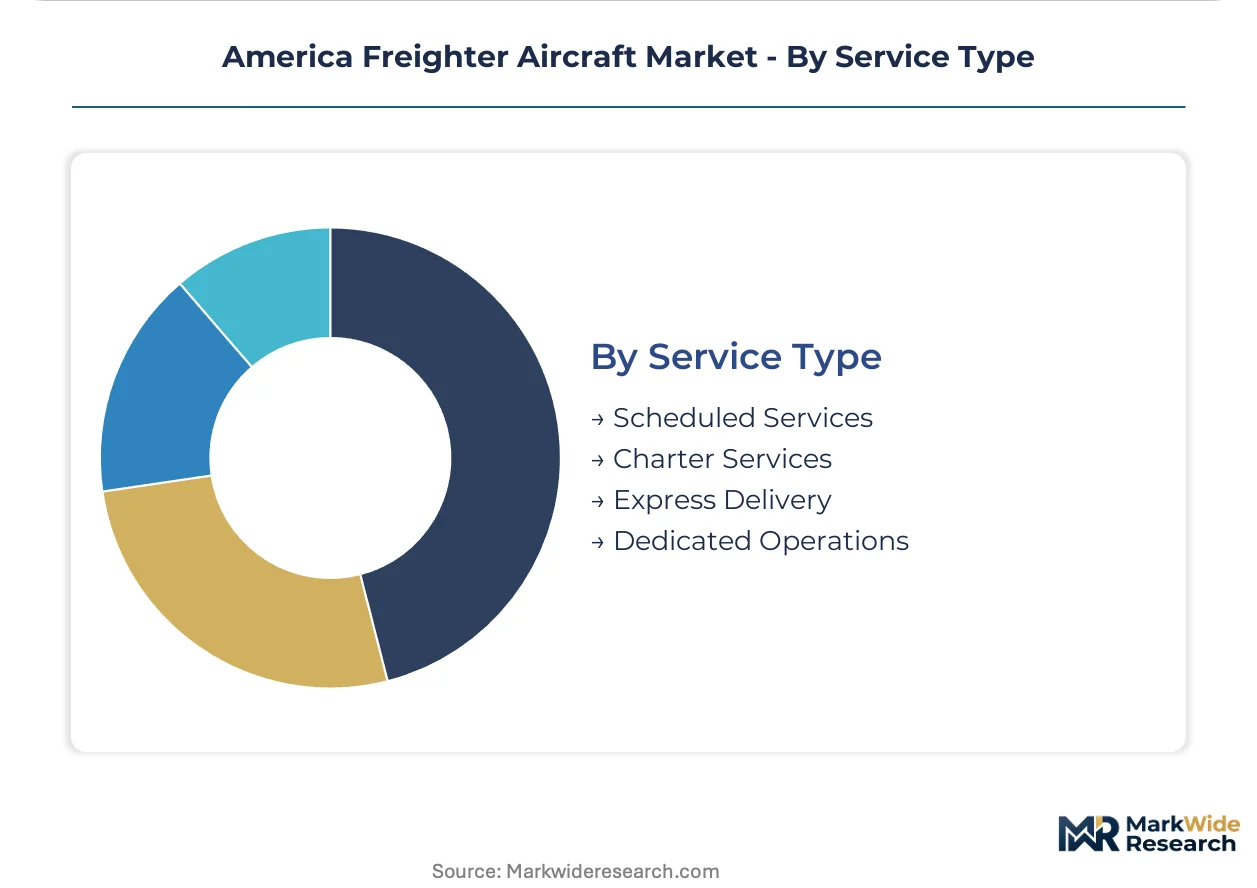
- Scheduled Services:Fixed-route, fixed-frequency operations anchor integrated carrier networks with predictable demand patterns and contracted yield management.
- Charter Services:Ad-hoc capacity deployment serves project cargo, humanitarian relief, and peak season overflow with premium pricing volatility.
- Express Delivery:Time-definite overnight and second-day services drive the highest aircraft utilization rates, with Memphis, Louisville, and Indianapolis super-hubs compressing turnaround cycles below 45 minutes.
- Dedicated Operations:Single-customer captive fleets including Amazon Air and DHL Express provide guaranteed capacity with eliminated third-party exposure.
Scheduled Services absorb the freighter-hour majority. Dedicated Operations are expanding most quickly as e-commerce vertical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands freighter fleet scale unmatched elsewhere in the Americas, while Brazil's cargo corridor development accelerates toward Miami hub connections. Canada maintains conversion specialization through Montreal-area engineering clusters. Mexico's manufacturing export growth drives narrowbody freighter demand across its central industrial belt.
United States
Memphis, Louisville, and Cincinnati super-hubs anchor FedEx Express and Amazon Air captive fleets with 45-minute turnaround protocols. The FAA enforces ICAO Annex 16 Vol. III emissions certification through 14 CFR Part 25 standards, forcing pre-2020 turbofan retirements. Atlanta's Hartsfield-Jackson corridor concentrates A350F and 777-8F deliveries as southeastern distribution density justifies factory-new acquisition premiums.
Brazil
São Paulo-Guarulhos cargo volume surges on e-commerce import flows from Miami and Panama City. ANVISA coordinates with the national civil aviation authority on freighter operational safety alongside EPA-aligned emissions benchmarks for international route access. The Campinas-Viracopos cluster hosts ATR 72-600F turboprop deployment for regional express networks serving the interior.
Canada
Montreal-area conversion specialists exploit retired Boeing 767 and A330 passenger feedstock from North American carrier retirements. Transport Canada aligns airworthiness certification with FAA 14 CFR Part 25 standards for seamless cross-border freighter operations. Vancouver International anchors transpacific cargo flows with dedicated freighter parking infrastructure and sustainable aviation fuel blending capabilities.
Mexico
Querétaro and Guadalajara manufacturing export growth compresses narrowbody freighter utilization on US-Mexico cross-border routes. The Secretariat of Infrastructure, Communications and Transport coordinates with FAA on bilateral airworthiness recognition for converted freighter imports. Mexico City International's slot constraints push cargo operators toward alternate hubs at Monterrey and Puebla with expanded runway capacity.
America Freighter Aircraft Market Competitive Environment
United States producers anchor one tier through Boeing's Everett and Charleston assembly lines; European specialists hold factory-built freighter positioning through Airbus SE's Toulouse operations. The market structures around two dominant archetypes: original equipment manufacturers with dedicated freighter programs, and conversion specialists exploiting passenger feedstock retirements. Capacity expansion and strategic partnerships constitute the primary competitive vectors as emissions compliance timelines compress fleet renewal decisions.
Within the OEM tier, Airbus SE and The Boeing Company exemplify divergent platform strategies—Airbus through A350F fuel efficiency positioning, Boeing through 777-8F scale and established 767 conversion ecosystems. Among operator-archetype players, Atlas Air Worldwide Holdings, Inc. occupies the ACMI and charter capacity provider position, while FedEx Express anchors the integrated express carrier model with captive fleet scale.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| Textron Inc. |
| ATR |
| Singapore Technologies Engineering Ltd. |
| Embraer S.A. |
| Lockheed Martin Corporation |
| Atlas Air Worldwide Holdings, Inc. |
| FedEx Express (FedEx Corporation) |
| Others |
Value Chain & Pricing Dynamics
ICAO Annex 16 Vol. III emissions certification gates qualified supply for factory-built dedicated freighters and anchors premium-tier pricing access for operators serving transoceanic routes from Atlanta and Memphis. The EPA's alignment with international aviation standards compresses conversion economics while rewarding early-movers securing emissions-compliant turbofan platforms.
Pricing Analysis
Capacity additions in the southeastern United States are reshaping price floors for converted freighter feedstock as Boeing 767 and A330 passenger retirements deplete. Contract-based long-term offtake agreements dominate procurement among FedEx Express and Amazon Air, with price differentiation driven by emissions certification tier and guaranteed volume scale. Cost compression in the conversion segment intensifies because 14 CFR Part 25 supplemental type certificate timelines extend, while cargo airlines exhibit highest price sensitivity against integrated express carriers with captive fleet economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for factory-built A350F and 777-8F platforms from Airbus SE and Boeing. Geographic supply concentrates in the United States, France, and Canada, with final assembly drawing from titanium forgings, composite fuselage sections, and high-bypass turbofan powerplants. Single-source vulnerability in engine supply from Pratt & Whitney and General Electric exposes operators to delivery bottlenecks. Distribution runs through manufacturer-direct sales for dedicated freighters and conversion specialist networks for passenger-to-freighter modifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The America Freighter Aircraft Market reads as a late-cycle quality story where e-commerce parcel volume concentration forces procurement toward emissions-certified factory-built platforms with guaranteed utilization economics.
For Market Incumbents: Deploy conversion certification capacity as a defensive moat against feedstock scarcity. Atlas Air and Kalitta Air should anchor ACMI pricing power through long-term block space agreements with freight forwarders, while securing early delivery positions for 777-8F platforms to outrun ICAO Annex 16 Vol. III compliance deadlines. Backward integration into maintenance, repair, and overhaul clusters at Memphis and Louisville locks in technician labor pools. For New Entrants and Emerging Players: Sustainable aviation fuel logistics platforms offer a technology-first wedge into the ground services layer without airframe capital intensity. Latin American cargo corridors from Miami to São Paulo and Bogotá present the most penetrable whitespace for scheduled freighter services. A go-to-market angle centered on SAF offtake aggregation at southeastern United States hubs bypasses OEM delivery queue disadvantages. For Investors and Strategic Acquirers: Roll-up economics work for regional conversion specialists because 14 CFR Part 25 certification expertise concentrates in Montreal-area engineering clusters with limited replication. The five-to-ten year viability window favors platforms with established FAA supplemental type certificate portfolios over greenfield entrants. Watch for inflection in feedstock availability as major US carriers accelerate widebody passenger retirements.| Strategic Initiative | Industry Significance |
|---|---|
| Factory-Built Freighter Acquisition | Airbus A350F and Boeing 777-8F deliveries secure ICAO Annex 16 Vol. III compliance for transoceanic operators. |
| Passenger-to-Freighter Conversion Expansion | Montreal-area specialists exploit Boeing 767 and A330 retirements to serve regional cargo operators. |
| Sustainable Aviation Fuel Infrastructure Partnership | Memphis and Cincinnati super-hubs blend SAF to compress emissions profiles for captive e-commerce fleets. |
| Maintenance Technician Certification Investment | FAA airframe and powerplant programs concentrate qualified labor at southeastern United States MRO clusters. |
| Latin American Network Development | Miami-São Paulo cargo corridors capture underpenetrated e-commerce import flows with turboprop feeder connectivity. |
Study Parameters
Direct dialogue with fleet planning executives at integrated express carriers, conversion program managers at Montreal-area engineering firms, procurement leads at ACMI operators, and FAA certification specialists grounded qualitative findings. Secondary validation drew from FAA 14 CFR Part 25 filings, EPA aviation emissions guidelines, ICAO Annex 16 Vol. III documentation, and manufacturer delivery disclosures. Bottom-up and top-down triangulation cross-checked airframe deployment data against e-commerce volume flows through Memphis, Louisville, and Cincinnati super-hubs.
Bottom-up modeling segmented the market across dedicated freighter, converted freighter, cargo aircraft, and multi-role platforms, with propulsion technology and service type as cross-cutting dimensions. Top-down validation anchored aggregate fleet value against manufacturer order backlogs and conversion pipeline estimates. CAGRs were derived from deployment velocity assumptions tied to emissions compliance deadlines and hub-and-spoke network expansion across the analysis window. Forecast inputs incorporated feedstock availability curves for Boeing 767 and A330 passenger retirements, plus turbofan engine delivery schedules from Pratt & Whitney and General Electric.
The model holds under steady ICAO Annex 16 Vol. III enforcement timelines and sustained e-commerce parcel growth; deviation in feedstock retirement acceleration or SAF infrastructure deployment would shift fleet composition toward converted platforms. Forecasts reflect documented assumptions on regulatory stringency and buyer concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Latin America Business Jet Market
Aircraft
Light and Very Light Jets Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Aircraft Seals Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Aircraft Wheels Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
Military Fixed-Wing Aircraft Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Asia-Pacific Commercial Aircraft Market